
 Asia-Pacific Feed Amino Acids Market | 2026-2036
Asia-Pacific Feed Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Amino Acids Market Outlook
Chinese amino acid producers is broadening fermentation capacity to serve regional livestock demand. Adisseo leverages integrated methionine complexes across coastal China to anchor supply security for poultry integrators. CJ CheilJedang sustains lysine fermentation scale through backward integration into corn processing and captive enzyme technology. Evonik Industries AG differentiates via DL-methionine purity grades tailored to high-performance aquaculture diets across Vietnam and Indonesia.
Feed amino acids are crystalline or liquid organic compounds synthesized through microbial fermentation or chemical synthesis, typically specified at minimum purity thresholds of 98.5% for lysine and 99% for methionine, and are incorporated into compound feed to optimize protein utilization and reduce nitrogen excretion in monogastric animals. Lysine dominates volume consumption across poultry and swine rations where corn-soybean meal baselines create chronic deficiency, while methionine commands premium positioning in aquaculture formulations requiring sulfur-bearing amino acids for shrimp and finfish growth performance. Feed grade specifications absorb the vast majority of regional output, though pharmaceutical grade isolates attract margin concentration from veterinary therapeutic applications in Japan and South Korea.
China's SAMR enforces GB standard compliance for amino acid content claims and contaminant limits, while Japan's MAFF mandates residue testing protocols that elevate quality thresholds for imported feed additives. India's FSSAI and BIS coordinate feed-grade certification requirements that shape market access for foreign suppliers entering dairy and broiler supply chains. Stakeholders must monitor evolving MEE environmental enforcement on fermentation wastewater discharge, as tightening effluent rules in Shandong and Jiangsu provinces could reshape cost structures for domestic manufacturers and redirect procurement decisions toward suppliers with certified green production systems.
Market Dynamics
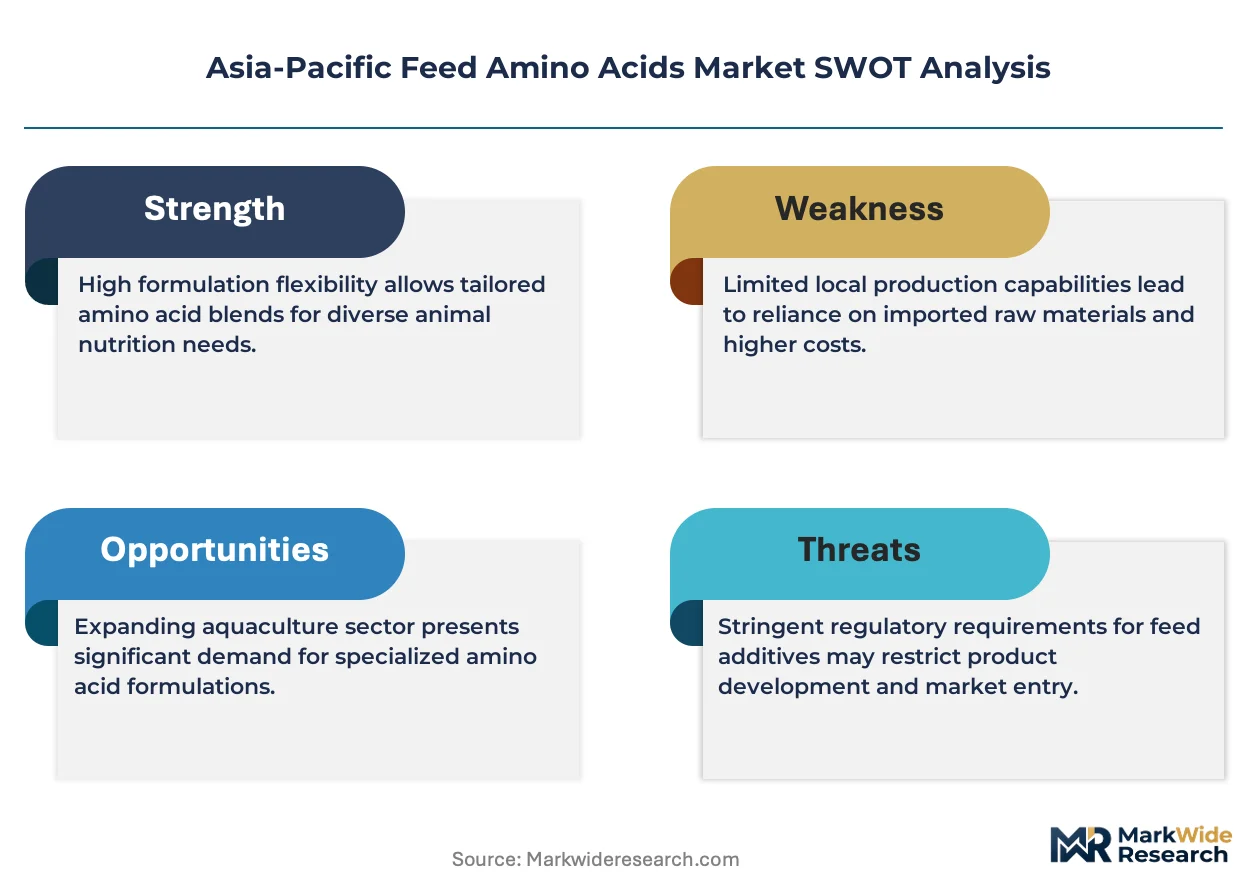
Fermentation wastewater discharge rules from China's MEE are forcing capital reallocation toward closed-loop production systems across Shandong and Jiangsu provinces, compressing margins for conventional amino acid manufacturers while advantaging certified green producers.
Growth Catalysts
- GB Standard Tightening:China's SAMR revised feed additive quality thresholds under updated GB regulations, mandating stricter amino acid purity verification and contaminant limits that elevate technical barriers for low-grade imports.
- Poultry Integration:Southeast Asian broiler integrators are expanding lysine and methionine inclusion rates in compound feed formulations to optimize feed conversion ratios and reduce nitrogen excretion compliance costs.
- Coastal Manufacturing Clustering:Amino acid production capacity concentrates in eastern Chinese provinces where integrated livestock operations sit adjacent to fermentation hubs, minimizing logistics friction for just-in-time feed delivery.
Market Restraints
- Corn Price Volatility:Lysine fermentation depends on corn-derived dextrose feedstock, and price swings in Chinese grain markets transmit directly to amino acid cost structures without short-term hedging mechanisms.
- Effluent Compliance Burden:MEE enforcement on fermentation wastewater discharge in Shandong and Jiangsu provinces requires membrane bioreactor and zero-liquid-discharge investments that add 15-25% to baseline capex for capacity expansion.
- Synthetic Methionine Competition:Chemical synthesis routes for DL-methionine from petrochemical precursors compete with fermentation-based alternatives on cost, particularly when crude oil benchmarks trend below agricultural commodity indices.
Strategic Opportunities
- Vietnam Aquaculture Expansion:Shrimp and finfish producers across the Mekong Delta are adopting sulfur-bearing amino acid formulations for growth performance optimization, creating demand pull for methionine grades tailored to high-protein aquafeed.
- Enzyme-Coupled Fermentation:Captive enzyme technology for corn processing is integrating with lysine fermentation trains, enabling producers to capture margin from dextrose through amino acid output in single-site operations.
- India Dairy Feed Formalization:FSSAI and BIS coordination on feed-grade certification is professionalizing compound feed procurement for dairy cooperatives in Gujarat and Punjab, opening structured demand channels for imported amino acid suppliers.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiology and bioprocess engineering talent pools concentrate in coastal Chinese universities, leaving interior provinces and emerging ASEAN manufacturing sites dependent on expatriate technical staffing.
- Multi-Jurisdiction Certification Timelines:Japan's MAFF residue testing protocols, China's SAMR GB compliance, and India's BIS feed-grade requirements create overlapping approval cycles that extend market entry timelines by 18-24 months for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Amino Acids Market |
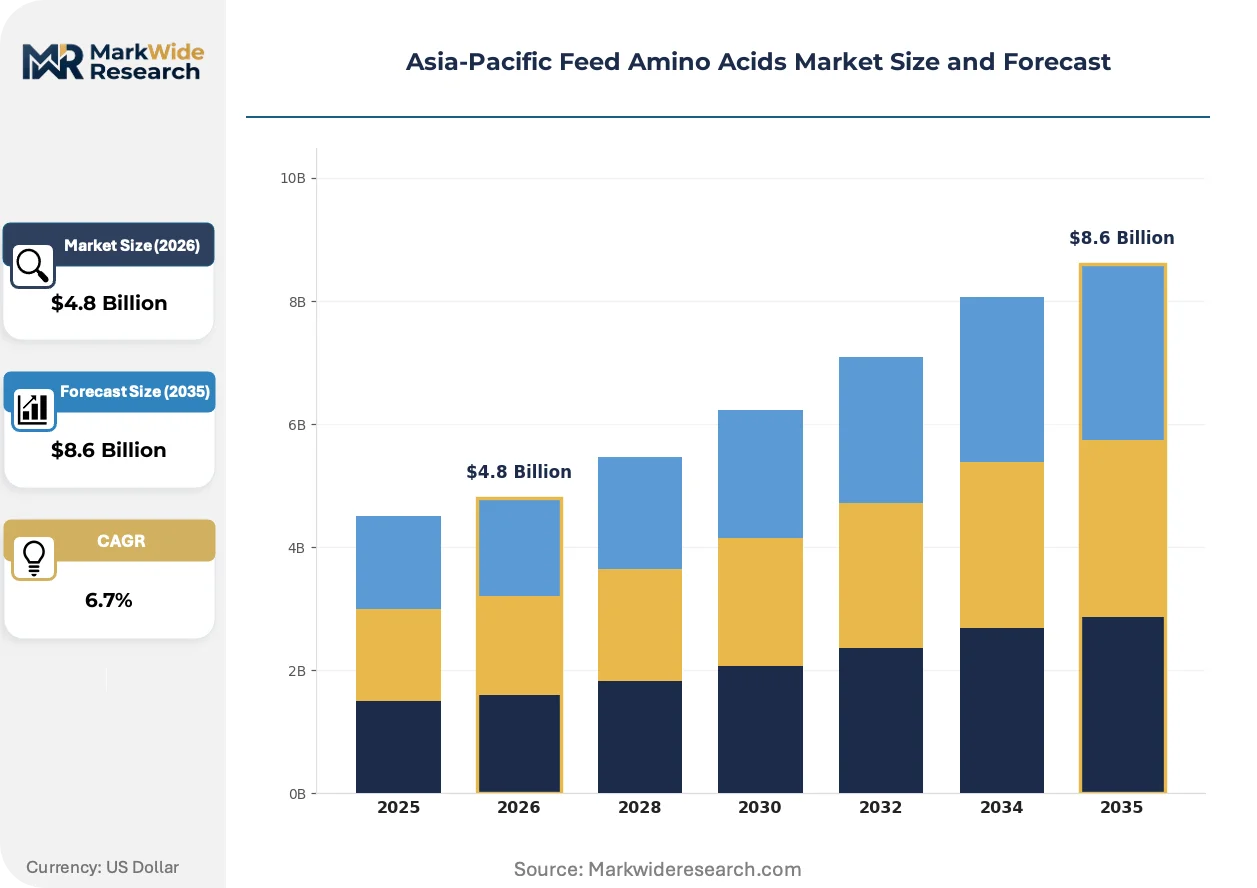
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lysine, Methionine, Threonine, Tryptophan End User: Poultry, Swine, Ruminants, Aquaculture Grade: Feed Grade, Food Grade, Pharmaceutical Grade, Industrial Grade Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Adisseo, Ajinomoto Co., Inc., Evonik Industries AG, SHV (Nutreco NV), Archer Daniels Midland Co., CJ CheilJedang, Royal DSM N.V., Cargill Inc., Novus International Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Amino Acids Market Strategic Shifts
Bioprocess intensification and regulatory harmonization pressures are converging to reshape amino acid manufacturing economics, with technology adoption rates diverging sharply between coastal Chinese incumbents and emerging ASEAN producers.
Continuous fermentation technology with real-time metabolite monitoring is integrating into lysine production trains across Shandong province. Large-scale poultry integrators in Guangdong and Fujian are specifying amino acid suppliers with validated continuous processing capabilities to secure batch-to-batch consistency. This technology compression is displacing conventional fed-batch fermentation for new capacity additions while locking in multi-year supply agreements.
China's MEE is tightening effluent discharge coefficients for fermentation wastewater under revised environmental enforcement calendars. Manufacturers in Jiangsu province face mandatory zero-liquid-disclosure upgrades or production curtailments during inspection windows. Aquafeed specialists across Vietnam and Indonesia are redirecting procurement toward suppliers with certified green production systems to preempt supply interruption risks.
Integrated livestock operators in eastern China are consolidating compound feed procurement through captive amino acid offtake agreements directly with fermentation complexes. Traditional distributor networks serving small-scale swine farmers in Henan and Sichuan provinces are losing volume to direct mill-to-farm arrangements. This channel compression is most visible in Shandong province where three poultry integrators account for majority lysine consumption within 200-kilometer radius of manufacturing hubs.
Asia-Pacific Feed Amino Acids Market Segmentation
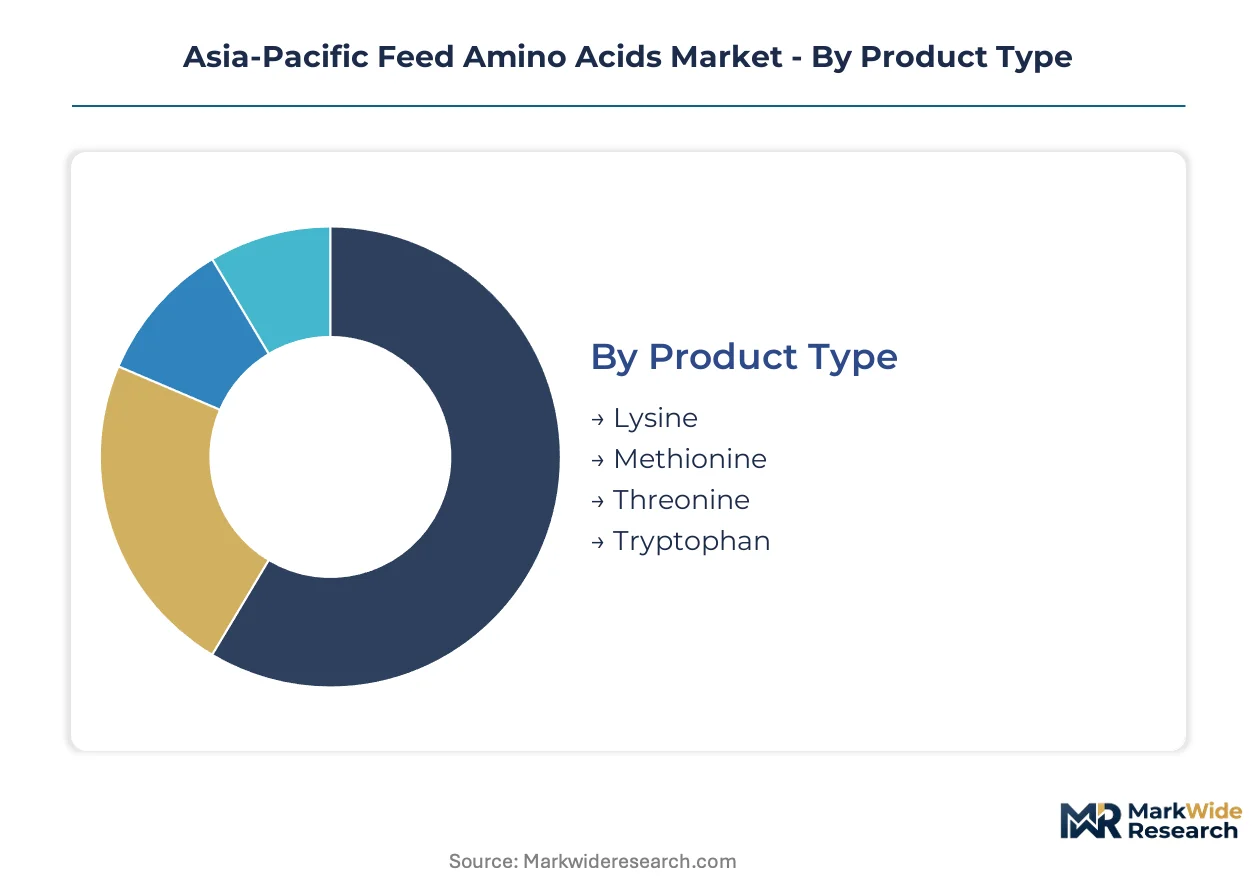
Feed amino acid procurement patterns diverge sharply across product chemistry, livestock species, and certification tiers. Understanding these fault lines reveals where margin concentrates and which supply channels are compressing.
Product Type:
Lysine and methionine anchor the volume core as standalone additives, while threonine and tryptophan embed more deeply into premix formulations.
- Lysine:Crystalline L-lysine monohydrochloride specified at 98.5% minimum purity dominates poultry and swine rations across eastern Chinese provinces. Corn-soybean meal baselines create chronic deficiency that compound feed mills address through bulk lysine inclusion. Demand concentrates in Shandong and Guangdong where integrated poultry operations cluster near fermentation hubs.
- Methionine:DL-methionine at 99% purity serves sulfur-bearing requirements in aquaculture diets across Vietnam and Indonesia, commanding premium positioning over fermentation alternatives when crude oil benchmarks favor chemical synthesis economics. Coastal Chinese manufacturers leverage integrated complexes to anchor supply security for Mekong Delta shrimp producers.
- Threonine:Second-limiting amino acid in swine formulations, typically bundled into lysine-threonine premixes for Southeast Asian broiler integrators optimizing feed conversion ratios.
- Tryptophan:Lowest-volume essential amino acid, specified for high-performance breeding stock diets in Japan and South Korea where veterinary therapeutic applications absorb pharmaceutical-grade isolates.
Lysine leads volumes today; methionine is gaining share fastest.
End User:
Poultry and swine operations drive bulk consumption, while aquaculture and ruminant segments fragment across formulation sophistication tiers.
- Poultry:Broiler integrators across Southeast Asia specify elevated lysine and methionine inclusion rates to optimize feed conversion ratios and preempt nitrogen excretion compliance costs. Guangdong and Fujian operations consolidate procurement through direct fermentation complex offtake agreements.
- Swine:Corn-soybean meal baselines in Henan and Sichuan provinces sustain chronic lysine deficiency, though channel compression favors direct mill-to-farm arrangements over traditional distributor networks serving small-scale farmers.
- Ruminants:Dairy cooperatives in Gujarat and Punjab represent emerging formalized demand as FSSAI and BIS coordination professionalizes compound feed procurement.
- Aquaculture:Shrimp and finfish producers across Vietnam's Mekong Delta adopt sulfur-bearing amino acid formulations for growth performance optimization, redirecting procurement toward certified green production systems to preempt MEE enforcement disruption risks.
Poultry anchors consumption today; aquaculture is expanding most quickly.
Grade:
Feed grade absorbs regional output volume, while pharmaceutical and food grades concentrate margin in specialized applications.
- Feed Grade:Minimum 98.5% purity specifications for lysine and 99% for methionine serve compound feed mills across China, Vietnam, and Indonesia. GB standard tightening under SAMR revisions elevates technical barriers for low-grade imports.
- Food Grade:Nutritional fortification applications in processed food manufacturing, particularly in Japan and South Korea where MAFF residue testing protocols shape quality thresholds.
- Pharmaceutical Grade:Veterinary therapeutic applications in Japan and South Korea attract margin concentration through isolates meeting JIS and PMDA standards for injectable and oral formulations.
- Industrial Grade:Lowest purity tier serving non-nutritional applications including cosmetic and chemical synthesis feedstock, primarily sourced from conventional fermentation without zero-liquid-disclosure certification.
Feed grade leads volumes today; pharmaceutical grade commands the steepest expansion trajectory.
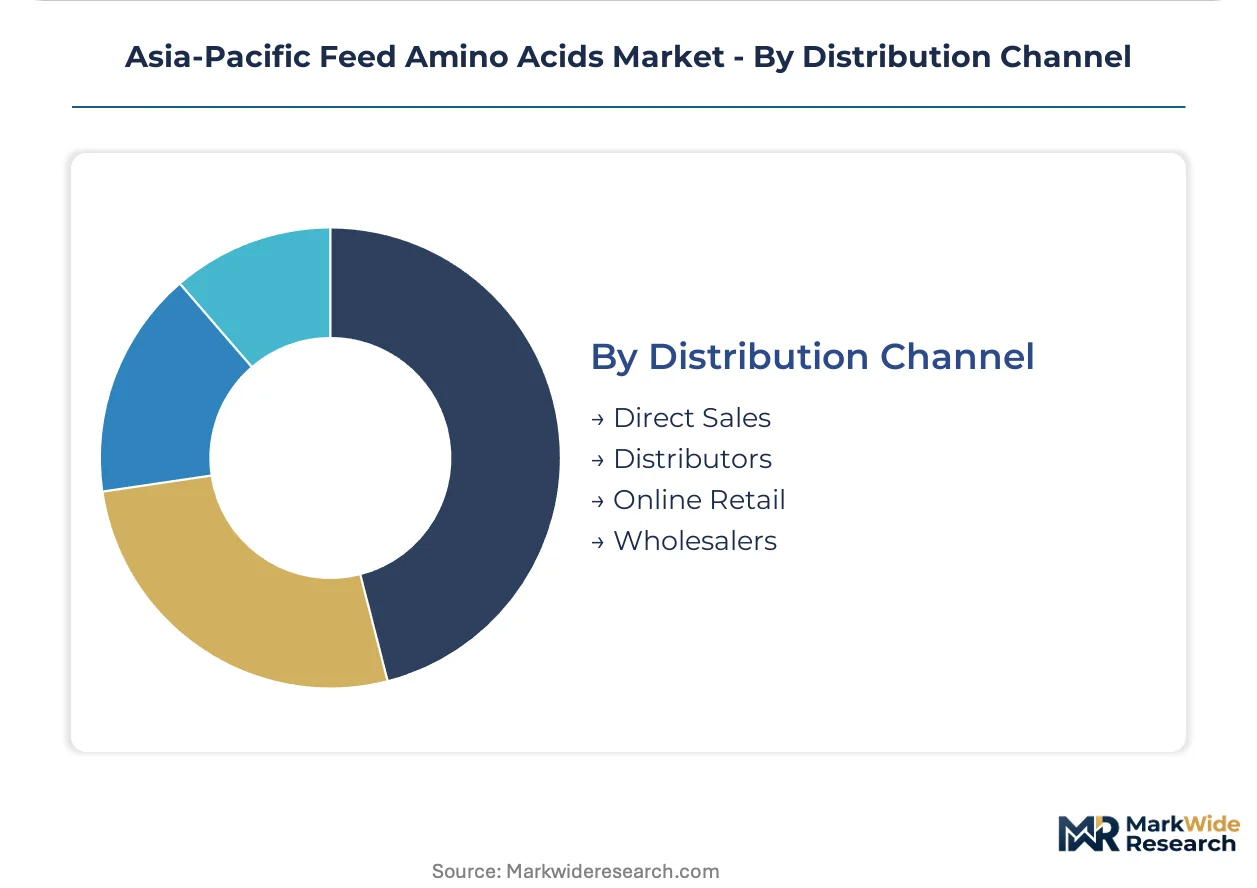
Distribution Channel:
Direct sales compress traditional intermediaries in coastal manufacturing clusters, while interior provinces and emerging ASEAN markets retain distributor dependency.
- Direct Sales:Captive offtake agreements between fermentation complexes and integrated livestock operators in Shandong province displace traditional distributor networks. Three poultry integrators account for majority lysine consumption within 200-kilometer radius of manufacturing hubs.
- Distributors:Traditional networks persist for small-scale swine farmers in Henan and Sichuan provinces, though volume erosion accelerates as direct mill-to-farm arrangements expand.
- Online Retail:Emerging channel for specialty amino acid premixes serving niche aquaculture operations and independent compound feed mills seeking spot procurement flexibility.
- Wholesalers:Bulk aggregation function for interior Chinese provinces and emerging ASEAN manufacturing sites lacking immediate fermentation hub proximity.
Direct sales lead volumes today; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting amino acid fermentation capacity toward jurisdictions with lower wastewater compliance costs, even as end-use demand concentrates in coastal Chinese provinces where poultry integrators cluster near manufacturing hubs.
China
Shandong and Jiangsu provinces host the dominant fermentation complexes, with three poultry integrators absorbing majority lysine consumption within 200-kilometer radius of manufacturing hubs. SAMR's revised GB standards mandate stricter amino acid purity verification and contaminant limits that elevate technical barriers for low-grade imports. MEE enforcement on fermentation wastewater discharge is forcing membrane bioreactor investments that add 15-25% to baseline capex.
Vietnam
Shrimp and finfish producers across the Mekong Delta are adopting sulfur-bearing amino acid formulations for growth performance optimization, creating demand pull for methionine grades tailored to high-protein aquafeed. The country's national agricultural regulator coordinates feed-grade certification requirements that shape market access for foreign suppliers entering aquaculture supply chains. Aquafeed specialists are redirecting procurement toward suppliers with certified green production systems to preempt supply interruption risks.
Japan
Pharmaceutical-grade amino acid isolates attract margin concentration from veterinary therapeutic applications, with MAFF residue testing protocols elevating quality thresholds for imported feed additives. The country's national pharmaceutical regulator enforces standards that extend market entry timelines for new suppliers. Kanto region concentrates demand for high-performance breeding stock diets where tryptophan specifications exceed standard feed-grade baselines.
India
FSSAI and BIS coordination on feed-grade certification is professionalizing compound feed procurement for dairy cooperatives in Gujarat and Punjab, opening structured demand channels for imported amino acid suppliers. Corn-soybean meal baselines in dairy rations sustain chronic lysine deficiency that compound feed mills address through bulk inclusion. Channel compression favors direct mill-to-farm arrangements over traditional distributor networks serving small-scale farmers.
Indonesia
Aquaculture operations across Java and Sumatra are expanding methionine inclusion rates in compound feed formulations to optimize feed conversion ratios. The country's national standards body coordinates feed additive quality requirements that shape import procurement decisions. Coastal manufacturing sites lacking immediate fermentation hub proximity rely on bulk aggregation through wholesaler networks serving interior provinces.
Asia-Pacific Feed Amino Acids Market Competitive Environment
Chinese producers anchor one tier through integrated fermentation complexes; European and Japanese specialists hold differentiated positioning through purity-grade segmentation and aquaculture-tailored formulations. Market structure tilts toward consolidation among coastal Chinese incumbents with captive corn processing and enzyme technology, while foreign entrants face 18-24 month certification timelines across multiple jurisdictions. Three archetypes dominate: state-linked fermentation giants with backward integration into grain processing, multinational chemical conglomerates with DL-methionine synthesis capabilities, and regional premix specialists with distribution depth in ASEAN markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with green production certification emerging as a procurement gatekeeper.
Within the multinational chemical conglomerate tier, Evonik Industries AG and Adisseo occupy positions differentiated by methionine purity grades and coastal China supply security. CJ CheilJedang exemplifies the state-linked fermentation archetype through lysine scale sustained by captive corn processing. Among diversified agricultural conglomerates, Archer Daniels Midland Co. and Cargill Inc. represent integrated players with compound feed manufacturing that internalizes amino acid demand. Ajinomoto Co., Inc. anchors the Japanese specialist position through amino acid fermentation heritage and pharmaceutical-grade isolate capabilities.
| Leading Market Players |
|---|
| Adisseo |
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| SHV (Nutreco NV) |
| Archer Daniels Midland Co. |
| CJ CheilJedang |
| Royal DSM N.V. |
| Cargill Inc. |
| Novus International Inc. |
| Others |
Value Chain & Pricing Dynamics
Integrated poultry integrators in Guangdong and Fujian provinces are mandating certified green production systems in supplier qualification protocols, forcing amino acid manufacturers to absorb membrane bioreactor investments that compress margins while elevating technical barriers for uncertified competitors.
Pricing Analysis
Distributor margins in interior Chinese provinces face sustained compression as direct mill-to-farm arrangements displace traditional intermediaries in coastal manufacturing clusters. Pricing stratifies across pharmaceutical-grade isolates, feed-grade baselines, and industrial-grade tiers, with purity verification under SAMR GB standards serving as the primary price differentiation driver. Cost compression in conventional fermentation runs through MEE wastewater compliance investments, while small-scale swine farmers in Henan province exhibit highest price sensitivity and aquafeed specialists in Vietnam show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Mekong Delta shrimp producers are diversifying procurement portfolios beyond single-province dependencies in Shandong. Supply concentrates in China, Vietnam, and Indonesia, with corn-derived dextrose, petrochemical precursors, and captive enzyme technology anchoring raw material dependencies. Single-source vulnerability runs through fermentation hub concentration in eastern Chinese provinces, while distribution runs through direct offtake agreements for integrated operators and wholesaler networks for interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific feed amino acids market reads as a late-cycle quality story, with pharmaceutical-grade specifications and zero-liquid-discharge certification emerging as non-negotiable procurement filters across Japanese and South Korean demand channels.
For Market Incumbents: Cement supply security through captive corn processing integration in Shandong province and accelerate zero-liquid-discharge certification to preempt MEE enforcement disruption. Synthetic methionine competition from petrochemical routes threatens fermentation-based margins; defend through aquaculture-tailored formulation partnerships in Vietnam. For New Entrants and Emerging Players: Continuous fermentation technology with real-time metabolite monitoring offers a technology-first wedge into lysine supply contracts with Guangdong poultry integrators. Target India's Gujarat dairy cooperatives as the most penetrable geography, leveraging FSSAI-BIS coordination gaps with direct mill-to-farm certification support. For Investors and Strategic Acquirers: Asymmetric upside sits with regional premix specialists possessing ASEAN distribution depth and green production certification. Long-term viability hinges on backward integration into grain processing and enzyme technology capture. Watch MEE enforcement calendars in Jiangsu province as the inflection indicator for capacity rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | CJ CheilJedang's captive dextrose supply secures lysine fermentation margin against Chinese grain volatility. |
| Green Manufacturing Transition | Zero-liquid-discharge certification opens procurement channels with Vietnam aquafeed specialists facing MEE disruption risks. |
| Long-term Supply Agreement | Direct offtake contracts between Shandong fermentation hubs and Guangdong poultry integrators lock in volume commitments. |
| Joint Venture | Coastal manufacturing clustering in Jiangsu minimizes logistics friction for just-in-time feed delivery to integrated livestock operations. |
| Capacity Expansion | Membrane bioreactor investments respond to SAMR GB standard tightening while filtering low-grade import competition. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, poultry integrator procurement leads, aquafeed formulation specialists, and distribution channel partners with secondary validation from customs trade data, SAMR regulatory filings, MEE environmental enforcement calendars, and SEC disclosures from listed chemical conglomerates. Bottom-up amino acid consumption estimates triangulated against top-down compound feed production benchmarks.
Segment-weighting approaches distributed volume and value projections across product chemistry tiers, livestock species end-uses, certification grade specifications, and distribution channel structures throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and buyer consolidation patterns, with corn price volatility indices and crude oil benchmark differentials serving as key forecast sensitivity inputs.
The model holds under steady MEE enforcement progression and SAMR GB standard adherence; deviation in wastewater discharge rule acceleration or pharmaceutical-grade purity threshold elevation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
Peat Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Europe Ruminant Feed Market
Agricultural Commodities
Marine Powder Market