
 Black Pellet Market | 2026-2036
Black Pellet Market Size, Share, and Industry Trends Forecast 2026-2036
Black Pellet Market Analysis
Finland's expanding torrefaction corridor is narrowing the cost gap between black pellets and conventional white pellets for baseload power contracts. Zilkha Biomass Energy leverages its Gulf Coast logistics network to supply European utilities under long-term offtake agreements. Blackwood Technology B.V. anchors its position through proprietary flash torrefaction reactor designs that cut residence time below thirty minutes. Arbaflame AS specializes in steam explosion pellet formulations that achieve grindability metrics matching Powder River Basin coal specifications.
Black pellets are thermally treated biomass briquettes produced through torrefaction or steam explosion processes at temperatures between 200 and 300 degrees Celsius, yielding a hydrophobic solid fuel with energy densities approaching 20 gigajoules per tonne and coal-like handling characteristics for direct co-firing or full substitution in pulverized fuel boilers. The power generation application dominates current offtake volumes as utilities pursue coal-to-biomass conversions without capital-intensive boiler rebuilds. Wood-derived feedstock occupies the premium tier due to consistent calorific value and low ash content, while agricultural residue variants compete on delivered cost in markets with relaxed particulate emission thresholds.
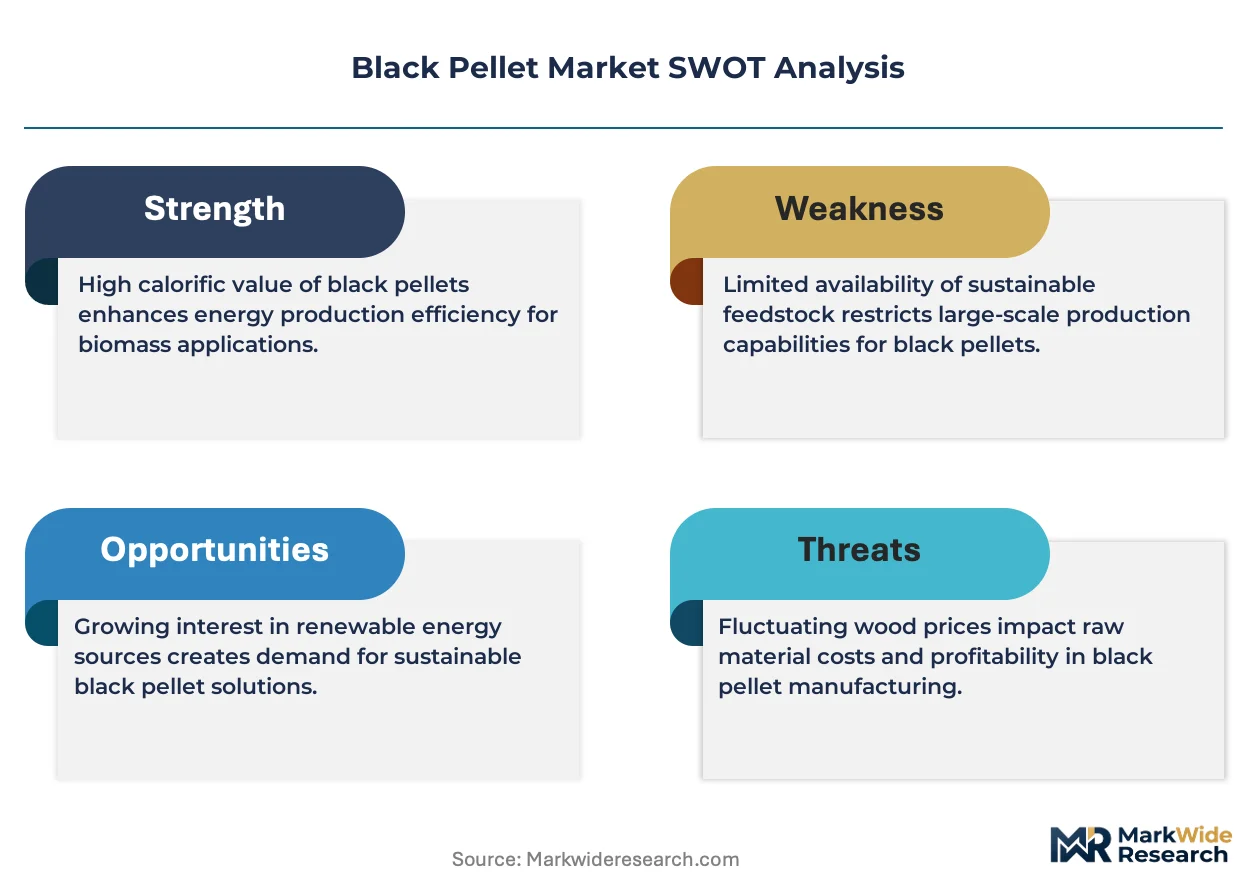
The EU Green Deal's revised Renewable Energy Directive tightens sustainability criteria for biomass feedstock sourcing, compelling suppliers to demonstrate chain-of-custody compliance through recognized certification schemes. Japan's METI enforces fixed-price purchase obligations under its feed-in tariff mechanism, creating predictable revenue streams for certified black pellet exporters. The US EPA maintains overlapping authority under the Renewable Fuel Standard and Clean Air Act provisions that affect co-firing project permitting timelines. Stakeholders must monitor feedstock cost volatility against carbon credit pricing mechanics to determine optimal capacity allocation across torrefaction and steam explosion technology pathways.
Market Dynamics
Coal-to-biomass retrofit economics is the dominant structural force reshaping black pellet demand, as utilities seek carbon reductions without boiler replacement costs. This pressure concentrates procurement decisions on grindability equivalence and hydrophobic durability rather than energy density alone.
Growth Catalysts
- Japan's Feed-in Tariff:METI's fixed-price purchase obligations create decade-long revenue visibility for certified exporters, channeling capital toward torrefaction capacity expansion.
- EU Green Deal Sustainability Criteria:The revised Renewable Energy Directive tightens chain-of-custody requirements, advantaging suppliers with established certification infrastructure over commodity traders.
- Steam Explosion Technology:Advanced pellet formulations achieve Powder River Basin coal grindability metrics, enabling direct co-firing without pulverizer modifications at German and Dutch power stations.
Market Restraints
- Wood Feedstock Cost Volatility:Sawmill residue and forest thinning supply fluctuations in the Baltic states and southeastern US directly compress torrefaction margins during housing construction downturns.
- Agricultural Residue Quality Variability:Straw and husks from South Asian suppliers exhibit inconsistent ash fusion temperatures, limiting substitution rates in high-efficiency pulverized fuel boilers.
- REACH Registration Burden:ECHA's substance registration requirements for torrefaction byproducts impose fixed compliance costs that disproportionately burden sub-scale producers.
Strategic Opportunities
- South Korean Industrial Heating Clusters:District heating networks in Incheon and Ulsan seek baseload biomass alternatives to LNG, creating import demand for steam explosion pellets with guaranteed moisture resistance.
- Carbon Border Adjustment Mechanism:The EU's CBAM phase-in from 2026 raises effective carbon costs on coal imports, widening the economic window for black pellet substitution in power generation.
- Flash Torrefaction-Grinding Integration:Coupling Blackwood Technology's reactor designs with on-site pulverization equipment collapses logistics costs for captive utility supply chains.
Industry Challenges
- Torrefaction Process Control Expertise:Residence time optimization and temperature profiling require specialized chemical engineering talent scarce outside Nordic biomass research institutes.
- ENplus Certification Timelines:The 6-12 month audit cycle for premium pellet certification delays market entry for new torrefaction entrants seeking utility offtake contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Pellet Market |
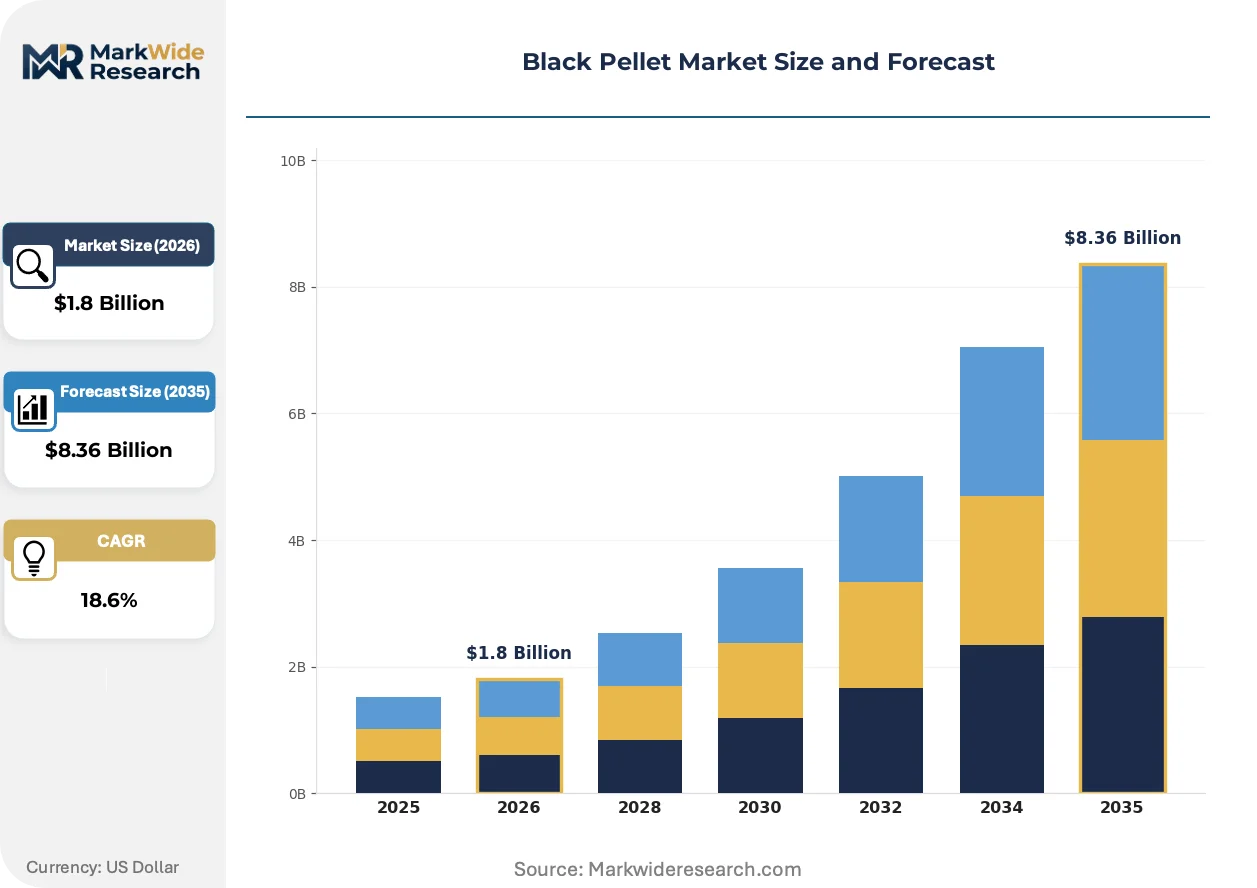
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Biomass, Agricultural Residue, Sawdust Application: Power Generation, Residential Heating, Industrial Heating, Biogas Production End User: Utilities, Industrial Sector, Commercial Buildings, Households Packaging Type: Bags, Bulk Bags, Loose, Pallets |
| Companies Covered | Zilkha Biomass Energy, Blackwood Technology B.V., Airex Energy Inc., NT Biomass Products Co., Ltd., Bioendev AB, Arbaflame AS, New Biomass Energy, Talwandi Sabo Power Limited, Idemitsu Kosan Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Pellet Market Emerging Trajectories
Torrefaction process intensification and digital quality assurance systems are compressing capital recovery timelines while expanding addressable boiler retrofits beyond premium European utilities.
Flash torrefaction reactor designs are virtualizing traditional batch processing economics by cutting residence times below thirty minutes while maintaining hydrophobicity targets. European utilities with baseload power contracts are piloting these systems at 100,000-tonne annual scales. The technology is virtualizing the cost structure that previously confined black pellets to premium coal substitution applications.
REACH substance registration requirements for torrefaction condensates are forcing capital allocation toward closed-loop emission control systems. Industrial consequence includes 15-20% capex inflation for new entrant producers relative to grandfathered facilities. German and Dutch power utilities are responding by consolidating procurement through vertically integrated suppliers with established ECHA compliance histories.
Buyer preference is migrating from spot-market pellet purchasing toward ten-year indexed supply agreements with guaranteed grindability specifications. This behavior shift compresses trading margins for commodity brokers while rewarding producers with captive feedstock and certified quality systems. The pattern is most visible in Japan's biomass-fired generation sector, where METI's tariff structure rewards long-term contract security over price optimization.
Black Pellet Market Segmentation
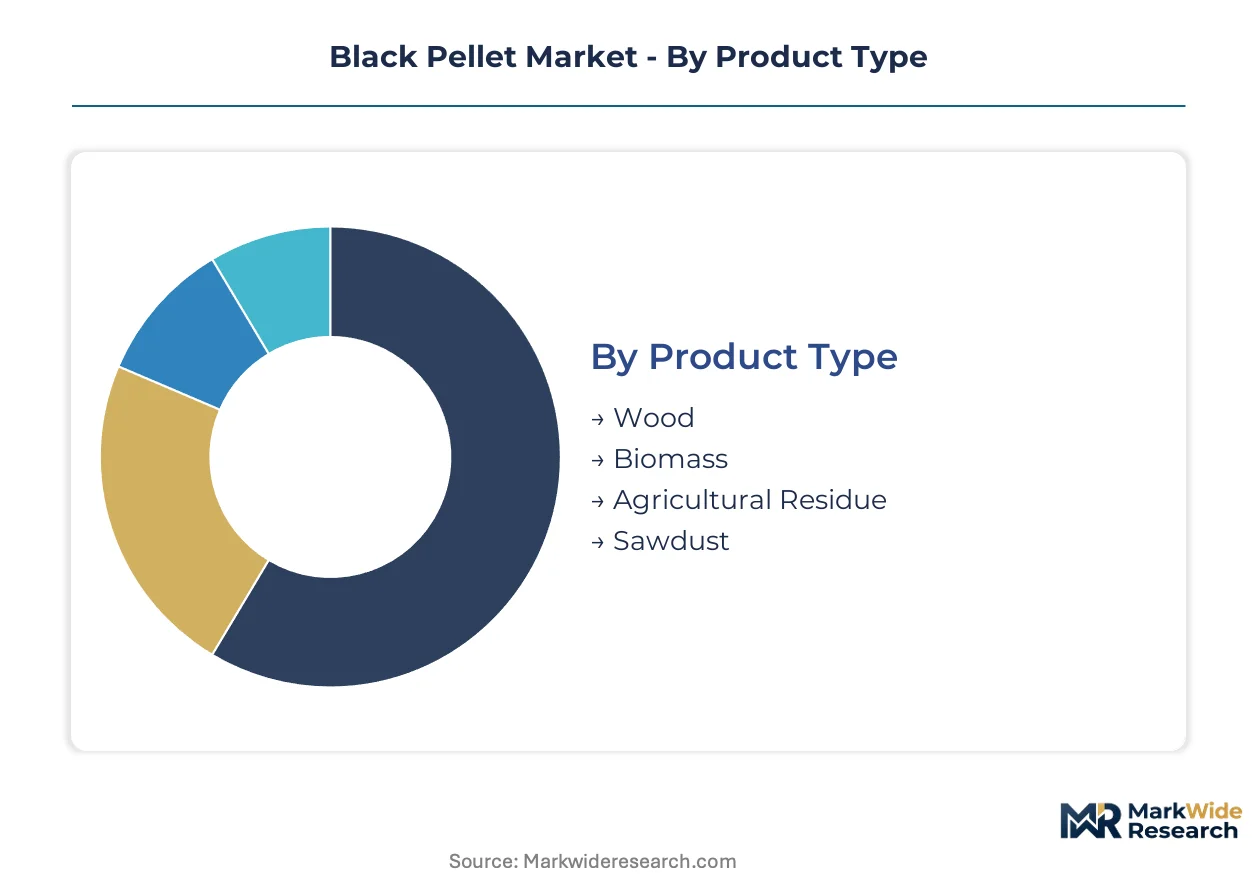
Black pellet procurement patterns diverge sharply across feedstock origins, thermal applications, and delivery formats. Each segmentation axis carries distinct margin profiles, certification requirements, and logistics constraints that reshape supplier competitive positioning.
Product Type:
Feedstock selection dictates torrefaction reactor configuration, ash handling systems, and final grindability specifications for coal substitution contracts.
- Wood:Forest thinning and sawmill residues deliver consistent calorific value near 20 gigajoules per tonne with sub-1% ash content. German and Dutch power utilities specify wood-derived black pellets for baseload pulverized fuel boilers under EU Green Deal sustainability criteria.
- Biomass:Dedicated energy crops and forestry residues enable larger-scale procurement volumes with documented chain-of-custody compliance. Japanese utilities under METI feed-in tariff obligations favor certified biomass pathways for decade-long offtake security.
- Agricultural Residue:Straw and husks compete on delivered cost in markets with relaxed particulate thresholds.
- Sawdust:Fine particle feedstock accelerates torrefaction kinetics but requires moisture pre-conditioning.
The dominant share belongs to Wood, while Agricultural Residue is closing the gap fastest.
Application:
End-use thermal requirements range from high-efficiency pulverized fuel combustion to small-scale residential stove compatibility.
- Power Generation:Coal-to-biomass retrofits at European utilities demand grindability metrics matching Powder River Basin coal specifications without pulverizer modifications. Steam explosion pellet formulations from Arbaflame AS and Blackwood Technology B.V. anchor this segment through direct co-firing compatibility.
- Industrial Heating:District heating networks in South Korean clusters at Incheon and Ulsan seek baseload alternatives to LNG with guaranteed moisture resistance below 5%.
- Residential Heating:Automated pellet stove systems require standardized ENplus certification for ash fusion temperature.
- Biogas Production:Torrefied material serves as structural feedstock in anaerobic digestion pre-treatment stages.
Power Generation commands the largest procurement volumes, though Industrial Heating is expanding most quickly.
End User:
Customer scale determines contract duration, pricing indexation, and quality assurance protocol intensity.
- Utilities:Vertically integrated power generators negotiate ten-year indexed supply agreements with guaranteed grindability specifications and ECHA REACH compliance documentation.
- Industrial Sector:Chemical process heat and cement kiln operators prioritize delivered cost per gigajoule over certification tier.
- Commercial Buildings:District heating subscribers and institutional campuses require seasonal delivery flexibility with bagged or bulk bag formats.
- Households:Individual consumers purchase through retail channels with spot pricing and ENplus A1 or A2 grade differentiation.
Utilities retain the dominant procurement position, while Industrial Sector buyers are gaining share fastest.
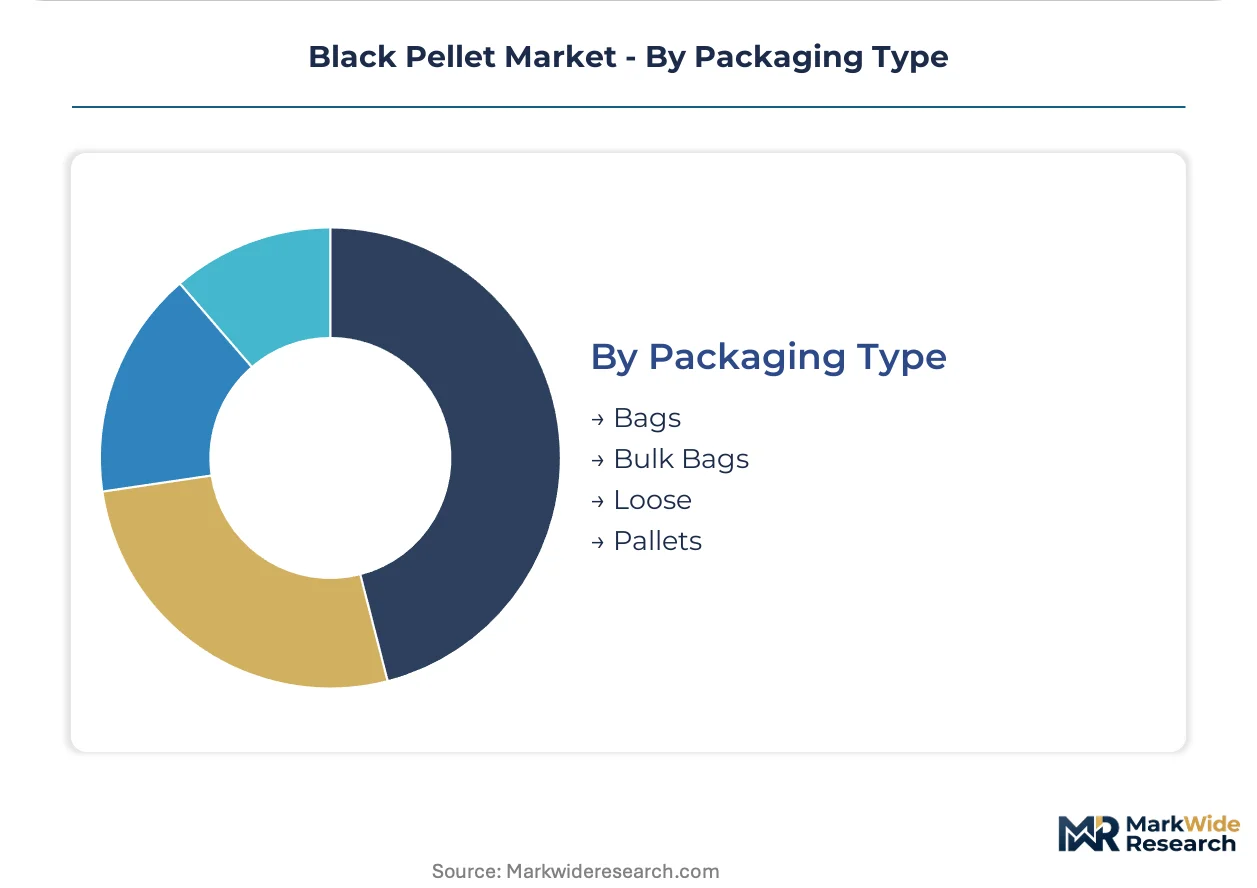
Packaging Type:
Logistics configuration directly ties to end-user handling infrastructure and inventory turnover economics.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate utility and industrial deliveries with mechanical unloading compatibility.
- Bags:15-20 kilogram retail units serve residential and small commercial heating installations through distributor networks.
- Loose:Unpackaged bulk delivery by pneumatic trailer minimizes packaging cost for captive utility supply chains with on-site storage silos.
- Pallets:Standardized unit loads facilitate warehouse handling for commercial building procurement with forklift infrastructure.
Bulk Bags hold the leading position, yet Loose format deliveries are climbing the fastest among new utility contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Black pellet supply chains concentrate in Nordic torrefaction corridors, North American forest residue belts, and East Asian import terminals. Procurement decisions in each geography track distinct regulatory incentives and feedstock availability patterns.
Germany
Coal phase-out mandates under the EU Green Deal drive utility procurement of steam explosion pellets for baseload power. ECHA REACH compliance documentation is mandatory for torrefaction condensate handling. Industrial clusters in the Rhineland and Lusatia regions host pilot co-firing installations at retrofitted lignite plants.
Japan
METI's feed-in tariff mechanism guarantees fixed-price purchase obligations for certified biomass imports over decade-long contract horizons. The country's national sustainability regulator enforces chain-of-custody verification for forestry-derived feedstock. Port infrastructure at Kobe and Nagoya channels torrefied pellet volumes toward utilities in the Kanto and Kansai load centers.
United States
Gulf Coast logistics networks position suppliers to serve European utility offtake agreements via bulk vessel export. EPA authority under the Renewable Fuel Standard and Clean Air Act provisions affects co-firing project permitting timelines. Southeastern forest residue belts in Georgia and Alabama anchor feedstock aggregation for torrefaction capacity.
South Korea
District heating networks in Incheon and Ulsan seek baseload biomass alternatives to LNG imports for industrial process heat. The country's national energy regulator enforces renewable portfolio standards that channel utility procurement toward certified black pellet supply. Port terminal investments at Busan support moisture-resistant pellet handling for power sector offtake.
Netherlands
Rotterdam's biomass import terminal infrastructure positions the country as a distribution hub for German and Belgian utility procurement. EU Green Deal sustainability criteria tighten chain-of-custody requirements for forestry feedstock sourcing. The Eindhoven-Helmond corridor hosts pilot flash torrefaction installations targeting grindability specifications for direct coal substitution.
Black Pellet Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base organizes around three functional layers: torrefaction technology licensors, captive feedstock producers, and utility-integrated offtake aggregators. Nordic engineering houses and North American logistics platforms anchor the first tier; Baltic forest residue processors and Southeast US sawmill operators populate the second. Competitive dynamics center on long-term supply agreement security and ECHA compliance infrastructure rather than unit cost optimization alone.
Among technology-anchored specialists, Blackwood Technology B.V., Arbaflame AS, and Zilkha Biomass Energy represent distinct archetypes within the competitive set. Blackwood Technology B.V. occupies a position tied to reactor engineering intellectual property. Arbaflame AS exemplifies formulation-focused specialists targeting grindability equivalence with Powder River Basin coal specifications. Zilkha Biomass Energy anchors the logistics-integrated tier through Gulf Coast export infrastructure. Each sits within a differentiated value capture mechanism: licensing revenue, premium product positioning, or throughput arbitrage respectively.
| Leading Market Players |
|---|
| Zilkha Biomass Energy |
| Blackwood Technology B.V. |
| Airex Energy Inc. |
| NT Biomass Products Co., Ltd. |
| Bioendev AB |
| Arbaflame AS |
| New Biomass Energy |
| Talwandi Sabo Power Limited |
| Idemitsu Kosan Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Nordic torrefaction corridors is compressing supplier margins while amplifying pricing power for integrated producers with captive feedstock positions. EU Green Deal sustainability criteria and Japan's METI feed-in tariff obligations are reshaping how utilities value long-term contract security against spot-market volatility.
Pricing Analysis
The EU's revised Renewable Energy Directive dictates the pricing tier structure across the black pellet market, separating certified wood-derived pellets from agricultural residue variants. Three-tier pricing stratifies across ENplus A1 premium grades, standard industrial certifications, and uncertified economy tiers for relaxed-emission markets. Cost compression in the economy tier is intensifying because Baltic sawmill residue supply fluctuates with housing construction cycles. Industrial sector buyers in South Korean district heating clusters exhibit the highest price sensitivity, while Japanese utilities under METI obligations prioritize decade-long supply security over unit cost optimization.
Supply Chain Analysis
Forest residue aggregation in Finland, Georgia, and Alabama anchors upstream feedstock availability for torrefaction capacity expansion. Sawmill residues, forest thinnings, and dedicated energy crops constitute the primary input categories, with moisture pre-conditioning requirements varying by particle size. Single-source vulnerability concentrates in Baltic state wood supply during regional housing downturns. Distribution runs through Rotterdam's biomass import terminals for European utility offtake, while Gulf Coast logistics networks serve trans-Atlantic export contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The black pellet market represents an early-cycle expansion story, with coal-to-biomass retrofit economics at European utilities driving penetration beyond pilot-scale installations.
For Market Incumbents: Insulate margin positions by deepening backward integration into southeastern US and Baltic forest residue aggregation networks. Prioritize ECHA REACH compliance infrastructure investments to capture procurement consolidation at German and Dutch utilities. Flash torrefaction reactor deployments at 100,000-tonne scales will defend against emerging commodity traders lacking certification audit histories. For New Entrants and Emerging Players: Agricultural residue torrefaction for South Korean industrial heating clusters represents the most penetrable entry point, given relaxed ash fusion temperature thresholds and LNG price volatility. Steam explosion technology licensing from established reactor engineering houses offers faster market entry than proprietary R&D cycles. Target district heating procurement officers in Incheon and Ulsan with guaranteed moisture resistance specifications below 5%. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated suppliers with decade-long Japanese offtake agreements and captive feedstock positions. Long-term viability hinges on carbon border adjustment mechanism phase-in timing and EU sustainability criteria enforcement intensity. Monitor ENplus certification backlog durations as an inflection indicator for new entrant supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Flash Torrefaction Capacity Buildout | Residence times below thirty minutes collapse utility supply chain costs for baseload power contracts. |
| Backward Integration into Feedstock Aggregation | Captive sawmill residue supply in Georgia and Alabama defends margins against Baltic price volatility. |
| Long-term Supply Agreement with Japanese Utilities | METI feed-in tariff obligations create decade-long revenue visibility for certified exporters. |
| Technology Licensing to New Market Entrants | Reactor engineering IP monetization accelerates industry capacity expansion without direct capital deployment. |
| Green Certification Program Investment | ENplus A1 grade differentiation captures premium procurement from German pulverized fuel boiler operators. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing utility procurement officers at German and Dutch power generators, torrefaction plant managers in Nordic engineering corridors, biomass fuel supply specialists at Japanese trading houses, and district heating network operators in South Korea. Secondary validation drew from EU ECHA substance registration databases, METI feed-in tariff implementation reports, US EIA biomass consumption statistics, and customs trade data for torrefied pellet volumes through Rotterdam and Kobe terminals. Bottom-up capacity installation tracking and top-down utility procurement survey data were triangulated to reconcile volume estimates.
Calibration against historical torrefaction capacity utilization rates and utility co-firing substitution ratios anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include feedstock origin, thermal application type, end-user scale tier, and delivery format configuration. CAGRs were derived from regression analysis of utility procurement contract volumes against regulatory incentive trajectories. Forecast inputs incorporated coal phase-out mandate timelines and carbon border adjustment mechanism implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in housing construction activity, natural gas price volatility, or EU sustainability criteria enforcement intensity would shift the trajectory. Cross-checking against IEA biomass market outlooks and national renewable energy statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Peat Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
Global Ruminant Feed Premix Market