
 Dairy Cattle Feed Market | 2026-2036
Dairy Cattle Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Cattle Feed Market Analysis
Market Context
Product bundling is shifting toward modular premix-to-concentrate configurations that let dairy operators scale rations by lactation stage rather than buying fixed formulations. Cargill leverages its vertical integration into grain origination and amino acid production to lock in margin pools across the value chain. Archer Daniels Midland anchors its position through oilseed processing infrastructure that supplies bypass protein and fat supplements to large herd operations. Alltech differentiates via yeast-based technologies and mycotoxin management programs that command premium positioning in veterinary-advised feeding protocols.
Technical Definition and Segments
Dairy cattle feed comprises formulated nutritional inputs designed to meet metabolizable energy, crude protein, fiber, and mineral requirements for lactating and dry cows, typically delivered as total mixed rations with specified dry matter content between 45% and 65%. Its primary commercial purpose is to maximize energy-corrected milk output while minimizing metabolic disorders and optimizing feed conversion efficiency. Concentrates and premixes within feed type segmentation capture the deepest margin pools due to their technical complexity and ingredient concentration, while organic supplements under formulation type represent the fastest-expanding category as processors respond to retailer and export market certification requirements. Distribution through agricultural cooperatives remains the dominant channel in consolidated dairy regions, though online retailers are gaining traction among mid-sized independent operators seeking price transparency and just-in-time delivery.
Regulatory Outlook
The US FDA and EPA jointly govern dairy feed through the BSE feed rule and environmental discharge permits that constrain protein sourcing and manure nutrient management, while the EU EFSA and REACH frameworks regulate novel feed additives and chemical residues in imported soybean and palm kernel meals. India's FSSAI and BIS standards enforce maximum residue limits and feed safety protocols that determine market access for domestic and imported premix suppliers. Stakeholders must monitor evolving antibiotic growth promoter restrictions and carbon accounting requirements that will reshape ingredient procurement decisions and supplier qualification criteria across major dairy producing regions.
Market Dynamics
Precision nutrition platforms and modular ration formulations are displacing fixed-formula procurement across commercial dairy operations, compressing traditional feed-mixing margins while elevating technical advisory services.
Growth Catalysts
- EU Green Deal sustainability mandates:Carbon accounting requirements for imported soybean and palm kernel meals are accelerating demand for traceable, certified-sustainable concentrate formulations.
- India's PLI scheme for animal husbandry:Government production-linked incentives are channeling capital toward organized dairy sector expansion and commercial feed penetration in Gujarat and Punjab.
- Yeast-based mycotoxin management:Veterinary-advised feeding protocols are incorporating live yeast cultures to reduce aflatoxin-related metabolic disorders in high-yielding herds.
Market Restraints
- Argentine and Brazilian soybean meal concentration:Protein sourcing dependency on South American crush capacity exposes formulation costs to weather-driven supply volatility and export duty fluctuations.
- US EPA environmental discharge permits:Manure nutrient management constraints limit herd expansion rates and increase compliance capital requirements for nitrogen and phosphorus runoff controls.
- Bypass fat technical limitations:Rumen-protected lipid formulations face absorption ceiling effects above 6% diet inclusion, capping energy density gains for peak-lactation cows.
Strategic Opportunities
- India's organized dairy cooperatives:Underpenetrated feed conversion in Rajasthan and Madhya Pradesh offers volume expansion for premix suppliers with cold-chain distribution partnerships.
- Online retailer channel emergence:Mid-sized independent operators in Maharashtra are migrating to digital procurement platforms for price transparency and just-in-time concentrate delivery.
- FSSAI-BIS feed safety harmonization:Unified maximum residue limit standards are streamlining market access for domestic and imported additive suppliers.
Industry Challenges
- Ruminant nutritionist talent scarcity:Commercial operations struggle to recruit specialists capable of balancing metabolizable energy models with farm-level feed conversion optimization.
- Total mixed ration mixer wagon capex:Precision delivery equipment for 500+ cow herds requires capital outlays that compress returns for mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Cattle Feed Market |
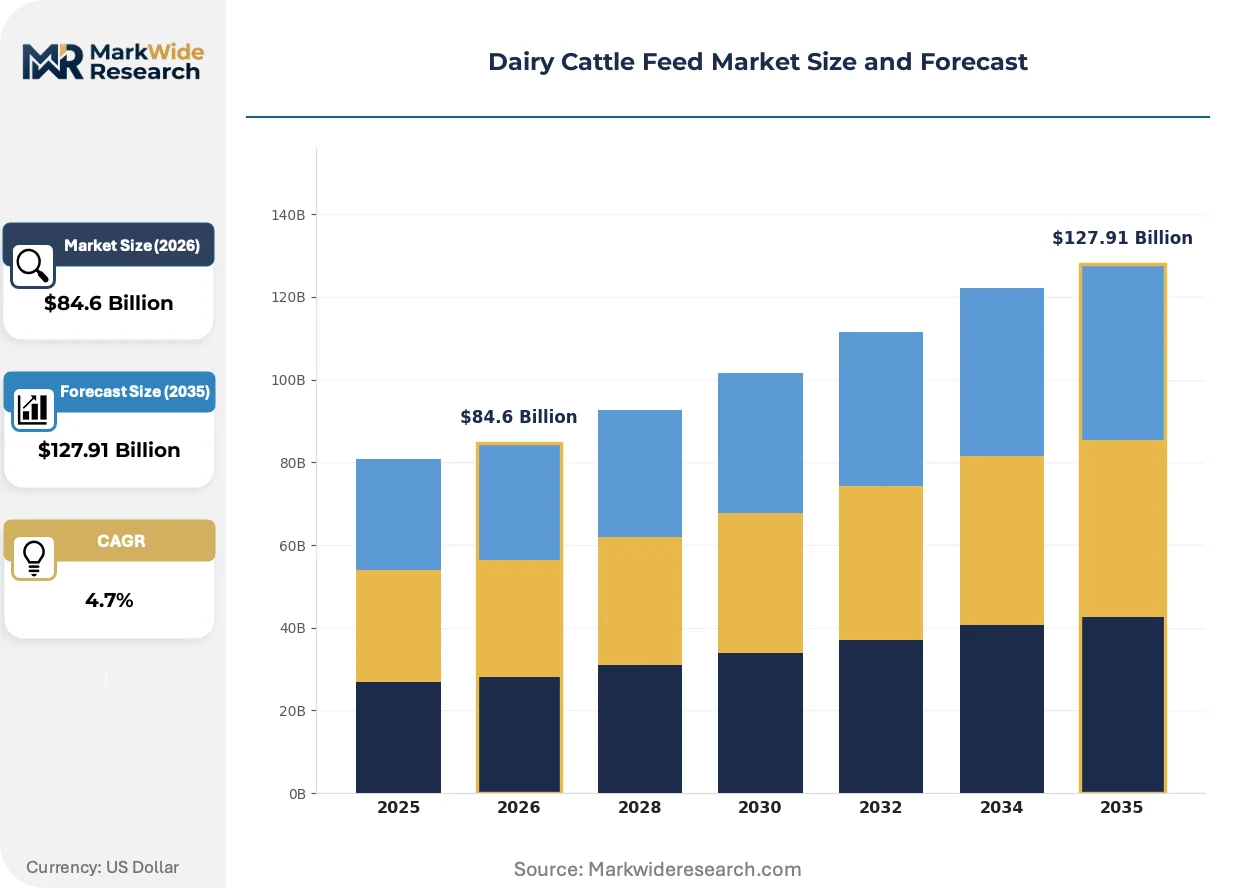
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $127.91 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Concentrates, Roughages, Additives, Premixes Nutritional Components: Proteins, Carbohydrates, Vitamins, Minerals Formulation Type: Custom Blends, Commercial Mixes, Organic Supplements, Conventional Feeds Distribution Channel: Online Retailers, Feed Stores, Wholesale Distributors, Agricultural Cooperatives |
| Companies Covered | Cargill, Archer Daniels Midland, Land O'Lakes, Nutreco, De Heus Animal Nutrition, ForFarmers, Godrej Agrovet, Charoen Pokphand Foods, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Cattle Feed Market Emerging Trajectories
Digital feed management systems and biosensor-enabled herd monitoring are compressing the feedback loop between ration formulation and milk output measurement, elevating data-analytics capabilities over commodity sourcing scale.
Near-infrared spectroscopy for real-time forage analysis is converging with cloud-based ration optimization software to enable dynamic TMR adjustments based on dry matter variation. Large herd operations in California's Central Valley are deploying portable NIR units at feed alleys, reducing nutritionist visit frequency while tightening energy-corrected milk consistency. This technology convergence is compressing the traditional feed consultant service model into software-subscription offerings.
REACH framework revisions for novel feed additives are extending safety dossier timelines for yeast derivatives and enzyme preparations entering the EU market. EFSA's expanded residue testing protocols for imported oilseed meals are redirecting procurement toward certified deforestation-free supply chains. Premix suppliers with pre-validated additive portfolios are capturing shelf space from competitors facing 18-24 month approval delays.
Cooperative members in Gujarat are unbundling veterinary advisory from concentrate supply, purchasing modular premixes separately and sourcing base grains through independent traders. This procurement fragmentation is compressing integrated feed company margins while elevating specialized premix brands with strong technical support reputations. Channel disintermediation is most visible among 50-200 cow operations seeking pricing transparency against cooperative pooling arrangements.
Dairy Cattle Feed Market Segmentation
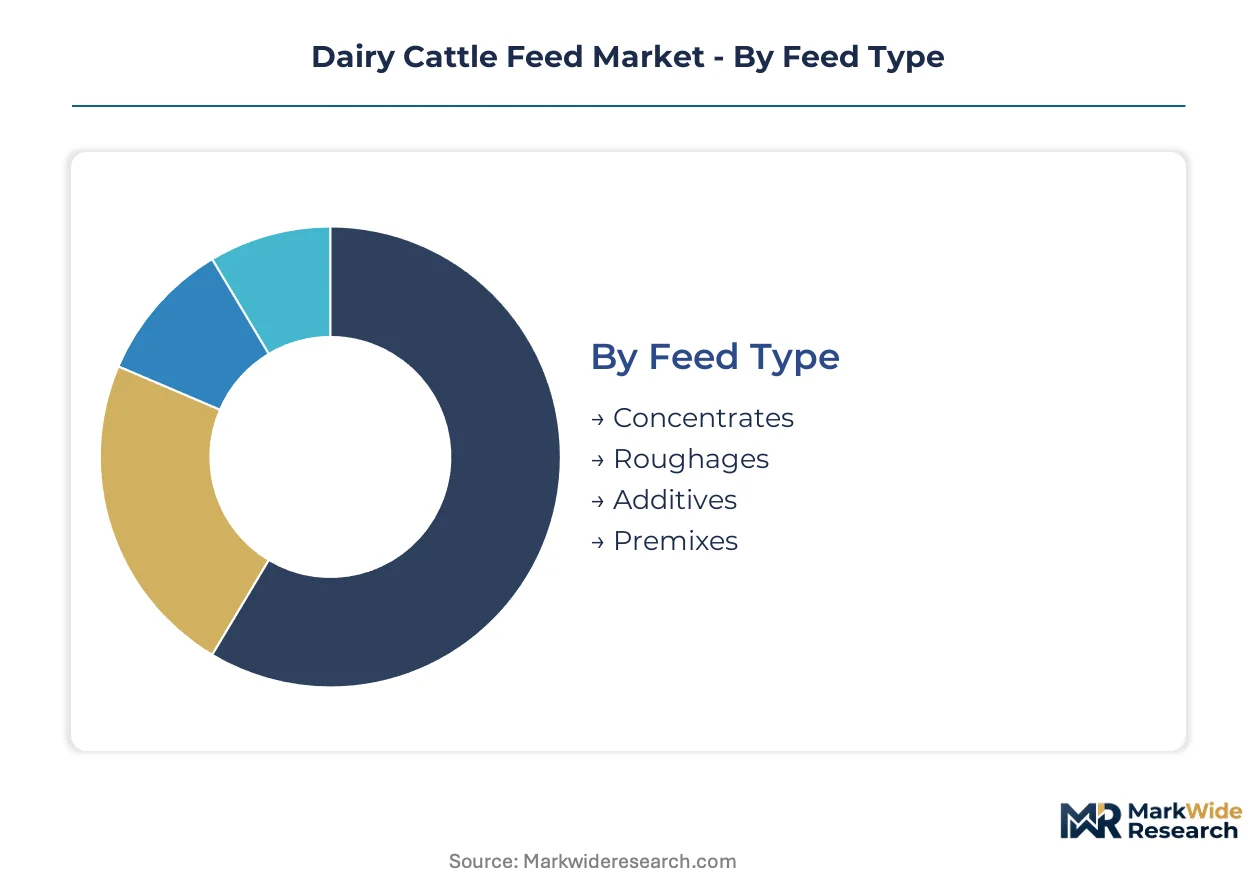
Dairy cattle feed segmentation reflects divergent procurement strategies between precision-focused commercial operations and cost-conscious traditional farms. Technical complexity and margin concentration vary sharply across formulation approaches, channel structures, and nutritional specifications.
Feed Type:
Standardization dominates commodity roughages while concentrates and premixes offer modular customization by lactation stage and metabolic requirements.
- Concentrates:Energy-dense formulations combining grains, oilseed meals, and bypass proteins to balance metabolizable energy deficits in high-yielding herds. Demand concentrates in Gujarat and Punjab commercial dairies where PLI scheme incentives accelerate organized sector feed conversion.
- Premixes:Micro-ingredient blends delivering precise vitamin, mineral, and additive concentrations for veterinary-advised feeding protocols. Procurement is fragmenting among Rajasthan and Madhya Pradesh cooperatives unbundling advisory from base grain supply.
- Roughages:Forage-based bulk feeds including hay, silage, and pasture providing fiber for rumen function. Gujarat dairy cooperatives dominate procurement volume through pooled sourcing arrangements.
- Additives:Yeast cultures, enzymes, and mycotoxin binders targeting metabolic efficiency and herd health. EFSA safety dossier timelines constrain EU market entrants while premix suppliers with pre-validated portfolios capture shelf space.
Leading the category by volume: Roughages. Growing fastest: Premixes.
Nutritional Components:
Cost tier stratification separates commodity carbohydrates from premium proteins and precision-delivered micronutrients.
- Proteins:Soybean meal, canola, and bypass protein sources meeting crude protein specifications for lactation maintenance and milk synthesis. Argentine and Brazilian crush capacity concentration exposes formulation costs to weather-driven supply volatility.
- Carbohydrates:Starch and fiber sources including corn, barley, and forage providing fermentable energy for rumen microbial protein production. Base grain procurement is shifting toward independent traders as cooperatives lose pooling leverage.
- Vitamins:Fat-soluble and water-soluble micronutrient premixes preventing deficiency disorders in confined feeding operations. Custom blend demand is rising among 50-200 cow operations seeking veterinary-specific formulations.
- Minerals:Macro and trace element supplements balancing calcium, phosphorus, and selenium for metabolic health. FSSAI-BIS maximum residue limit harmonization is streamlining supplier qualification for domestic and imported sources.
Volume concentration: Carbohydrates. Steepest expansion trajectory: Proteins.
Formulation Type:
Application specificity drives divergence between commodity commercial mixes and precision-engineered custom blends.
- Custom Blends:Ration formulations tailored to herd-specific metabolic profiles, forage quality, and production targets by on-staff or consultant nutritionists. Maharashtra mid-sized operators are migrating toward digital procurement platforms enabling just-in-time concentrate delivery.
- Organic Supplements:Certified-sustainable inputs meeting retailer and export market requirements for residue-free milk production. EU Green Deal carbon accounting mandates for imported soybean and palm kernel meals are accelerating traceable sourcing.
- Commercial Mixes:Fixed-formulation products targeting standard production stages with limited customization. Margin compression is forcing integrated feed companies toward technical advisory services.
- Conventional Feeds:Traditional commodity rations without certification or precision nutrition targeting. Market share is eroding as organized dairy sector participation rises.
Dominant by volume: Commercial Mixes. Climbing the fastest: Organic Supplements.
Distribution Channel:
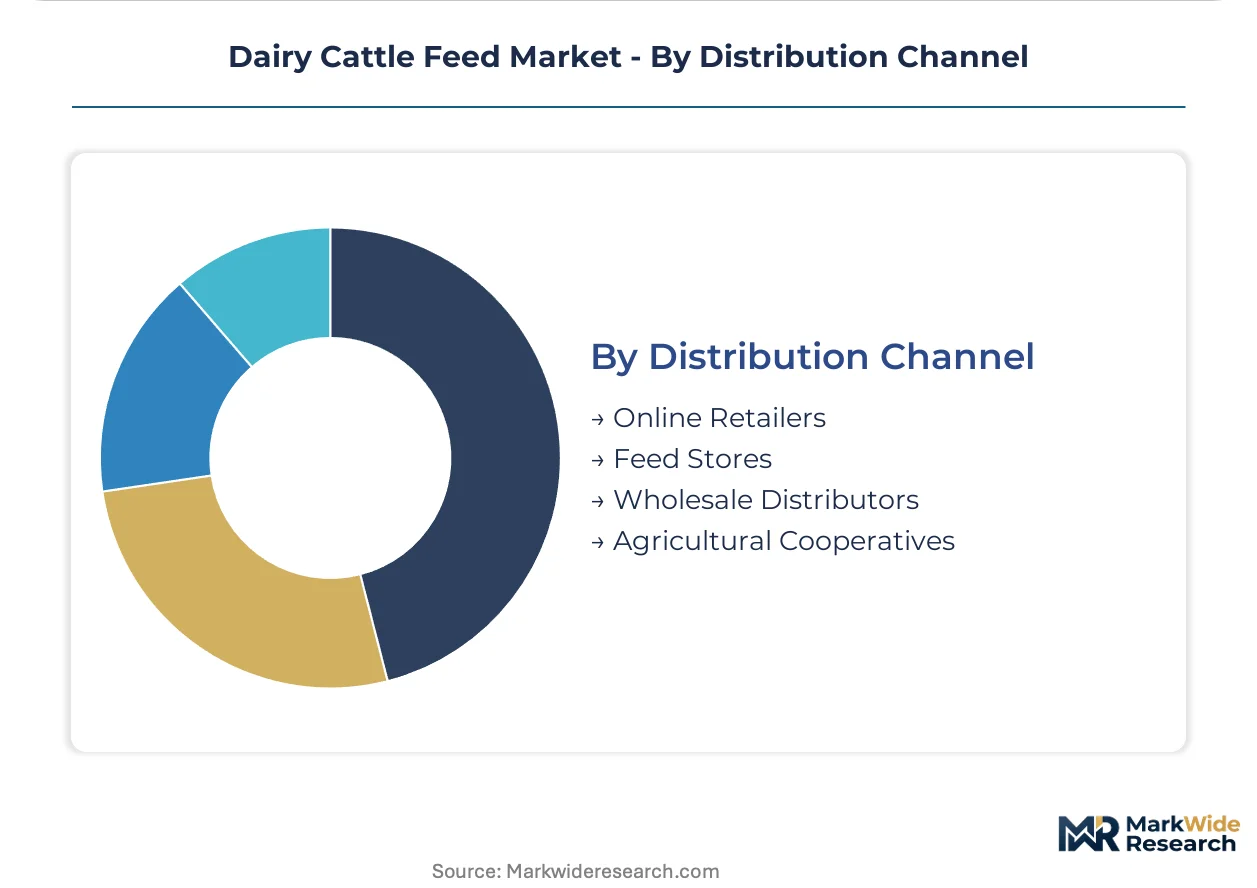
Customer scale determines channel selection between cooperative pooling and direct digital procurement.
- Agricultural Cooperatives:Member-based purchasing organizations dominating consolidated dairy regions through volume aggregation and credit terms. Gujarat and Punjab cooperatives retain stronghold among 200+ cow operations despite unbundling pressures.
- Online Retailers:Digital platforms delivering price transparency and just-in-time logistics to independent operators. Maharashtra mid-sized dairies are leading migration away from cooperative pooling arrangements.
- Feed Stores:Local retail outlets serving smallholder operations with limited storage capacity and immediate delivery needs. Foot traffic is declining as smartphone penetration enables digital price comparison.
- Wholesale Distributors:Regional logistics networks supplying bulk volumes to large herd operations and secondary retailers. Cold-chain partnerships are becoming critical for premix suppliers targeting Rajasthan and Madhya Pradesh expansion.
Highest volume channel: Agricultural Cooperatives. Gaining share fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Punjab concentrate commercial dairy feed demand through India's PLI scheme for animal husbandry, channeling capital toward organized sector expansion.
United States
California's Central Valley dairies deploy precision nutrition platforms with near-infrared spectroscopy for real-time forage analysis. The US FDA and EPA jointly govern feed through BSE feed rules and environmental discharge permits that constrain protein sourcing. Large herd operations in Tulare and Merced counties lead adoption of modular premix-to-concentrate configurations.
India
Organized dairy cooperatives in Gujarat and Punjab accelerate commercial feed penetration through government production-linked incentives. FSSAI and BIS standards enforce maximum residue limits that determine market access for domestic and imported premix suppliers. Rajasthan and Madhya Pradesh present underpenetrated expansion opportunities for cold-chain-equipped premix distributors.
Germany
Precision-formulated concentrate demand concentrates in Lower Saxony's intensive dairy regions responding to EU Green Deal carbon accounting mandates. EFSA and REACH frameworks regulate novel feed additives and chemical residues in imported oilseed meals. Bavarian dairy operations source certified-deforestation-free soybean meals to meet retailer sustainability certification requirements.
Brazil
Crush capacity concentration in Paraná and Rio Grande do Sul exposes formulation costs to weather-driven supply volatility and export duty fluctuations. The country's national agricultural regulator enforces feed safety protocols for commercial dairy expansion in São Paulo's organized sector. Minas Gerais dairies balance metabolizable energy models with farm-level feed conversion optimization challenges.
Netherlands
Cooperative pooling arrangements dominate consolidated dairy regions while mid-sized operators migrate toward digital procurement platforms. EU EFSA expanded residue testing protocols redirect procurement toward traceable supply chains. Friesland and Gelderland clusters lead unbundling of veterinary advisory from concentrate supply toward modular premix purchasing.
Dairy Cattle Feed Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered margin pools. Concentrates and premixes capture the deepest margins due to technical complexity, while commodity roughages consolidate around agricultural cooperatives. Three archetypes dominate: grain-origination conglomerates with captive amino acid production, oilseed processors supplying bypass proteins, and yeast-technology specialists commanding veterinary-advised protocol premiums. Competitive moves center on backward integration into grain origination and technical advisory service expansion.
Within the diversified conglomerate tier, Cargill and Archer Daniels Midland occupy positions spanning grain origination through oilseed processing infrastructure. Cargill exemplifies backward integration into amino acid production, while Archer Daniels Midland anchors supply networks for bypass protein and fat supplements. Alltech sits within the specialist tier, representing yeast-based technology and mycotoxin management programs that command premium positioning. These three companies illustrate the divergence between scale-driven commodity sourcing and technical differentiation in precision nutrition platforms.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Land O'Lakes |
| Nutreco |
| De Heus Animal Nutrition |
| ForFarmers |
| Godrej Agrovet |
| Charoen Pokphand Foods |
| Alltech |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon accounting mandates for imported soybean and palm kernel meals gate qualified supply access and premium-tier pricing for certified-sustainable concentrate formulations. Buyers without traceable sourcing documentation face exclusion from retailer and export market procurement while compliant suppliers capture margin premiums through deforestation-free certification tiers.
Pricing Analysis
Margin tightening in premix formulations reflects EFSA safety dossier timelines extending novel additive approval cycles to 18-24 months. Three-tier pricing structure across veterinary-advised premium, cooperative-standard, and commodity-economy levels separates buyers by certification grade and technical support depth. Cost-down pressure on commercial mixes accelerates because cooperative members in Gujarat unbundle advisory services from base grain supply. Mid-sized independent operators in Maharashtra exhibit highest price sensitivity through digital platform migration, while large herd operations in California's Central Valley demonstrate lowest sensitivity due to energy-corrected milk yield optimization priorities.
Supply Chain Analysis
Regional distribution centers in Paraná and Rio Grande do Sul anchor hub-and-spoke patterns for South American crush capacity serving global protein demand. Argentine and Brazilian soybean meal concentration draws formulation costs into weather-driven supply volatility and export duty fluctuation exposure. Raw material dependencies center on oilseed processing infrastructure, amino acid production, and yeast culture propagation facilities. Single-source vulnerability from South American crush concentration presents structural risk for premix suppliers without diversified protein sourcing. Distribution runs through agricultural cooperatives in consolidated dairy regions, with cold-chain partnerships becoming critical for Rajasthan and Madhya Pradesh expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH framework revisions for novel feed additives create a compliance moat that rewards premix suppliers with pre-validated portfolios while excluding competitors facing extended approval delays. This cost-of-compliance dynamic concentrates margin capture among established players with existing safety dossiers.
For Market Incumbents: Lock in backward integration into grain origination and amino acid production to defend margin pools against cooperative unbundling pressures. Capture channel control through cold-chain distribution partnerships in underpenetrated Rajasthan and Madhya Pradesh. Certification investment in EU Green Deal traceability systems represents the priority lever for premium-tier pricing access.
For New Entrants and Emerging Players: Begin with modular premix formulations targeting 50-200 cow operations in Maharashtra seeking pricing transparency through digital procurement platforms. The most penetrable segment sits among cooperative members unbundling veterinary advisory from concentrate supply. A go-to-market angle through just-in-time logistics partnerships with online retailers bypasses established cooperative gatekeepers.
For Investors and Strategic Acquirers: EFSA pre-validated additive portfolio announcements are the leading indicator that premix suppliers are capturing shelf space from approval-delayed competitors. Long-term viability over a 5-10 year horizon favors yeast-technology specialists with veterinary-advised protocol positioning. Acquisition target archetype: regional premix brands with strong technical support reputations and established cold-chain partnerships in India.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Production | Cargill's captive supply of lysine and methionine locks in concentrate margin pools across Gujarat and Punjab. |
| Cold-Chain Distribution Partnership | Premix suppliers with Rajasthan and Madhya Pradesh logistics networks capture volume from underpenetrated cooperative markets. |
| EFSA Pre-Validation Investment | Yeast derivative and enzyme portfolios with completed safety dossiers bypass 18-24 month approval delays for EU shelf space. |
| Digital Platform Channel Expansion | Online retailer partnerships with just-in-time delivery capabilities penetrate Maharashtra's mid-sized independent operator segment. |
| Certified Deforestation-Free Sourcing | Traceable soybean and palm kernel meal procurement meets Bavarian retailer sustainability certification requirements. |
Methodological Framework
USDA National Agricultural Statistics Service, EU EFSA feed additive registers, and India FSSAI maximum residue limit notifications formed the secondary backbone of this study. Primary interviews with dairy nutritionists, cooperative procurement managers, premix formulation specialists, and cold-chain logistics operators combined with secondary validation across customs records and oilseed crush capacity databases. Bottom-up herd-size segmentation triangulated against top-down feed consumption estimates from agricultural ministry disclosures.
Historical trendline analysis of commercial feed penetration rates, premix adoption curves, and cooperative unbundling patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include feed type, formulation approach, distribution channel, and regional dairy sector organization level. CAGRs derived from metabolizable energy demand projections, milk yield optimization targets, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated PLI scheme capital deployment timelines and EFSA approval pipeline status.
Underlying measurement precision varies by segment; concentrates and premixes carry tighter precision than roughage volumes due to commercial transaction documentation. Forecasts reflect assumptions around regulatory timeline stability, climate volatility patterns, and cooperative structural integrity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Organic Feed Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Bamboos Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Italy Animal Protein Market