
 Global Ruminant Feed Premix Market | 2026-2036
Global Ruminant Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ruminant Feed Premix Market Foresight
Multi-source procurement of micronutrient blends is shifting toward vertically integrated compound feed operations. Cargill leverages its global grain origination network to secure captive vitamin supply chains. DSM-Firmenich anchors its position through fermentation-derived amino acid platforms. BASF competes on synthetic vitamin A and E cost curves across European dairy markets.
Ruminant feed premix denotes a concentrated blend of vitamins, minerals, amino acids, enzymes, and probiotics mixed at 0.5-3% inclusion rates into complete feeds to optimize rumen fermentation and nutrient absorption. Vitamin premix maintains mature volume leadership but faces margin compression from generic suppliers. Enzyme premix represents the fastest-expanding category as phytase and fibrolytic additives displace inorganic phosphate in dairy rations. Probiotic premix concentrates margin pools in anaerobic stability and mycotoxin binding applications for high-starch diets.
Feed Hygiene Regulation (183/2005) and the EU Green Deal's methane reduction targets compel reformulation toward low-emission nutrient densities. FDA's Center for Veterinary Medicine and China's MEE enforce residue limits and environmental discharge standards that filter market access. Stakeholders must monitor regulatory divergence between jurisdictions that reward carbon-accounted premix credentials versus cost-optimized commodity blends.
Market Dynamics
Precision fermentation and cell-culture vitamin synthesis are compressing traditional chemical synthesis margins while EU methane mandates force reformulation toward low-nitrogen premix architectures.
Growth Catalysts
- EU Green Deal methane targets:Dairy operations across Denmark and the Netherlands must reduce enteric emissions by 2030, accelerating demand for rumen-modifier premixes containing 3-NOP and essential oils.
- High-yielding herd expansion:US dairy producers operating 1,000+ cow facilities are standardizing precision nutrition protocols that mandate micronutrient premix customization by lactation stage.
- Phytase enzyme adoption:Brazilian integrated beef systems in Mato Grosso are displacing inorganic phosphate with heat-stable fungal phytase premixes to meet export residue standards.
Market Restraints
- Vitamin A/E price volatility:Synthetic retinol and tocopherol feedstock costs track petrochemical naphtha indices, exposing compounders to margin squeeze during energy price spikes.
- China captive supply concentration:Over 60% of global B-vitamin fermentation capacity sits in Shandong and Jiangsu provinces, creating single-source vulnerability for European premix formulators.
- Regulatory divergence friction:FDA's GRAS self-affirmation pathway conflicts with EFSA's mandatory pre-market authorization, forcing dual dossier development for transatlantic premix suppliers.
Strategic Opportunities
- Vietnam dairy modernization:State-backed herd expansion to 1.5 million milking cows by 2030 creates first-mover advantage for premix suppliers offering total mixed ration consulting bundled with micronutrient blends.
- Carbon-accounted premix certification:France's national low-carbon label and California's LCFS credit system reward suppliers documenting Scope 3 feed ingredient emissions, unlocking price premiums in sustainability-indexed procurement.
- Direct-to-farm digital channels:Argentine feedlot operators in Buenos Aires province are bypassing traditional distributor networks through platform-based premix ordering with real-time formulation adjustments.
Industry Challenges
- Rumen microbiome modeling talent scarcity:Formulation teams lack computational biologists capable of integrating metagenomic data into premix design, slowing next-generation probiotic development cycles.
- Multi-jurisdiction residue compliance:Codex MRL harmonization lags behind national enforcement, forcing exporters to maintain parallel premix specifications for EU, US, and Chinese maximum residue limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ruminant Feed Premix Market |
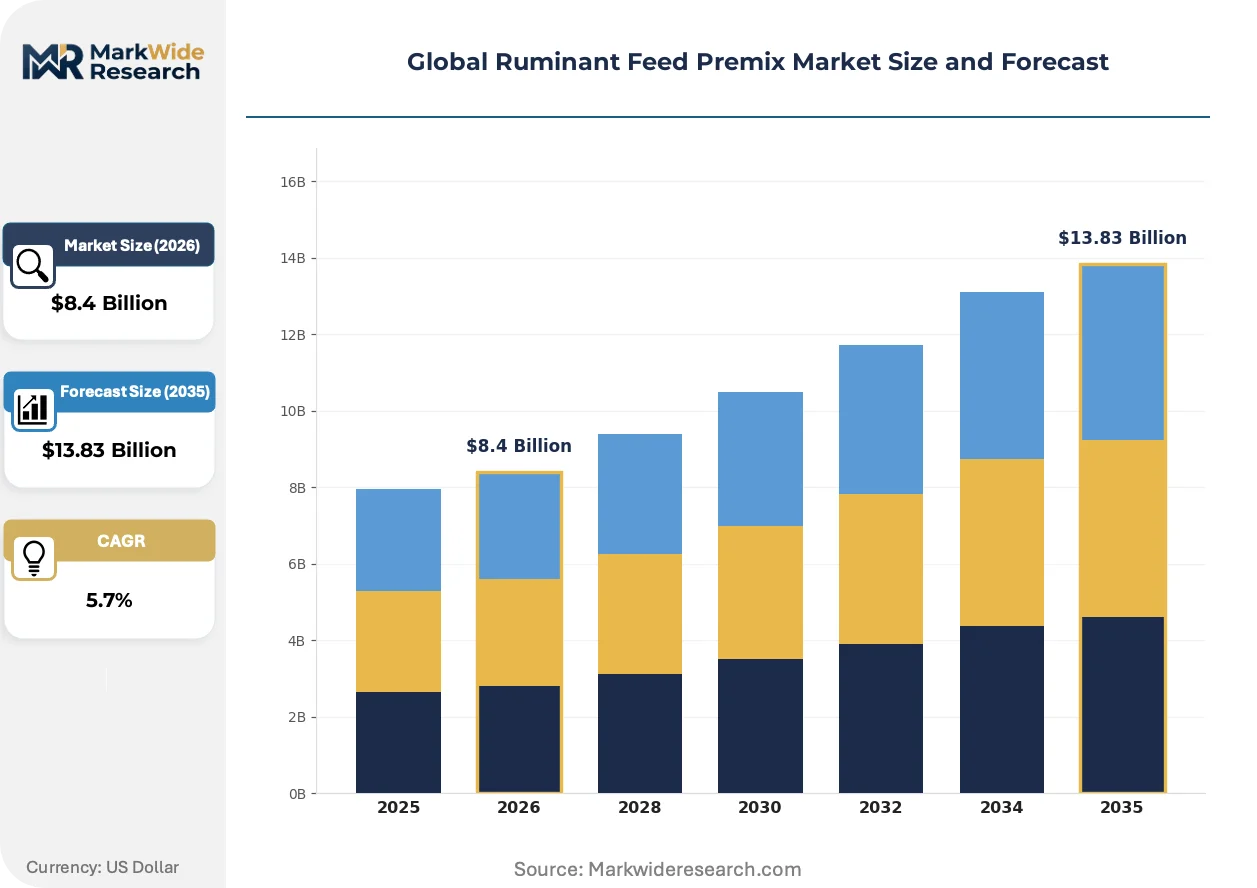
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin Premix, Mineral Premix, Amino Acid Premix, Enzyme Premix, Probiotic Premix Application: Dairy Production, Meat Production, Calf Feed, Breeding Stock Nutrition, Wool Production End User: Livestock Farms, Feed Manufacturers, Animal Nutritionists, Veterinary Clinics, Research Institutions Distribution Channel: Direct Sales, Online Platforms, Dealers & Distributors, Retail Stores, Cooperative Societies |
| Companies Covered | Cargill, Archer Daniels Midland Company, DSM-Firmenich, BASF, Alltech, Nutreco, Land O'Lakes, Evonik Industries, De Heus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ruminant Feed Premix Market Shifts & Advancements
Biotechnology-enabled ingredient platforms and carbon-accounting supply chains are redefining competitive differentiation beyond traditional micronutrient specifications.
Precision-fermented amino acids are expanding into dairy premix formulations as L-lysine and L-methionine producers achieve cost parity with extraction-based supply. Large-scale cooperatives in Wisconsin and Minnesota are trialing these bio-identical inputs for high-producing Holstein herds. The technology is expanding into ruminant markets from monogastric dominance, compressing synthetic amino acid incumbent margins.
EFSA's updated guidance on botanical feed additives requires full toxicological dossiers for novel essential oil premixes, extending approval timelines from 18 to 36 months. Italian and Spanish premix houses are consolidating legacy product lines to focus resources on dossier-heavy submissions. Dairy calf starter segments face the tightest reformulation pressure as thyme and oregano oil claims require new efficacy validation.
Consolidated procurement by mega-dairies is compressing distributor tiers as 5,000-cow operations in Idaho and Texas negotiate direct premix supply agreements with vitamin houses. Traditional regional feed dealers are repositioning as logistics and technical service providers rather than margin-capturing intermediaries. This channel restructuring is most advanced in US Southwest and Midwest dairy belts where buyer concentration exceeds 40% of regional volume.
Global Ruminant Feed Premix Market Segmentation
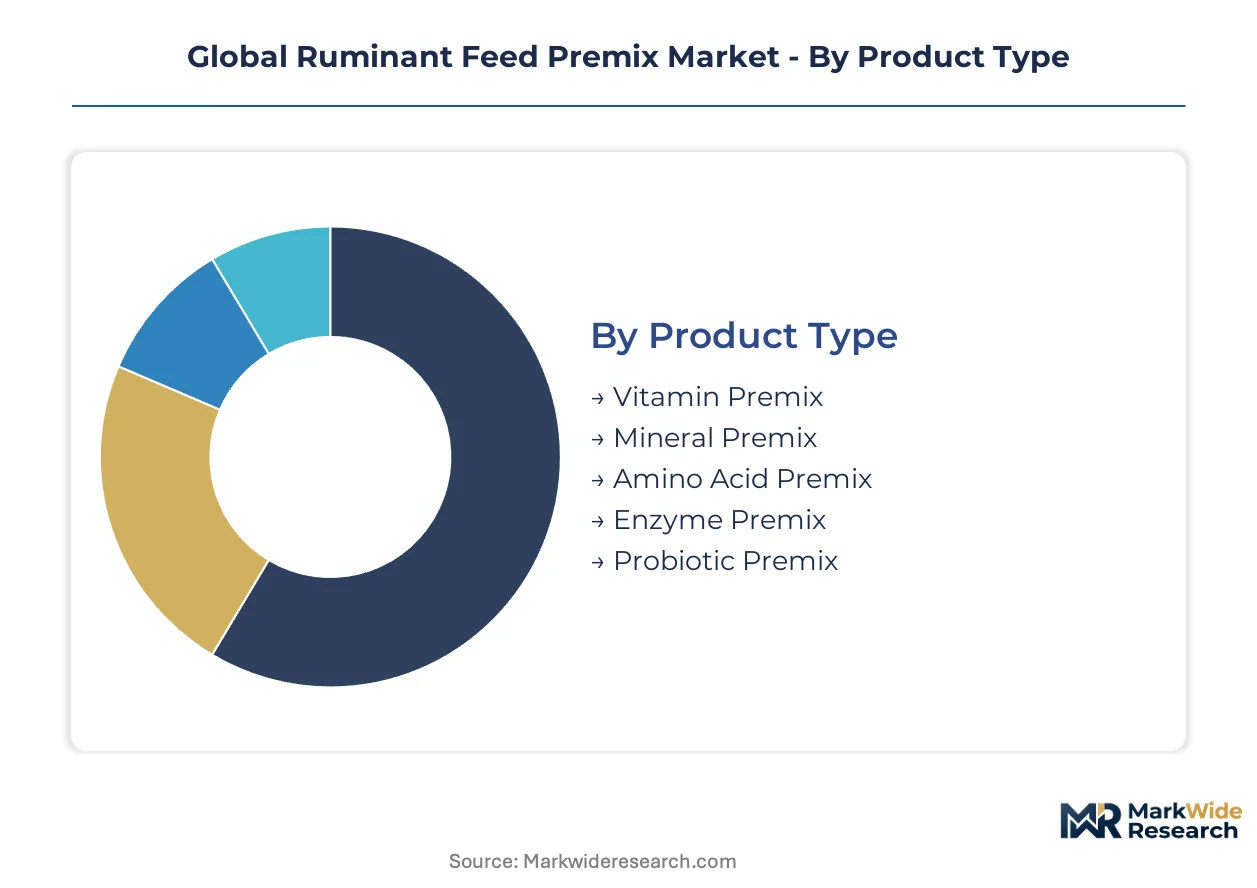
Ruminant feed premix markets fragment across nutritional function, production system, and procurement channel. Each dimension carries distinct margin structures and regulatory exposure that shape supplier positioning.
Product Type:
Customization intensity varies sharply across this category, from commodity vitamin blends to precision-engineered enzyme platforms requiring species-specific dosing algorithms.
- Vitamin Premix:Concentrated blends of fat-soluble and water-soluble vitamins formulated at 0.1-0.5% inclusion rates. Demand concentrates in European dairy operations facing EU Green Deal methane mandates that require reformulated nutrient densities. Generic supplier proliferation has compressed margins, forcing differentiation through stability-enhancing encapsulation technologies.
- Enzyme Premix:Heat-stable phytase and fibrolytic enzyme concentrates displacing inorganic phosphate in high-starch dairy rations. Brazilian integrated beef systems in Mato Grosso are scaling adoption fastest to meet export residue standards for EU and Chinese buyers.
- Mineral Premix:Chelated and inorganic trace element blends optimized for bioavailability in rumen environments.
- Amino Acid Premix:Rumen-protected lysine and methionine formulations for high-yielding Holstein herds.
- Probiotic Premix:Live culture and postbiotic concentrates targeting anaerobic stability and mycotoxin binding.
Most installed capacity flows through Vitamin Premix. Expansion is steepest in Enzyme Premix.
Application:
Volume concentration tracks herd scale and output intensity, with dairy operations commanding the most sophisticated micronutrient protocols.
- Dairy Production:Lactation-stage customized premixes for high-producing herds in Wisconsin, Minnesota, and Denmark. US operations running 1,000+ cow facilities now mandate precision nutrition protocols with real-time formulation adjustments.
- Meat Production:Feedlot finishing rations emphasizing feed conversion efficiency and residue compliance for export markets. Argentine operators in Buenos Aires province are bypassing traditional distributors through platform-based premix ordering.
- Calf Feed:Starter formulations with elevated vitamin E and selenium for immune development.
- Breeding Stock Nutrition:Reproductive performance premixes for bull and replacement heifer development.
- Wool Production:Sulfur amino acid supplemented rations for Merino and specialty fiber flocks.
Revenue concentration sits with Dairy Production. Technology transfer is accelerating fastest in Meat Production.
End User:
Procurement sophistication separates captive compound feed operations from price-sensitive direct farm buyers.
- Feed Manufacturers:Vertically integrated compounders in Brazil and the United States sourcing captive vitamin supply chains. Cargill leverages global grain origination networks to secure backward integration into micronutrient inputs.
- Livestock Farms:Mega-dairies in Idaho and Texas negotiating direct supply agreements with vitamin houses, compressing traditional distributor tiers.
- Animal Nutritionists:Independent consultants specifying custom premix architectures for performance optimization.
- Veterinary Clinics:Therapeutic nutrition protocols for metabolic disorder prevention and recovery.
- Research Institutions:Trial-grade premixes for rumen microbiome and methane mitigation studies.
Contract volume aggregates through Feed Manufacturers. Margin expansion is strongest with Livestock Farms.
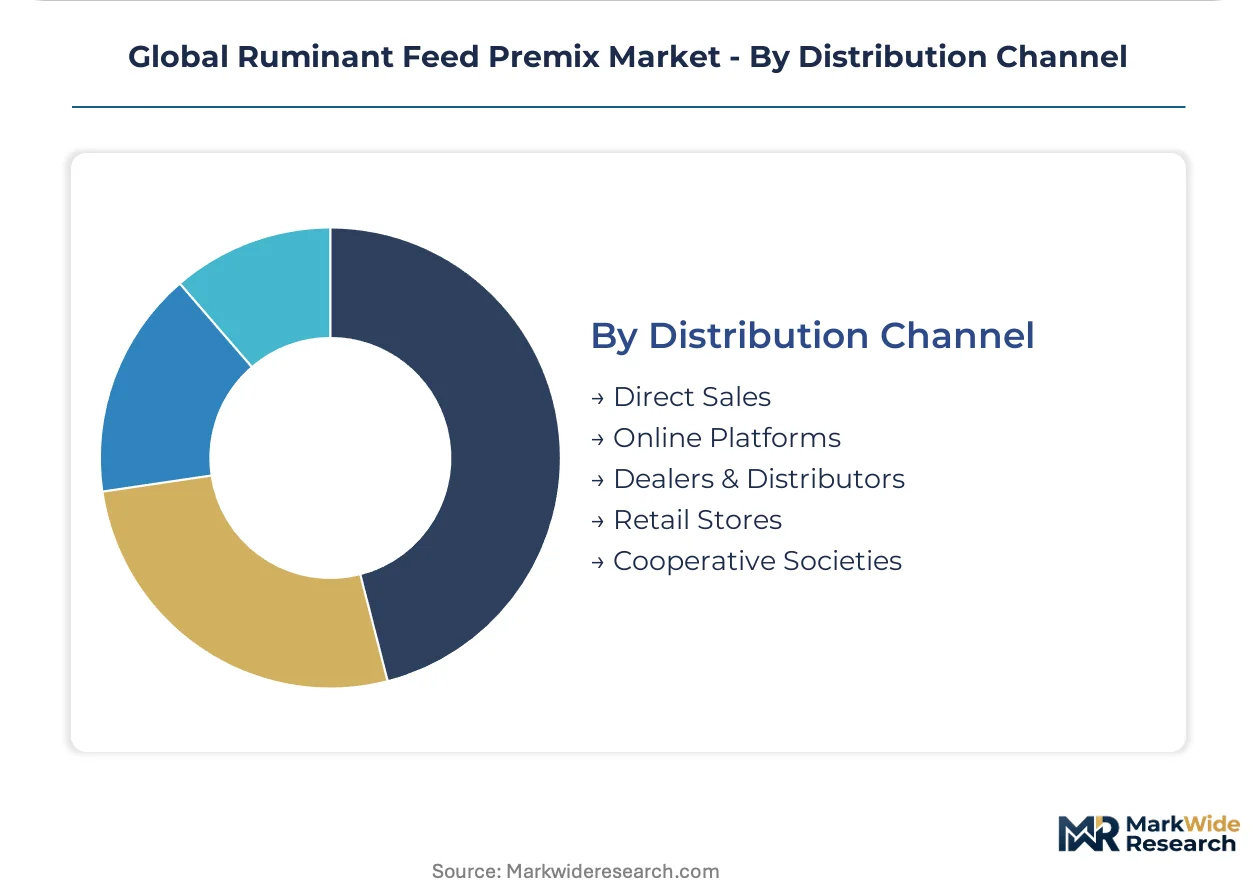
Distribution Channel:
Channel restructuring reflects buyer scale concentration and digital platform penetration.
- Direct Sales:Long-term supply agreements between vitamin houses and 5,000-cow operations. This channel captures the highest margin premix formulations with bundled technical service.
- Dealers & Distributors:Traditional regional feed dealers repositioning as logistics providers rather than margin-capturing intermediaries. Concentration exceeds 40% of regional volume in US Southwest and Midwest dairy belts.
- Online Platforms:Argentine feedlot operators ordering with real-time formulation adjustments.
- Cooperative Societies:Member-owned purchasing for mid-scale dairy and beef operations.
- Retail Stores:Smallholder-accessible premix packaging for hobby farms and specialty breeders.
Volume share is consolidating in Direct Sales. Platform penetration is climbing fastest in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso and São Paulo states anchor premix demand concentration through Brazil's integrated beef and dairy operations. Wisconsin and Minnesota dairy belts in the United States command precision nutrition sophistication. Denmark and the Netherlands face EU Green Deal methane mandates forcing rapid reformulation.
United States
Idaho and Texas mega-dairies running 5,000+ cow facilities negotiate direct supply agreements with vitamin houses, bypassing traditional distributor tiers. FDA's Center for Veterinary Medicine enforces residue limits that filter market access for imported premix formulations. The Southwest and Midwest dairy belts concentrate over 40% of regional premix volume through buyer consolidation.
Brazil
Integrated beef systems in Mato Grosso displace inorganic phosphate with heat-stable fungal phytase premixes to meet EU and Chinese export residue standards. ANVISA coordinates with Codex MRL frameworks while maintaining national enforcement discretion. São Paulo state dairy cooperatives scale commercial premix adoption through backward integration into compound feed operations.
Denmark
Dairy operations must reduce enteric emissions by 2030 under EU Green Deal methane targets, accelerating demand for rumen-modifier premixes containing 3-NOP and essential oils. EFSA mandates pre-market authorization for novel botanical additives, extending approval timelines. Jutland Peninsula clusters host formulation R&D for low-nitrogen premix architectures.
China
Shandong and Jiangsu provinces concentrate over 60% of global B-vitamin fermentation capacity, creating single-source vulnerability for European premix formulators. MEE enforces environmental discharge standards that constrain expansion timelines. Yangtze River Delta feed manufacturers captive supply chains through state-backed industrial consolidation.
Vietnam
State-backed herd expansion to 1.5 million milking cows by 2030 creates first-mover advantage for premix suppliers offering total mixed ration consulting bundled with micronutrient blends. The country's national agricultural regulator coordinates import permit frameworks for enzyme and probiotic additives. Mekong Delta dairy zones attract technical service investments from multinational vitamin houses.
Global Ruminant Feed Premix Market Competitive Landscape
Global majors compete with regional champions across formulation sophistication and supply chain control. The vendor base stratifies into three tiers: integrated agribusiness conglomerates with captive vitamin supply chains, fermentation-derived specialty houses, and regional compounders serving price-sensitive livestock farms. Strategic archetypes include backward-integrated grain originators, precision-fermentation amino acid platforms, and synthetic vitamin cost-curve competitors. Dominant competitive moves center on direct-to-farm channel compression and carbon-accounted certification development.
Within the integrated conglomerate tier, Cargill leverages its global grain origination network to secure upstream control over micronutrient inputs. DSM-Firmenich anchors the fermentation-specialist position through amino acid platform investments. BASF occupies a position on synthetic vitamin cost curves across European dairy markets. These three exemplify divergent strategic bets on biotechnology-enabled ingredient platforms versus petrochemical-derived feedstock economics.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| BASF |
| Alltech |
| Nutreco |
| Land O'Lakes |
| Evonik Industries |
| De Heus |
| Others |
Supply & Pricing Matrix
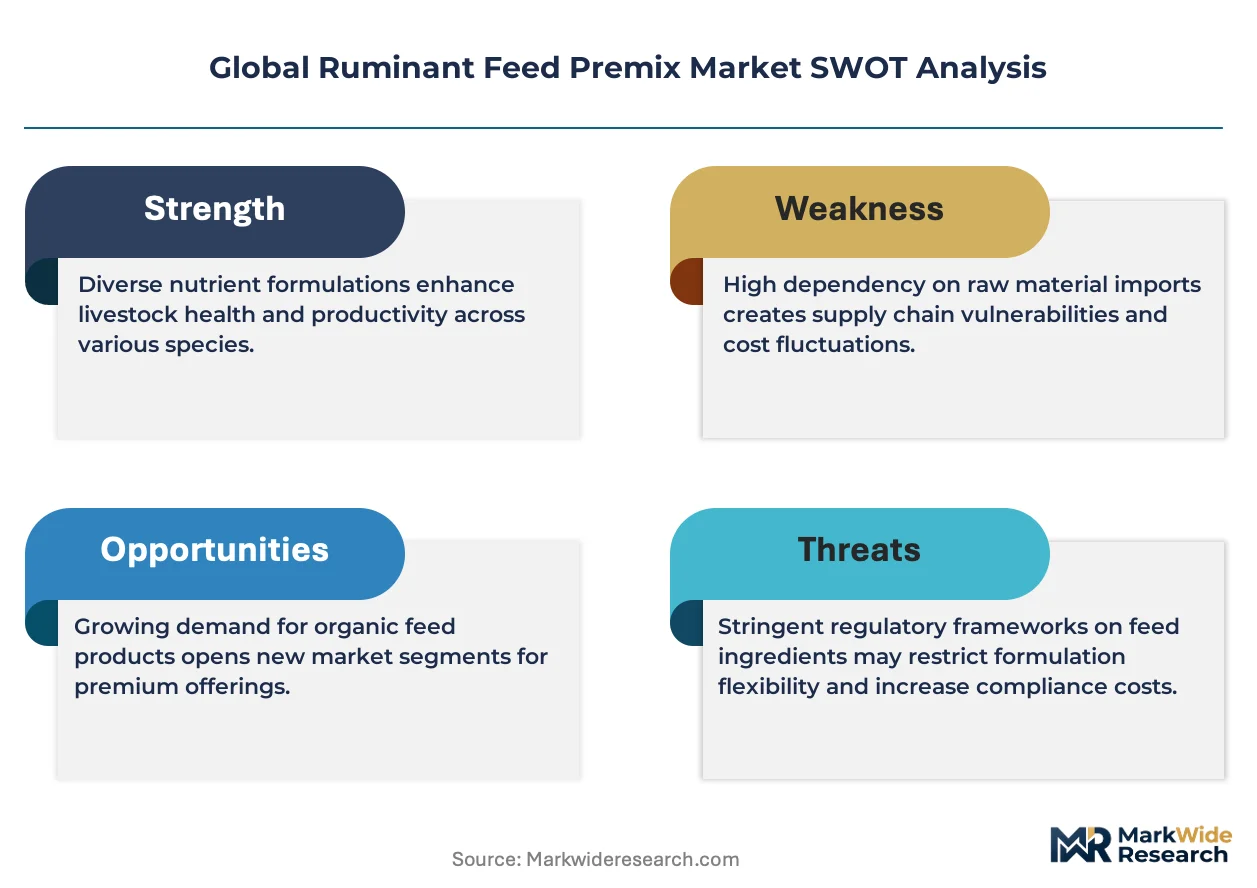
Family-owned mid-cap premix specialists in Northern Italy and the Netherlands operate with patient capital structures that resist short-term margin compression, enabling supply discipline that sustains pricing power even when petrochemical feedstock costs spike. Their ownership model permits multi-year vitamin inventory positions that commodity traders cannot replicate, creating asymmetric resilience against naphtha-indexed input volatility.
Pricing Analysis
Petrochemical feedstock pass-through dominates synthetic vitamin A and E pricing, with retinol and tocopherol costs tracking naphtha indices that expose compounders to margin squeeze during energy price spikes. Three-tier pricing structure across premium encapsulated, standard stabilized, and economy bulk vitamin tiers separates suppliers by thermal stability certification and geographic delivery scope. Cost compression in economy-grade vitamin premixes is intensifying because generic Chinese fermentation capacity floods spot markets. Mega-dairies running 5,000-cow direct supply agreements exhibit lowest price sensitivity, while smallholder cooperatives in Vietnam and Argentina face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates from European premix formulators now require qualified backup suppliers for all B-vitamin inputs, responding to single-source vulnerability after Shandong and Jiangsu province concentration exceeded sixty percent of global fermentation capacity. Raw material dependencies center on corn-derived dextrose for fermentation media, petrochemical naphtha for synthetic vitamin synthesis, and specialized mineral chelates from Belgian and German metal processors. Tariff exposure on Chinese vitamin imports into the United States and European Union threatens margin structures for non-vertically integrated compounders. Distribution runs through captive compound feed operations in Brazil and the United States, with direct-to-farm channels capturing fastest volume migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ruminant Feed Premix Market functions as a geographic-arbitrage play where EU Green Deal methane compliance costs in Denmark and the Netherlands run three to four times above Brazilian residue-standard requirements, creating divergent margin pools for formulation sophistication versus cost-optimized commodity supply.
For Market Incumbents: Extend precision-fermentation amino acid platforms into ruminant-specific protected formulations before synthetic methionine incumbents recover cost parity. Secure captive vitamin supply through backward integration into Shandong province fermentation partnerships, neutralizing single-source vulnerability that threatens European formulators. Channel control through direct-to-farm digital platforms in Argentina and Texas compresses distributor tiers and captures technical service premiums. For New Entrants and Emerging Players: EU Green Deal methane targets in Denmark and the Netherlands open a window for rumen-modifier premix specialists offering 3-NOP and essential oil formulations with full EFSA toxicological dossiers. Vietnam's state-backed dairy expansion to 1.5 million milking cows represents the most penetrable geography, with bundled total mixed ration consulting and micronutrient supply as the decisive go-to-market angle. Carbon-accounted premix certification unlocks price premiums in France's national low-carbon label procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders serving price-sensitive livestock farms in Southeast Asia and Latin America, where digital platform penetration remains under fifteen percent. Five-to-ten year viability hinges on biotechnology-enabled ingredient platform transitions that displace petrochemical-derived feedstock economics. Acquisition targets with precision-fermentation amino acid capabilities or rumen microbiome modeling talent pools offer asymmetric upside. The signal to watch is EFSA approval velocity for novel botanical additives, where extended timelines from eighteen to thirty-six months concentrate margin pools among dossier-capable specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Platform Expansion | DSM-Firmenich's amino acid investments compress synthetic incumbent margins across European dairy markets. |
| Carbon-Accounted Certification Development | France's national low-carbon label rewards suppliers documenting Scope 3 feed ingredient emissions. |
| Direct-to-Farm Digital Channel Buildout | Argentine feedlot operators in Buenos Aires province bypass traditional distributors through platform-based ordering. |
| Rumen Microbiome Modeling Capability Acquisition | Computational biology talent scarcity slows next-generation probiotic development cycles for premix houses. |
| Captive Vitamin Supply Chain Integration | Cargill leverages global grain origination networks to secure upstream control over micronutrient inputs. |
Research Methodology
Bottom-up dairy and beef operation modeling reconciled against top-down vitamin and amino acid production tracking forms the analytical core of this study. Primary interviews with premix formulation directors, procurement leads at integrated beef systems, veterinary nutrition consultants, and regulatory affairs specialists at EFSA and FDA were cross-validated against secondary sources including customs trade databases, feed industry association reports, SEC filings from listed agribusiness conglomerates, and national agricultural statistics from Brazil's IBGE and the United States Department of Agriculture.
Input-output matrix framing connects herd expansion projections in Vietnam and Brazil against fermentation capacity utilization rates in Shandong province and synthetic vitamin operating rates in Ludwigshafen. Segmentation dimensions span nutritional function, production system intensity, and procurement channel sophistication across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating methane mitigation policy stringency and precision nutrition adoption rates among 1,000-cow-plus facilities.
Revisions become necessary when EU Green Deal implementation timelines accelerate, Chinese environmental discharge enforcement tightens fermentation capacity expansion, or precision-fermentation amino acid costs achieve parity with extraction-based supply ahead of modeled trajectories. Deviation in B-vitamin fermentation concentration or rumen modifier regulatory approval velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Straw Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Europe Ruminant Feed Market