
 Bladderpod Oil Market | 2026-2036
Bladderpod Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Bladderpod Oil Market Analytics
Pharmaceutical-grade bladderpod oil specification is redrawing competitive boundaries in this niche seed oil segment. Agricultural Research Service anchors germplasm development through its Lesquerella breeding program in the southwestern United States. Standard Oil Company leverages its legacy refining infrastructure to process high-erucic acid feedstocks with minimal retooling. Mohawk Oil specializes in small-batch cold pressing for cosmetic clients demanding unrefined, high-mucilage product.
Bladderpod oil is a fixed vegetable oil extracted from Lesquerella fendleri seeds, containing approximately 55-60% lesquerolic acid, a hydroxylated C20:1 fatty acid functionally similar to castor oil's ricinoleic acid but with superior oxidative stability for lubricant and cosmetic applications. Cold pressed oil commands premium positioning in clean-label cosmetic formulations where minimal processing preserves native tocopherol profiles and phospholipid content. Refined oil dominates volume throughput in biofuel and industrial lubricant channels where color stability and low moisture specifications override trace nutrient retention. Fractionated oil represents the fastest-growing structural segment as molecular distillation enables separation of lesquerolic acid concentrates for pharmaceutical excipient and synthetic ester applications.
EPA biofuel pathway qualifications under the Renewable Fuel Standard govern market access for bladderpod-derived renewable diesel and sustainable aviation fuel feedstocks in the United States. FDA food-contact substance notifications and cosmetic ingredient safety assessments shape product liability exposure for suppliers targeting dual-use pharmaceutical and personal care applications. USDA germplasm collection protocols and Plant Variety Protection certificates influence intellectual property positioning for improved cultivars with elevated oil content or modified fatty acid profiles. Stakeholders must monitor how California's Department of Food and Agriculture native seed certification standards interact with emerging state-level biofuel procurement preferences to determine optimal vertical positioning between commodity crush and specialty refined product tiers.
Market Dynamics
California's native Lesquerella cultivation clusters are concentrating supply-side power among regional crush operators, while REACH compliance and biofuel blending mandates in North America and Europe are simultaneously tightening feedstock specifications and fragmenting demand channels across pharmaceutical, cosmetic, and industrial lubricant applications.
Growth Catalysts
- Specialty cosmetics procurement:Formulators are expanding cold-pressed bladderpod oil purchases for emollient applications where native tocopherol profiles command formulation premiums.
- EPA Renewable Fuel Standard:Biofuel pathway qualifications under this framework are opening renewable diesel and sustainable aviation fuel channels for lesquerolic acid feedstocks.
- Molecular distillation advances:Fractionation technology is enabling pharmaceutical-grade lesquerolic acid concentrates for synthetic ester and excipient manufacturing.
Market Restraints
- Native seed supply concentration:Germplasm development remains anchored to USDA Agricultural Research Service breeding programs in the southwestern United States, creating single-source genetic dependency.
- Castor oil substitution pressure:Established ricinoleic acid supply chains from India and Brazil compete on price for lubricant and cosmetic applications where oxidative stability differentials are undervalued.
- REACH registration costs:European chemical compliance requirements impose fixed cost burdens that disadvantage small-batch specialty oil processors relative to commodity refiners.
Strategic Opportunities
- Pharmaceutical excipient white space:Lesquerolic acid concentrates are penetrating synthetic ester applications where hydroxylated C20:1 fatty acids replace petrochemical-derived intermediates.
- California state biofuel procurement:Department of Food and Agriculture native seed certification standards are creating preferential sourcing channels for in-state renewable fuel producers.
- Clean-label cosmetic positioning:Unrefined cold-pressed oil is capturing formulation share among brands emphasizing minimal processing narratives and phospholipid retention.
Industry Challenges
- Germplasm intellectual property complexity:USDA Plant Variety Protection certificates and germplasm collection protocols create licensing friction for improved cultivars with modified fatty acid profiles.
- Dual-use compliance timelines:Suppliers targeting pharmaceutical and personal care applications face simultaneous FDA food-contact substance notifications and cosmetic ingredient safety assessments.
- Crush capacity reconfiguration:Legacy oilseed processing infrastructure requires retooling to handle high-mucilage Lesquerella fendleri feedstocks without yield loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bladderpod Oil Market |
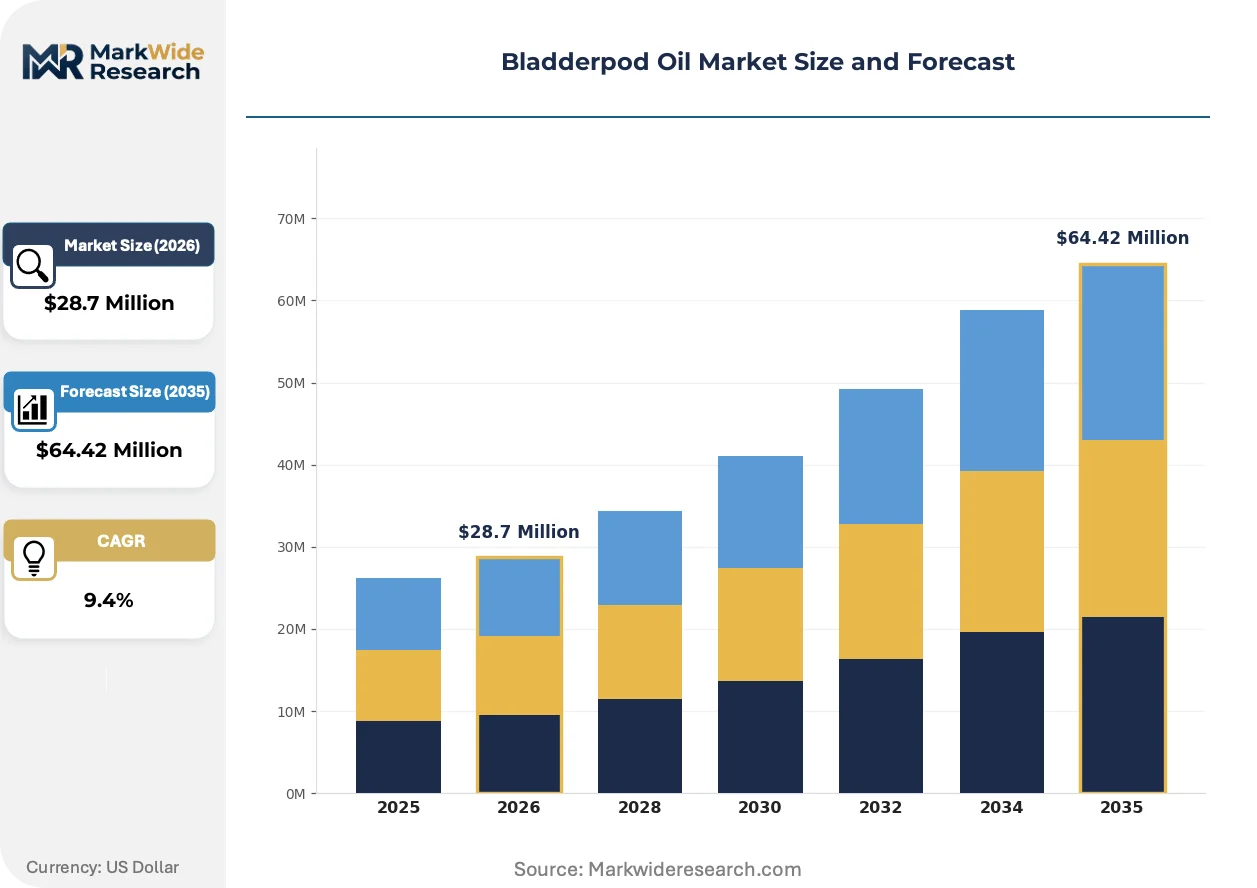
| Market Size in 2026 | $28.7 Million |
| Market Size in 2035 | $64.42 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed Oil, Refined Oil, Fractionated Oil, Culinary Oil End Use Industry: Cosmetics, Food & Beverage, Biofuel, Pharmaceuticals Distribution Channel: Online Retail, Wholesale, Direct Sales, Supermarkets Packaging Type: Bottles, Drums, Pouches, Tins |
| Companies Covered | Agricultural Research Service (ARS), Deep Market Insights, Center for Native Ecosystems, Colorado Natural Heritage Program, Standard Oil Company, Associated Oil, Fifty-Seven Petroleum, Mohawk Oil, Pacific Oil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bladderpod Oil Market Evolving Landscape
Processing technology and regulatory qualification requirements are actively segmenting the bladderpod oil value chain into distinct premium and commodity tiers, with molecular distillation capabilities and EPA biofuel certifications becoming the primary axes of competitive differentiation.
Molecular distillation equipment is bifurcating the refined oil segment into pharmaceutical-grade concentrate producers and commodity biofuel feedstock suppliers. Cosmetic formulators with captive fractionation capacity are securing lesquerolic acid supply directly from California crush operators, bypassing traditional refined oil merchants. This technology compression is forcing merchant refiners to choose between capital-intensive pharmaceutical qualification or volume-focused renewable diesel channels.
REACH compliance deadlines in Europe are accelerating substitution testing for hydroxylated fatty acids in industrial lubricant applications. ECHA registration requirements for novel vegetable oil feedstocks are diverting R&D investment toward toxicological dossier preparation rather than product formulation. German and French lubricant blenders are prioritizing suppliers with existing REACH dossiers, disadvantaging North American crush operators without European regulatory infrastructure.
Cosmetic procurement patterns are rotating toward direct-origin contracting with California Central Valley growers. Clean-label brands are eliminating intermediaries to secure cold-pressed oil with verifiable native seed provenance and harvest-date documentation. This channel disintermediation is compressing margins for traditional oil merchants while rewarding crush operators with in-house organic certification and small-batch processing capabilities.
Bladderpod Oil Market Segmentation
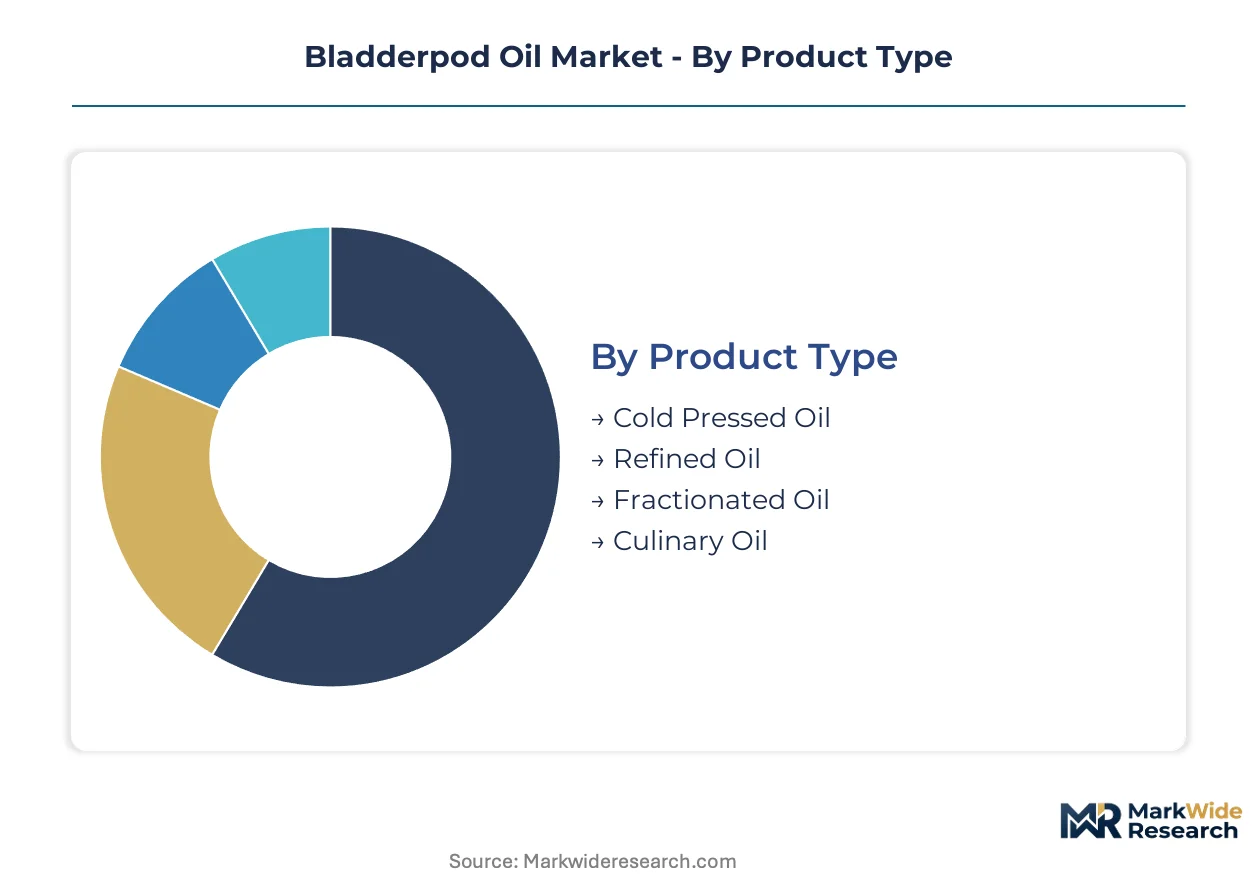
Bladderpod oil's functional versatility—spanning hydroxylated fatty acid chemistry for lubricants, emollient properties for cosmetics, and renewable diesel feedstock specifications—creates distinct demand profiles across processing tiers. Segmentation reveals how extraction method, end-use purity requirements, and channel economics partition value capture between commodity crush operators and specialty refiners.
Product Type:
Cold pressed oil anchors California's Central Valley export flows to European cosmetic formulators, while refined and fractionated grades serve domestic biofuel and pharmaceutical channels with divergent specification thresholds.
- Cold Pressed Oil:Unrefined extraction preserves native tocopherol profiles and phospholipid content for clean-label cosmetic formulations. Demand concentrates among California-based organic brands sourcing directly from Central Valley crush operators with harvest-date documentation capabilities.
- Refined Oil:Bleaching and deodorization strips color bodies and moisture to meet EPA biofuel pathway specifications for renewable diesel and sustainable aviation fuel. Volume throughput dominates this segment as North American refiners retool legacy infrastructure for high-erucic acid feedstocks.
- Fractionated Oil:Molecular distillation separates lesquerolic acid concentrates for pharmaceutical excipient manufacturing. German and French lubricant blenders prioritize suppliers with existing REACH dossiers, disadvantaging small-batch processors.
- Culinary Oil:Food-grade specifications remain nascent pending FDA food-contact substance notification clearances for Lesquerella fendleri derivatives.
Refined oil commands the established base. The steepest expansion runs through fractionated oil.
End Use Industry:
Margin structures diverge sharply between pharmaceutical-grade qualification requirements and commodity biofuel volume plays, with cosmetics occupying a mid-tier premium anchored to provenance verification.
- Cosmetics:Formulators expand cold-pressed procurement for emollient applications where oxidative stability advantages over castor oil justify formulation premiums. Direct-origin contracting with California growers eliminates traditional merchant intermediaries.
- Pharmaceuticals:Lesquerolic acid concentrates penetrate synthetic ester applications as hydroxylated C20:1 fatty acid replacements for petrochemical-derived intermediates. EMA qualification timelines and FDA dual-use assessments create compliance friction for suppliers.
- Biofuel:EPA Renewable Fuel Standard pathway qualifications govern market access for bladderpod-derived renewable diesel. California state procurement preferences for native seed certification create geographic sourcing advantages.
- Food & Beverage:Commercial traction awaits USDA GRAS determination and FSSAI import clearance for Indian market access.
Cosmetics anchors current revenue. Pharmaceuticals is gaining share fastest.
Distribution Channel:
Channel economics reflect the tension between small-batch specialty premiums and volume-driven biofuel procurement, with disintermediation compressing traditional merchant margins.
- Direct Sales:Cosmetic brands contract directly with California Central Valley crush operators for verifiable native seed provenance. This channel captures the highest margins through organic certification and small-batch processing premiums.
- Wholesale:Bulk refined oil moves through established oilseed merchants to North American biofuel refiners with EPA certification requirements. REACH registration costs disadvantage small-batch processors in European wholesale flows.
- Online Retail:Clean-label cosmetic brands leverage e-commerce for cold-pressed oil with harvest-date transparency and minimal processing narratives.
- Supermarkets:Limited penetration pending broader culinary oil regulatory clearances and consumer education on Lesquerella-derived products.
Wholesale commands the established base. Direct sales is climbing the fastest.
Packaging Type:
Packaging specifications track the downstream split between industrial bulk handling and consumer-facing premium positioning.
- Drums:Industrial-grade containment for refined biofuel feedstocks and pharmaceutical intermediate shipments. Standardized specifications align with oilseed commodity handling infrastructure.
- Bottles:Amber glass and UV-protective formats preserve tocopherol integrity for cold-pressed cosmetic oils. Premium positioning supports clean-label brand narratives.
- Pouches:Flexible formats for sample-size cosmetic and culinary oil distribution. Emerging adoption in direct-to-consumer subscription channels.
- Tins:Heritage positioning for specialty culinary and gift-market applications. Limited commercial scale.
Drums command the established base. Bottles is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of cold-pressed bladderpod oil concentrate in California's Central Valley, while refined grades circulate through domestic biofuel channels. Import dependence for pharmaceutical-grade concentrates shapes European procurement patterns.
United States
California's Central Valley anchors native Lesquerella cultivation clusters that supply regional crush capacity. EPA Renewable Fuel Standard pathway qualifications govern market access for renewable diesel and sustainable aviation fuel feedstocks. USDA Agricultural Research Service breeding programs in Arizona and New Mexico anchor germplasm development for improved oil content cultivars.
Germany
German lubricant blenders prioritize suppliers with existing REACH dossiers for hydroxylated fatty acid applications. ECHA registration requirements for novel vegetable oil feedstocks divert R&D investment toward toxicological dossier preparation. Industrial clusters in North Rhine-Westphalia concentrate formulation expertise for synthetic ester manufacturing.
France
French cosmetic formulators source cold-pressed oil through direct-origin contracting with California growers. ANSM cosmetic ingredient safety assessments shape product liability exposure for dual-use pharmaceutical applications. The Provence-Alpes-Côte d'Azur region hosts specialty oil distributors with clean-label brand relationships.
India
Indian castor oil processors compete on price for lubricant applications where oxidative stability differentials are undervalued. FSSAI import clearance for Lesquerella fendleri derivatives remains pending for culinary oil market access. Gujarat's established ricinoleic acid supply chains dominate regional hydroxylated fatty acid trade flows.
United Kingdom
UK cosmetic brands emphasize minimal processing narratives and phospholipid retention in procurement specifications. The country's national pharmaceutical regulator aligns with EMA qualification timelines for excipient applications. London-based specialty chemical traders broker pharmaceutical-grade concentrate shipments from North American fractionators.
Bladderpod Oil Market Competitive Landscape
Listed leaders compete with private specialists across regulatory qualification infrastructure, creating tiered access to pharmaceutical and biofuel channels. The market structure concentrates around USDA-affiliated germplasm developers, legacy petroleum refiners with high-erucic acid processing capabilities, and small-batch cold press operators. Three archetypes dominate: public research institutions controlling genetic intellectual property, diversified energy companies leveraging legacy refining assets, and boutique processors serving cosmetic clean-label demand. Competitive moves center on backward integration into captive cultivation and molecular distillation capacity expansion for pharmaceutical-grade concentrates.
Within the public research tier, Agricultural Research Service anchors germplasm development through its Lesquerella breeding program. Among legacy petroleum refiners, Standard Oil Company exemplifies players leveraging existing infrastructure for high-erucic acid feedstock processing. On the boutique specialty end, Mohawk Oil occupies a position serving cosmetic clients demanding unrefined, high-mucilage product with verifiable provenance documentation.
| Leading Market Players |
|---|
| Agricultural Research Service (ARS) |
| Deep Market Insights |
| Center for Native Ecosystems |
| Colorado Natural Heritage Program |
| Standard Oil Company |
| Associated Oil |
| Fifty-Seven Petroleum |
| Mohawk Oil |
| Pacific Oil |
| Others |
Value Network & Pricing Analysis
Castor oil substitution pressure from Indian and Brazilian ricinoleic acid suppliers simultaneously redraws supply geography toward established tropical oilseed corridors and compresses pricing premiums for oxidative stability claims in lubricant formulations. California crush operators respond by emphasizing native provenance certification and cold-press processing narratives that command formulation premiums from European cosmetic buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for refined biofuel feedstocks, while cosmetic formulators absorb premium-mid-economy pricing differentiation driven by organic certification tier and harvest-date documentation granularity. Price differentiation separates unrefined cold-pressed cosmetic grades from commodity refined channels. Cost compression in standard refined tiers intensifies as legacy petroleum refiners retool for high-erucic acid feedstocks without specialized Lesquerella handling experience. Biofuel blenders exhibit highest price sensitivity due to EPA pathway qualification compliance costs, whereas pharmaceutical excipient manufacturers demonstrate lowest sensitivity given lesquerolic acid concentrate scarcity.
Supply Chain Analysis
Inventory lead times stretch longest for pharmaceutical-grade fractionated concentrates requiring molecular distillation capacity and REACH dossier completion. Geographic supply concentration centers on the United States, Germany, and France, with California's Central Valley anchoring native seed cultivation. Raw material dependencies rest on USDA Agricultural Research Service germplasm collections, Arizona and New Mexico breeding program outputs, and European ECHA registration infrastructure. Single-source vulnerability permeates germplasm intellectual property controlled by federal research institutions. Distribution runs through direct-origin contracting for cosmetic channels and wholesale oilseed merchants for biofuel throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bladderpod oil functions as a platform where molecular distillation capabilities and EPA biofuel certifications create interoperability between pharmaceutical, cosmetic, and industrial demand channels. Ecosystem lock-in effects intensify as qualification timelines extend and captive fractionation capacity becomes the scarce resource.
For Market Incumbents: Consolidate backward integration into captive Lesquerella cultivation in California's Central Valley to secure native seed provenance documentation. Deepen molecular distillation capacity for pharmaceutical-grade concentrate production. Castor oil price competition from Indian processors threatens margin sustainability in standard lubricant applications. For New Entrants and Emerging Players: Anchor in pharmaceutical excipient manufacturing where lesquerolic acid concentrate scarcity supports premium positioning. Target synthetic ester applications replacing petrochemical-derived intermediates. Pursue direct-origin contracting relationships with California organic crush operators bypassing traditional merchant intermediaries. For Investors and Strategic Acquirers: The market sits at a qualification-infrastructure buildout phase that favors fractionation technology owners and REACH-registered suppliers. Five-to-ten year viability hinges on EPA pathway certification permanence and EMA excipient qualification acceleration. Monitor California Department of Food and Agriculture native seed certification standard adoption rates as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive Lesquerella supply secures California native seed certification for state biofuel procurement preferences. |
| Molecular Distillation Capacity Expansion | Pharmaceutical-grade lesquerolic acid concentrate production opens synthetic ester and excipient manufacturing channels. |
| REACH Dossier Completion | ECHA registration enables German and French lubricant blender supplier qualification for hydroxylated fatty acid applications. |
| Direct-Origin Contracting Infrastructure | Harvest-date documentation capabilities capture cosmetic formulator premiums for clean-label minimal processing narratives. |
| EPA Pathway Certification Investment | Renewable Fuel Standard qualification governs renewable diesel and sustainable aviation fuel feedstock market access. |
Research Methodology
Initial hypotheses were tested against primary input from crush facility operators, cosmetic formulation chemists, biofuel refinery procurement managers, and pharmaceutical excipient manufacturers and refined through secondary validation. Crush facility operators provided operational data on high-mucilage feedstock handling yields. Cosmetic formulation chemists detailed tocopherol profile specifications and phospholipid retention requirements. Biofuel refinery procurement managers clarified EPA pathway qualification timelines and feedstock specification thresholds. Pharmaceutical excipient manufacturers outlined EMA qualification friction points and synthetic ester substitution economics. Secondary sources included USDA germplasm collection protocols, EPA Renewable Fuel Standard pathway documentation, ECHA REACH registration databases, and California Department of Food and Agriculture native seed certification standards. Bottom-up volume estimates from regional crush capacity and top-down demand segmentation from end-use industry consumption patterns were triangulated for convergence.
Variance decomposition across the projection horizon isolates contribution from extraction method tier shifts, end-use industry mix evolution, and geographic regulatory cluster adoption timing. Segmentation dimensions modeled encompass product type, end-use industry, distribution channel, and packaging format alongside regional production hub qualification status. CAGRs were derived from segment-level volume trajectories weighted by price realization differentials. Industry-specific forecast inputs include EPA biofuel pathway approval velocity, EMA excipient qualification pipeline depth, and California native seed certification program enrollment rates.
Material uncertainties — germplasm intellectual property licensing friction, REACH registration cost escalation, and castor oil price volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory timeline stability and substitution elasticity in lubricant applications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market