
 Cattle Feed Market | 2026-2036
Cattle Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Feed Market Intelligence
The FAMI-QS certification requirement is unwinding the historical dominance of smaller, uncertified feed producers in the supply chain. This quality and safety standard creates a barrier to entry, favoring large-scale operators with documented control systems. Cargill leverages its global sourcing network to manage input cost volatility. Archer Daniels Midland sustains its market position through extensive R&D in feed additives and nutritional supplements. New Hope Group competes on production scale, primarily serving Asian markets.
Cattle feed consists of specially formulated nutritional products designed to provide a complete diet or supplement grazing for bovine animals. These formulations are balanced for specific levels of crude protein, metabolizable energy, and fiber to support either lactation in dairy cows or weight gain in beef cattle. Concentrated feeds represent the largest product segment by volume, used extensively in feedlots. The complete feed category, however, offers higher margin potential, particularly for high-producing dairy farms and specialized beef producers demanding precise nutritional delivery.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) governs feed content and safety. These agencies enforce strict limits on contaminants, antibiotics, and growth promoters, directly shaping product development and market access. In Brazil, regulations from the Ministry of Agriculture focus on traceability and disease prevention within the cattle supply chain. Navigating divergent regional standards on genetically modified ingredients and novel additives remains a critical challenge for producers.
Market Dynamics
The central dynamic in the cattle feed market is the structural tension between sustainability mandates, such as the EU Green Deal, and the persistent volatility of core commodity inputs. This forces producers to innovate for efficiency while managing intense cost pressures.
Growth Catalysts
- Brazilian Beef Exports:Brazil's expanding beef export industry creates sustained demand for high-performance feed formulations designed to optimize weight gain and meet the standards of international buyers.
- Dairy Farm Optimization:The dairy sector's focus on nutritional science to boost milk yield and component quality drives adoption of specialized complete feeds and supplements, particularly on large-scale farms.
- EU Green Deal:Sustainability targets within the EU Green Deal encourage the development of advanced feeds that can reduce methane emissions and improve nutrient digestibility, creating a new value-added segment.
Market Restraints
- Input Cost Volatility:Fluctuations in the global prices of key ingredients like corn, soy, and wheat directly impact feed production costs, creating margin pressure for producers and price uncertainty for farmers.
- Regulatory Divergence:Conflicting regulations on genetically modified organisms, exemplified by stricter EFSA standards in Europe versus FDA policies in the US, create trade barriers and complicate global formulation strategies.
- Supply Chain Consolidation:The FAMI-QS certification mandate is displacing smaller, uncertified producers, which concentrates the supply base but can limit sourcing options and increase logistics costs for some buyers.
Strategic Opportunities
- Novel Additives:There is significant opportunity in developing and marketing novel feed additives, such as methane-inhibiting supplements, that help livestock producers meet environmental targets and command premium pricing.
- Southeast Asian Expansion:Underpenetrated markets in Southeast Asia, where dairy and beef production are modernizing, present a major growth area for suppliers of nutritionally balanced, high-quality feed products.
- Specialized Feed Lines:Formulating feeds for niche, high-value segments like organic, non-GMO, or grass-fed finishing programs allows producers to capture higher margins and serve specific consumer-driven markets.
Industry Challenges
- Multi-Jurisdictional Compliance:Navigating the complex and often lengthy approval processes for new feed ingredients across different regulatory bodies like the FDA, EFSA, and ANVISA in Brazil is a significant operational burden.
- Traceability Implementation:The capital and operational expense of establishing robust, end-to-end traceability systems for feed ingredients is a major hurdle, though increasingly necessary to meet food safety regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Feed Market |
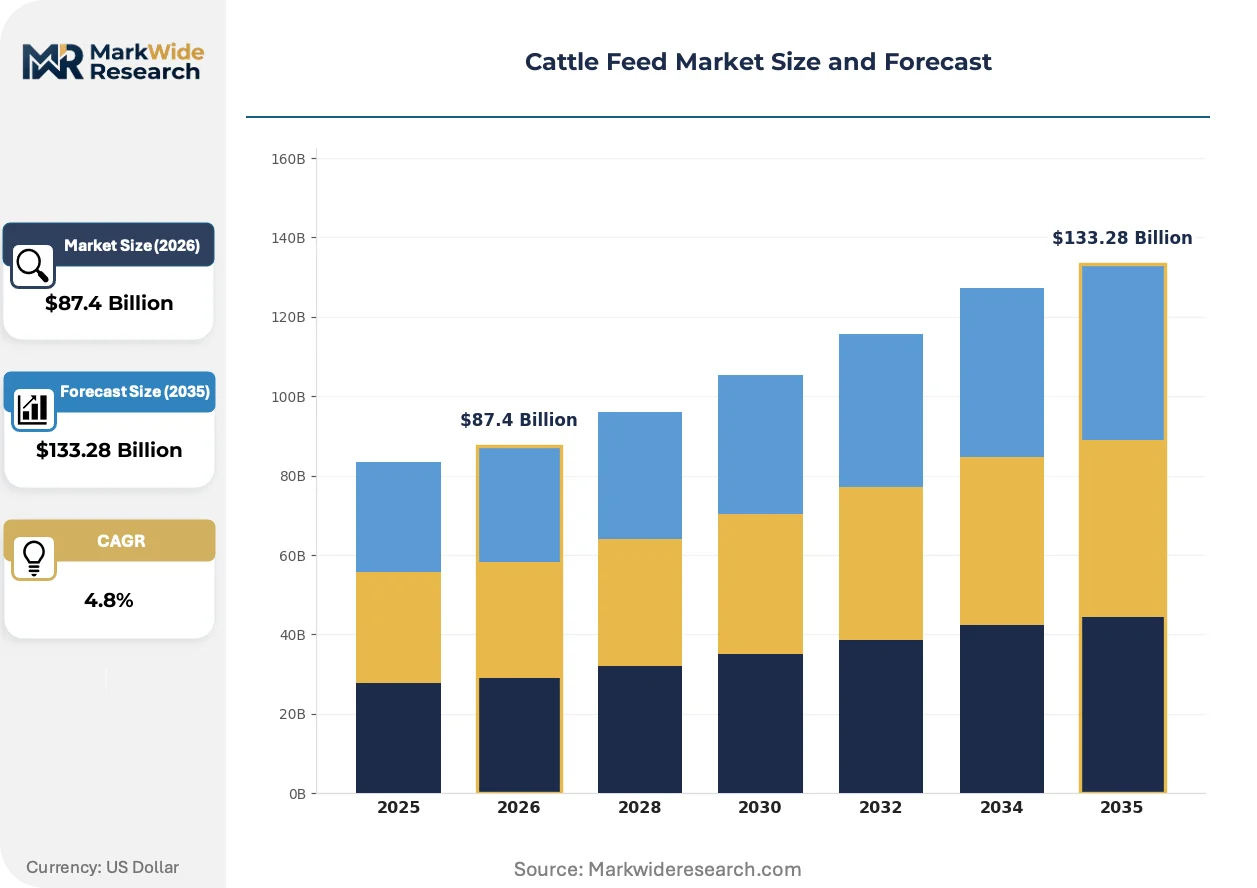
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Feed, Silage, By-Product Meals, Complete Feed Ingredient Type: Grains, Protein Meals, Additives, Minerals End User: Dairy Farms, Beef Producers, Feedlots, Retailers Distribution Channel: Wholesale, Online, Direct Sales, Brokers |
| Companies Covered | ForFarmers, New Hope Group, Cargill, Muyuan Foodstuff, Haid Group, Archer Daniels Midland, De Heus, CP Group, Land O'Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Feed Market Strategic Shifts & Innovations
Precision nutrition, driven by digital farm management platforms and advanced sensor technology, is becoming a primary focus. This trend links feed formulation directly to animal performance metrics, shifting the value proposition from simple volume to documented, outcome-based nutritional efficiency.
Precision feeding systems, which utilize data analytics to create and deliver customized rations for individual animals, are a key technological evolution. High-producing dairy operations and large-scale beef feedlots are steadily adopting these systems to optimize feed conversion ratios and monitor animal health in real time. This technology is displacing conventional bulk feeding methods, creating demand for feed products designed for automated and data-integrated delivery.
The EU Green Deal and its Farm to Fork Strategy are imposing new requirements on the agricultural sector to reduce its environmental footprint. This directly influences feed formulation, pushing for ingredients that lower methane and nitrogen excretion from cattle. Dairy and beef producers in Europe are most affected, actively seeking certified feeds that help them comply with national emissions targets and sustainability reporting.
A clear shift in purchasing behavior is the growing preference for feeds sourced from FAMI-QS certified suppliers, especially among large-scale, export-oriented livestock operations. This certification-driven requirement is disrupting traditional supply channels by favoring large, compliant manufacturers over smaller, local producers who lack the necessary quality management systems. This trend is most visible in regions like Brazil and the EU, where proof of safety standards is critical for market access.
Cattle Feed Market Segmentation
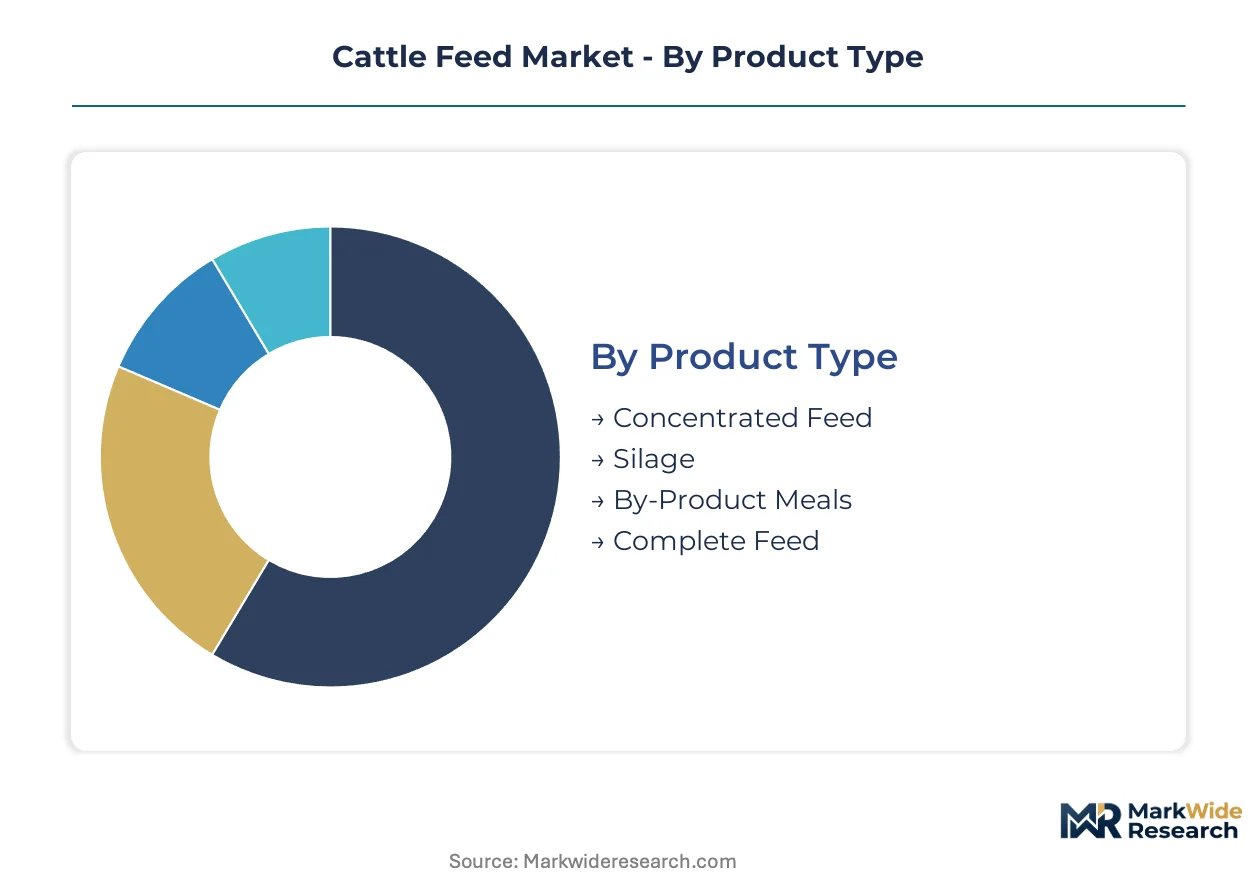
Segmentation provides a granular understanding of the cattle feed market's intricate structure, revealing how diverse product types, ingredient compositions, end-user demands, and distribution channels shape competitive dynamics. This analysis helps stakeholders identify key value pools and strategic entry points within the bovine nutrition industry.
Product Type:
Segments within product type face varying substitution pressures from alternative feed sources and on-farm forage.
- Complete Feed:These formulations provide all necessary nutrients for a balanced diet, minimizing the need for additional supplements. Demand concentrates in high-producing dairy farms across Europe, driven by EU Green Deal sustainability targets for reduced methane emissions.
- Concentrated Feed:High-energy, nutrient-dense products, often grain-based, are designed to boost weight gain and milk production efficiently. Feedlots in Brazil primarily utilize concentrated feeds to optimize beef export quality and meet international market specifications.
- Silage:Fermented forage, typically corn or grass, serves as a cost-effective bulk feed, providing fiber and energy.
- By-Product Meals:Repurposed industrial waste, such as distillers' grains or oilseed meals, offers protein and fiber content to feed formulations.
Concentrated Feed retains volume leadership; Complete Feed holds the steepest expansion curve.
Ingredient Type:
The ingredient type segmentation highlights distinct cost structures and supply chain vulnerabilities for feed manufacturers.
- Grains:Primary energy sources like corn and wheat form the bulk of many feed formulations, subject to global commodity price volatility. Large-scale producers such as Cargill manage grain sourcing through extensive global networks for cost stability.
- Additives:Specialized compounds including enzymes, amino acids, and methane inhibitors enhance feed efficiency or animal health. Archer Daniels Midland invests heavily in research and development for novel additives to meet evolving sustainability mandates.
- Protein Meals:Soybean meal, canola meal, and sunflower meal provide essential amino acids crucial for animal growth and milk synthesis.
- Minerals:Essential trace elements and macro-minerals support bone health, immune function, and various metabolic processes in cattle.
Grains dominate the raw material input by volume, while specialized Additives command premium pricing.
End User:
This segmentation reflects differing nutritional requirements and purchasing behaviors across various livestock production systems.
- Dairy Farms:Require feeds optimized for milk production, reproductive health, and herd longevity, often utilizing advanced nutritional programs. Large-scale dairy operations in the United States increasingly adopt complete feeds for herd optimization.
- Beef Producers:Focus on formulations for efficient weight gain and meat quality, especially for export markets requiring specific carcass characteristics. Brazilian beef producers demand high-performance feeds to meet stringent international buyer specifications.
- Feedlots:Large commercial operations intensively feed cattle for rapid fattening prior to slaughter, prioritizing energy-dense and cost-effective rations.
- Retailers:Offer packaged feed products to smaller farms, hobbyists, and backyard livestock owners, emphasizing convenience and accessibility.
Dairy Farms are driving demand for specialized formulations, while Feedlots consume the largest feed volumes.
Distribution Channel:
The distribution channel segmentation reveals the varied pathways through which cattle feed reaches end-users, influencing market access and pricing strategies.
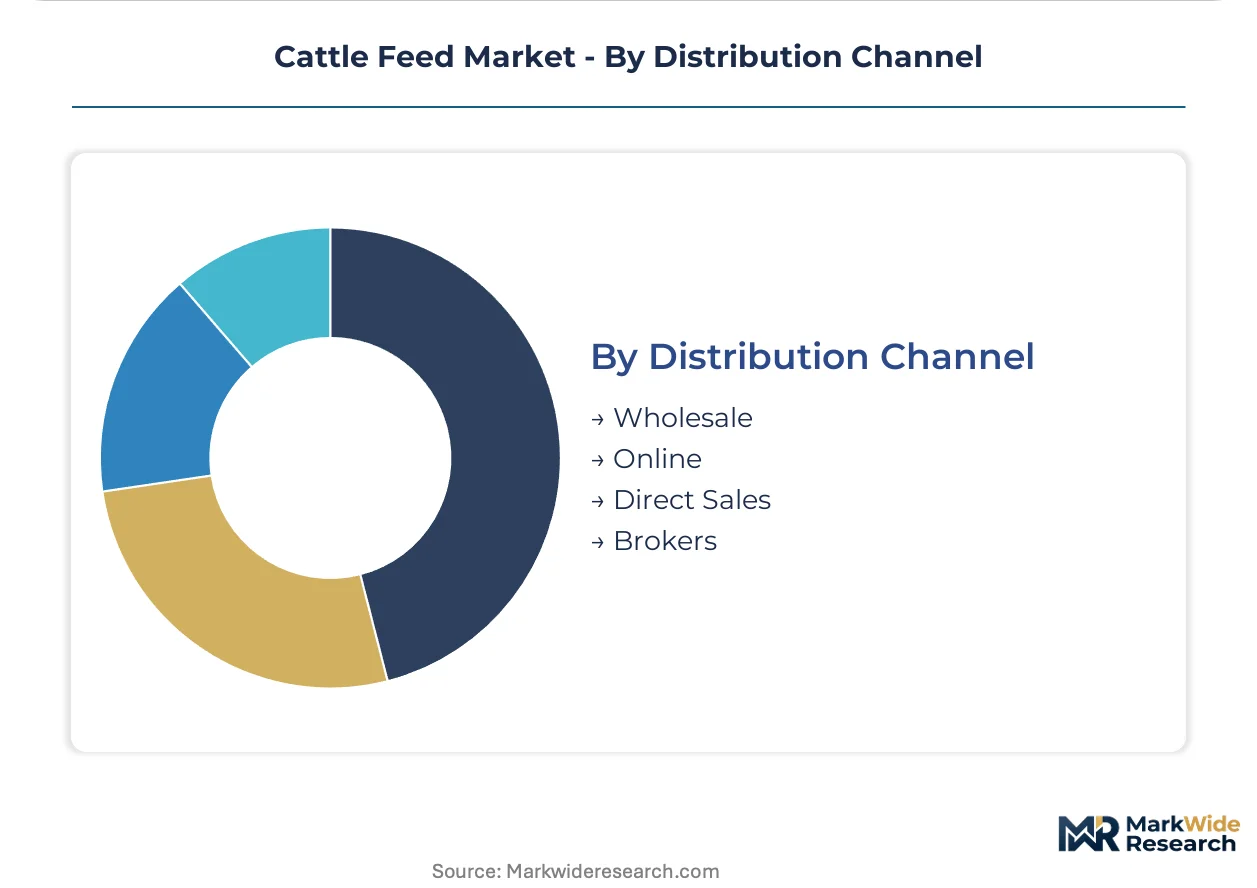
- Wholesale:Large volumes of feed are sold to cooperatives, large commercial farms, and feedlots, often accompanied by bulk discounts. This channel dominates in regions with consolidated agricultural industries, such as the US Midwest.
- Direct Sales:Manufacturers sell directly to farmers, allowing for customized feed programs, technical support, and strong customer relationships. This approach is particularly effective for specialized feed lines and premium products.
- Online:E-commerce platforms facilitate feed purchases, offering convenience and broader product selection for smaller orders and niche feed products.
- Brokers:Intermediaries connect feed producers with buyers, often specializing in commodity ingredients or facilitating transactions across specific regions.
Wholesale channels account for the majority of feed volume, while Direct Sales offer higher margins through tailored services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's expanding beef export industry concentrates significant demand for high-performance cattle feed. Large-scale dairy farms in regions like the United States and Europe also represent substantial buyer archetypes, focusing on nutritional optimization for milk yield. This global market reflects diverse regional priorities in livestock production.
Brazil
Brazilian beef producers require high-performance feed formulations to optimize weight gain and meet international market specifications for exports. Regulations from the Ministry of Agriculture (MAPA) enforce strict traceability and disease prevention within the cattle supply chain. The state of Mato Grosso, a major cattle-producing region, sees intensive utilization of concentrated feeds for large-scale feedlot operations.
United States
Large-scale dairy operations in the United States drive demand for complete feeds optimized for milk production and herd longevity. The US Food and Drug Administration (FDA) sets standards for feed content and safety, influencing product development. Midwest agricultural hubs, particularly in states like Nebraska, concentrate extensive feedlot operations requiring cost-effective, energy-dense rations.
Germany
German dairy farms prioritize advanced feeds that reduce methane emissions and improve nutrient digestibility, aligning with EU Green Deal targets. The European Food Safety Authority (EFSA) enforces strict limits on contaminants and growth promoters in feed formulations. Agricultural regions in Bavaria and Lower Saxony are increasingly adopting specialized complete feeds to meet national emissions targets.
China
China's modernizing dairy and beef production sectors create demand for nutritionally balanced, high-quality feed products. The State Administration for Market Regulation (SAMR) oversees feed quality and safety standards across the country. Provinces like Heilongjiang, a key agricultural area, are witnessing growth in large-scale livestock operations requiring specialized feed solutions.
Cattle Feed Market Key Industry Players
Player mix skews toward large, globally integrated operators capable of meeting stringent quality standards. The FAMI-QS certification mandate has created a barrier to entry, consolidating the supply base and favoring producers with documented control systems. Strategic archetypes include global sourcing and logistics specialists, R&D-intensive additive developers, and scale-focused regional manufacturers. Key competitive moves involve extensive R&D investments in nutritional science and the strategic management of global commodity input costs.
Global integrators like Cargill exemplify robust supply chain management, leveraging extensive networks to mitigate input cost volatility. Archer Daniels Midland, a prominent US-based company, occupies a position focused on advanced research and development for novel feed additives and nutritional supplements. New Hope Group, a China-based enterprise, represents a scale-driven production model primarily serving extensive Asian markets. These entities anchor distinct strategic approaches within the cattle feed industry.
| Leading Market Players |
|---|
| ForFarmers |
| New Hope Group |
| Cargill |
| Muyuan Foodstuff |
| Haid Group |
| Archer Daniels Midland |
| De Heus |
| CP Group |
| Land O'Lakes |
Cost & Logistics Intelligence
Large-scale feed production facilities achieve significant scale economies, which directly shapes supply concentration and establishes competitive price floors across the cattle feed market.
Pricing Analysis
Cost-plus contract pricing, often indexed to global corn and soy futures, dominates the cattle feed market. Price differentiation stems from FAMI-QS certification levels and the precision of customized nutritional programs. Pricing pressure stems from the persistent volatility of key commodity inputs like grains and protein meals. Small, uncertified local producers exhibit the highest price sensitivity, while large-scale dairy farms and feedlots prioritize performance and nutritional precision over absolute lowest cost.
Supply Chain Analysis
Inbound logistics costs, particularly for global grain shipments, significantly influence cattle feed supply chain efficiency. Geographic supply concentration for demand centers in Brazil, the United States, and the European Union, while raw materials are globally sourced. The supply chain relies heavily on corn, soybean meal, and specialized additives. Commodity price volatility for these agricultural inputs represents a primary structural risk. Distribution runs through wholesale channels, serving large commercial farms and feedlots directly.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cattle feed market is experiencing a platform-economics inflection, driven by the integration of precision nutrition with digital farm management ecosystems.
For Market Incumbents: Compound investments in advanced R&D for novel additives to mitigate methane emissions, addressing EU Green Deal regulatory shifts. Deepen backward integration into raw material sourcing through long-term contracts and strategic partnerships, buffering against input cost volatility. Expand FAMI-QS certified production capacity to reinforce barriers to entry against smaller, uncertified competitors. Control distribution channels to ensure technical support for complex feed formulations.
For New Entrants and Emerging Players: Anchor in underpenetrated Southeast Asian markets by offering FAMI-QS certified, nutritionally balanced feed products for modernizing dairy and beef operations. Target niche, high-value segments such as organic or non-GMO certified cattle feeds, leveraging consumer-driven demand. Implement a direct sales model bundled with technical advisory services to build strong customer relationships in these specialized segments. Focus on digital integration for precision feeding systems.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized additive developers and precision feeding system providers, offering long-term viability within the cattle feed market. Target R&D-intensive companies with proven intellectual property in feed efficiency or environmental impact reduction. Acquisition profiles should prioritize firms with robust data analytics capabilities for animal performance monitoring. The signal to watch is the widespread adoption of methane-inhibiting feed supplements by major livestock producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Methane-Inhibiting Additives | Addresses EU Green Deal mandates and creates a premium product segment for compliant producers. |
| Expand FAMI-QS Certified Production Capacity | Meets rising demand from export-oriented livestock operations and reinforces market access barriers. |
| Develop Precision Feeding Software Solutions | Integrates feed formulation with real-time animal performance data, optimizing feed conversion ratios. |
| Secure Long-Term Commodity Sourcing Contracts | Mitigates input cost volatility for key ingredients like corn and soy, stabilizing production margins. |
| Target Southeast Asian Market Entry | Captures growth from modernizing dairy and beef sectors in regions with increasing protein demand. |
Research Approach
The analysis maps cattle feed product types, ingredient compositions, and end-user segments, each validated through extensive primary interviews with industry stakeholders. Researchers engaged with feed manufacturers, large-scale dairy farm managers, feedlot operators, and regulatory affairs specialists. Secondary validation utilized FDA and EFSA regulatory documents, USDA and MAPA agricultural reports, and company financial filings. The approach employed both bottom-up market sizing and top-down triangulation for data accuracy.
Forecast outputs were consistently cross-referenced against external industry benchmarks and historical growth patterns across the analysis window. The analytical framework modeled market segmentation by product type, ingredient type, end-user, distribution channel, and regional demand. Compound annual growth rates were derived from a model integrating historical trends and future projections. Key forecast inputs included livestock population growth and per-animal feed consumption rates.
Decision-makers should treat outputs as directional under base assumptions regarding commodity price stability and regulatory enforcement; material deviation would warrant model refresh. Unforeseen global trade disputes or rapid shifts in sustainability mandates represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Peat Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Feed Sucrose Market