
 Sod Peat Market | 2026-2036
Sod Peat Market Size, Share, and Industry Trends Forecast 2026-2036
Sod Peat Market Insights
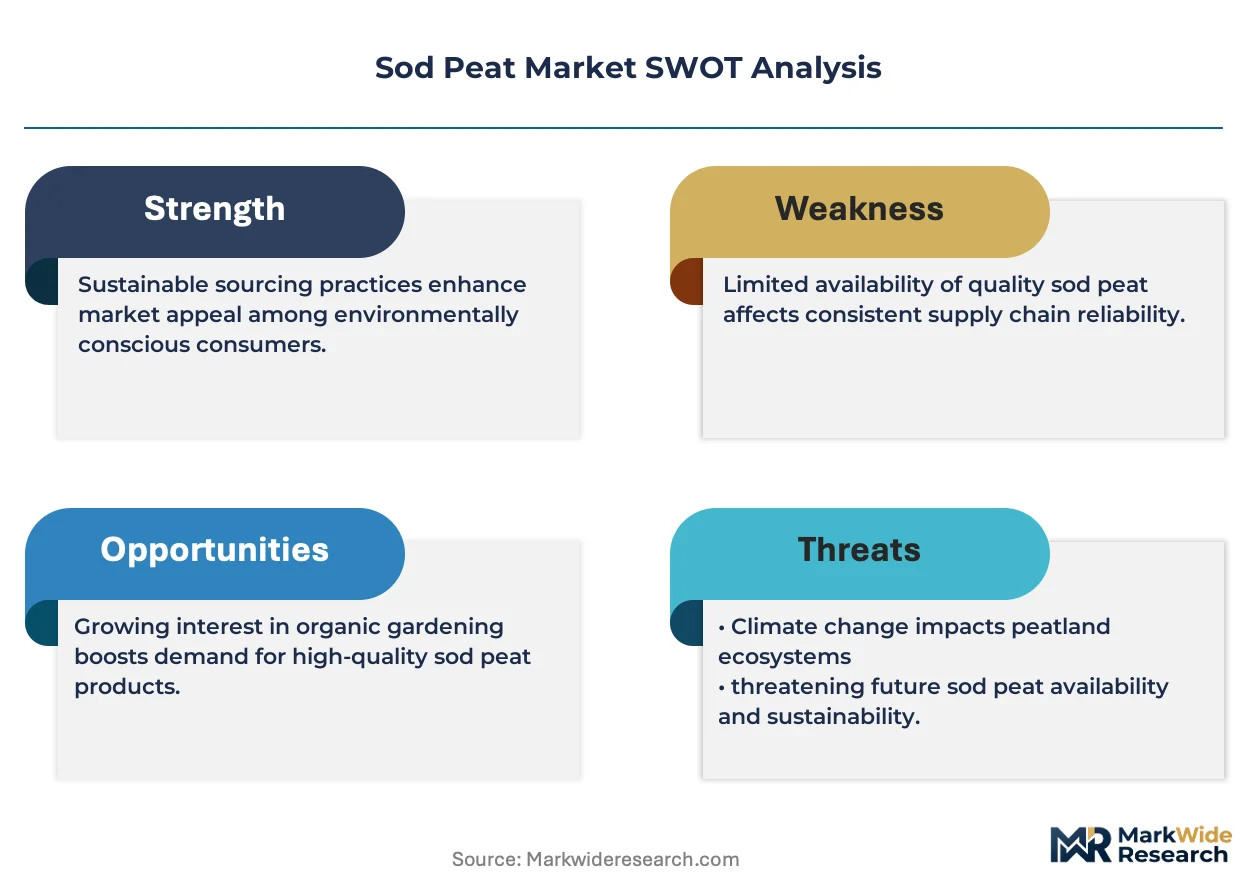
Finnish extraction permit approvals is hardening as MEE wetland conservation rules tighten operational scope for domestic producers. Vapo Oy leverages its integrated harvesting and processing footprint across Finnish bogs to sustain volume leadership in Nordic markets. Bord na Mona anchors Ireland's supply base through state-vested peatland concessions, while Neova Oy competes via specialized fuel-grade and horticultural peat streams across the Baltic rim.
Sod peat consists of partially decomposed sphagnum moss and organic matter harvested from surface wetland deposits, typically compressed into rectangular sods with moisture content between 40-60 percent for combustion or soil amendment applications. Its primary commercial purpose centers on energy generation in district heating plants and as a structured growing medium in professional horticulture. Natural peat dominates product type revenue due to established combustion infrastructure across Northern Europe, while horticulture leads application demand as commercial growers in the Netherlands and Germany prioritize consistent substrate porosity. Enhanced peat variants represent the fastest-growing product segment, commanding margin premiums through integrated fertilizer coatings and pH buffering.
Finland's MEE wetland protection directives, Estonia's Water Act extraction licensing, and the EU Green Deal sustainable carbon management frameworks collectively constrain new bog access while redirecting volumes toward certified horticultural grades. These regulations reshape competitive positioning by favoring operators with legacy concession rights and compliance infrastructure over new market entrants. Stakeholders must monitor peatland restoration bond requirements and carbon accounting methodologies to assess long-term asset viability.
Market Dynamics
Finland's MEE wetland protection directives are compressing extraction permits while Estonia's Water Act licensing redirects harvest volumes toward certified horticultural grades, reshaping competitive access across the Baltic rim.
Growth Catalysts
- Horticulture substrate standardization:Commercial greenhouse operators in the Netherlands demand consistent porosity specifications for sphagnum-based growing media, pulling volume toward certified organic grades.
- District heating infrastructure:Municipal energy plants across the Baltic states maintain combustion capacity for sod peat briquettes, sustaining baseline offtake despite carbon accounting pressures.
- Mechanized harvesting diffusion:Estonian extraction operations deploy automated cutting and compression equipment, lowering unit labor costs and expanding exportable surplus.
Market Restraints
- Input access contraction:Finland's MEE wetland conservation rules reduce permitted bog surface area, forcing domestic processors to source raw peat across the Gulf of Finland.
- Substitution by biomass pellets:Wood fiber briquettes from Latvian sawmills displace sod peat in district heating feedstock blends, compressing energy-grade pricing power.
- Carbon border leakage:EU Green Deal sustainable carbon management frameworks impose embedded emissions tracking on imported substrates, complicating cross-border horticultural trade.
Strategic Opportunities
- Enhanced peat formulation:Integrated fertilizer coating and pH buffering technologies command margin premiums in professional greenhouse supply chains.
- Restoration bond arbitrage:Operators with legacy concession rights in Ireland's midlands leverage Bord na Mona state-vested peatland access ahead of rewetting mandates.
- Direct-to-grower channels:Bypassing wholesale distributors, Estonian harvesters establish containerized shipping relationships with German commercial nursery clusters.
Industry Challenges
- Peatland ecology expertise gap:Wetland hydrology and carbon stock assessment skills are scarce among extraction workforce, slowing compliance documentation for permit renewals.
- Legacy combustion plant retrofit costs:District heating facilities require particulate filtration upgrades to meet EU F-Gas Regulation-equivalent emission thresholds for solid biofuel firing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sod Peat Market |
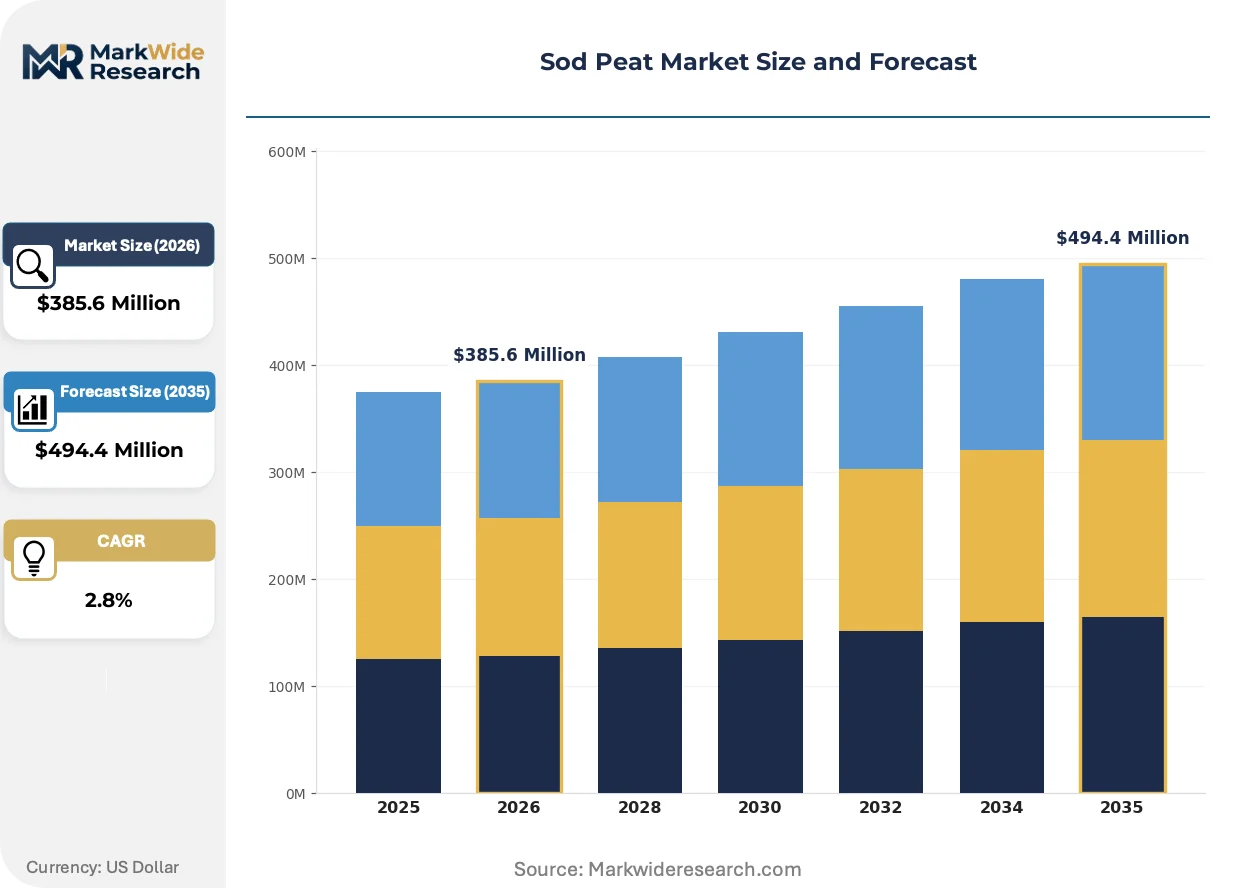
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $494.4 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Peat, Artificial Peat, Organic Peat, Enhanced Peat Application: Horticulture, Landscaping, Sports Turf, Erosion Control Distribution Channel: Online Retail, Garden Centers, Wholesale Suppliers, Specialty Stores End User: Commercial Growers, Home Gardeners, Landscape Contractors, Golf Courses |
| Companies Covered | Premier Tech, Klasmann-Deilmann, Sun Gro Horticulture, Bord na Mona, Lambert Peat Moss, Vapo Oy, Jiffy Products, Neova Oy, AS Tootsi Turvas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sod Peat Market Trends and Innovations
Processing technology and regulatory carbon accounting are converging to compress the distinction between fuel-grade and horticultural peat streams, forcing operators to choose specialization or integrated diversification.
Automated optical sorting is unifying quality grading across previously separate harvest batches. Estonian processors deploy near-infrared moisture and organic content scanners to standardize sod peat compression parameters. Commercial greenhouse buyers in Germany now accept machine-graded substrate blocks that previously required manual inspection, compressing procurement cycle times.
EU Green Deal sustainable carbon management frameworks are tightening embedded emissions disclosure for organic soil amendments. Horticultural peat importers into the Netherlands must document wetland drainage history and restoration bonding. Certified organic grades now carry blockchain-tracked provenance credentials, displacing undocumented Baltic volumes from premium supply chains.
Containerized bulk shipping is displacing traditional break-bag distribution for professional growers. German nursery clusters now procure full-container loads directly from Estonian extraction sites, bypassing Rotterdam wholesale handlers. This channel compression is visible across the Rhine-Ruhr greenhouse belt, where logistics cost savings fund on-site substrate storage infrastructure.
Sod Peat Market Segmentation
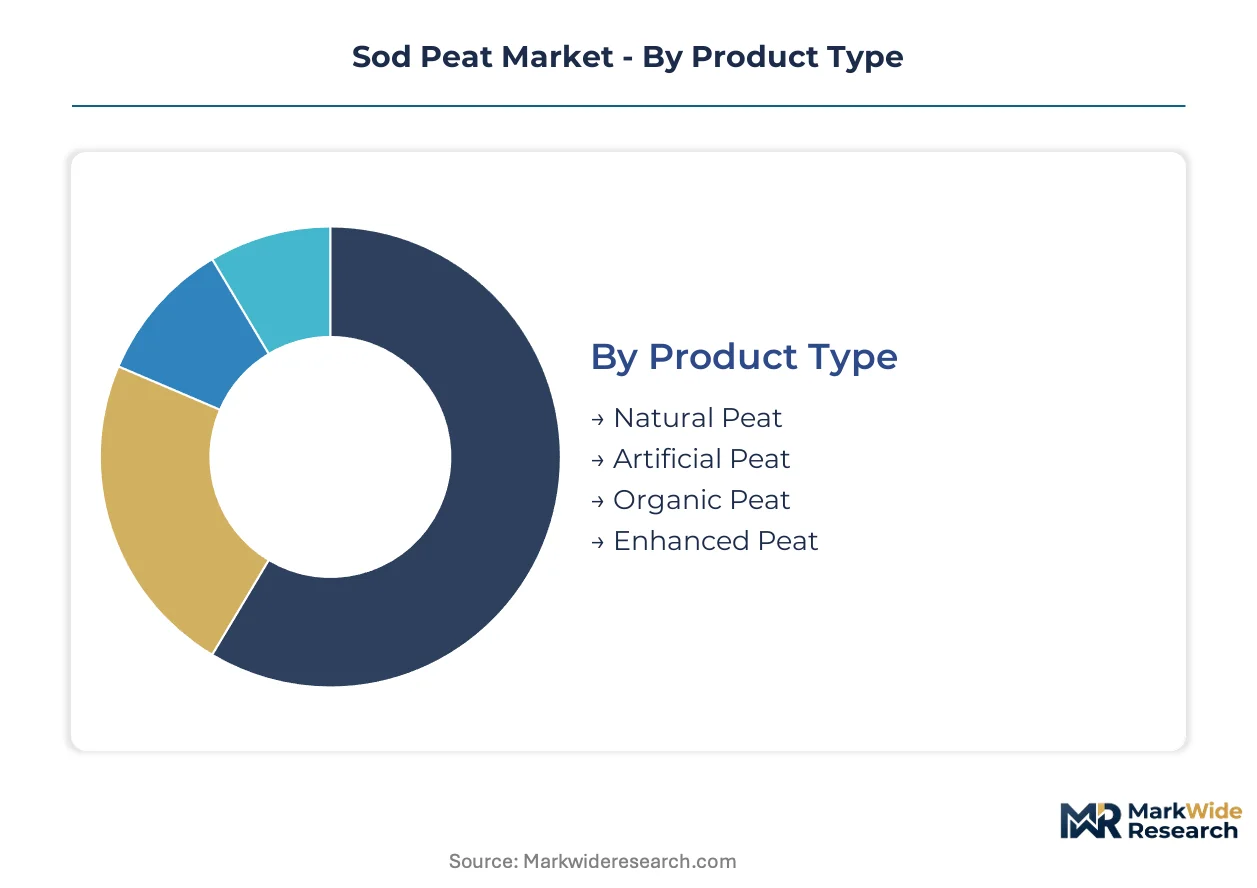
Sod peat segmentation reveals how extraction economics, regulatory pressure, and end-use specifications fragment supply chains across Northern Europe. Product type and application tiers diverge sharply on carbon accounting rules and margin structure, while channel and user segments reflect procurement professionalization in horticulture versus price sensitivity in consumer markets.
Product Type:
Volume leadership sits with legacy combustion grades, while premium positioning concentrates in certified horticultural streams with embedded fertilizer and pH management.
- Natural Peat:Raw sphagnum moss and partially decomposed organic matter harvested from surface wetland deposits, typically field-dried to 40-60% moisture for direct combustion or basic soil amendment. District heating plants across Estonia and Latvia anchor offtake volumes, though EU Green Deal carbon accounting pressures compress long-term contract renewals.
- Enhanced Peat:Compression-stage integration of controlled-release fertilizer coatings, limestone pH buffers, and wetting agents creates standardized growing media for commercial greenhouse operators. Professional horticulture clusters in the Netherlands and Germany pay margin premiums for batch-consistent porosity specifications that reduce transplant mortality rates.
- Artificial Peat:Manufactured substrate blends using composted bark, coir, and wood fiber as peat alternatives, formulated to mimic water retention and aeration properties. German and Danish regulators drive substitution mandates in public procurement contracts.
- Organic Peat:Certified extraction from designated wetland sites with documented restoration bonding and drainage history tracking. Dutch import protocols under EU Green Deal frameworks require blockchain-verified provenance for premium supply chain access.
Today's leader: Natural Peat. Tomorrow's challenger: Enhanced Peat.
Application:
Professional cultivation demands precision-engineered substrates, while recreational and infrastructure applications tolerate higher variability in organic content and compression density.
- Horticulture:Commercial greenhouse propagation and container nursery production require consistent air-filled porosity and cation exchange capacity. Dutch glasshouse operators specify sphagnum-based grades for tomato and ornamental seedling programs, with direct containerized procurement from Estonian extraction sites displacing Rotterdam wholesale intermediaries.
- Landscaping:Large-scale soil amendment for urban parks, highway verges, and reclamation projects prioritizes volume pricing over substrate precision. Irish midlands extraction through Bord na Mona state concessions supplies bulk volumes for British municipal contracts.
- Sports Turf:Golf course construction and professional pitch renovation demand specific particle size distribution for root zone drainage. German golf federations increasingly specify certified organic grades with documented restoration bonds.
- Erosion Control:Hydroseeding and slope stabilization applications use lower-grade peat as organic binder in fiber-matrix applications. Baltic coastal protection programs in Latvia and Lithuania sustain baseline offtake.
Horticulture commands absolute revenue share, yet sports turf specifications are climbing fastest on certification requirements.
Distribution Channel:
Procurement consolidation among professional growers fragments traditional wholesale structures, while consumer segments retain multi-channel access patterns.
- Wholesale Suppliers:Traditional break-bulk handlers in Rotterdam and Hamburg face margin compression as German nursery clusters source direct from Estonian extraction sites via containerized shipping.
- Online Retail:E-commerce platforms serve home gardener demand for packaged substrate volumes, with logistics costs limiting viable shipping radii from Baltic production centers.
- Garden Centers:Physical retail maintains consumer segment access in suburban and rural markets, though assortment breadth narrows on working capital constraints.
- Specialty Stores:Professional horticultural supply depots stock certified organic grades with technical support services for greenhouse operators.
Channel compression favors direct sourcing for volume buyers, while intermediaries retain relevance in fragmented consumer markets.
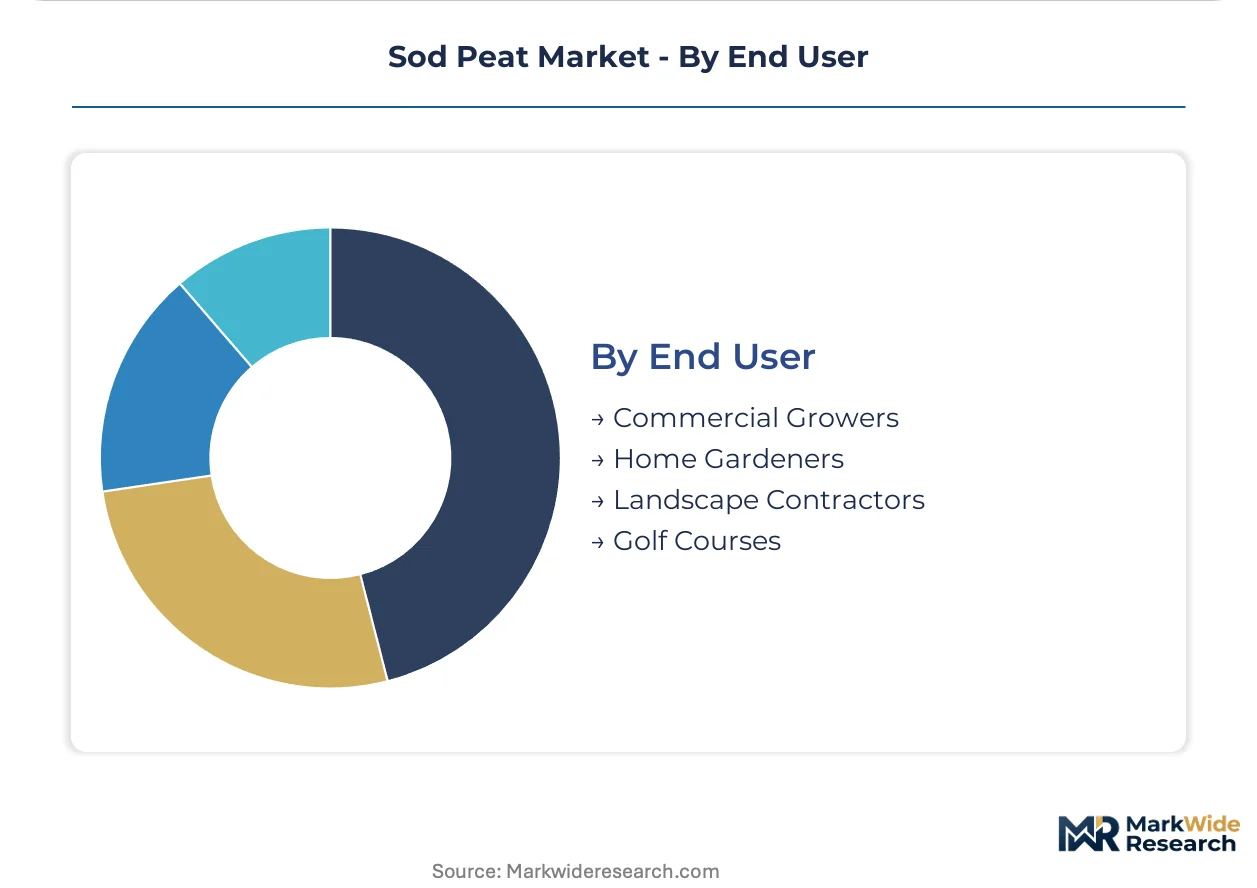
End User:
Procurement sophistication stratifies sharply between commercial cultivation operations with technical specifications and price-sensitive recreational users.
- Commercial Growers:Professional greenhouse and nursery operations demand batch-certificate consistency, driving specification-grade premiums and direct supplier relationships.
- Landscape Contractors:Project-based procurement prioritizes delivered cost and availability over substrate precision, with seasonal demand spikes.
- Golf Courses:Turf management specifications increasingly incorporate certified organic requirements and restoration bond documentation.
- Home Gardeners:Price-sensitive retail purchasers with low volume per transaction and high brand recognition dependency.
Commercial growers extract maximum supplier concessions through volume consolidation, while golf course specifications are tightening fastest on sustainability credentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting sod peat extraction toward jurisdictions with lower compliance burdens, as Finland's MEE wetland protection directives compress domestic permits while Estonian Water Act licensing maintains export-oriented access. This divergence concentrates harvest capacity along the Baltic rim.
Finland
District heating plants in Tampere and Oulu sustain baseline offtake for combustion-grade sod peat despite carbon accounting pressures. MEE wetland conservation rules have halved new bog extraction permits since 2020, forcing Vapo Oy to process residual stocks from legacy concessions. The Ostrobothnia region hosts the country's densest concentration of mechanized harvesting equipment.
Estonia
Water Act licensing frameworks prioritize certified horticultural grades over fuel-grade output, redirecting export volumes toward Dutch greenhouse buyers. Automated cutting and compression operations in Pärnu County achieve unit labor costs below Finnish benchmarks by 15-20 percent. Tallinn-based processors now ship containerized substrate blocks directly to German nursery clusters.
Ireland
Bord na Mona leverages state-vested peatland concessions across the midlands to supply bulk landscaping volumes for British municipal contracts. National peatland restoration mandates scheduled for 2025-2030 are accelerating harvest rates ahead of rewetting deadlines. The Kildare-Offaly corridor contains the island's highest density of extraction infrastructure.
Germany
Commercial greenhouse operators in the Lower Rhine region specify certified organic grades with documented restoration bonds for tomato propagation programs. F-Gas Regulation-equivalent emission thresholds for solid biofuel combustion are forcing district heating retrofits away from peat firing. Bavarian golf federations increasingly mandate blockchain-tracked provenance for root zone amendments.
Netherlands
EU Green Deal sustainable carbon management frameworks require embedded emissions disclosure for all imported horticultural substrates entering Rotterdam port. Glasshouse clusters in Westland demand batch-consistent porosity specifications that only Baltic sphagnum grades reliably deliver. Direct procurement relationships with Estonian extractors are displacing traditional wholesale intermediaries.
Sod Peat Market Competitive Landscape
Baltic producers anchor the volume-export tier; Nordic integrated operators hold concession-dependent positions. The market structures around three strategic archetypes: state-vested legacy concessionaires with rewetting deadlines, mechanized Baltic exporters with cost advantages, and formulated-substrate specialists commanding greenhouse premiums. Competitive moves center on restoration bond arbitrage ahead of regulatory phase-outs and backward integration into automated optical sorting.
Among Nordic integrated operators, Vapo Oy and Neova Oy exemplify the concession-dependent archetype, leveraging Finnish bog access for district heating supply chains while diversifying toward horticultural certification. Bord na Mona occupies a parallel position in Ireland, anchoring state-vested extraction capacity ahead of midlands rewetting mandates. Klasmann-Deilmann represents the formulated-substrate specialist tier, with German greenhouse technical specifications driving premium positioning.
| Leading Market Players |
|---|
| Premier Tech |
| Klasmann-Deilmann |
| Sun Gro Horticulture |
| Bord na Mona |
| Lambert Peat Moss |
| Vapo Oy |
| Jiffy Products |
| Neova Oy |
| AS Tootsi Turvas |
| Others |
Pricing and Supply Chain Analysis
Mechanized harvesting specialists concentrated in Pärnu County compress unit labor costs below Finnish benchmarks by 15-20 percent, widening spreads between premium certified organic grades and economy fuel-tier sods. Estonia's Water Act licensing prioritizes horticultural certification, redirecting margin capture toward growers willing to document restoration bonds.
Pricing Analysis
Retailer markup compression in Rotterdam wholesale channels is accelerating direct-to-grower contracting, with German nursery clusters now procuring containerized substrate blocks from Estonian extraction sites. Three-tier pricing structure across premium certified organic, standard horticultural, and economy combustion grades reflects divergence in carbon accounting documentation. Pricing pressure stems from Latvian wood fiber briquettes displacing sod peat in Baltic district heating blends. Home gardeners exhibit highest price sensitivity per packaged volume, while Dutch glasshouse operators absorb specification premiums for batch-consistent porosity.
Supply Chain Analysis
Workforce availability constraints in Finland's Ostrobothnia region are forcing Vapo Oy to source raw peat across the Gulf of Finland, lengthening inbound logistics legs. Supply concentrates in Estonia, Finland, and Ireland, with extraction economics drawing from sphagnum moss deposits, mechanized cutting equipment, and legacy concession infrastructure. Single-source vulnerability sits with Bord na Mona's state-vested midlands concessions ahead of rewetting mandates. Distribution runs through containerized bulk shipping displacing break-bag handlers, with direct procurement relationships compressing channel layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sod peat functions as a stable compounder where district heating infrastructure sustains baseline offtake despite carbon accounting pressures, while horticulture substrate standardization pulls volume toward certified organic premiums.
For Market Incumbents: Hedge against peatland restoration bond escalations by accelerating harvest rates from legacy Irish concessions ahead of midlands rewetting deadlines. Secure backward integration into automated optical sorting infrastructure to standardize batch consistency for Dutch glasshouse specifications. Diversify revenue streams toward enhanced peat formulations with integrated fertilizer coatings. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap offers white-space entry for mid-grade horticultural suppliers lacking blockchain-verified provenance but meeting basic porosity specifications. Target sports turf applications in German golf federations where certification requirements are tightening fastest. Pursue direct containerized shipping relationships with Rhine-Ruhr nursery clusters to bypass Rotterdam margin compression. For Investors and Strategic Acquirers: Formulated-substrate specialists are the most active acquirer in this space, consolidating greenhouse technical specification capabilities. Five-to-ten year viability hinges on restoration bond arbitrage windows and carbon accounting methodology evolution. Monitor EU Green Deal embedded emissions disclosure enforcement as the inflection signal for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanized Harvesting Scale-Up | Estonian operators deploy automated cutting to sustain 15-20 percent labor cost advantages over Finnish peers. |
| Enhanced Peat Formulation Development | Integrated fertilizer coatings command margin premiums from Dutch tomato propagation programs. |
| Direct-to-Grower Channel Establishment | German nursery clusters bypass Rotterdam handlers via containerized procurement from Pärnu County. |
| Restoration Bond Arbitrage Positioning | Legacy Irish concession holders accelerate extraction ahead of Bord na Mona rewetting mandates. |
| Blockchain Provenance Integration | Dutch import protocols under EU Green Deal frameworks require verified tracking for premium access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with peatland extraction operators, district heating plant procurement officers, commercial greenhouse technical managers, and horticultural wholesale distributors with secondary validation. Customs and trade data from Baltic port authorities, EU Green Deal regulatory filings, national wetland conservation directives, and extraction concession registries anchored supply-side modeling. Bottom-up volume aggregation across Estonian, Finnish, and Irish production clusters triangulated against top-down demand estimates from Dutch and German horticulture associations.
Historical reference periods spanning pre-regulatory reform baselines through current permitting constraints anchored the projection horizon, with analytical frameworks modeling product type evolution, application tier shifts, and channel restructuring across the forecast period. Segmentation dimensions included certification grade tier, end-use application, procurement channel, and regional regulatory cluster. CAGRs derived from regression analysis against peatland access trajectories and substitution elasticity parameters, with district heating retrofit timelines and horticulture substrate standardization curves as key forecast inputs.
Caveats apply where Finland's MEE wetland protection directive enforcement intensity or EU Green Deal carbon border adjustment scope could materially shift the outlook. Forecasts reflect assumptions regarding restoration bond requirement stability and mechanized harvesting diffusion rates. Material deviation in peatland rewetting mandate timing or biomass pellet substitution economics warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Peat Market