
 Black Gram Market | 2026-2036
Black Gram Market Size, Share, and Industry Trends Forecast 2026-2036
Black Gram Market Intelligence
Multi-source procurement is decoupling from traditional farm-gate aggregation across the black gram value chain. Cargill, Incorporated leverages its grain origination infrastructure to secure supply from diverse growing belts. AGT Food and Ingredients Inc. specializes in pulse fractionation, converting whole black gram into higher-margin ingredient formats. Olam International Ltd. controls export corridors linking Indian processing centers to Middle Eastern and Southeast Asian buyers.
Black gram (Vigna mungo) is a diploid legume containing approximately 25% protein by dry weight, with its seed coat delivering concentrated anthocyanin content valued in functional food formulations. The grain undergoes primary processing—milling into split black gram or grinding into flour—to unlock applications ranging from traditional dosa batters to extruded snack matrices. Whole black gram dominates volume trade, while black gram flour captures expanding margin pools in gluten-free and high-protein ingredient supply. The food and beverage end-use industry anchors current offtake, though nutritional supplements represents the fastest-growing demand category as sports nutrition brands reformulate with plant protein isolates.
India's FSSAI mandates contaminant thresholds and labeling standards for packaged black gram products, directly shaping product specifications for domestic market access. The country's BIS certification requirements for pulse quality grades influence export readiness and price realization at wholesale mandis. Stakeholders must monitor evolving EU REACH-aligned residue protocols, as European buyers tighten import specifications for legume-derived ingredients entering human food chains.
Market Dynamics
Plant protein fractionation technology is compressing margins for whole-bean traders while concentrating value capture among processors capable of isolating functional protein concentrates and starch fractions for ingredient supply chains.
Growth Catalysts
- India's PLI scheme for food processing:The production-linked incentive program subsidizes capital investment in pulse milling and fractionation infrastructure, accelerating domestic value-added manufacturing capacity.
- Sports nutrition formulation:Brands targeting muscle recovery segments are reformulating with black gram protein isolates to diversify beyond soy and pea protein bases in plant-based supplements.
- Anthocyanin extraction demand:Functional food manufacturers are sourcing seed coat derivatives for natural colorant and antioxidant applications in beverage and confectionery matrices.
Market Restraints
- Monsoon-dependent supply:Indian kharif and rabi sowing patterns tie production volumes to rainfall distribution across Maharashtra, Andhra Pradesh, and Madhya Pradesh growing belts.
- Phytosanitary barriers:EU REACH-aligned residue protocols and maximum residue limits for pesticides constrain export readiness for European food ingredient buyers.
- Pulse flour substitution:Chickpea and lentil flours compete in gluten-free formulations, limiting black gram flour pricing power in commodity ingredient markets.
Strategic Opportunities
- Extruded snack matrices:Black gram flour's expansion properties suit high-protein puffed and extruded product development for Southeast Asian convenience food markets.
- FSSAI fortification mandates:India's mandatory micronutrient fortification standards for staple foods create formulation partnerships between millers and premix suppliers.
- Direct-to-bakery distribution:Bypassing traditional mandi intermediaries to supply dosa batter and idli mix manufacturers with consistent protein-specified flour grades.
Industry Challenges
- Fractionation engineering talent:Shortage of process engineers experienced in pulse protein isolation and starch separation limits capacity expansion timelines.
- BIS certification timelines:Bureau of Indian Standards quality grade testing creates bottlenecks for export-bound lots awaiting laboratory clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Gram Market |
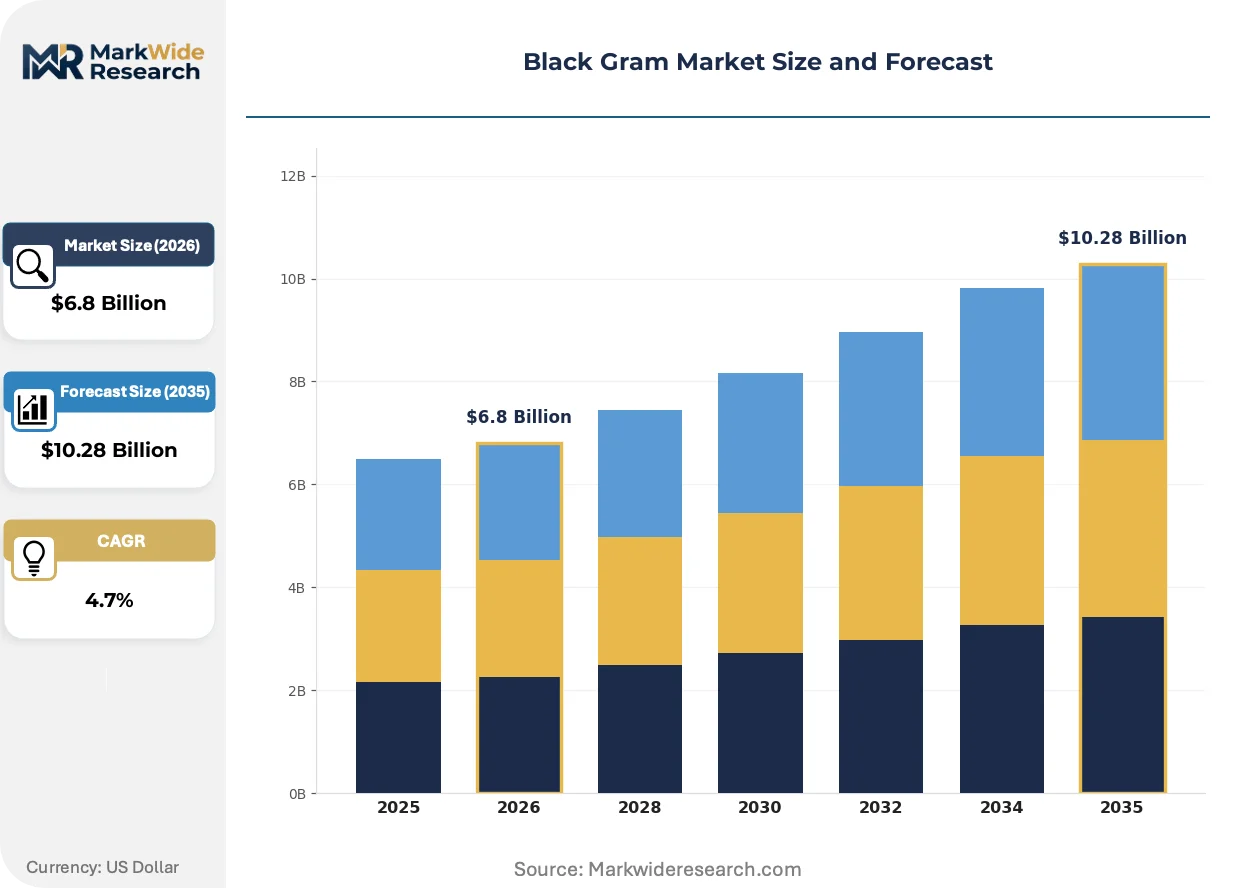
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Black Gram, Split Black Gram, Black Gram Flour, Black Gram Snacks End Use Industry: Food & Beverage, Animal Feed, Nutritional Supplements, Cosmetics Packaging Type: Sack, Pouch, Box, Bulk Container Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Cargill, Incorporated, AGT Food and Ingredients Inc., Olam International Ltd., CHS Inc., Louis Dreyfus Company B.V., Adani Wilmar Ltd., Bunge Limited, Gavilon LLC, Archer-Daniels-Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Gram Market Strategic Shifts & Innovations
Mechanization of traditional processing steps is reshaping quality consistency and throughput economics across the black gram value chain. Equipment upgrades are compressing labor dependence while enabling tighter specification control.
Optical sorting technology is automating defect detection and color grading at primary processing facilities. Medium-scale millers in Tamil Nadu and Karnataka are retrofitting lines with near-infrared spectroscopy units to standardize protein content claims. This equipment investment is automating batch-to-batch variation reduction that previously required manual inspection labor.
India's FSSAI has tightened contaminant thresholds for aflatoxin and heavy metals in packaged pulse products. The regulation forces reformulation of existing product specifications and accelerates testing infrastructure investment. Export-oriented processors are responding by segregating supply chains into domestic-compliant and EU-export-ready production flows.
Bakery and snack manufacturers are consolidating supplier relationships around processors offering certificate-of-analysis documentation for every lot. Long-term contracts with protein-minimum guarantees are displacing spot mandi purchases for volume buyers. This specification-driven procurement is most visible in South Indian urban markets where branded dosa batter chains require consistent hydration and fermentation performance.
Black Gram Market Segmentation
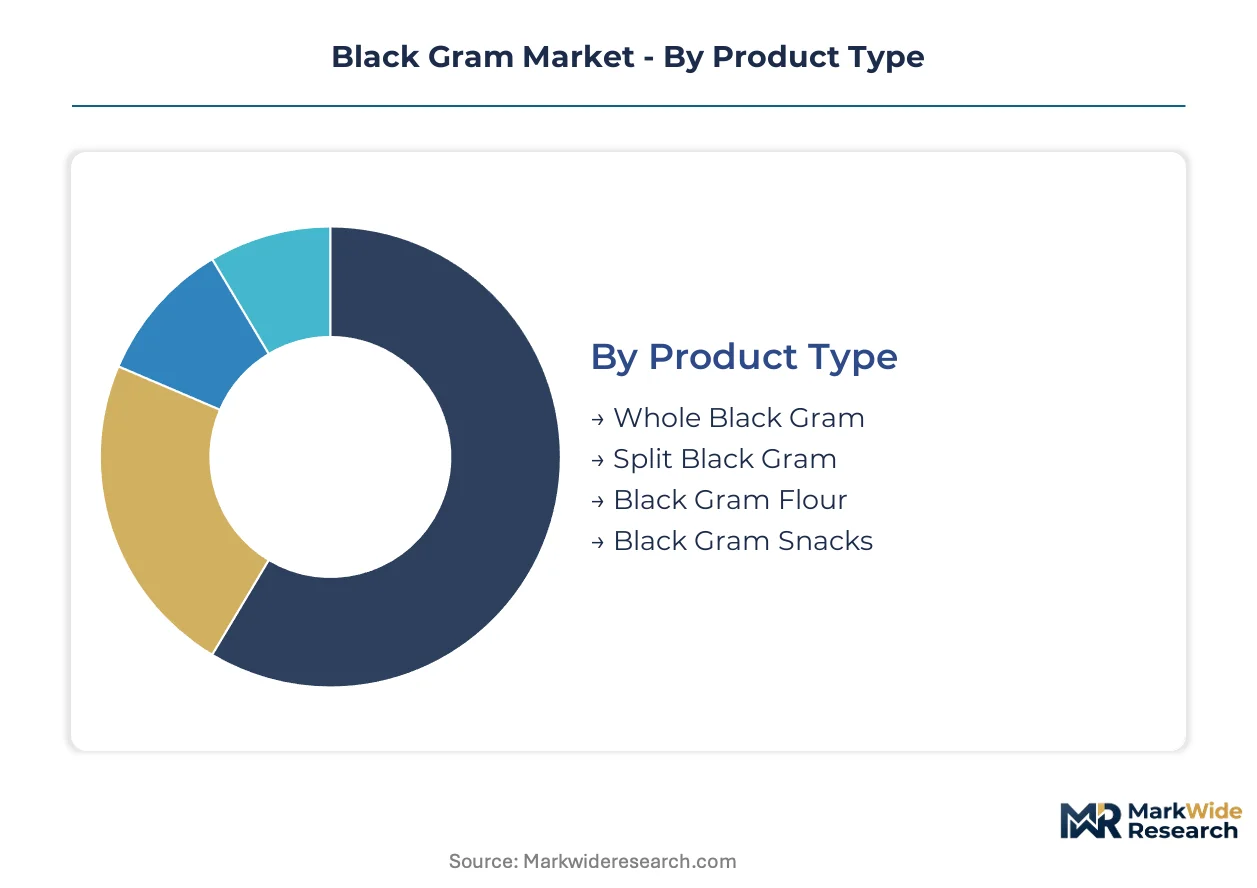
Black gram's physical form and processing intensity determine margin capture and supply chain configuration across distinct product tiers. Specification requirements from FSSAI fortification mandates and EU REACH residue protocols create divergent quality thresholds that reshape procurement patterns by segment.
Product Type:
Processing depth separates commodity traders from ingredient manufacturers capable of isolating functional protein fractions and starch derivatives.
- Whole Black Gram:Unprocessed seeds retain the intact seed coat rich in anthocyanin antioxidants, commanding premium pricing from functional food extractors in Maharashtra and Karnataka processing clusters. Volume trade concentrates at wholesale mandis in Andhra Pradesh and Madhya Pradesh, where BIS certification grades determine export readiness for Middle Eastern buyers.
- Black Gram Flour:Fine-milled powder with 25% protein content serves gluten-free bakery formulations and extruded snack matrices, with protein-minimum specifications now standard in long-term supply contracts. South Indian dosa batter manufacturers in Chennai and Bengaluru are consolidating procurement around processors offering certificate-of-analysis documentation for every lot.
- Split Black Gram:De-husked halves reduce cooking time for traditional dal preparations across domestic Indian households and diaspora markets in the United Arab Emirates.
- Black Gram Snacks:Extruded and roasted products target convenience food channels in Southeast Asian urban centers.
Whole Black Gram leads on scale; Black Gram Flour leads on momentum.
End Use Industry:
Application requirements range from basic caloric input to bioactive compound extraction, with regulatory intensity escalating through the value chain.
- Nutritional Supplements:Sports nutrition brands reformulate muscle recovery products with black gram protein isolates to diversify beyond soy and pea bases, with FSSAI contaminant thresholds for heavy metals forcing segregated production flows. PLI scheme subsidies are accelerating domestic fractionation capacity for isolate production.
- Food & Beverage:Traditional fermented batter applications and modern gluten-free formulations consume the majority of processed black gram derivatives, with branded chains in Tamil Nadu and Karnataka mandating consistent hydration performance specifications.
- Animal Feed:Protein-rich meal byproducts from milling operations enter poultry and aquaculture nutrition formulations.
- Cosmetics:Seed coat anthocyanin extracts supply natural antioxidant and colorant applications in personal care formulations.
Food & Beverage leads on scale; Nutritional Supplements leads on momentum.
Packaging Type:
Packaging selection tracks customer scale, shelf-life requirements, and handling infrastructure across the distribution network.
- Sack:Woven polypropylene bags dominate mandi-level wholesale trade and bulk export shipments to Middle Eastern processors, with standard weights aligning with port handling equipment specifications.
- Pouch:Laminated flexible packaging serves retail-ready flour and snack products requiring moisture barriers for urban Indian supermarket channels.
- Box:Corrugated containers protect value-added gift packs and premium organic certifications for specialty store distribution.
- Bulk Container:Food-grade liners in ISO containers enable direct-to-processor delivery for large-scale fractionation facilities.
Sack leads on scale; Pouch leads on momentum.
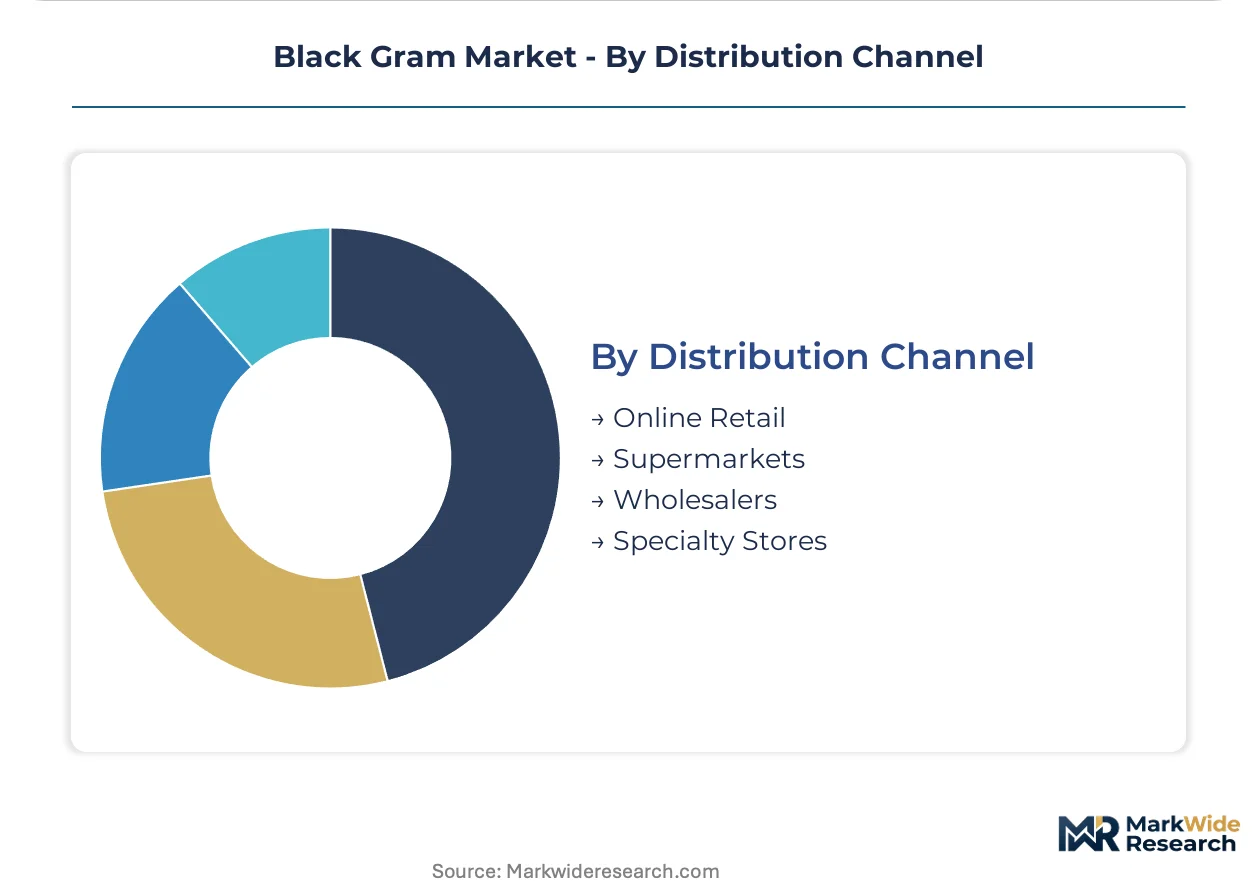
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and the presence of quality documentation requirements.
- Wholesalers:Traditional mandi intermediaries aggregate farm-gate supply for volume buyers, though their role is compressing as direct-to-processor procurement expands.
- Supermarkets:Organized retail chains in Indian metro markets are expanding private-label black gram flour and snack assortments with FSSAI-mandated fortification labeling.
- Online Retail:E-commerce platforms enable direct distribution of organic-certified and specialty-grade products to diaspora consumers in North America and Europe.
- Specialty Stores:Ethnic grocery channels in the United Arab Emirates and Saudi Arabia serve South Asian expatriate demand for traditional whole and split formats.
Wholesalers leads on scale; Online Retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's processing clusters anchor black gram value creation, with fractionation infrastructure concentrating in Pune and Nashik districts. Domestic demand from nutritional supplement manufacturers and export corridors to Middle Eastern buyers shape procurement patterns across key producing territories.
India
FSSAI fortification mandates and PLI scheme subsidies are accelerating domestic milling capacity expansion. The Bureau of Indian Standards certification requirements govern export-ready quality grades for wholesale mandis. Tamil Nadu and Karnataka millers retrofit optical sorting lines with near-infrared spectroscopy to standardize protein content documentation for branded dosa batter chains.
United Arab Emirates
South Asian expatriate populations sustain demand for traditional whole and split black gram formats through ethnic grocery channels. MOHAP food safety protocols align with import specifications for packaged pulse products entering retail distribution. Dubai's Jebel Ali port corridor handles bulk re-export shipments to Saudi Arabia and other Gulf Cooperation Council markets.
Saudi Arabia
SFDA import regulations enforce residue limits and labeling standards for legume derivatives entering human food chains. Domestic food manufacturing investments under Vision 2030 are creating formulation partnerships with Indian fractionation facilities. Riyadh and Jeddah processing centers are expanding extruded snack production using black gram flour as protein fortification input.
Myanmar
Cross-border trade corridors supply whole black gram to Indian millers in Andhra Pradesh and Telangana processing zones. Monsoon-dependent production in the central dry zone creates seasonal supply volatility for regional traders. Yangon-based aggregators are consolidating farm-gate collections for direct-to-processor contracts bypassing traditional mandi intermediaries.
Black Gram Market Key Industry Players
Global majors compete with regional champions across supply chain control and processing technology deployment. The vendor base separates into grain origination specialists, pulse fractionation engineers, and export corridor operators. Three archetypes dominate: integrated agribusiness conglomerates with multi-commodity infrastructure, dedicated pulse processors with ingredient formulation capabilities, and trading houses controlling logistics nodes between producing and consuming regions. Competitive moves concentrate on backward integration into farm-gate procurement networks and technology licensing for protein isolation systems.
Among integrated agribusiness conglomerates, Cargill, Incorporated and Archer-Daniels-Midland Company represent the scale-driven archetype with grain origination infrastructure spanning multiple growing belts. AGT Food and Ingredients Inc. exemplifies the specialized pulse fractionation tier, converting whole legumes into higher-margin ingredient formats for nutritional supplement supply chains. Olam International Ltd. occupies the export corridor control position, linking Indian processing centers to Middle Eastern and Southeast Asian buyer networks.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| AGT Food and Ingredients Inc. |
| Olam International Ltd. |
| CHS Inc. |
| Louis Dreyfus Company B.V. |
| Adani Wilmar Ltd. |
| Bunge Limited |
| Gavilon LLC |
| Archer-Daniels-Midland Company |
| Others |
Cost & Logistics Intelligence
Backward integration into farm-gate procurement networks anchors both supply security and margin capture for Indian black gram processors, with PLI scheme subsidies compressing payback periods on optical sorting and fractionation equipment. This upstream control separates commodity mandi traders from ingredient manufacturers capable of protein-minimum guarantees.
Pricing Analysis
Input-cost pass-through from monsoon-dependent kharif and rabi sowing patterns creates seasonal volatility at Andhra Pradesh and Madhya Pradesh mandis. Three-tier pricing structure across premium organic-certified, standard BIS-graded, and economy ungraded tiers reflects certification investment and quality testing documentation. Pricing pressure stems from chickpea and lentil flour substitution in gluten-free formulations, compressing black gram flour premiums. Contract manufacturers for branded dosa batter chains exhibit lowest price sensitivity due to fermentation-performance specifications, while spot mandi buyers remain highly elastic.
Supply Chain Analysis
Direct-to-processor channels handle volume demand from nutritional supplement fractionators and extruded snack manufacturers, displacing traditional mandi intermediaries. Supply concentrates in India, with Myanmar cross-border corridors and limited UAE re-export processing providing secondary sourcing. Raw material flows draw from monsoon-dependent Maharashtra, Andhra Pradesh, and Karnataka growing belts, with seed coat anthocyanin content varying by cultivar. Single-source vulnerability around Indian kharif harvest concentration creates Q3 supply risk. Distribution runs through Jebel Ali port corridors for Middle Eastern buyers and Chennai-Bengaluru road networks for South Indian mill clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Black gram processing presents a geographic-arbitrage play between India's PLI-subsidized fractionation infrastructure and the EU's tightening REACH-aligned residue protocols, which force segregated production flows and quality-premium capture.
For Market Incumbents: Deepen backward integration into Tamil Nadu and Karnataka farm-gate collection networks to secure seed coat-rich cultivars for anthocyanin extractors. Add near-infrared spectroscopy documentation capacity to defend against emerging direct-to-bakery procurement models. Lock in long-term offtake contracts with UAE and Saudi extruded snack manufacturers before fractionation engineering talent scarcity widens.
For New Entrants and Emerging Players: Specialty organic-certified aggregators represent the most penetrable channel partner type for bypassing established mandi intermediaries. Target Myanmar cross-border supply corridors where Yangon-based consolidation is displacing traditional traders. White-space exists in direct-to-bakery distribution for protein-specified flour grades with certificate-of-analysis documentation.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale optical sorting-equipped millers because BIS certification bottlenecks create captive supply value for export-ready processors. Acquire targets with existing EU-segregated production flows and FSSAI fortification partnership relationships. Watch PLI scheme subsidy renewal announcements as inflection indicators for domestic capacity expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Gate Networks | Captures seed coat-rich cultivars before mandi aggregation dilutes anthocyanin content specifications. |
| Optical Sorting and NIR Spectroscopy Deployment | Automates protein content standardization for branded dosa batter chain contracts. |
| EU-Compliant Production Flow Segregation | Enables REACH-aligned residue protocol access for European nutritional supplement buyers. |
| Direct-to-Bakery Distribution Partnerships | Bypasses mandi intermediaries for consistent hydration-specified flour supply to idli mix manufacturers. |
| Anthocyanin Extraction Capacity Addition | Unlocks functional food and cosmetics applications from seed coat byproduct streams. |
Research Approach
Coverage spans India, the United Arab Emirates, Saudi Arabia, and Myanmar, with primary inputs from each territory's processing clusters and export corridors. The analysis combines interviews with pulse mill operations managers, FSSAI compliance officers at packaged food manufacturers, BIS laboratory certification leads, and procurement directors at Middle Eastern extruded snack producers. Secondary validation draws from DGFT export statistics, FSSAI fortification mandate filings, EU REACH residue protocol updates, and BIS quality grade specification documents. Bottom-up volume modeling from mandi transaction data and top-down value estimation from PLI scheme disbursement records provide triangulation.
Rate-of-change decomposition separates volume growth from price realization across product type, end-use industry, packaging format, and distribution channel dimensions. CAGRs derive from regression against historical kharif and rabi sowing data, monsoon deviation indices, and PLI capacity addition timelines. Industry-specific forecast inputs include FSSAI fortification mandate implementation pace and EU MRL tightening trajectories for legume-derived ingredients.
Revisions become necessary when monsoon failure triggers supply shocks, PLI scheme subsidy structures shift, or EU REACH protocols extend to new contaminant categories. Forecasts reflect documented assumptions about fractionation technology adoption curves and diaspora demand elasticity in Gulf Cooperation Council markets. Periodic stress-testing of base assumptions against BIS certification backlog data and Myanmar cross-border trade flow disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Soy Grits Market
Grains
Triticale Market
Grains
Gluten Feed Market
Grains
Whole-Wheat Flour Market
Grains
Guar Complex Market
Grains
Global Oats Market
Grains
Argentina Grains Market
Grains
China Rice Market
Grains
Low Fat Rice Market
Grains
Asia-Pacific Guar Market
Grains
Quinoa Flour Market
Grains
Sorghum Market
Grains
Organic Wheat Flour Market
Grains
Dried Spent Grain Market
Grains
Grain Bins Market
Grains
United States Maize Market