
 Triticale Market | 2026-2036
Triticale Market Size, Share, and Industry Trends Forecast 2026-2036
Triticale Market Analytics
EU Seed Certification (OECD Seed Schemes) is bifurcating the competitive landscape into qualified breeders and commodity resellers. Limagrain leverages its integrated breeding-to-distribution network across French and German trial stations. KWS Saat anchors Central European germplasm development through proprietary hybrid lines. Bayer Crop Science competes via digital agronomy platforms paired with certified seed portfolios.
Triticale is a synthetic allopolyploid cereal (× Triticosecale Wittmack) combining wheat and rye genomes, typically exhibiting 6.5-13.5% protein content and superior cold tolerance versus parent species, primarily serving dual-purpose grain and forage markets. The grain segment dominates volume throughput due to compound feed mill procurement scale, while the flour category occupies niche human-food channels where gluten functionality requirements limit substitution. Animal feed applications sustain the fastest expansion trajectory as dairy and swine operations reformulate rations around cost-optimized energy-to-protein ratios.
EU Plant Health Regulation and OECD Seed Schemes govern variety registration and cross-border seed movement, with national phytosanitary authorities in Germany, Poland, and France conducting field inspection protocols that determine market access eligibility. REACH compliance for co-product processing residues adds downstream compliance layers for bioenergy offtakers. Stakeholders must monitor germplasm patent cliff dynamics and carbon-accounting rulemaking in feed supply chains to anticipate margin redistribution between breeders and end-users.
Market Dynamics
The EU F-Gas Regulation is redirecting livestock feed procurement toward lower-carbon grain sources, compressing the decision window for compound feed millers across Central Europe.
Growth Catalysts
- Animal Nutrition Reformulation:Dairy and swine operations in Poland and Germany are elevating triticale inclusion rates to optimize energy-to-protein ratios in compound feeds.
- EU Green Deal Compliance:Carbon-accounting mandates in feed supply chains are accelerating sourcing shifts toward domestically produced, lower-emission grains.
- Cold Climate Adaptation:Superior winter hardiness versus wheat parent species is expanding cultivation zones into Baltic and Nordic latitudes previously unsuitable for cereal production.
Market Restraints
- Input Cost Volatility:Nitrogen fertilizer price swings tied to natural gas markets compress margins for triticale growers in Germany and Poland.
- Supply Concentration Risk:Certified seed germplasm is controlled by a narrow breeder base operating French and German trial stations, limiting farmer choice.
- Substitution Threat:Barley and wheat remain entrenched in flour milling channels where gluten functionality requirements resist triticale displacement.
Strategic Opportunities
- Bioenergy Co-Product Streams:REACH-compliant processing residues are opening ethanol and biogas offtake channels for grain processors.
- Ukraine Corridor Integration:Eastern Poland's grain logistics infrastructure can capture volume from western Ukrainian production zones as trade routes normalize.
- OECD Seed Scheme Expansion:Variety registration harmonization is reducing cross-border friction for certified seed distribution into Baltic markets.
Industry Challenges
- Phytosanitary Certification Timelines:National field inspection protocols in Germany, Poland, and France create multi-season delays for new variety market entry.
- Germplasm Patent Cliffs:Proprietary hybrid line expirations are destabilizing royalty structures and forcing breeder portfolio restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triticale Market |
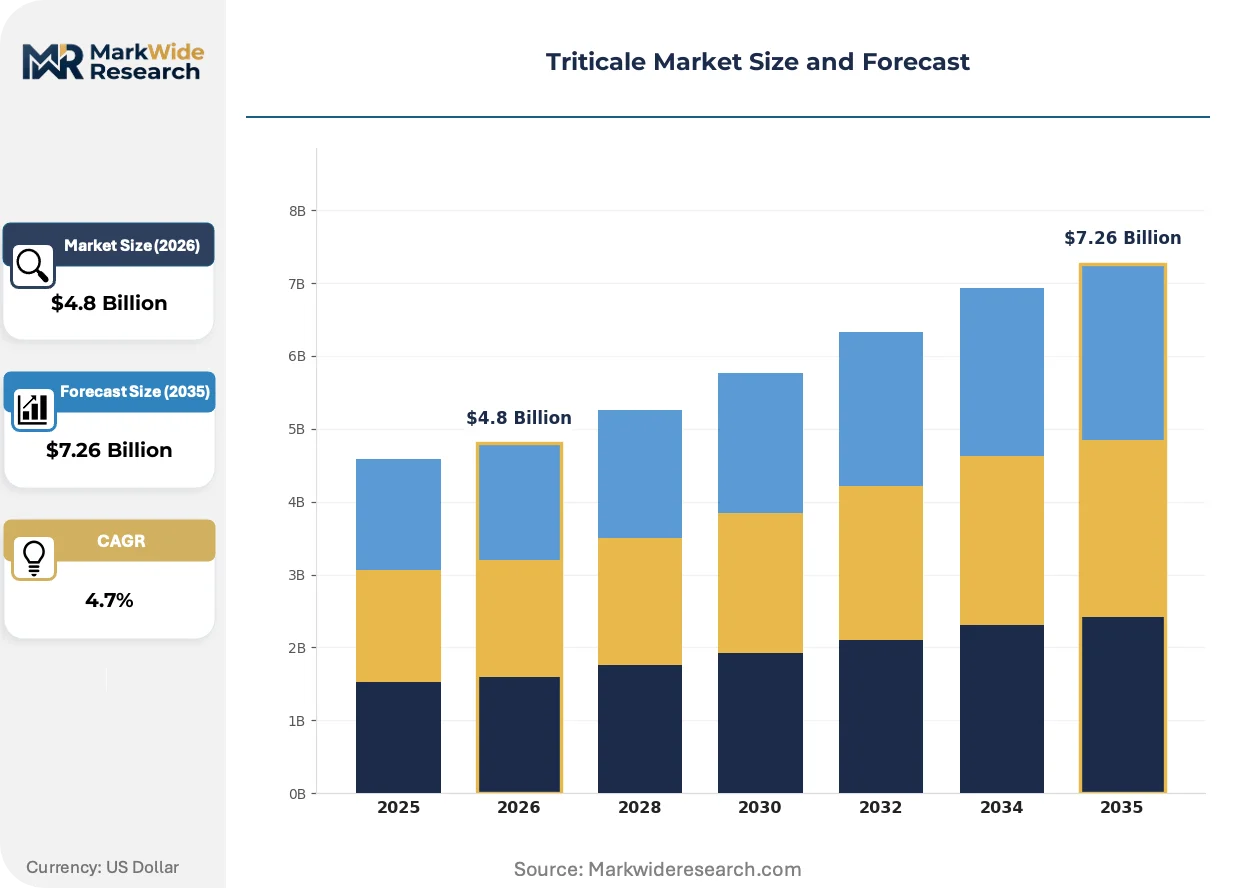
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain, Flour, Animal Feed, Biofuel End Use Industry: Agriculture, Food & Beverage, Animal Nutrition, Bioenergy Distribution Channel: Direct Sales, Retail, Online, Wholesalers Form: Whole Grain, Processed, Powdered, Pellets |
| Companies Covered | Limagrain, Advanta Seeds, Poland Triticale Producers Association, Bayer Crop Science, DuPont Pioneer, KWS Saat, Sempra Seeds, AGCO Corporation, Syngenta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triticale Market Evolving Landscape
Digital agronomy platforms are compressing the feedback loop between field performance data and breeding selection, altering how seed companies prioritize trait development.
Precision phenotyping using drone-mounted multispectral sensors is miniaturizing the scale at which breeders can evaluate cold tolerance and protein expression across trial stations. German and French seed houses are deploying these systems at hundreds of micro-plots simultaneously. The technology is miniaturizing the cost structure of germplasm development, allowing mid-tier breeders to compete on trait specificity.
REACH enforcement for co-product processing residues is tightening documentation requirements for bioenergy offtakers sourcing distillers grains. ECHA compliance deadlines are forcing feed compounders to requalify supply chain partners. Dairy operations in Denmark and the Netherlands are responding by demanding batch-level carbon intensity certificates from grain suppliers.
Compound feed millers are consolidating procurement decisions at the regional hub level, displacing decentralized buying from individual livestock cooperatives. This concentration is compressing price negotiation cycles and favoring volume suppliers with certified seed traceability. The shift is most visible across Poland's Kuyavian-Pomeranian and Greater Poland voivodeships where dairy cluster density is highest.
Triticale Market Segmentation
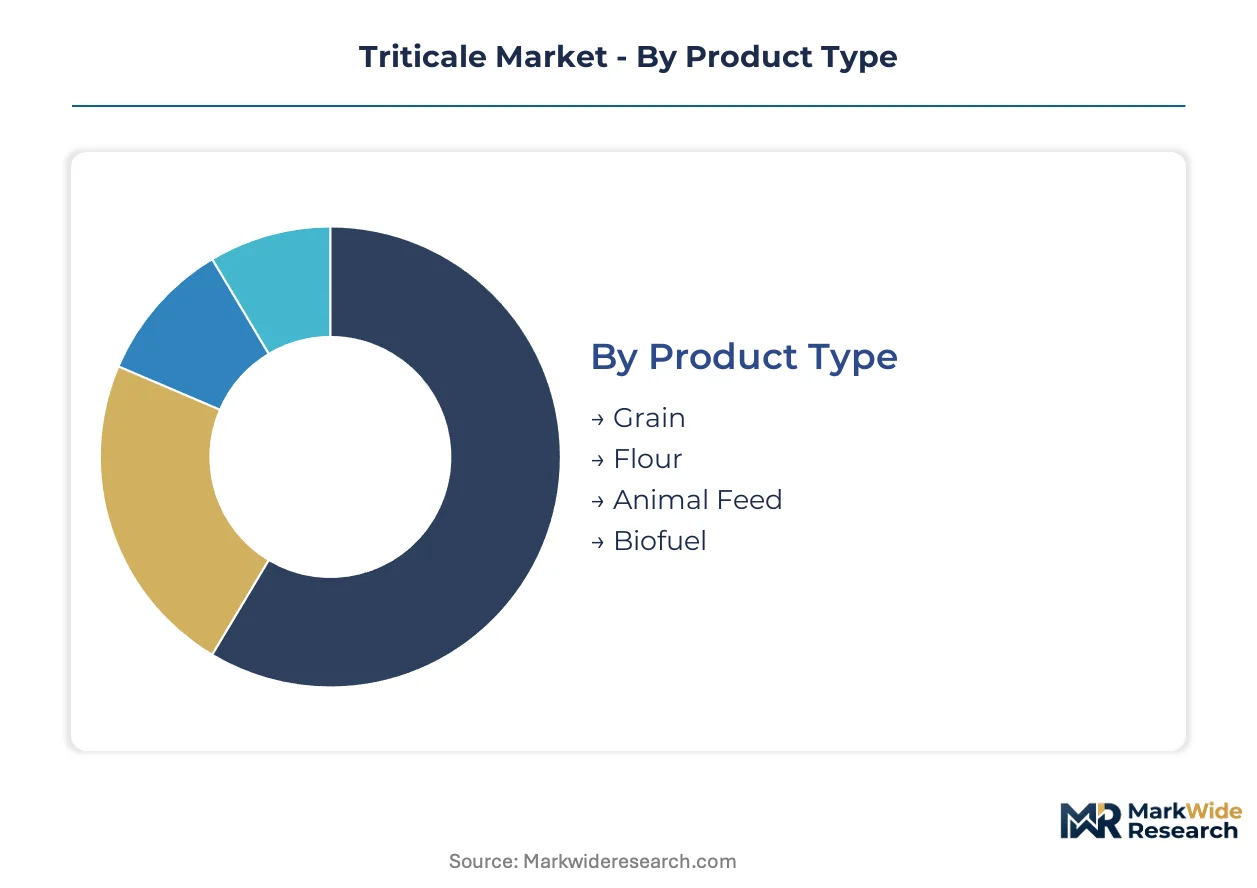
Channel configuration determines margin capture across triticale value chains, with compound feed mills and bioenergy processors commanding procurement scale that reshapes segment economics. Breeders and grain traders must align product specifications to the technical requirements of dominant offtake channels rather than pursuing horizontal market coverage.
Product Type:
Grain flows through high-volume procurement channels serving compound feed mills and bioenergy facilities, while flour and processed forms access fragmented food manufacturing and specialty ingredient distributors.
- Grain:Unprocessed triticale kernels with 6.5-13.5% protein content serve as the primary input for compound feed formulation and ethanol production. Demand concentrates in Poland's Kuyavian-Pomeranian dairy clusters where feed millers optimize energy-to-protein ratios for swine and cattle rations.
- Animal Feed:Formulated compound feeds incorporating triticale as a cost-optimized carbohydrate source displace wheat and barley in Central European dairy operations. Expansion concentrates in Germany's Lower Saxony and Bavaria regions where EU F-Gas Regulation compliance pressures lower-carbon feed sourcing decisions.
- Flour:Milled triticale with modified gluten functionality occupies niche human-food channels including specialty breads and breakfast cereals. German and French artisanal bakeries represent the primary offtake.
- Biofuel:Starch-rich grain streams feed ethanol distillation and biogas anaerobic digestion systems. REACH-compliant processing residue documentation requirements shape processor qualification protocols.
Grain dominates installed base. Animal feed is where expansion concentrates.
End Use Industry:
Cost tier differentiation separates commodity grain procurement from premium-certified seed and specialty ingredient channels, with carbon-accounting compliance adding a new price stratification layer.
- Animal Nutrition:Dairy and swine operations in Poland and Germany drive volume demand through reformulated rations targeting feed cost reduction. Batch-level carbon intensity certificates are becoming mandatory for supply chain qualification.
- Agriculture:Seed multiplication and certified germplasm distribution serve farmer replanting demand governed by OECD Seed Scheme variety registration. German and French trial stations anchor breeding program output.
- Bioenergy:Ethanol distilleries and biogas plants source triticale as a fermentable carbohydrate stream. ECHA enforcement timelines for co-product residue documentation compress processor compliance windows.
- Food & Beverage:Limited human-food applications include specialty milling for gluten-modified bakery products and breakfast cereal formulations. Gluten functionality constraints resist broader substitution.
Animal nutrition commands procurement volume. Bioenergy is climbing the fastest as carbon-accounting rules tighten.
Distribution Channel:
Customer type concentration—large feed millers versus fragmented livestock cooperatives—determines channel selection and pricing power allocation.
- Direct Sales:Large compound feed millers and bioenergy processors contract directly with grain traders and breeder-affiliated distributors for volume procurement. Poland's Greater Poland voivodeship hosts the densest direct sales contracting.
- Wholesalers:Regional grain aggregators consolidate farm-gate production for redistribution to smaller feed compounders and food processors. Eastern Poland's grain corridor infrastructure supports wholesaler concentration.
- Retail:Farm supply stores and agricultural cooperatives serve smallholder replanting demand for certified seed. German and Polish retail networks carry OECD-registered varieties.
- Online:Digital platforms facilitate certified seed ordering and agronomic input bundling, particularly for precision phenotyping-enabled variety selection. Bayer Crop Science and KWS Saat operate proprietary portals.
Direct sales dominate installed base. Wholesalers are gaining share fastest as regional hub procurement consolidates.
Form:
Supply concentration in certified seed germplasm and processing infrastructure shapes form availability and geographic reach.
- Whole Grain:Unprocessed kernels move through bulk commodity channels to feed mills, bioenergy facilities, and export terminals. Baltic port infrastructure expansion supports whole grain throughput growth.
- Pellets:Densified feed forms improve handling efficiency and ration uniformity for automated feeding systems in large-scale dairy operations. Danish and Dutch dairy clusters drive pellet specification demand.
- Processed:Cracked, rolled, or extruded grain forms enhance digestibility for monogastric livestock. German feed technology suppliers dominate processing equipment provision.
- Powdered:Fine-milled flour serves specialty food manufacturing and ingredient blending applications. Limited volume reflects gluten functionality constraints in mainstream baking.
Whole grain dominates installed base. Pellets are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation compliance pressures are redirecting livestock feed procurement toward lower-carbon grain sources across Central and Eastern Europe. Poland and Germany anchor volume demand through dairy cluster density and compound feed mill consolidation. Baltic and Nordic cultivation zones expand as winter hardiness advantages unlock previously unsuitable latitudes.
Germany
Dairy operations in Lower Saxony and Bavaria drive compound feed reformulation around triticale's energy-to-protein optimization. The country's national agricultural regulator enforces OECD Seed Scheme field inspection protocols that determine variety registration timelines. KWS Saat anchors germplasm development through proprietary hybrid lines tested across German trial stations.
Poland
Swine and cattle operations in the Kuyavian-Pomeranian and Greater Poland voivodeships scale triticale inclusion rates in automated feeding systems. EU Plant Health Regulation compliance shapes cross-border seed movement with Ukraine. Eastern Poland's grain corridor infrastructure consolidates wholesaler activity linking western Ukrainian production zones.
France
Artisanal bakeries in Île-de-France and Auvergne-Rhône-Alpes sustain niche flour demand despite gluten functionality constraints limiting broader substitution. The country's national seed certification authority enforces OECD Seed Schemes that bifurcate breeders from commodity resellers. Limagrain leverages integrated breeding-to-distribution networks across French trial stations.
Ukraine
Western Ukrainian production zones supply volume into Polish grain corridors as trade route normalization proceeds. National phytosanitary protocols align with EU Plant Health Regulation requirements for cross-border movement. Lviv and Volyn oblasts concentrate cultivation expansion targeting compound feed mill procurement in adjacent Polish voivodeships.
Denmark
Dairy clusters demand batch-level carbon intensity certificates from grain suppliers under tightening EU Green Deal compliance timelines. ECHA enforcement for co-product processing residues shapes bioenergy offtake documentation requirements. Pellet specification demand concentrates in Jutland Peninsula feeding operations with automated ration systems.
Triticale Market Competitive Landscape
Player mix skews toward integrated seed-to-distribution networks and specialized germplasm developers. Market structure concentrates certified seed supply within a narrow breeder base operating French and German trial stations, limiting farmer choice. Two strategic archetypes dominate: multinational agrochemical conglomerates with digital agronomy platforms, and regionally anchored cooperatives with variety registration expertise. Competitive moves center on precision phenotyping technology deployment and regional hub procurement consolidation.
Within the integrated breeder tier, Limagrain and KWS Saat exemplify archetypes combining proprietary hybrid development with trial station networks. Bayer Crop Science occupies a position representing the agrochemical-digital platform convergence. Poland Triticale Producers Association anchors cooperative-scale variety registration and regional distribution. These three entities collectively illustrate the competitive tension between multinational R&D scale and cooperative proximity to farm-gate demand.
| Leading Market Players |
|---|
| Limagrain |
| Advanta Seeds |
| Poland Triticale Producers Association |
| Bayer Crop Science |
| DuPont Pioneer |
| KWS Saat |
| Sempra Seeds |
| AGCO Corporation |
| Syngenta |
| Others |
Value Network & Pricing Analysis
Triticale's displacement of wheat and barley in compound feed rations simultaneously redraws procurement geography toward Poland's Kuyavian-Pomeranian dairy clusters and compresses price negotiation cycles for certified seed germplasm. This substitution dynamic concentrates buying power among regional hub millers while fragmenting farm-gate seller leverage.
Pricing Analysis
Cost-plus contracts indexed to Euronext wheat futures dominate compound feed procurement, with certified seed premiums stratifying across OECD-registered, farm-saved, and commodity resale tiers. Price differentiation hinges on germplasm registration status and volume scale, with large millers extracting handling discounts unavailable to livestock cooperatives. Pricing pressure stems from nitrogen fertilizer cost volatility tied to natural gas markets, compressing grower margins in Germany and Poland. Smallholder dairy operations exhibit highest price sensitivity, while bioenergy processors with carbon-credit revenue streams absorb modest premiums.
Supply Chain Analysis
Inventory cycles spanning two to three growing seasons characterize certified seed multiplication, creating lead-time rigidity for new variety introduction. Supply concentrates in France, Germany, and Poland, where OECD trial station networks anchor germplasm development. Nitrogen fertilizers, phosphates, and crop protection chemicals constitute critical input dependencies. Single-source vulnerability in hybrid line breeding threatens royalty structure stability. Distribution runs through breeder-affiliated distributors for certified seed and regional grain aggregators for commodity offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: OECD Seed Scheme certification creates multi-season switching costs that lock feed millers into proven germplasm relationships and deter speculative variety adoption.
For Market Incumbents: Shield proprietary hybrid portfolios against patent cliff exposure by accelerating backcrossing programs for trait stacking. Secure exclusive distribution agreements across Poland's Greater Poland voivodeship before trade route normalization unlocks Ukrainian volume. Limagrain and KWS Saat demonstrate the leverage available from captive trial station networks. For New Entrants and Emerging Players: Lead with precision phenotyping-enabled variety selection tools targeting mid-tier breeders excluded from French and German trial station access. Baltic markets present the most penetrable geography given OECD Seed Scheme harmonization reducing cross-border friction. Digital agronomy bundling offers the clearest go-to-market angle against integrated incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated breeders with carbon-accounting compliance infrastructure. Long-term viability hinges on feed supply chain decarbonization mandates tightening across the analysis window. Acquisition targets should display certified seed registration expertise paired with regional hub procurement relationships. The signal to watch is EU F-Gas Regulation enforcement intensity redirecting livestock procurement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Seed Portfolio Expansion | OECD registration unlocks premium pricing in Poland's Kuyavian-Pomeranian dairy clusters. |
| Precision Phenotyping Deployment | Drone-mounted multispectral sensors compress germplasm development cost structures for mid-tier breeders. |
| Carbon-Accounting Compliance Integration | Batch-level intensity certificates satisfy ECHA documentation demands from Danish bioenergy offtakers. |
| Regional Hub Procurement Consolidation | Direct miller contracts displace cooperative buying in Greater Poland voivodeship feed markets. |
| Ukraine Corridor Logistics Investment | Eastern Poland infrastructure captures western Ukrainian volume as trade routes normalize. |
Research Methodology
Operator-level perspectives from seed breeding directors, compound feed procurement managers, dairy farm operations heads, and bioenergy facility compliance officers anchored the qualitative base. Primary interview findings were cross-validated against EU Plant Health Regulation filings, OECD Seed Scheme registration databases, ECHA REACH compliance documentation, and national phytosanitary authority inspection protocols. Bottom-up volume estimates from farm-gate production zones were triangulated with top-down compound feed formulation demand models.
Sensitivity analysis tested forecast robustness across nitrogen fertilizer price volatility bands, patent cliff timing scenarios, and Ukraine trade route normalization assumptions. Segmentation modeling captured product type, end-use industry, distribution channel, and geographic cultivation zone dimensions. CAGRs were derived from trend extrapolation of breeder trial station output, feed mill procurement surveys, and bioenergy capacity expansion announcements. Carbon-accounting rulemaking timelines and F-Gas Regulation enforcement intensity served as key scenario variables.
Underlying assumptions cover EU Green Deal compliance trajectory, OECD Seed Scheme harmonization pace, and grain corridor infrastructure investment, with deviation risk concentrated in Ukraine phytosanitary protocol alignment and nitrogen fertilizer supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Corn Gluten Feed Market
Grains
Basmati Rice Market
Grains
Ancient Grain Market
Grains
Tunisia Grain Market
Grains
GCC Basmati Rice Market
Grains
Cultured Wheat Market
Grains
Egypt Rice Market
Grains
North America Wheat Protein Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Grain-Based Flours Market
Grains
Organic Oats Market
Grains
Whole-Wheat Flour Market
Grains
Spelt Wheat Market
Grains
Grain Storage Systems Market
Grains
Argentina Maize Market
Grains
Organic Rice Market