
 Global Oats Market | 2026-2036
Global Oats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oats Market Outlook
Multi-source procurement for raw grain is recalibrating how processors secure supply across hemispheres. Quaker Oats Company leverages its century-old milling infrastructure to dominate North American rolled oat distribution. Oatly AB competes through specialized oat-base formulations for the alternative dairy channel. General Mills anchors its position via backward integration into grain handling and extensive private-label manufacturing.
Oats are cereal grains from Avena sativa, typically processed through steaming and flaking to achieve a shelf-stable flake form with beta-glucan content between 2-8% by weight; this soluble fiber profile drives their primary use in heart-health-positioned foods and functional beverages. Rolled oats and instant oats occupy the largest volume share within product type segmentation, reflecting convenience-driven household purchasing patterns. Steel-cut oats sustain premium positioning in health food stores, where slower cooking times signal minimal processing to discerning buyers. Powdered oat ingredients are gaining traction among bakeries reformulating for clean-label claims and gluten-free positioning.
The FDA's qualified health claims for beta-glucan and coronary heart disease risk shape how manufacturers label oat-containing products in the United States. EFSA's nutrition and health claims regulation in Europe enforces stricter evidentiary standards for oat-based functional food marketing, filtering market access for smaller suppliers. USDA organic certification and EU organic farming standards create dual compliance tracks for exporters serving both markets. Stakeholders must monitor evolving carbon accounting rules under the EU Green Deal and emerging state-level regenerative agriculture incentives in the United States to anticipate sourcing cost shifts and premium capture opportunities.
Market Dynamics
EU Green Deal carbon accounting rules are forcing oat processors to reconfigure grain sourcing networks across hemispheres, with compliance costs now embedded in procurement decisions.
Growth Catalysts
- FDA Qualified Health Claims:The FDA's beta-glucan coronary heart disease claim enables heart-health positioning on oat product labels in the United States, expanding functional food applications.
- Plant-Forward Food Service:Restaurant and café operators are expanding oat-based menu items as consumer preference shifts away from dairy-heavy preparations.
- Germany Demand Concentration:Bakery and beverage manufacturers in Germany are scaling oat ingredient procurement, creating pull-through for Nordic and Baltic grain suppliers.
Market Restraints
- Input Cost Volatility:Fertilizer and fuel price swings tied to natural gas markets compress milling margins during planting and harvest cycles.
- Supply Concentration Risk:Premium oat varieties for food-grade processing concentrate in Canada and Nordic regions, exposing buyers to climate-driven yield variability.
- EFSA Evidentiary Barriers:EFSA's strict health claims regulation filters market access for smaller oat-based functional food suppliers lacking clinical trial resources.
Strategic Opportunities
- Indian Urban Markets:Underpenetrated breakfast cereal and alternative dairy segments in Indian metropolitan areas offer whitespace for oat-based product introductions.
- EU Regenerative Incentives:Emerging state-level regenerative agriculture incentives in EU member states create premium capture potential for certified sustainable oat sourcing.
- Powdered Ingredient Channel:Clean-label bakery reformulation demand is opening specialized distribution for powdered oat ingredients in artisanal and industrial baking segments.
Industry Challenges
- Dual Certification Complexity:USDA organic and EU organic farming standards create parallel compliance tracks that extend export approval timelines for multi-market suppliers.
- Legacy Milling Integration:Century-old flaking infrastructure requires capital-intensive retrofitting to meet modern food safety and traceability protocols.
- Carbon Accounting Talent Gap:Shortage of professionals versed in EU Green Deal agricultural emissions measurement delays supplier verification programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oats Market |
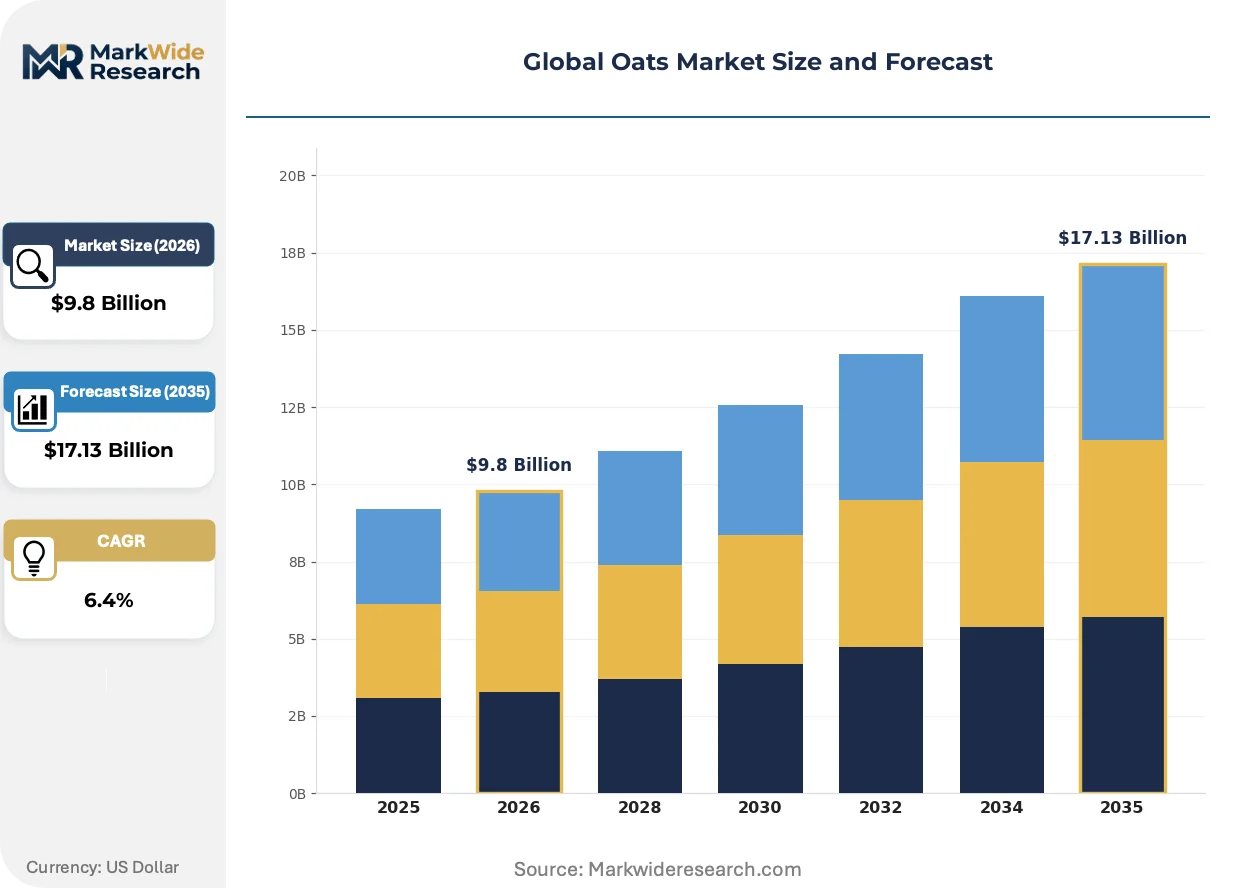
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Oats, Rolled Oats, Steel-Cut Oats, Instant Oats Packaging Type: Bags, Boxes, Bulk, Sachets End User: Households, Food Service, Bakeries, Health Food Stores Form: Flakes, Granules, Powder, Whole Grain |
| Companies Covered | Nestlé SA, Bob's Red Mill Natural Foods, General Mills, Oatly AB, Post Holdings, PepsiCo, Quaker Oats Company, Grain Millers, The Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oats Market Strategic Shifts
Processing automation and regulatory transparency requirements are compressing traditional oat supply chain structures while opening new formulation channels.
Optical sorting combined with near-infrared spectroscopy is automating grain quality assessment at intake points. Large-scale millers in Canada and northern Europe are deploying these systems to reduce manual inspection labor. This technology is automating the segregation of food-grade from feed-grade oats, tightening premium capture for processors with capital deployment capacity.
REACH chemical safety protocols and emerging EU Green Deal farm-to-fork traceability mandates are reshaping ingredient documentation requirements. Processors must now maintain batch-level pesticide residue and carbon intensity records. Organic and conventional oat streams face diverging compliance burdens, with smaller Nordic suppliers consolidating to share certification costs.
Direct contracting between food manufacturers and farm cooperatives is displacing spot-market grain purchasing. Bakery and beverage producers in Germany and the United States are locking in multi-year supply agreements with specified beta-glucan content. This pattern concentrates procurement leverage among scaled end-users while marginalizing traditional grain merchants.
Global Oats Market Segmentation
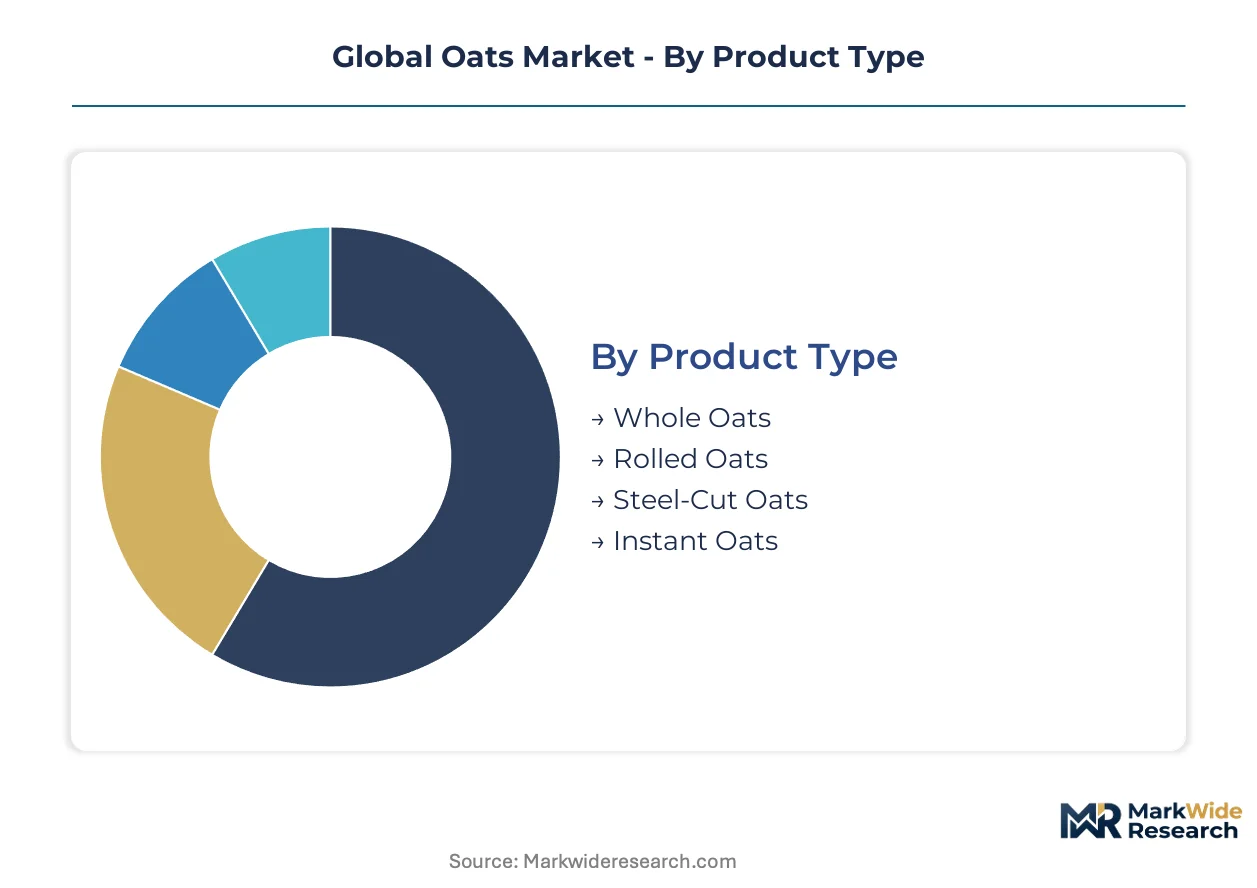
Segmentation in the oats market reveals how processing intensity and distribution channels determine margin capture. Each dimension exposes different competitive pressures from grain sourcing through final consumption.
Product Type:
Integration depth varies sharply across processing stages, with minimally transformed grains serving distinct demand pools than highly processed formats.
- Rolled Oats:Steamed and flattened whole groats yielding shelf-stable flakes with beta-glucan content between 2-8% by weight. German bakery and beverage manufacturers are scaling procurement of this format for clean-label reformulation, driven by EU Green Deal carbon accounting requirements that favor established supply chains.
- Instant Oats:Pre-cooked and thinner flakes designed for sub-two-minute preparation. Convenience-driven household purchasing in the United States concentrates demand here, with FDA qualified health claims enabling heart-health positioning that commands shelf space in conventional retail.
- Whole Oats:Unprocessed groats retaining complete bran and germ layers for feed and specialty food applications.
- Steel-Cut Oats:Groats chopped into pinhead pieces requiring longer cooking; minimal processing signals premium positioning in health food stores.
Volume placements concentrate in Rolled Oats; the faster expansion belongs to Instant Oats.
Packaging Type:
Cost tier structures separate commodity bulk flows from branded retail formats with diverging margin profiles.
- Bulk:Unpackaged grain delivered in totes or tankers for industrial milling and food manufacturing. Large-scale processors in Canada and Nordic regions favor this format for carbon intensity tracking under EU Green Deal protocols.
- Bags:Flexible polyethylene or paper packaging for retail shelf presence. Household demand in Germany and the United States drives specification of resealable closures and portion-control features.
- Boxes:Rigid cardboard containers with printed nutritional panels for premium retail positioning.
- Sachets:Single-serve pouches targeting food service and on-premise consumption channels.
Cost efficiency peaks in Bulk; branded value capture concentrates in Bags.
End User:
Customer type segmentation exposes how formulation requirements and procurement scale reshape supplier relationships.
- Households:Individual consumers purchasing through retail channels for breakfast and baking applications. Convenience-driven purchasing patterns in the United States favor instant formats, while German households show stronger preference for traditional rolled oats.
- Food Service:Restaurants, cafés, and institutional kitchens incorporating oats into plant-forward menu items. Operators across Germany are expanding oat-based preparations as dairy alternatives gain traction in coffee and dessert applications.
- Bakeries:Artisanal and industrial producers reformulating for gluten-free and clean-label claims.
- Health Food Stores:Specialty retailers curating minimally processed and organic-certified options for discerning buyers.
Procurement scale concentrates in Food Service; margin premiums concentrate in Health Food Stores.
Form:
Application-driven form factors determine equipment compatibility and formulation flexibility across end-use segments.
- Flakes:Flattened grain pieces produced through steaming and rolling. Bakery and beverage manufacturers in Germany specify flake thickness and hydration rates for consistent performance in alternative dairy bases.
- Powder:Finely milled oat flour for ingredient applications. Clean-label bakery reformulation demand in the United States is opening specialized distribution channels for this format.
- Granules:Intermediate particle size for textured food applications and nutritional fortification.
- Whole Grain:Intact groats for specialty food and limited industrial uses requiring minimal processing.
Processing throughput concentrates in Flakes; formulation flexibility gains most quickly in Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bakery and beverage manufacturers are scaling oat ingredient procurement faster than any other national demand cluster, pulling grain through Nordic and Baltic supply corridors. The United States anchors North American consumption through FDA-qualified health claim positioning. Canada, India, and Sweden round out the five-country concentration where regulatory frameworks and industrial capacity intersect.
Germany
Bakery reformulation for clean-label claims and alternative dairy base production are absorbing rolled oat volumes at unprecedented rates. The EU Green Deal's carbon accounting protocols now embed compliance costs directly into procurement decisions for processors serving German manufacturers. Hamburg and Berlin industrial clusters are witnessing direct contracting between food manufacturers and farm cooperatives, displacing traditional grain merchants.
United States
Convenience-driven household purchasing concentrates in instant oat formats, while heart-health positioning enabled by FDA qualified health claims secures shelf space in conventional retail. USDA organic certification requirements create parallel compliance tracks for exporters also serving European markets. Minneapolis-St. Paul and Chicago processing hubs are retrofitting century-old flaking infrastructure to meet modern food safety and traceability protocols.
Canada
Premium food-grade oat varieties concentrate in Prairie provinces, exposing buyers to climate-driven yield variability that reshapes annual contracting patterns. The Canadian Grain Commission's grading standards enforce strict quality segregation that underpins export premiums to European and Asian markets. Saskatchewan and Manitoba farm cooperatives are deploying optical sorting combined with near-infrared spectroscopy to automate grain quality assessment at intake points.
India
Underpenetrated breakfast cereal and alternative dairy segments in Mumbai, Delhi, and Bangalore metropolitan areas offer whitespace for oat-based product introductions. FSSAI food safety regulations are tightening documentation requirements for imported grain, filtering market access for smaller international suppliers. Maharashtra and Karnataka urban clusters are seeing early-stage plant-forward menu expansion by food service operators adapting to shifting consumer preferences.
Sweden
Specialized oat-base formulation expertise concentrates among processors serving the alternative dairy channel, with EFSA's strict evidentiary standards for health claims filtering functional food marketing. EU organic farming standards create premium capture potential for certified sustainable sourcing. Skåne and Västra Götaland agricultural regions are consolidating smaller suppliers to share certification costs under REACH chemical safety protocols and emerging farm-to-fork traceability mandates.
Global Oats Market Competitive Environment
Backward integration into grain handling dominates the current landscape as processors secure supply against climate-driven yield variability. The vendor base organizes around three archetypes: century-old milling houses with flaking infrastructure, specialized oat-base formulators for alternative dairy, and diversified cereal conglomerates with private-label manufacturing arms. M&A activity concentrates on Nordic and Baltic grain cooperatives, while capacity expansion focuses on optical sorting and near-infrared spectroscopy deployment for automated quality assessment.
Within the diversified conglomerate tier, Nestlé SA and General Mills occupy positions defined by extensive private-label manufacturing footprints and multi-channel distribution networks. Among specialized oat-base formulators, Oatly AB exemplifies the alternative dairy channel focus that has reshaped competitive positioning in European and North American markets. Quaker Oats Company anchors the century-old milling house archetype, representing infrastructure depth that newer entrants cannot readily replicate.
| Leading Market Players |
|---|
| Nestlé SA |
| Bob's Red Mill Natural Foods |
| General Mills |
| Oatly AB |
| Post Holdings |
| PepsiCo |
| Quaker Oats Company |
| Grain Millers |
| The Kellogg Company |
| Others |
Value Chain & Pricing Dynamics
German bakery and beverage manufacturers' direct contracting with farm cooperatives is compressing spot-market grain purchasing and forcing supply chain reconfiguration toward long-term offtake agreements with specified beta-glucan content.
Pricing Analysis
Volume placements concentrate in bulk commodity flows while margin capture concentrates in certified organic and specialty-grade segments. Pricing stratifies across premium, standard, and economy tiers based on beta-glucan concentration thresholds and organic certification status. Cost compression in standard-grade rolled oats is intensifying because fertilizer and fuel price volatility tied to natural gas markets squeezes milling margins during planting and harvest cycles. Food service operators demonstrate the highest price sensitivity due to thin menu margins, while health food stores absorb premiums for minimal-processing positioning.
Supply Chain Analysis
Freight cost differentials between Prairie province origins and Hamburg port delivery are reshaping procurement geography for European processors. Supply concentrates in Canada, Sweden, and Finland for premium food-grade varieties, with raw material flows drawing from nitrogen fertilizer applications, diesel fuel for field operations, and specialized groat processing equipment. Single-source vulnerability runs through Nordic climate-driven yield variability that disrupts annual contracting patterns. Distribution runs through direct manufacturer-cooperative agreements that displace traditional grain merchants in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into grain handling and captive oat-base formulation capability is becoming the decisive competitive moat as processors race to secure supply against climate-driven yield variability and regulatory traceability mandates.
For Market Incumbents: Anticipate margin compression from optical sorting automation deployment by large-scale Canadian and Nordic millers by accelerating in-house production of specialty oat-base formulations for alternative dairy channels. Lock multi-year direct contracts with Saskatchewan and Manitoba farm cooperatives before EU Green Deal carbon accounting rules fully embed compliance premiums into procurement costs. For New Entrants and Emerging Players: Launch via powdered oat ingredient distribution to artisanal bakeries in underpenetrated Indian metropolitan markets, where FSSAI documentation requirements filter established international suppliers. Target clean-label reformulation demand in Mumbai and Bangalore food service channels with specified hydration-rate flake products that bypass legacy milling infrastructure advantages. For Investors and Strategic Acquirers: The window for entry favors Nordic and Baltic grain cooperatives with consolidated certification cost structures under REACH protocols. Long-term viability hinges on acquisition targets possessing optical sorting and near-infrared spectroscopy capacity for automated quality assessment. Monitor EU member state regenerative agriculture incentive rollouts as the signal for premium capture inflection in sustainable oat sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Handling | Quaker Oats Company leverages century-old milling infrastructure to secure captive supply against climate volatility. |
| Specialized Oat-Base Formulation | Oatly AB anchors competitive positioning through proprietary alternative dairy channel expertise and EFSA-compliant health claim substantiation. |
| Optical Sorting Technology Deployment | Large-scale Canadian millers automate food-grade segregation to reduce manual inspection labor and tighten premium capture. |
| Direct Manufacturer-Cooperative Contracting | German bakery and beverage producers displace traditional grain merchants via multi-year agreements with specified beta-glucan content. |
| Dual Organic Certification Investment | Exporters serving USDA and EU organic markets extend approval timelines but access parallel premium capture opportunities. |
Study Parameters
Document review covered EU Green Deal regulatory filings, FDA qualified health claim substantiation records, and FSSAI import documentation requirements, complemented by interviews with grain procurement directors at German bakery manufacturers, oat mill operations managers in Saskatchewan, and alternative dairy formulation specialists in Sweden. Secondary validation drew from Canadian Grain Commission grading standards, USDA organic certification databases, and EFSA nutrition and health claims registers. Bottom-up volume estimates from product-type and end-user segments were triangulated against top-down market sizing from regional demand clusters.
Quantitative outputs span the projection horizon across product type, packaging format, end-user category, and form factor dimensions, with CAGRs derived from trend extrapolation of FDA and EFSA regulatory influence, plant-forward food service adoption curves, and carbon accounting cost embedding patterns. Forecast inputs incorporated fertilizer and fuel price volatility indices, climate-driven yield variability models for Prairie and Nordic growing regions, and optical sorting technology penetration rates at mill intake points.
EU Green Deal implementation delays, FSSAI documentation requirement tightening, and nitrogen fertilizer price spikes are the dominant revision risks that could compress or extend the projected expansion trajectory. Stakeholders should weight assumptions against their own operating context and procurement exposure to spot-market versus contracted grain flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Europe Wheat Protein Market
Grains
Rolled Oats Market
Grains
Corn Flour Market
Grains
Italy Rice Market
Grains
Black Gram Market
Grains
00 Flour Market
Grains
South America Rice Market
Grains
Brazil Maize Market
Grains
Dried Spent Grain Market
Grains
Asia Pacific Maize Market
Grains
Grain and Cereal Crop Market
Grains
North America Wheat Market
Grains
Corn Gluten Feed Market
Grains
Gluten Free Ancient Grain Market
Grains
Wheat Fiber Market
Grains
Spelt Wheat Market