
 Myanmar Rice Seed Market | 2026-2036
Myanmar Rice Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Rice Seed Market Foresight
Myanmar's central dry zone is reshaping national seed distribution logistics as climate-adaptive varieties gain priority. Myanma Awba Group leverages its integrated supply chain to dominate hybrid seed distribution across the Ayeyarwady basin. Yuan Longping High-Tech Agriculture Co. Ltd anchors its position through proprietary two-line hybrid rice systems optimized for tropical lowlands. Bayer AG competes via its vegetable seed platform while extending digital farming advisory services to commercial growers.
Rice seed constitutes the reproductive propagule of Oryza sativa, typically bred to achieve germination rates exceeding 85 percent and genetic purity standards of 98 percent for certified grades, serving as the foundational input for paddy field establishment and yield consistency. Hybrid seed commands premium positioning due to its heterosis-driven yield advantage of 15-20 percent over open-pollinated alternatives, though smallholder cost sensitivity sustains demand for certified variety seed in marginal districts. Distribution through agricultural cooperatives captures the densest farmer networks, while direct sales from seed companies to commercial farming enterprises concentrate margin pools in the Irrawaddy and Bago regions.
The Department of Agricultural Research enforces seed certification under Myanmar's national seed policy, while the Ministry of Agriculture and Irrigation coordinates varietal release committees that govern market access for new genetics. Seed companies must navigate BIS-aligned purity testing and phytosanitary standards to maintain commercial registration. Stakeholders should monitor varietal approval timelines and irrigation rehabilitation schedules as determinants of seed category demand shifts.
Market Dynamics
The Irrawaddy Delta's irrigation rehabilitation is compressing seed replacement cycles as commercial farms abandon saved seed for certified genetics. This infrastructure-driven demand concentration is restructuring procurement relationships between seed suppliers and large-scale paddy operators.
Growth Catalysts
- Seed Certification Mandates:The Department of Agricultural Research's tightened purity protocols under Myanmar's national seed policy are disqualifying uncertified varieties from government procurement channels.
- Commercial Farm Expansion:Irrawaddy and Bago region enterprises exceeding 50 hectares are standardizing on hybrid systems to capture yield premiums from export-grade milling contracts.
- Climate-Adaptive Breeding:Drought-tolerant varieties developed for the central dry zone are extending the planting window into previously marginal rainfall districts.
Market Restraints
- Input Cost Volatility:Fertilizer price fluctuations linked to Myanmar's foreign exchange constraints are compressing farmer margins and deferring certified seed purchases.
- Supply Concentration Risk:Hybrid germplasm dependence on Chinese two-line system imports creates vulnerability to cross-border phytosanitary disruptions.
- Technical Limitation:Farmer-saved seed from hybrid plants exhibits 40-50 percent yield depression, locking smallholders into annual repurchase cycles they cannot sustain.
Strategic Opportunities
- Underpenetrated Dry Zone:Magway and Mandalay regions with erratic monsoon patterns represent unserved demand for short-duration aerobic rice varieties.
- Regulatory Tailwind:Ministry of Agriculture and Irrigation varietal release committee fast-tracks are accelerating market access for heat-tolerant genetics.
- Cooperative Distribution:Agricultural cooperative networks in Shan State offer embedded credit channels to reach credit-constrained smallholders.
Industry Challenges
- Certification Timeline Compression:BIS-aligned purity testing protocols require 18-24 month field evaluation cycles that lag behind climate stress acceleration.
- Seed Multiplication Bottleneck:Foundation seed supply from Department of Agricultural Research stations cannot scale to meet commercial farm demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Rice Seed Market |
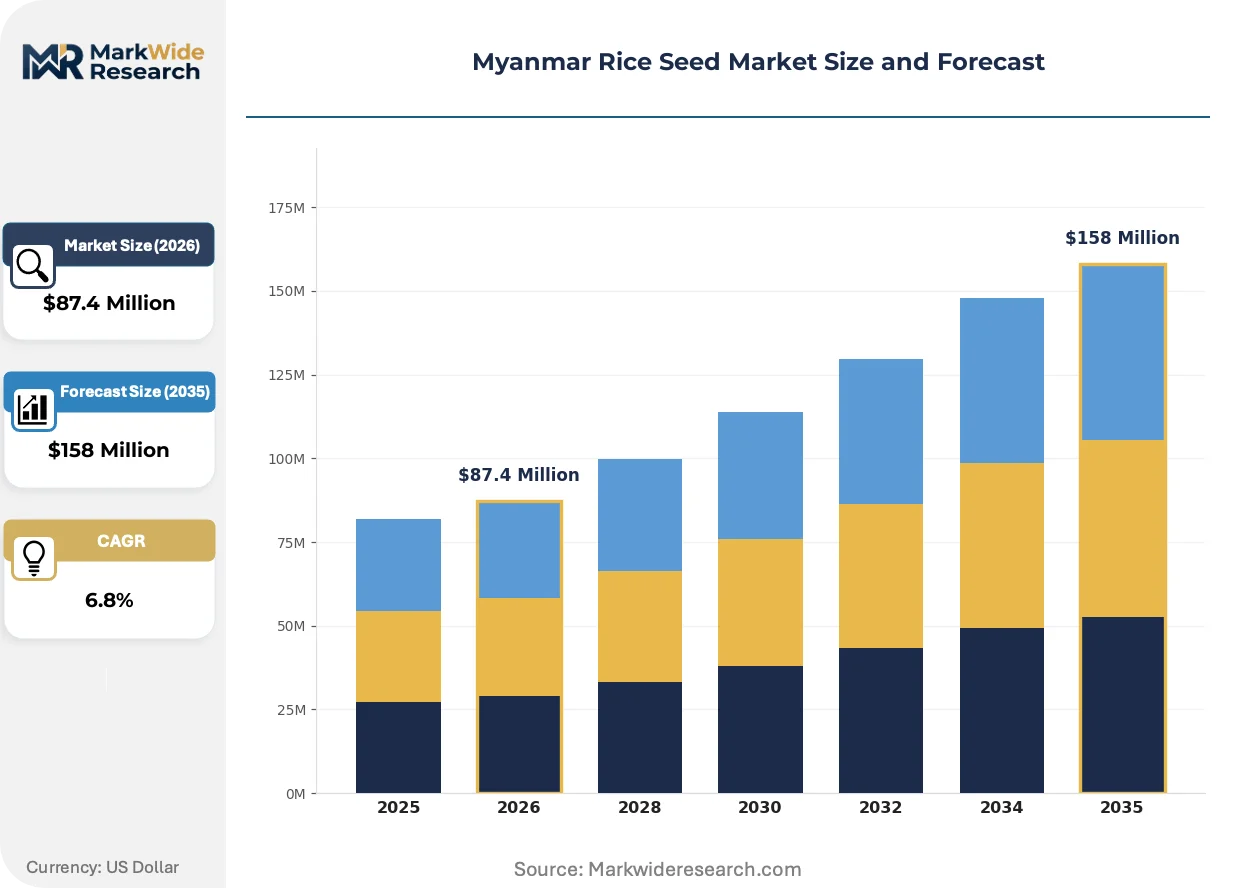
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid Seed, Open-Pollinated Seed, Variety Seed, Certified Seed Distribution Channel: Retail Stores, Agricultural Cooperatives, Online Platforms, Direct Sales Application: Commercial Farming, Smallholder Farming, Research Purposes, Education Market Segment: Regional Farmers, Exporters, Government Initiatives, Seed Companies |
| Companies Covered | Myanma Awba Group, Yuan Longping High-Tech Agriculture Co. Ltd, Bayer AG, Syngenta AG, Myanmar Agribusiness Public Corporation (MAPCO), Dagon Group of Companies, SL Agritech Corporation (SLAC), Corteva, Groupe Limagrain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Rice Seed Market Shifts & Advancements
Myanmar's seed sector is pivoting from informal exchange systems toward quality-assured supply chains as commercial farming consolidates. Three interconnected developments are restructuring how genetic material reaches paddy fields.
Two-line hybrid rice systems are replacing three-line alternatives in tropical lowland breeding programs. Yangon Region commercial farms are adopting these varieties at accelerating rates to secure 15-20 percent yield premiums. The technology is hybridizing seed company business models, compressing the gap between germplasm development and field deployment.
The Department of Agricultural Research's seed certification protocols are tightening genetic purity benchmarks under Myanmar's national seed policy. These standards are disqualifying farmer-saved seed from government-supported irrigation schemes. Mandalay Region commercial operators are responding by consolidating procurement through registered seed dealers to maintain input subsidy eligibility.
Large-scale farming enterprises are abandoning decentralized village-level seed exchange in favor of direct contractual relationships with certified suppliers. Agricultural cooperatives in the Irrawaddy Delta are losing intermediary margins as 50-plus hectare operations negotiate volume discounts directly with hybrid seed distributors. This channel compression is most visible in Bago Region where commercial paddy expansion is concentrating buyer power.
Myanmar Rice Seed Market Segmentation
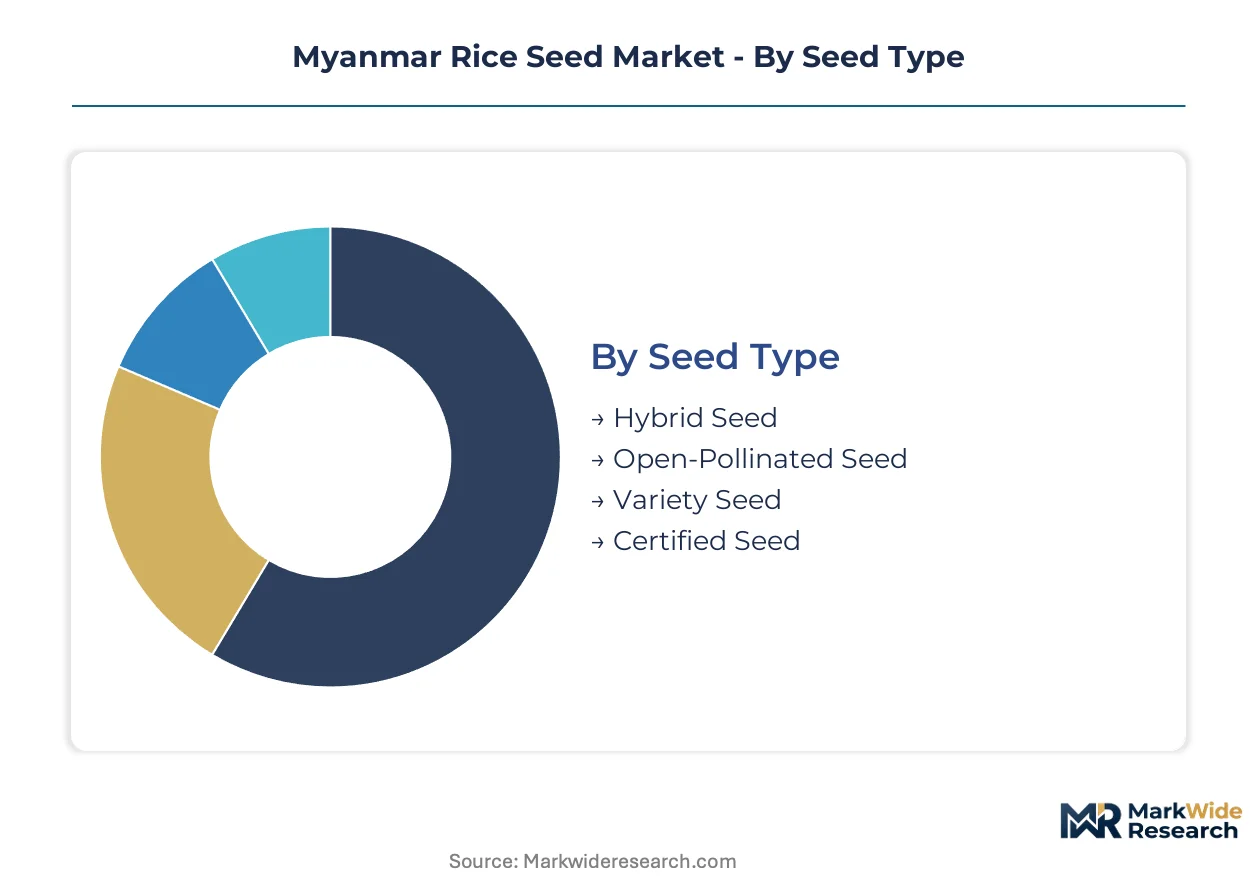
Myanmar's rice seed market fragments across seed genetics, procurement pathways, and end-user scale. Each dimension shapes pricing power, certification requirements, and distribution economics differently.
Seed Type:
Cost tier stratification separates premium genetics from commodity propagation material in farmer purchasing decisions.
- Hybrid Seed:Two-line and three-line systems deliver heterosis-driven yield advantages of 15-20 percent over conventional alternatives. Irrawaddy Delta commercial farms exceeding 50 hectares standardize on these varieties to secure export-grade milling premiums, though annual repurchase requirements strain smallholder liquidity.
- Certified Seed:Department of Agricultural Research protocols enforce 98 percent genetic purity and 85 percent germination benchmarks. Government irrigation scheme eligibility now hinges on certified procurement, compressing informal seed exchange in Yangon and Mandalay regions.
- Open-Pollinated Seed:Farmer-saved propagation material dominates marginal districts where input cost sensitivity overrides yield optimization.
- Variety Seed:Fixed-line genetics from DAR release committees serve intermediate adopters transitioning toward quality-assured systems.
Certified Seed commands the established base. The steepest expansion runs through Hybrid Seed.
Distribution Channel:
Channel selection reflects farm scale, credit access, and technical service requirements across Myanmar's agricultural landscape.
- Agricultural Cooperatives:Embedded credit channels and dense farmer networks capture smallholder demand in Shan State and central dry zone districts. Cooperative procurement aggregates volume for margin negotiation with registered seed dealers.
- Direct Sales:Seed companies bypass intermediaries to serve Irrawaddy and Bago region commercial enterprises. Volume discount structures and technical advisory bundling concentrate buyer power among 50-plus hectare operators.
- Retail Stores:Township-level agro-dealers maintain last-mile presence in fragmented geographies lacking cooperative infrastructure.
- Online Platforms:Digital ordering remains nascent, constrained by rural connectivity gaps and farmer preference for physical seed inspection.
Direct Sales is capturing margin concentration. Agricultural Cooperatives maintain the deepest penetration trajectory.
Application:
Farm scale determines input intensity, varietal selection, and certification compliance thresholds.
- Commercial Farming:Irrawaddy Delta and Bago region enterprises deploy hybrid systems with precision irrigation to fulfill export contract specifications. These operators drive certified seed demand spikes that outpace DAR foundation seed multiplication capacity.
- Smallholder Farming:Subsistence and semi-commercial operators across Magway and Mandalay regions balance cost constraints against yield stability, sustaining demand for certified variety seed in marginal rainfall districts.
- Research Purposes:DAR stations and university breeding programs consume foundation seed for varietal development and adaptive trials.
- Education:Agricultural extension training programs represent minimal volume but shape adoption pathways for next-generation farmers.
Smallholder Farming commands the established base. Commercial Farming registers the steepest expansion trajectory.
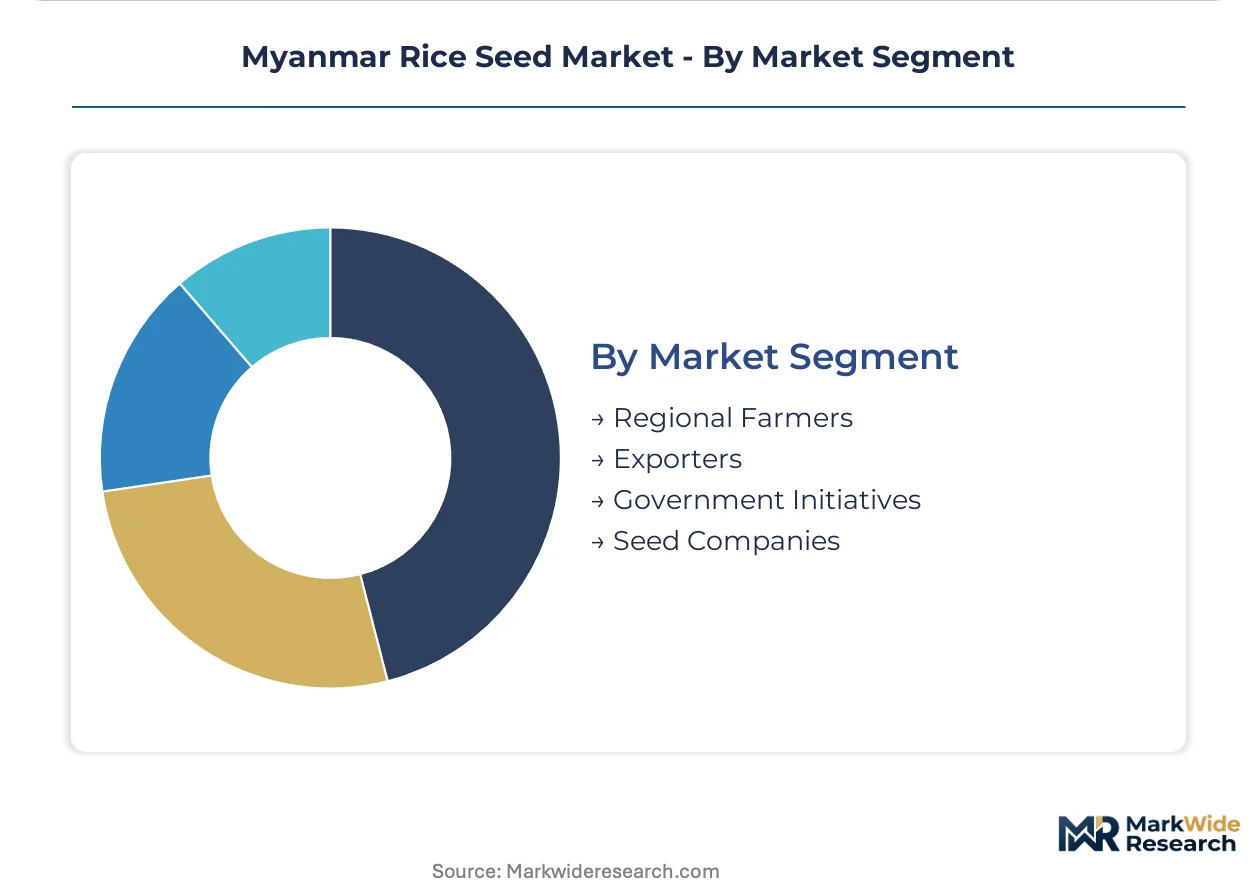
Market Segment:
Customer type alignment shapes pricing architecture and relationship investment intensity for seed suppliers.
- Regional Farmers:End-user demand aggregates across cooperative, retail, and direct channels with divergent service expectations and price elasticity profiles.
- Exporters:Milling and trading enterprises impose varietal specifications on contract farmers, transmitting quality requirements upstream to seed procurement decisions.
- Government Initiatives:Ministry of Agriculture and Irrigation subsidy programs and irrigation rehabilitation schemes create certified seed demand through eligibility mandates.
- Seed Companies:Myanma Awba Group and Yuan Longping High-Tech Agriculture anchor supply-side concentration, integrating germplasm development with distribution control.
Regional Farmers command the established base. Government Initiatives demonstrate the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hybrid seed distribution concentrates in the Irrawaddy Delta's commercial belt, while the central dry zone drives demand for drought-tolerant genetics. State-level irrigation investments and varietal approval timelines reshape procurement geography across Myanmar's agro-ecological zones.
Yangon Region
Commercial paddy enterprises exceeding 50 hectares dominate certified seed procurement here. The Department of Agricultural Research's seed certification protocols now disqualify uncertified varieties from government irrigation scheme eligibility. Thanlyin and Hlegu townships anchor direct sales channels as large operators bypass agricultural cooperatives for volume discounts.
Mandalay Region
Erratic monsoon patterns in this central dry zone district accelerate demand for short-duration aerobic rice varieties. The Ministry of Agriculture and Irrigation's varietal release committee fast-tracks heat-tolerant genetics for this agro-ecology. Meiktila and Yamethin sub-districts concentrate cooperative distribution networks reaching credit-constrained smallholders.
Ayeyarwady Region
The Irrawaddy Delta's irrigation rehabilitation compresses seed replacement cycles across commercial farms. BIS-aligned purity testing requirements enforce 98 percent genetic purity standards for certified grades. Pathein and Myaungmya townships host the densest hybrid seed adoption as export-grade milling contracts drive input intensification.
Bago Region
Commercial farm expansion here standardizes on two-line hybrid systems to capture yield premiums. Government procurement channel mandates now require certified seed documentation for subsidy access. Pyay and Taungoo districts register the steepest direct sales growth as 50-plus hectare operations consolidate buyer power.
Shan State
Agricultural cooperative networks maintain deepest penetration in this highland zone with fragmented farm structures. Embedded credit channels enable certified seed access for smallholders transitioning from farmer-saved propagation material. Taunggyi and Kalaw townships represent underpenetrated demand for quality-assured supply chains.
Myanmar Rice Seed Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in germplasm development and foundation seed multiplication. The Myanmar rice seed market structures around three archetypes: integrated agribusiness conglomerates controlling distribution infrastructure, multinational breeders licensing proprietary hybrid systems, and domestic seed multipliers serving cooperative networks. Competitive moves concentrate on backward integration into captive foundation seed supply and direct contractual relationships with commercial farming enterprises.
Within the integrated conglomerate tier, Myanma Awba Group anchors distribution control across the Ayeyarwady basin. Yuan Longping High-Tech Agriculture Co. Ltd exemplifies the multinational breeder archetype, occupying a position in proprietary two-line hybrid rice systems. Bayer AG sits within the diversified agricultural input platform category, representing extension into digital farming advisory services.
| Leading Market Players |
|---|
| Myanma Awba Group |
| Yuan Longping High-Tech Agriculture Co. Ltd |
| Bayer AG |
| Syngenta AG |
| Myanmar Agribusiness Public Corporation (MAPCO) |
| Dagon Group of Companies |
| SL Agritech Corporation (SLAC) |
| Corteva |
| Groupe Limagrain |
| Others |
Supply & Pricing Matrix
Pathein township's hybrid seed multiplication capacity constrains downstream pricing power as commercial farms compete for limited certified volumes. The Department of Agricultural Research's foundation seed bottlenecks transmit cost pressure through registered dealer networks.
Pricing Analysis
Myanmar's national seed policy dictates the pricing tier structure across certified, variety, and open-pollinated grades. Three-tier pricing structure across premium hybrid, standard certified, and economy farmer-saved levels separates export-grade commercial operators from subsistence smallholders. Cost compression in hybrid tiers is intensifying because DAR foundation seed supply cannot scale to meet demand spikes from Irrawaddy Delta commercial farms. Smallholders in Magway and Mandalay regions exhibit highest price sensitivity, while 50-plus hectare operators in Yangon Region show lowest elasticity due to export contract yield premiums.
Supply Chain Analysis
Extended payment terms from seed companies to agricultural cooperatives lubricate working capital for credit-constrained smallholders. Germplasm development draws from China, foundation seed multiplication rests on DAR stations in Myanmar, and commercial distribution centers on Yangon and Mandalay regional hubs. Supply chain risk centers on single-source vulnerability for two-line hybrid system imports subject to cross-border phytosanitary disruptions. Distribution runs through direct sales channels for commercial farms and cooperative networks for smallholder aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Irrawaddy Delta commercial farms exceeding 50 hectares, fragmenting procurement relationships and compressing intermediary margins across agricultural cooperatives.
For Market Incumbents: Pre-empt foundation seed supply bottlenecks by securing captive multiplication agreements with DAR stations in Ayeyarwady and Bago regions. Channel control through direct contractual relationships with commercial farms defends margin pools against cooperative disintermediation. Certification investment in BIS-aligned purity testing protocols maintains eligibility for government irrigation scheme procurement channels.
For New Entrants and Emerging Players: Establish a beachhead in Shan State's cooperative networks where embedded credit channels reach credit-constrained smallholders transitioning from farmer-saved seed. Magway Region's underpenetrated demand for short-duration aerobic rice varieties offers white-space expansion. Go-to-market through agricultural cooperative technical advisory bundling builds farmer loyalty before scaling to direct sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated agribusiness conglomerates controlling distribution infrastructure across the Ayeyarwady basin. Long-term viability hinges on backward integration into captive foundation seed supply and climate-adaptive breeding pipelines. Watch DAR varietal release committee fast-track approvals for heat-tolerant genetics as inflection indicator for dry zone market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundation Seed Multiplication | Captive supply from DAR stations secures certified genetics access for commercial farm contracts. |
| Direct Sales Channel Expansion | Bypassing agricultural cooperatives captures margin pools from 50-plus hectare operators in Bago Region. |
| Climate-Adaptive Breeding Investment | Drought-tolerant varieties unlock planting windows in Magway and Mandalay marginal rainfall districts. |
| Cooperative Credit Facility Partnerships | Embedded financing in Shan State networks reaches smallholders locked out of formal banking. |
| Digital Farming Advisory Platform Launch | Technical service bundling differentiates hybrid seed offerings beyond yield premiums alone. |
Research Methodology
A spread of perspectives from seed company distribution managers, agricultural cooperative procurement officers, DAR certification specialists, and commercial farm operators converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from Ministry of Agriculture and Irrigation policy documents, BIS-aligned testing protocols, customs trade records, and irrigation rehabilitation schedules. Bottom-up seed volume estimates from regional distribution channels triangulated against top-down market sizing from national paddy production statistics.
Demand-supply balance modeling across the projection horizon incorporated seed type segmentation by genetics tier, distribution channel fragmentation, farm scale application intensity, and regional agro-ecological clustering. CAGRs were derived from fitted growth curves against historical adoption patterns and infrastructure investment pipelines. Forecast inputs included DAR varietal release timelines, irrigation rehabilitation completion schedules, and commercial farm consolidation trajectories.
Stress conditions across foreign exchange volatility, cross-border phytosanitary disruption, and fertilizer price fluctuation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification protocol enforcement and infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
North America Forage Seed Market
Seeds
Global Sports Turf Seed Market
Seeds
Global Rice Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Global Grain Seed Market
Seeds
Garden Seeds Market
Seeds
Vietnam Seed Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
Cowpeas Market
Seeds
Fruit Tomatoes Seed Market
Seeds
United States Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Europe Sesame Seed Market
Seeds
Pumpkin Seeds Market
Seeds
Organic Seed Market
Seeds
Europe Chia Seeds Market