
 Low Fat Rice Market | 2026-2036
Low Fat Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Rice Market Analytics
Subscription-based replenishment services for low fat rice varieties is broadening what suppliers sell beyond one-time retail transactions. Ricegrowers Limited leverages its Australian milling infrastructure to supply consistent parboiled grades into Asian export channels. Nestiva sustains product differentiation through glycemic-index certification and specialized packaging for diabetic consumer segments. Chaman Lal Setia Exports Ltd. anchors its competitive position in premium Basmati variants with controlled fat profiles for Middle Eastern and European buyers.
Low fat rice denotes milled or parboiled rice grains processed to reduce lipid content, typically achieving below 0.5% fat composition through controlled steam-pressure treatment and bran-layer reduction while preserving amylose structure for slower carbohydrate release. Manufacturers deploy modified atmospheric packaging to extend shelf stability of these reduced-fat grains in humid climates. Brown rice within product type segments leads volume due to retained fiber appeal, while Basmati rice commands premium positioning in restaurant and catering channels where aroma and elongation properties justify higher procurement costs. Online retail as a distribution channel captures accelerating household demand as direct-to-consumer platforms reduce intermediary markups on certified low fat grades.
The Food Safety and Standards Authority of India mandates nutritional labeling disclosures that compel processors to verify and declare fat percentages on packaged rice, directly shaping product formulation investments. EFSA in Europe enforces contaminant thresholds for heavy metals and pesticide residues that determine which Asian-origin low fat rice batches gain market access. FSSAI's evolving standards on whole-grain claims and glycemic index disclosures will force stakeholders to monitor regulatory alignment between production geography and destination market requirements.
Market Dynamics
Parboiling technology advances are compressing processing costs while FSSAI fortification mandates force processors to reconfigure milling lines, creating a bifurcation between compliant integrated mills and legacy operations facing retrofit burdens.
Growth Catalysts
- Urban household dietary pivot:Fitness-conscious consumers in Mumbai, Bangalore, and Delhi NCR are substituting brown rice for white varieties as staple carbohydrates, expanding addressable volume for controlled-fat processors.
- FSSAI fortification guidelines:India's packaged staple regulations mandate nutritional transparency, compelling retail-format processors to verify and label fat percentages, which accelerates formal channel penetration.
- Parboiling steam-pressure systems:Advanced milling infrastructure achieves below 0.5% fat retention while preserving amylose structure, enabling slower glycemic release claims that command premium positioning.
Market Restraints
- Input cost volatility:Paddy procurement prices fluctuate with monsoon patterns across Punjab and Haryana, squeezing margin predictability for millers without long-term grower contracts.
- EFSA contaminant thresholds:European heavy metal and pesticide residue limits block substantial Asian-origin batches from EU market access, fragmenting export economics.
- Technical limitation in bran reduction:Aggressive fat stripping degrades grain integrity, limiting minimum achievable fat levels without unacceptable breakage rates during handling.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-consumer platforms bypass traditional wholesale markups, capturing recurring household demand for certified low fat grades in metropolitan corridors.
- Diabetic consumer segmentation:Glycemic-index certification creates specialized packaging opportunities for medical-nutrition channels underserved by generic rice brands.
- Modified atmospheric packaging:Humidity-resistant barrier technologies extend shelf stability in tropical climates, opening inventory-holding possibilities for modern trade retailers.
Industry Challenges
- Certification timeline compression:FSSAI's evolving whole-grain claim standards and glycemic index disclosure rules force simultaneous compliance tracking across multiple regulatory drafts.
- Capex intensity for mill retrofitting:Steam-pressure parboiling installation requires substantial capital outlay that mid-tier processors struggle to finance without external credit.
- Skill gap in quality assurance:Fat percentage verification and contaminant testing demand laboratory capabilities scarce in traditional rice-growing belts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Rice Market |
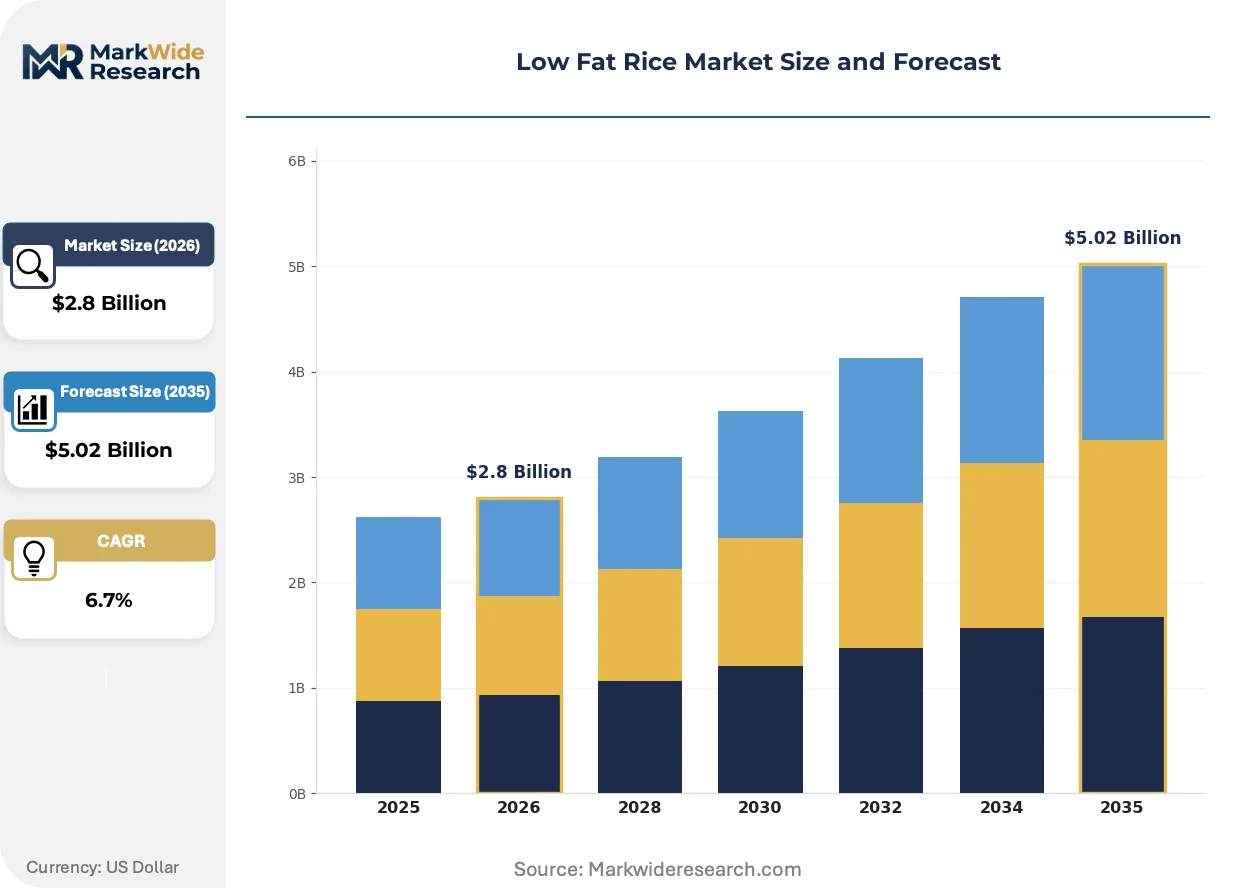
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brown Rice, White Rice, Basmati Rice, Jasmine Rice End User: Households, Restaurants, Cafes, Catering Services Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bags, Boxes, Pouches, Bulk |
| Companies Covered | Ricegrowers Limited, Nestiva, Chaman Lal Setia Exports Ltd., SDLG Radiant Pvt. Ltd., Sugar Watchers Low GI Staples, First Choice Food Products Pvt Ltd., Parish Rice, The Little Rice Company, Siam Lotus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Rice Market Evolving Landscape
Processing technology and distribution infrastructure are converging to redefine how low fat rice reaches end consumers, with regulatory disclosure requirements accelerating formalization of previously informal supply relationships.
Advanced parboiling systems incorporating precision steam-pressure control are rewriting the economics of fat-reduced grain production. Restaurant and catering buyers in premium Basmati channels are adopting these grades at accelerating pace. The technology is compressing quality variation between batches, enabling consistent supply contracts previously impossible with conventional milling.
FSSAI's nutritional labeling mandates for packaged staples are forcing disclosure investments across the processor base. Millers must now maintain laboratory verification capabilities to declare fat percentages on retail packaging. Urban modern trade formats are responding by expanding shelf space for certified grades that satisfy audit requirements.
Direct-to-consumer platforms are disintermediating traditional wholesale channels for household rice purchases. Subscription-based replenishment models capture recurring demand in health-focused consumer segments. This shift is most visible in Mumbai, Bangalore, and Delhi NCR where digital payment penetration supports automated reordering systems.
Low Fat Rice Market Segmentation
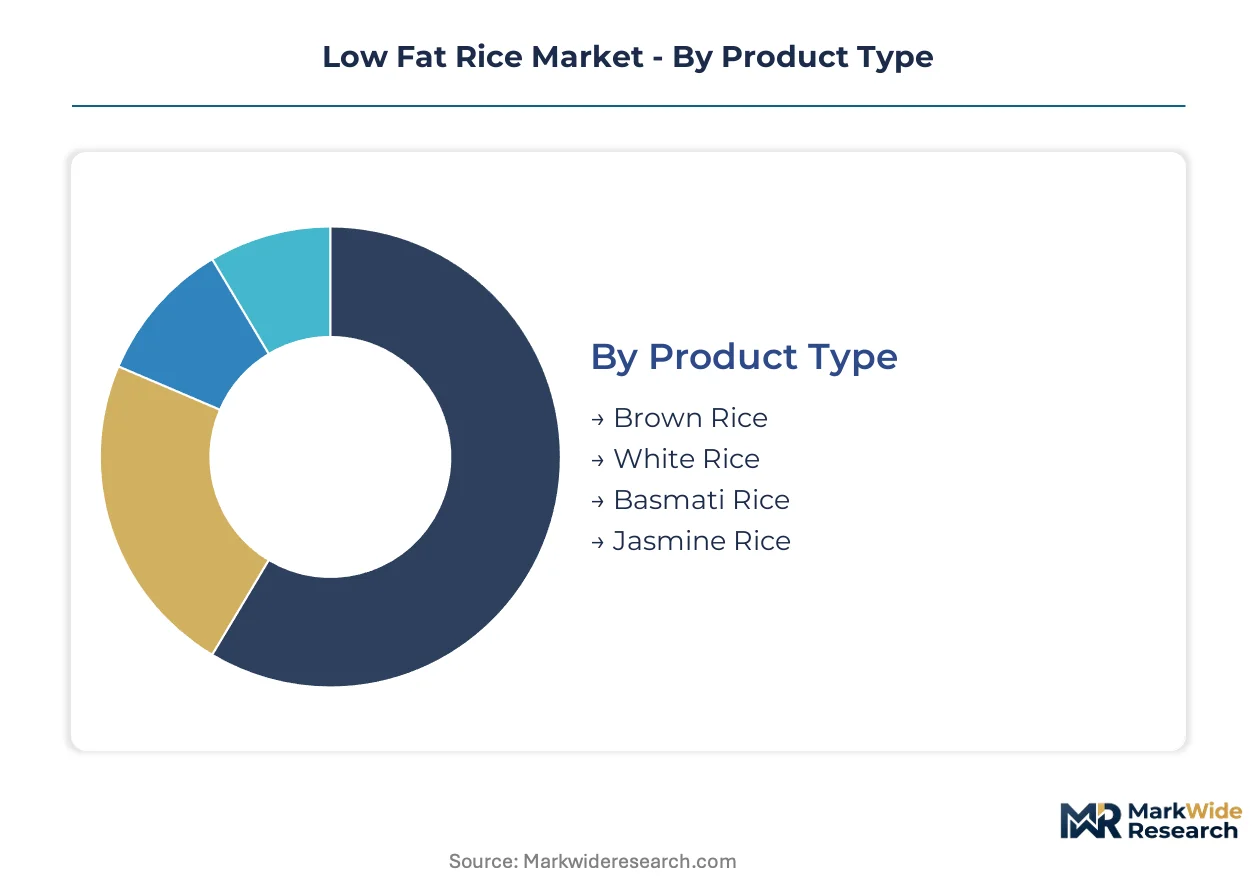
Low fat rice processors configure product portfolios across four distinct category axes, each carrying unique certification burdens and margin structures. Understanding how FSSAI fortification mandates and EFSA contaminant thresholds apply differentially across these segments determines viable market entry strategies.
Product Type:
Brown rice variants demand FSSAI whole-grain claim verification and glycemic index disclosure compliance, while Basmati exports to Europe trigger EFSA heavy metal testing protocols.
- Brown Rice:Retains bran layer with fiber content above 2% and fat composition typically 2.5-3%, requiring modified atmospheric packaging to prevent rancidity in humid climates. Fitness-conscious households in Mumbai and Bangalore drive volume as staple replacement for white varieties, with FSSAI fortification guidelines mandating nutritional transparency on retail labels.
- Basmati Rice:Aromatic long-grain varieties processed through controlled steam-pressure parboiling achieve below 0.5% fat while preserving elongation properties. Restaurant and catering channels in Delhi NCR absorb premium grades where aroma justifies higher procurement costs, though EFSA pesticide residue thresholds block substantial batches from EU access.
- White Rice:Fully milled grains with bran and germ removed, achieving minimal fat content through conventional processing without specialized steam-pressure infrastructure.
- Jasmine Rice:Fragrant Thai-origin varieties gaining traction in specialty retail formats, typically parboiled for fat reduction while retaining distinctive floral notes.
Brown rice sits at the top of the volume ranking, with Basmati rice climbing the fastest among premium-positioned segments.
End User:
Procurement patterns diverge sharply between recurring household replenishment and institutional bulk contracts, with certification documentation requirements scaling accordingly.
- Households:Individual consumers purchasing 5-25kg units through modern trade or subscription platforms, with FSSAI packaged staple regulations driving formal channel migration.
- Restaurants:Premium Basmati grades dominate where elongation and aroma properties command price premiums, with consistent batch quality enabling multi-year supply agreements.
- Cafes:Smaller-format foodservice operators seeking portion-controlled packaging with glycemic-index certification for health-positioned menu items.
- Catering Services:High-volume institutional buyers requiring bulk procurement with contaminant testing documentation for large-scale event provisioning.
Households generate the dominant revenue share, though restaurants exhibit the steepest expansion trajectory as premium channel penetration deepens.
Distribution Channel:
Channel selection determines margin capture and regulatory exposure, with direct-to-consumer platforms bypassing wholesale markups while assuming labeling compliance burdens.
- Supermarkets:Modern trade formats in metropolitan corridors expanding shelf space for certified low fat grades, with FSSAI audit requirements favoring established processors.
- Online Retail:Subscription-based replenishment platforms capturing recurring demand in Mumbai, Bangalore, and Delhi NCR through automated reordering systems.
- Specialty Stores:Health-focused retail formats emphasizing glycemic-index certification and organic claims for diabetic consumer segments.
- Wholesale:Traditional mandi channels serving price-sensitive bulk buyers with minimal certification documentation, facing displacement pressure from formal retail.
Supermarkets maintain volume leadership, with online retail gaining share fastest as digital payment penetration enables subscription model adoption.
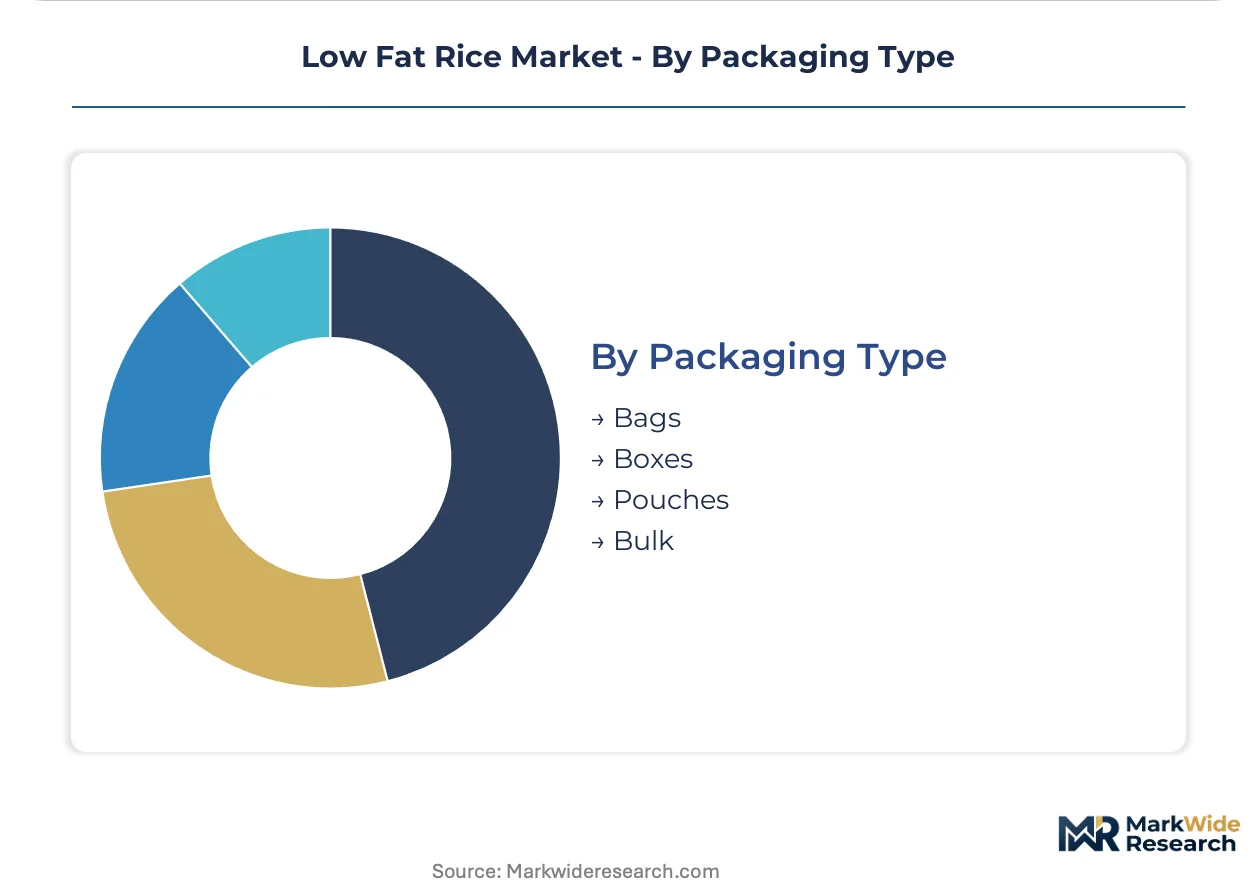
Packaging Type:
Packaging technology investments correlate directly with shelf stability requirements in tropical climates and regulatory labeling mandates.
- Bags:Standard woven polypropylene units for bulk procurement, offering minimal barrier protection and requiring rapid inventory turnover.
- Boxes:Rigid packaging for premium retail presentation, accommodating detailed nutritional labeling and glycemic-index certification displays.
- Pouches:Modified atmospheric barrier technologies extending shelf stability through humidity-resistant films, enabling modern trade inventory holding.
- Bulk:Loose grain procurement for institutional buyers with captive milling capabilities, bypassing retail packaging costs but assuming contaminant testing responsibilities.
Bags dominate absolute volume, with pouches expanding most quickly as humidity-resistant technologies penetrate metropolitan retail formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India commands household volume through fitness-conscious urban adoption, while Australia leverages parboiling infrastructure to supply Asian export corridors with consistent fat-controlled grades.
India
FSSAI fortification guidelines mandate nutritional labeling on packaged staples, compelling millers in Punjab and Haryana to verify fat percentages for retail distribution. Mumbai, Bangalore, and Delhi NCR absorb premium brown rice variants as staple replacements, with modern trade formats expanding certified product shelf space.
Australia
Ricegrowers Limited anchors milling infrastructure that supplies parboiled grades into Asian export channels with below 0.5% fat retention. The country's steam-pressure processing capabilities enable consistent batch quality for restaurant and catering procurement in Singapore and Hong Kong.
Thailand
Jasmine rice processors deploy modified atmospheric packaging to extend shelf stability in humid tropical climates for Middle Eastern export markets. Bangkok-centered millers face EFSA contaminant threshold barriers that block substantial batches from EU access, fragmenting revenue geography.
United Arab Emirates
Dubai's logistics hub position enables re-export of Indian and Pakistani Basmati variants to European and African buyers. MOHAP food safety standards require contaminant documentation that favors established processors with laboratory verification capabilities over informal traders.
United Kingdom
London's restaurant and catering channels absorb premium Basmati grades where aroma and elongation properties justify higher procurement costs. EFSA pesticide residue limits determine which Asian-origin batches gain market access, with compliant shipments concentrating in specialist South Asian retail formats.
Low Fat Rice Market Competitive Landscape
Top-tier vendors anchor premium Basmati and certified low-fat segments, while mid-tier millers compete on parboiled volume for institutional buyers. The vendor base spans integrated agricultural conglomerates with captive paddy supply, specialized export houses targeting Middle Eastern and European channels, and direct-to-consumer platforms capturing subscription replenishment in metropolitan India. Competitive moves concentrate on steam-pressure technology licensing for fat reduction consistency and backward integration into paddy procurement to buffer input cost volatility.
Among Australia-based agricultural enterprises, Ricegrowers Limited occupies a position representing integrated milling infrastructure, while Nestiva exemplifies glycemic-index certification specialization for diabetic consumer segments. Chaman Lal Setia Exports Ltd. anchors the premium export house archetype, with these three entities collectively illustrating how geographic origin and certification focus determine competitive positioning across distinct demand channels.
| Leading Market Players |
|---|
| Ricegrowers Limited |
| Nestiva |
| Chaman Lal Setia Exports Ltd. |
| SDLG Radiant Pvt. Ltd. |
| Sugar Watchers Low GI Staples |
| First Choice Food Products Pvt Ltd. |
| Parish Rice |
| The Little Rice Company |
| Siam Lotus |
| Others |
Value Network & Pricing Analysis
FSSAI fortification guidelines gate qualified supply and premium-tier pricing access by mandating laboratory verification capabilities that only integrated mills possess, forcing mid-tier processors into lower-margin wholesale channels or expensive retrofit investments.
Pricing Analysis
Capacity additions in Punjab and Haryana are reshaping price floors as steam-pressure parboiling infrastructure expands among integrated millers. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-certified retail grades from mandi-channel commodities and export-rejected batches. Cost compression in standard tiers is intensifying because paddy procurement volatility squeezes margin predictability for millers lacking long-term grower contracts. Households through subscription platforms exhibit lowest price sensitivity, while institutional catering buyers negotiate hardest on volume contracts.
Supply Chain Analysis
Direct-to-consumer channels handle metropolitan household demand in Mumbai, Bangalore, and Delhi NCR through automated replenishment platforms. Geographic supply concentrates in India, Thailand, and Australia, with each node serving distinct certification requirements and buyer archetypes. Raw material flows draw from Punjab and Haryana paddy belts, Thai jasmine rice zones, and Australian Riverina irrigation districts. Single-source vulnerability runs through monsoon-dependent Indian procurement, where rainfall variability disrupts input availability without diversified sourcing. Distribution runs through modern trade formats for certified grades and traditional mandi networks for undocumented bulk flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FSSAI's evolving whole-grain claim standards and glycemic index disclosure rules continuously force formulation investments that deepen incumbent advantages.
For Market Incumbents: To counter mid-tier miller retrofit completion, anchor premium positioning through captive paddy procurement in Punjab and Haryana that buffers input cost volatility. Deepen channel control by licensing steam-pressure technology to smaller processors, converting competitive threats into revenue streams while maintaining quality gatekeeping.
For New Entrants and Emerging Players: Precision glycemic-index certification technology offers entry into diabetic consumer segments underserved by generic rice brands. Target specialty retail formats in metropolitan India where health-positioned menu items at cafes create pull-through demand. Pursue white-label manufacturing partnerships with established modern trade chains seeking private-label certified grades.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier millers facing FSSAI compliance burdens but possessing intact distribution relationships. Five-to-ten year viability favors processors with backward integration into paddy procurement and laboratory verification capabilities. Watch EFSA contaminant threshold enforcement as the signal indicating which Asian-origin batches gain European market access and premium export economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Steam-Pressure Technology Licensing | Converts competitive retrofit pressure into recurring royalty revenue from mid-tier millers. |
| Backward Integration into Paddy Procurement | Captive supply from Punjab and Haryana buffers margin volatility from monsoon-driven price swings. |
| Glycemic-Index Certification Investment | Unlocks medical-nutrition channel access for diabetic consumer segments in metropolitan India. |
| Direct-to-Consumer Platform Launch | Subscription replenishment in Mumbai, Bangalore, and Delhi NCR bypasses wholesale markups. |
| Modified Atmospheric Packaging Adoption | Humidity-resistant barrier films extend shelf stability for modern trade inventory holding. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rice mill operations heads, FSSAI compliance officers, modern trade category buyers, and export house logistics managers with secondary validation from FSSAI fortification guidelines, EFSA contaminant threshold documentation, customs trade flows, and food processing sector filings. Bottom-up volume modeling across product types and end users triangulated against top-down market sizing from production capacity assessments.
Historical reference periods anchored the projection horizon through trend extrapolation and structural breakpoint analysis. Segmentation dimensions modeled include product type, end user archetype, distribution channel, and packaging technology across the analysis window. CAGRs derived from fitted growth curves incorporating parboiling technology adoption rates, FSSAI compliance timeline assumptions, and urban household dietary pivot indicators.
The model holds under stable regulatory enforcement intensity; deviation in FSSAI disclosure rule acceleration or EFSA threshold tightening would shift volume trajectories between formal and informal channels. Forecasts reflect assumptions about technology diffusion rates and certification cost structures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Soya Flour Market
Grains
Basmati Rice Market
Grains
Tunisia Grain Market
Grains
South Africa Maize Market
Grains
Asia-Pacific Guar Market
Grains
Pea Grits Market
Grains
Lentil Market
Grains
South America Wheat Market
Grains
Corn Silage Market
Grains
Grain Dryers Market
Grains
Black Gram Market
Grains
South American Maize Market
Grains
Africa Maize Market
Grains
Organic Rice Flour Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Gluten Free Ancient Grain Market