
 Guar Complex Market | 2026-2036
Guar Complex Market Size, Share, and Industry Trends Forecast 2026-2036
Guar Complex Market Foresight
A capital-intensity divergence between integrated processors and trading-dependent operators is reorganizing competitive tiers in the Guar Complex Market. Hindustan Gum and Chemicals Limited leverages captive guar seed sourcing across northwestern India to sustain margin stability. Vikas WSP Limited anchors its position through dedicated R&D facilities for modified guar derivatives. Ashland Global Holdings Inc. competes on pharmaceutical-grade gum specifications for controlled-release drug formulations.
Guar Complex encompasses the full value chain derived from Cyamopsis tetragonoloba seeds, comprising approximately 35-40% galactomannan polysaccharide content that hydrates in cold water to yield viscous colloidal solutions. The primary industrial purpose centers on rheology modification across hydraulic fracturing, food stabilization, and pharmaceutical binding applications. Guar gum powder commands the dominant value share due to premium pricing in oilfield and pharma applications, while guar meal expands as the fastest-growing category driven by ruminant feed protein demand. Oil and gas extraction represents the most margin-concentrated application segment, though food industry volumes provide demand baseload during energy sector cyclicality.
India's BIS and the FSSAI govern domestic processing standards, while REACH compliance in Europe and FDA food additive regulations in the US shape export market access and certification requirements. India's DGFT export policy on guar gum derivatives directly influences international supply availability and pricing benchmarks. Stakeholders must monitor regulatory divergence between food-grade and industrial-grade specifications as sustainability disclosure requirements intensify across buyer jurisdictions.
Market Dynamics
Capital-intensity divergence between integrated processors and trading-dependent operators is reorganizing competitive tiers across the Guar Complex Market, as captive seed sourcing and dedicated R&D facilities separate margin-stable leaders from price-takers.
Growth Catalysts
- PLI Scheme for Processed Agricultural Exports:India's production-linked incentive scheme subsidizes guar gum derivative manufacturing, expanding processing capacity in Rajasthan's industrial clusters.
- Hydraulic Fracturing Fluid Demand:Oil service providers in North American shale basins continue expanding guar gum consumption for rheology modification in high-pressure well completions.
- Ruminant Feed Protein Substitution:Guar meal is displacing soybean meal in dairy and beef cattle rations across Middle Eastern and Southeast Asian markets due to cost-advantaged amino acid profiles.
Market Restraints
- Monsoon-Dependent Seed Supply:Rajasthan and Gujarat account for over 80% of Indian guar seed output, concentrating climate risk in a narrow geographic band with erratic rainfall patterns.
- Synthetic Polymer Substitution:Xanthan gum and cellulose derivatives compete in food stabilization and oilfield applications, eroding price-premium capture in commoditized grades.
- REACH Compliance Burden:ECHA registration requirements for guar gum derivatives impose testing costs that exclude smaller Indian exporters from European pharmaceutical and industrial markets.
Strategic Opportunities
- Controlled-Release Pharmaceutical Binding:Modified guar derivatives for oral dosage formulations face limited qualified suppliers, opening margin capture in FDA-regulated drug delivery systems.
- BIS Quality Mandate Arbitrage:India's tightened domestic standards create dual-track certification capability that premium processors can monetize in export markets demanding traceability.
- Cluster Infrastructure Integration:Rajasthan's processing belt offers co-location economies for integrated gum and meal production, reducing logistics costs versus dispersed trading operations.
Industry Challenges
- Galactomannan Consistency Control:Seed-to-seed variation in polysaccharide content requires real-time process adjustment that legacy solvent-extraction equipment cannot automate.
- Dual-Grade Certification Timeline:Separate FSSAI food-grade and industrial-grade validation pathways extend product launch cycles by 8-14 months for multiproduct processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guar Complex Market |
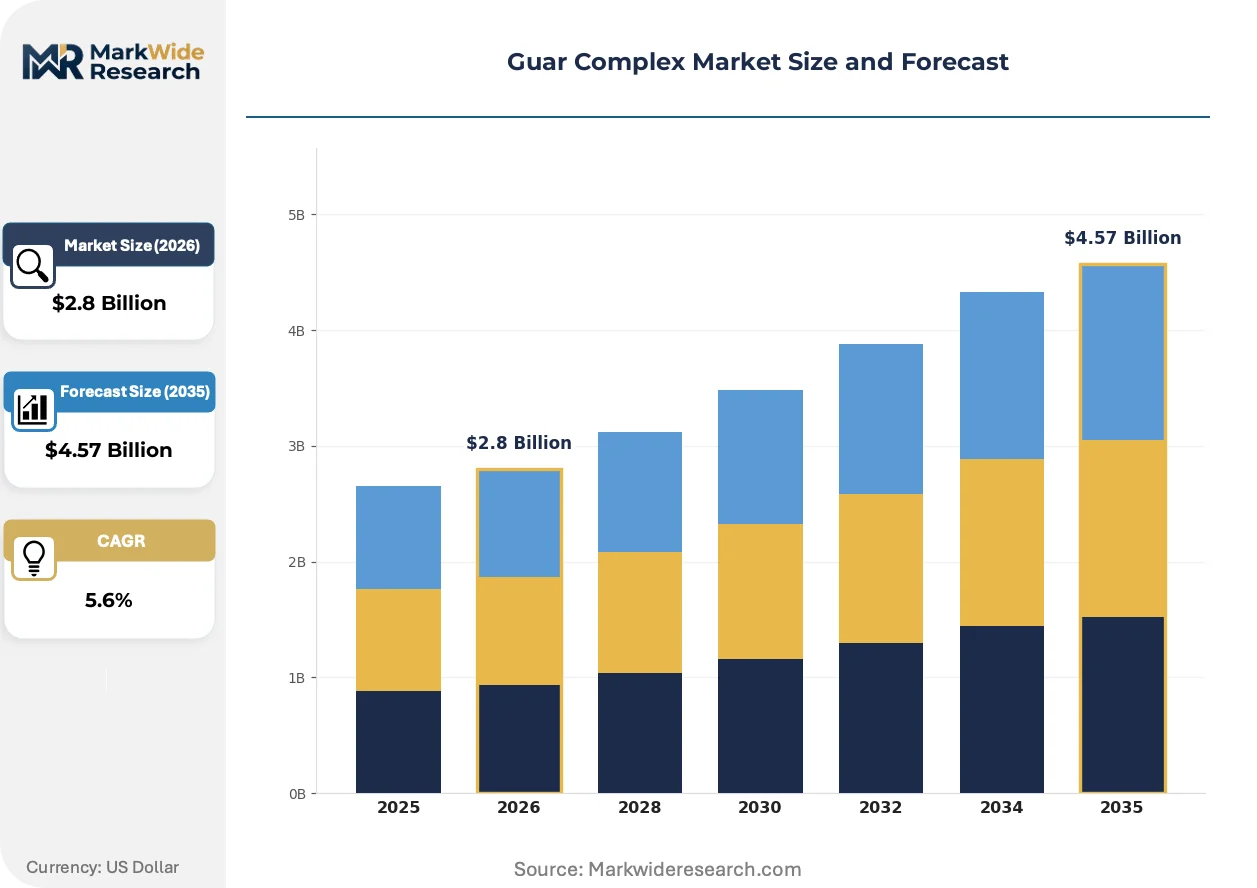
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guar Gum, Guar Meal, Guar Splits, Guar Powder Application: Food Industry, Cosmetic Products, Pharmaceutical Manufacturing, Oil & Gas Extraction Form: Powdered, Granulated, Liquid, Flakes End User: Food Manufacturers, Pharmaceutical Companies, Oil Service Providers, Personal Care Brands |
| Companies Covered | Hindustan Gum and Chemicals Limited, Vikas WSP Limited, Ashland Global Holdings Inc., Jai Bharat Gum and Chemicals Ltd., Lucid Group, India Glycols Limited, Agro Gums, Cargill, Lamberti S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guar Complex Market Shifts & Advancements
Enzymatic modification and cold-water hydration technologies are displacing conventional heat-processed guar derivatives, while regulatory disclosure requirements and buyer consolidation reshape value capture across the supply chain.
Carboxymethyl guar and hydroxypropyl guar derivatives are displacing unmodified gum powder in premium oilfield formulations. Shale operators in the Permian and Bakken basins specify these grades for enhanced thermal stability in high-salinity fracture fluids. The shift is compressing margins for commodity gum processors lacking enzymatic modification capability.
REACH substance registration deadlines and EU Green Deal sustainability disclosure rules are tightening traceability requirements for Indian exporters. ECHA compliance now mandates full supply chain documentation from seed sourcing through derivative processing. Pharmaceutical-grade guar gum faces the steepest certification escalation, with European formulators demanding carbon footprint audits alongside traditional purity specifications.
Oilfield service companies are consolidating procurement through long-term offtake agreements with integrated processors, bypassing traditional trading intermediaries. Halliburton and Schlumberger affiliates now contract directly with Rajasthan-based manufacturers for modified derivative supply. The disintermediation is most advanced in North American shale plays, where just-in-time logistics favor single-source relationships over spot-market purchasing.
Guar Complex Market Segmentation
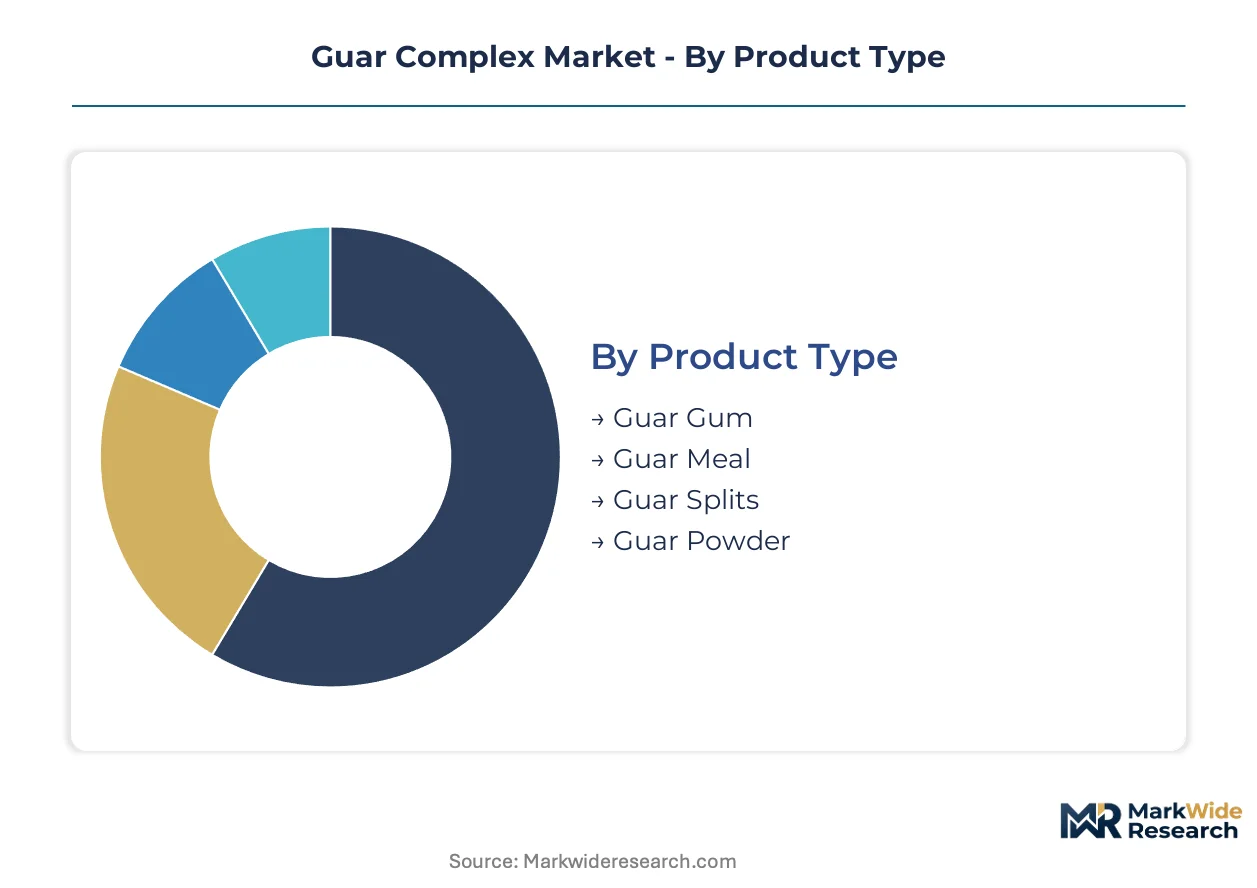
Guar Complex value capture varies sharply across product grades and end-use specifications. Segmentation reveals where margin stability concentrates versus where volume expansion accelerates.
Product Type:
Domestic consumption centers on guar meal for regional livestock feed, while guar gum derivatives dominate export value to North American oilfield and European pharmaceutical buyers.
- Guar Gum:Cold-water soluble galactomannan polysaccharide extracted from guar seeds. Oil service providers in the Permian Basin specify modified derivatives for high-salinity fracture fluid rheology, though synthetic polymer substitution from xanthan gum erodes pricing power in commoditized food grades.
- Guar Meal:Protein-rich byproduct of gum extraction containing 35-45% crude protein. Dairy and beef cattle operations across Saudi Arabia and Vietnam are displacing soybean meal due to cost-advantaged amino acid profiles and lower anti-nutritional factor content.
- Guar Splits:Dehusked guar seed endosperm serving as intermediate feedstock for gum powder production. Rajasthan processing clusters in Jodhpur and Bikaner concentrate split manufacturing for captive use by integrated derivative producers.
- Guar Powder:Finely milled gum product standardized to viscosity specifications for industrial applications. REACH-registered grades command premium positioning in EU pharmaceutical binding applications.
Guar gum commands the established base. The steepest expansion runs through guar meal.
Application:
Cost-tier differentiation separates commodity food stabilizers from premium pharmaceutical and oilfield specifications requiring modified derivative capability.
- Food Industry:Hydrocolloid stabilization in dairy beverages, baked goods, and processed meats. FSSAI-mandated purity specifications for domestic Indian consumption diverge from Codex Alimentarius export standards, creating dual-track certification burdens for multiproduct processors.
- Oil & Gas Extraction:Rheology modification in hydraulic fracturing fluids for shale completions. Carboxymethyl and hydroxypropyl guar derivatives specified by Halliburton and Schlumberger affiliates for thermal stability above 120°C in high-pressure well environments.
- Pharmaceutical Manufacturing:Controlled-release tablet binding and sustained-drug delivery matrices. FDA drug master file requirements and EMA excipient certification restrict qualified supplier pools to processors with dedicated GMP facilities.
- Cosmetic Products:Emulsion stabilization in skin creams and hair conditioning formulations. Personal care brands in South Korea and Brazil source hydroxypropyltrimonium chloride guar for cationic conditioning performance.
Food industry volumes provide demand baseload. The fastest value appreciation concentrates in pharmaceutical manufacturing.
Form:
Customer-type preferences drive form selection, with oilfield service companies favoring liquid dispersions for just-in-time logistics while food manufacturers standardize on powdered grades for dry-blend compatibility.
- Powdered:Spray-dried gum product with standardized particle size distribution for dry-mix applications. Dominates food industry procurement due to extended shelf stability and ease of bulk handling.
- Liquid:Pre-hydrated gum dispersions with biocide preservation for immediate-use oilfield applications. Eliminates on-site hydration equipment requirements at remote well pad locations.
- Granulated:Agglomerated powder with reduced dusting characteristics for pharmaceutical tableting operations. Improves flowability in high-speed compression equipment.
- Flakes:Thin-sheet dried gum for specialized film-forming cosmetic applications. Limited volume niche serving mask and peel formulations in Japanese personal care markets.
Powdered form anchors procurement volumes. Liquid formulations are climbing the fastest on oilfield logistics efficiency.
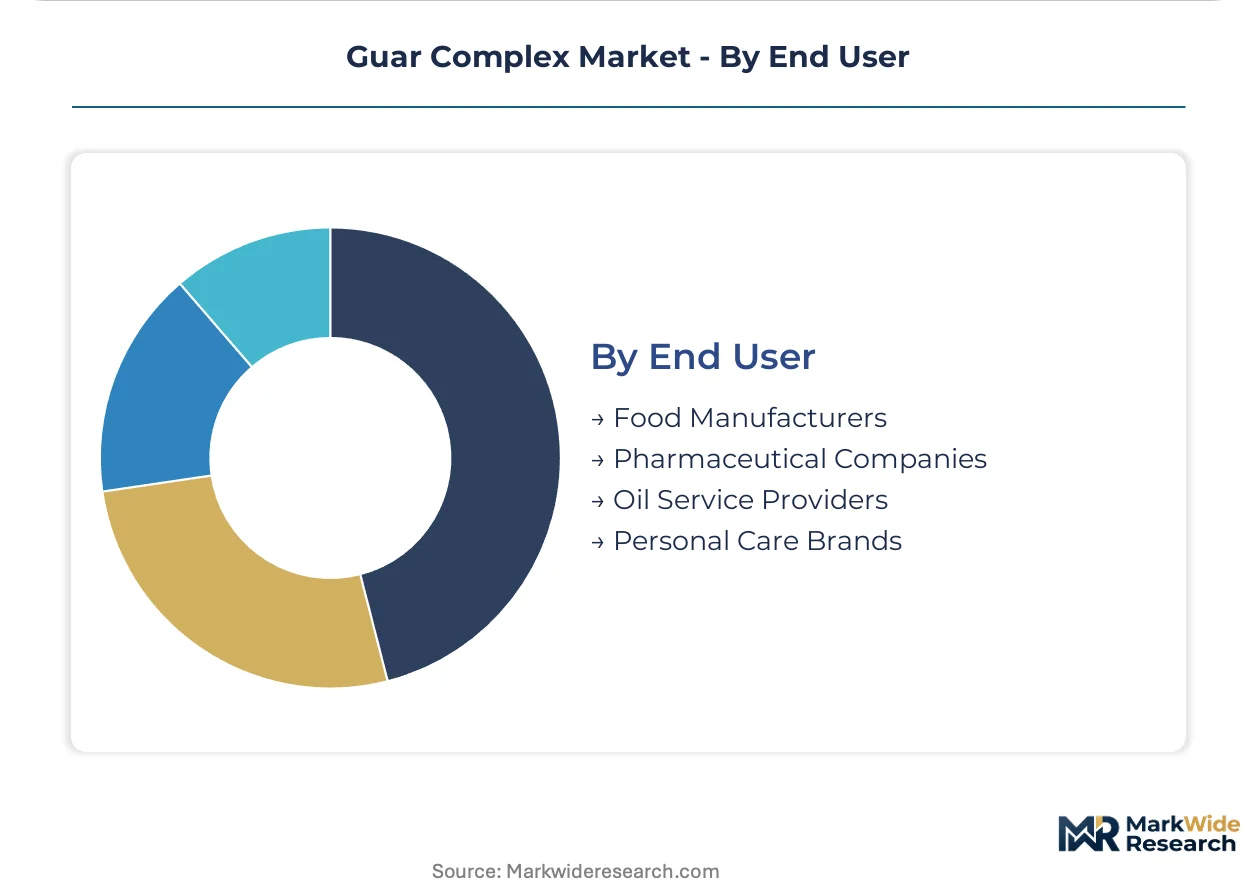
End User:
Supply concentration aligns with end-user scale, as integrated processors in Rajasthan's Jodhpur cluster serve multinational oil service companies through direct offtake agreements while dispersed trading networks supply fragmented food manufacturers.
- Oil Service Providers:Halliburton, Schlumberger, and Baker Hughes affiliates contracting directly with BIS-certified processors for modified derivative supply. Long-term agreements bypass traditional trading intermediaries and enforce traceability documentation for sustainability disclosure.
- Food Manufacturers:Dairy processors and bakery chains across India, Pakistan, and Bangladesh sourcing FSSAI-compliant grades. Price-sensitive procurement favors spot-market purchasing through Ahmedabad and Indore trading hubs.
- Pharmaceutical Companies:European and North American formulators demanding carbon footprint audits alongside traditional USP-NF purity specifications. CDSCO-registered Indian exporters face steepest certification escalation for EU Green Deal compliance.
- Personal Care Brands:Multinational cosmetics houses and regional private label producers in Southeast Asia. Cationic guar derivatives specified for conditioning performance in sulfate-free shampoo formulations.
Oil service providers concentrate premium value capture. Pharmaceutical companies impose the most stringent qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Indian processors commanding premium spreads on modified derivatives, while North American oilfield buyers absorb cost pass-throughs through long-term offtake structures. European pharmaceutical formulators face steeper compliance burdens that compress import margins. Supply chain traceability requirements now separate qualified from excluded supplier pools across all three demand centers.
United States
Permian and Bakken shale operators specify carboxymethyl and hydroxypropyl guar derivatives for thermal stability above 120°C in high-pressure fracture fluids. FDA food additive regulations govern hydrocolloid imports for dairy and meat processing applications. Houston-headquartered oilfield service companies now contract directly with Rajasthan manufacturers, bypassing traditional trading intermediaries through just-in-time logistics agreements.
India
BIS quality mandates and FSSAI dual-track certification requirements tighten product specifications across domestic and export supply chains. The PLI scheme for processed agricultural exports subsidizes derivative manufacturing capacity expansion in Rajasthan's Jodhpur and Bikaner industrial clusters. DGFT export policy directly influences international guar gum availability and pricing benchmarks through licensed shipment controls.
Germany
EMA excipient certification and REACH substance registration requirements restrict qualified supplier pools for pharmaceutical-grade gum derivatives. ECHA compliance mandates full supply chain documentation from seed sourcing through processing, excluding smaller Indian exporters. Frankfurt-area formulators now demand carbon footprint audits alongside traditional USP-NF purity specifications under EU Green Deal disclosure rules.
Saudi Arabia
Dairy and beef cattle operations across the Kingdom displace soybean meal with cost-advantaged guar meal due to favorable amino acid profiles and lower anti-nutritional factor content. SFDA feed ingredient regulations govern import quality standards for ruminant nutrition applications. Jeddah and Dammam port infrastructure handles rising volumes of Indian-origin meal shipments directed to integrated livestock operations.
Brazil
ANVISA pharmaceutical excipient regulations shape import requirements for controlled-release tablet binding applications. Personal care brands in São Paulo source cationic guar derivatives for sulfate-free shampoo conditioning performance. The country's national pharmaceutical regulator maintains strict documentation requirements that favor established Indian processors with dedicated GMP facilities over spot-market suppliers.
Guar Complex Market Competitive Landscape
Concentration sits with integrated processors controlling captive seed sourcing and enzymatic modification capability. Trading-dependent operators without R&D facilities face margin compression as oilfield buyers consolidate procurement through direct manufacturer relationships. Three archetypes define competitive positioning: Rajasthan-based integrated processors with cluster infrastructure, multinational specialty chemical houses with pharmaceutical-grade certification, and commodity traders serving fragmented food industry demand. Capacity expansion and backward integration into seed procurement represent the dominant competitive moves separating margin-stable leaders from price-takers.
Among Indian integrated processors, Hindustan Gum and Chemicals Limited, Vikas WSP Limited, and Jai Bharat Gum and Chemicals Ltd. occupy positions within the captive-sourcing archetype, representing the supply base that has captured direct offtake agreements from North American oilfield service providers. These entities exemplify the tier that has disintermediated traditional trading channels through cluster-based manufacturing infrastructure in Rajasthan's processing belt.
| Leading Market Players |
|---|
| Hindustan Gum and Chemicals Limited |
| Vikas WSP Limited |
| Ashland Global Holdings Inc. |
| Jai Bharat Gum and Chemicals Ltd. |
| Lucid Group |
| India Glycols Limited |
| Agro Gums |
| Cargill |
| Lamberti S.p.A. |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day seed-to-derivative lead times in Rajasthan's processing clusters concentrate pricing power with integrated processors commanding premium spreads on modified guar derivatives, while trading-dependent operators absorb volatility in spot-market guar meal.
Pricing Analysis
The customization-premium spread between enzymatically modified derivatives and commodity guar gum powder has widened as oilfield service providers specify carboxymethyl and hydroxypropyl grades for thermal stability above 120°C. Three-tier pricing structure across pharmaceutical-grade, oilfield-modified, and standard food-grade levels tracks certification burden and R&D intensity. Cost compression in unmodified food-grade segments is intensifying because xanthan gum substitutes erode pricing power. Food manufacturers sourcing through Ahmedabad trading hubs exhibit highest price sensitivity, while Halliburton and Schlumberger affiliates accept premium pass-throughs for qualified modified derivative supply.
Supply Chain Analysis
Inventory cycles stretching through monsoon-dependent harvest windows tether Rajasthan and Gujarat processors to erratic rainfall patterns concentrating climate risk in a narrow geographic band. The supply chain draws from guar seed cultivation, enzymatic modification inputs, and GMP-certified pharmaceutical excipient facilities. Single-source vulnerability runs through over 80% of Indian seed output concentrated in two states. Distribution runs through direct offtake agreements with North American oilfield service companies, bypassing traditional trading intermediaries, alongside spot-market channels serving fragmented Asian food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and buyer consolidation creates niche opportunities for processors capable of bridging food-grade and pharmaceutical-grade capability gaps.
For Market Incumbents: Consolidate through captive seed procurement in northwestern India and dedicated R&D investment for modified derivative production. Synthetic polymer substitution from xanthan gum threatens commoditized grades. Backward integration into Jodhpur-Bikaner cluster infrastructure separates margin-stable leaders from price-takers. For New Entrants and Emerging Players: Differentiate on carbon footprint traceability and EU Green Deal compliance documentation. The most penetrable white-space sits with pharmaceutical-grade guar derivatives for controlled-release tablet binding, where FDA drug master file requirements restrict qualified supplier pools. Target CDSCO-registered Indian exporters lacking EMA excipient certification as acquisition or partnership candidates. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because oilfield procurement disintermediation favors integrated processors with direct manufacturer relationships. Acquisition target archetype: Rajasthan-based mid-cap specialists with BIS certification and enzymatic modification capability. The signal to watch is REACH registration deadline compliance excluding smaller exporters from European pharmaceutical markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Procurement | Captive sourcing across Rajasthan cultivation belts insulates margin stability from monsoon volatility. |
| Enzymatic Modification Capacity Expansion | Carboxymethyl and hydroxypropyl derivative capability captures premium oilfield specification demand. |
| Dual-Track Certification Investment | Simultaneous FSSAI food-grade and CDSCO pharmaceutical-grade validation opens multiproduct revenue streams. |
| Long-Term Offtake Agreement Structuring | Direct contracts with Halliburton and Schlumberger affiliates disintermediate trading intermediaries. |
| Carbon Footprint Audit Implementation | EU Green Deal traceability documentation qualifies processors for European pharmaceutical formulator procurement. |
Research Methodology
A standing panel of oilfield procurement managers, Rajasthan processing plant directors, pharmaceutical formulation scientists, and FSSAI regulatory consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from DGFT export license records, BIS certification databases, ECHA REACH registration filings, and customs trade data. Bottom-up volume triangulation across seed procurement, split manufacturing, and derivative processing combined with top-down demand segmentation to produce integrated market estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, application grade, form specification, and end-user concentration. CAGRs were derived from regression-based trending of historical price-volume relationships and elasticity-adjusted demand projections. Industry-specific inputs included monsoon rainfall correlation models for seed supply estimation and oilfield drilling activity indices for derivative demand forecasting.
The analysis sits within stated boundaries; outcomes outside sustained Permian Basin drilling activity or stable Indian monsoon patterns would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and substitution elasticity parameters. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
United States Rice Market
Grains
Argentina Grains Market
Grains
Barley Market
Grains
Chickpeas Market
Grains
Quinoa Flour Market
Grains
China Rice Market
Grains
Global Oats Market
Grains
China Wheat Protein Market
Grains
Torrified Wheat Market
Grains
Asia-Pacific Rice Market
Grains
Cameroon Grains Market
Grains
GCC Basmati Rice Market
Grains
Sorghum Flour Market
Grains
Global Precooked Corn Flour Market
Grains
Dried Spent Grain Market
Grains
Whole-Wheat Flour Market