
 Gluten Feed Market | 2026-2036
Gluten Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Feed Market Intelligence
The direct sales channel to large-scale livestock and aquaculture operations is reconfiguring traditional distribution networks. Archer Daniels Midland Company leverages its extensive logistics infrastructure to support this direct-to-customer model. Cargill Incorporated competes by offering integrated supply chain solutions for animal nutrition clients. Meanwhile, Roquette Frères specializes in plant-based ingredients, differentiating its gluten feed products for premium applications.
Gluten feed is a co-product derived from the wet-milling process of grains like corn and wheat. It is characterized by its high protein and fiber content, serving as an economical source of nutrients in animal diets. Corn gluten feed, a byproduct of corn processing, dominates production volume due to the scale of the ethanol industry. Within end-user segments, its primary application remains in livestock feed for ruminants, while the higher-protein wheat gluten finds a growing niche in premium pet food formulations.
Market access is governed by feed safety regulations, with the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) setting strict limits on contaminants. In China, national GB standards dictate the quality and composition requirements for imported and domestically produced feed ingredients. Future competitive advantage will depend on demonstrating product consistency and supply chain traceability to meet evolving customer and regulatory demands.
Market Dynamics
The market's core dynamic is its dependence on the grain wet-milling sector, particularly for ethanol production. This linkage makes gluten feed supply volumes and costs intrinsically tied to energy policies and corn market fluctuations, not just animal nutrition demand.
Growth Catalysts
- Circular Economy Policies:The European Union's Green Deal promotes agricultural co-products, positioning gluten feed as a sustainable ingredient and reducing reliance on primary protein crops for animal feed formulations.
- Aquaculture Expansion:Demand from the aquaculture industry for protein-rich binders in fish feed formulations provides a significant growth vector, especially for higher-protein wheat gluten variants.
- Livestock Market Concentration:Concentrated demand from large-scale livestock operations in countries like China and the United States creates stable, high-volume offtake channels for corn gluten feed producers.
Market Restraints
- Input Price Volatility:The price of corn, the primary feedstock, is subject to significant fluctuations driven by its use in the ethanol and energy sectors, creating cost instability for gluten feed producers.
- Threat of Substitution:Gluten feed faces direct competition from other protein sources like soybean meal and dried distillers grains with solubles (DDGS), which can be substituted based on relative pricing and availability.
- Mycotoxin Contamination Risk:Strict limits on mycotoxins set by regulators like the European Food Safety Authority (EFSA) can lead to shipment rejections and increase compliance costs for exporters.
Strategic Opportunities
- Premium Pet Food Niche:The growing demand for high-protein, grain-based ingredients in premium pet food formulations presents a value-added opportunity, particularly for wheat gluten.
- Traceability Technologies:Implementing blockchain or other digital traceability systems can create a competitive advantage by verifying origin, quality, and non-GMO status for discerning customers.
- Geographic Market Development:There is an opportunity to develop markets in Southeast Asian countries where expanding livestock and aquaculture industries seek economical and reliable protein sources.
Industry Challenges
- Supply Chain Verification:Establishing and maintaining end-to-end traceability to meet customer demands for transparency and regulatory requirements like those from the FDA is a complex operational hurdle.
- Product Consistency:As a co-product, maintaining consistent protein, fiber, and nutrient levels from batch to batch requires rigorous process control and quality assurance, which can be challenging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Feed Market |
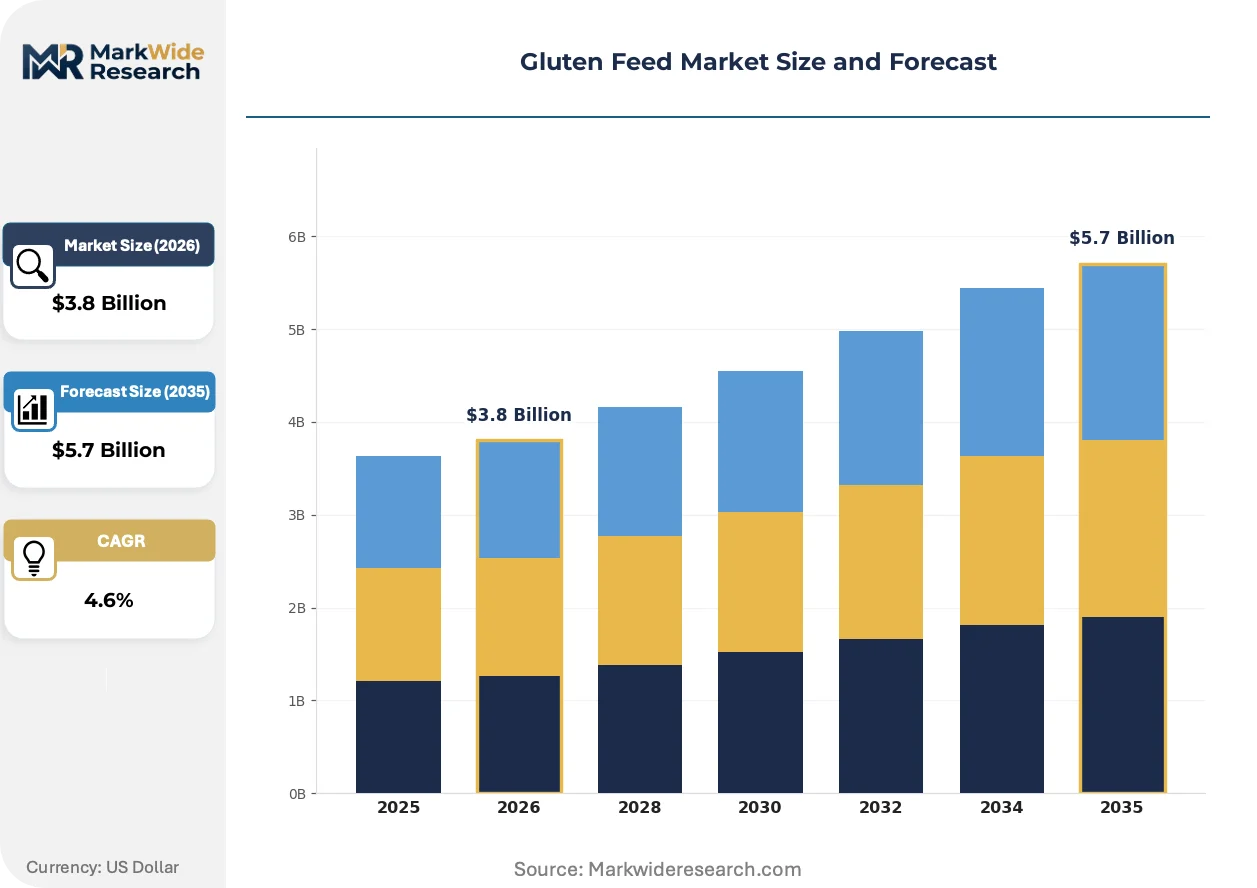
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Gluten, Corn Gluten, Barley Gluten, Rye Gluten End User: Animal Feed, Food Industry, Pet Food, Pharmaceuticals Application: Nutrition Supplement, Baking Ingredient, Protein Source, Livestock Feed Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion Incorporated, Roquette Frères, Bunge Ltd., Agrana Group, Grain Processing Corporation, Tate & Lyle Plc., Tereos Syral, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Feed Market Strategic Shifts & Innovations
A fundamental shift toward value-added differentiation is recasting the gluten feed market. Producers are moving beyond a bulk commodity mindset, leveraging processing innovations and verifiable data to meet demand for specialized, higher-margin animal nutrition ingredients.
Advanced enzymatic processing is enhancing the nutritional profile of gluten feed. Premium animal nutrition formulators in aquaculture and pet food are adopting these upgraded ingredients to improve digestibility. This technology is rendering obsolete the traditional classification of all gluten feed as a simple, low-cost bulk filler by creating distinct performance tiers.
The European Union's Green Deal, through its Farm to Fork strategy, creates a significant tailwind for agricultural co-products. This policy framework incentivizes a circular economy model within the food system, reducing waste. Consequently, European feed manufacturers are reformulating diets to include more sustainable ingredients like gluten feed, especially from local or regional sources.
Buyer behavior is evolving from simple price-based transactions to sourcing based on verified product attributes. This disrupts traditional commodity channels where opacity was common, favoring direct relationships between producers and large end-users. The shift is most apparent in European pet food and global aquaculture supply chains, where traceability is a key purchasing criterion.
Gluten Feed Market Segmentation
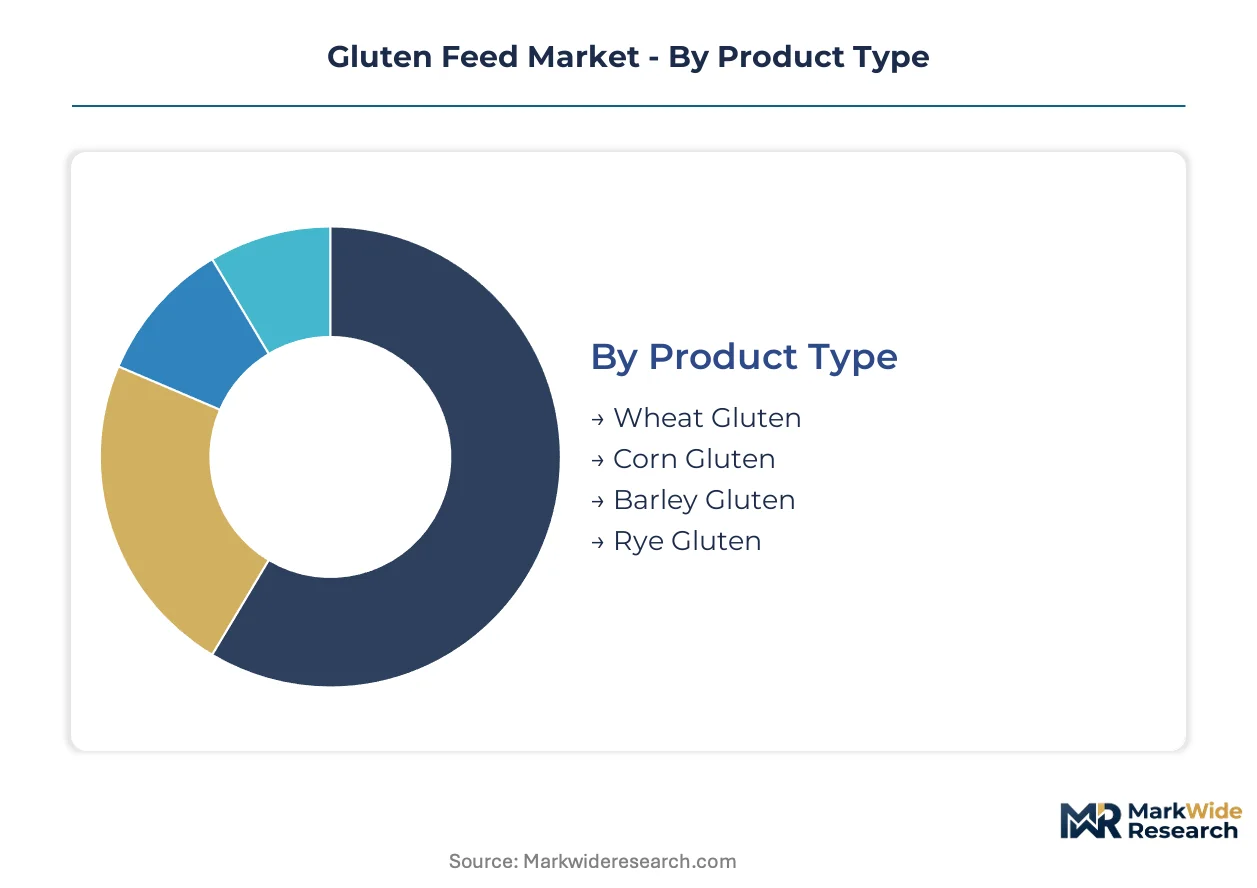
Segmentation provides a granular view of the Gluten Feed market, revealing distinct demand patterns and operational requirements across various product types, end-users, applications, and distribution channels. Understanding these segments is critical for producers to tailor product offerings, optimize supply chain strategies, and meet diverse customer needs effectively.
Product Type:
The intensity of after-sales service and technical support varies significantly across different gluten feed product types, influencing customer loyalty and repeat business.
- Wheat Gluten:This product type is characterized by its higher protein content and viscoelastic properties, making it suitable for specialized applications in premium pet food and aquaculture. Demand for wheat gluten is expanding due to its functional benefits in high-value animal nutrition formulations.
- Corn Gluten:Derived from corn wet-milling, corn gluten feed dominates production volume, primarily serving as an economical protein and fiber source in livestock feed. Its supply volumes are intrinsically linked to the scale of the ethanol industry, impacting its availability and pricing.
- Barley Gluten:A co-product of barley processing, barley gluten offers a nutritional profile suitable for certain animal feed formulations, though its market presence is smaller compared to corn and wheat variants.
- Rye Gluten:Less common than other gluten types, rye gluten finds limited applications in animal feed, often utilized in specific regional markets based on local grain availability.
Corn Gluten holds the largest share; momentum sits with Wheat Gluten.
End User:
Different end-user segments exhibit varying sensitivities to price, driving a tiered cost structure for gluten feed ingredients.
- Animal Feed:This segment represents the largest consumer of gluten feed, utilizing it as a cost-effective protein and energy source for various livestock, particularly ruminants. Regulatory bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) set strict quality and safety standards for feed ingredients.
- Pet Food:The pet food industry, especially the premium segment, increasingly demands high-protein, grain-based ingredients like wheat gluten for its nutritional and textural benefits. This segment prioritizes product consistency and verifiable origin to meet discerning consumer preferences.
- Food Industry:While less prevalent for gluten feed, some fractions of gluten, particularly wheat gluten, are used in the human food industry for their binding and textural properties in baked goods.
- Pharmaceuticals:A niche application, the pharmaceutical sector may use highly purified gluten derivatives as excipients or binders in certain formulations, requiring stringent quality control.
Animal Feed represents the largest consumption segment, with Pet Food expanding most quickly.
Application:
The volume demands for gluten feed vary considerably by application, influencing production scale and supply chain logistics.
- Livestock Feed:This application segment forms the backbone of gluten feed demand, providing essential protein and fiber for cattle, poultry, and swine diets. Large-scale livestock operations in countries like China and the United States drive consistent, high-volume procurement.
- Protein Source:Gluten feed functions as an economical protein source in various animal nutrition formulations, reducing reliance on more expensive alternatives like soybean meal. Aquaculture operations increasingly seek protein-rich binders for fish feed.
- Nutrition Supplement:Beyond bulk protein, gluten feed provides a valuable source of digestible fiber and other nutrients, complementing animal diets for improved health and performance.
- Baking Ingredient:Primarily for wheat gluten, this application leverages its viscoelastic properties to enhance dough strength and structure in commercial baking processes.
Livestock Feed applications account for the bulk of gluten feed consumption.
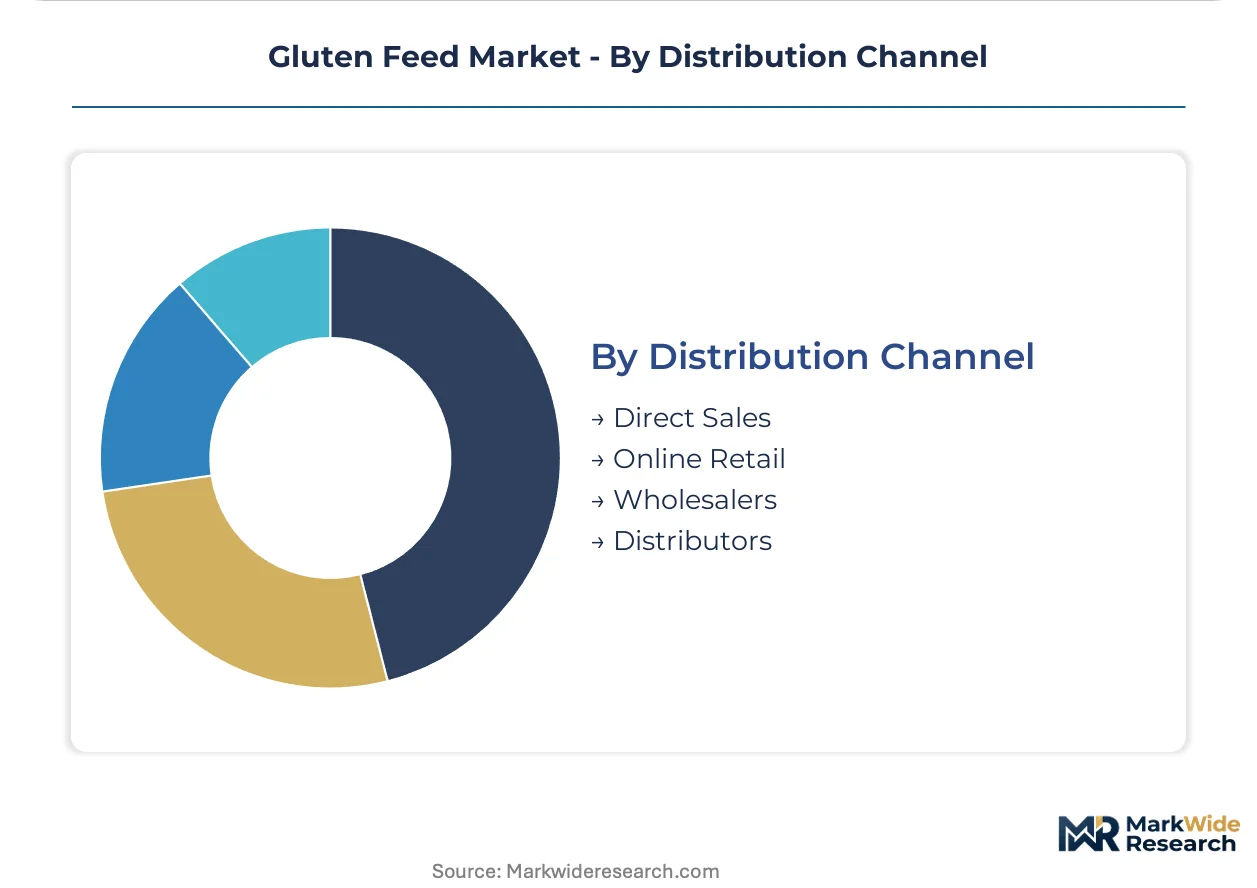
Distribution Channel:
Customer type dictates the preferred distribution channel, with large-scale operations favoring direct engagement and smaller buyers utilizing intermediaries.
- Direct Sales:Large-scale livestock and aquaculture operations increasingly procure gluten feed directly from producers like Archer Daniels Midland Company, streamlining supply chains and ensuring product traceability. This channel allows for customized contracts and technical support.
- Wholesalers:Traditional wholesalers play a vital role in aggregating supply from various producers and distributing gluten feed to a fragmented base of smaller feed mills and farms. They manage logistics and inventory for diverse customer needs.
- Online Retail:Emerging as a channel for smaller volume purchases or specialized ingredients, online platforms offer convenience and broader access for niche applications, though bulk commodities are less common here.
- Distributors:Regional distributors provide localized sales, marketing, and logistics services, bridging the gap between large producers and a dispersed customer base in specific geographic markets.
Direct Sales channels are gaining prominence due to evolving buyer behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Food and Drug Administration (FDA) sets safety standards for feed ingredients, anchoring demand patterns across the global gluten feed market. This regulatory environment influences production quality and trade flows, particularly for large-scale agricultural economies. Regional dynamics reflect varied livestock populations, aquaculture expansion, and local grain processing capacities.
United States
Demand for corn gluten feed in the United States stems from its extensive livestock industry, especially for ruminant diets. The U.S. Department of Agriculture (USDA) promotes sustainable feed ingredients, aligning with gluten feed's co-product status. Major corn-producing states like Iowa and Illinois host significant ethanol production facilities, generating substantial gluten feed volumes.
China
China's gluten feed consumption is driven by its vast and expanding aquaculture and swine sectors, seeking economical protein sources. National GB standards dictate stringent quality and composition requirements for imported and domestic feed ingredients. Large-scale animal husbandry operations in provinces like Shandong and Henan represent concentrated demand centers.
Germany
Germany's market for gluten feed benefits from the European Union's Green Deal, which incentivizes agricultural co-products in animal feed. The European Food Safety Authority (EFSA) ensures strict limits on contaminants, influencing import and production practices. Bavaria and North Rhine-Westphalia, with their strong agricultural and feed manufacturing bases, are key consumption regions.
Brazil
Brazil's growing poultry and beef industries create a robust demand for protein-rich feed ingredients like gluten feed. The country's Ministry of Agriculture, Livestock and Food Supply (MAPA) regulates feed safety and quality. Mato Grosso and Paraná, as major agricultural hubs, support both grain processing and large-scale animal production.
India
India's gluten feed market is expanding due to its increasing dairy and poultry production, driving the need for cost-effective animal nutrition. The Food Safety and Standards Authority of India (FSSAI) oversees feed ingredient quality and safety. States like Uttar Pradesh and Punjab, with significant livestock populations, are important consumption areas for feed formulators.
Gluten Feed Market Key Industry Players
Integrated agricultural conglomerates and specialized plant-based ingredient providers split the market for gluten feed. The competitive landscape is characterized by a mix of large-scale commodity producers and niche players focused on value-added applications. Dominant competitive moves include supply chain optimization and product differentiation through processing innovations.
Within the integrated supply chain providers, Archer Daniels Midland Company and Cargill Incorporated leverage extensive logistics and global sourcing networks. Roquette Frères occupies a position among specialized ingredient suppliers, focusing on plant-based solutions for premium applications. These companies exemplify the strategic diversity in meeting varied customer requirements across the gluten feed value chain.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Incorporated |
| Roquette Frères |
| Bunge Ltd. |
| Agrana Group |
| Grain Processing Corporation |
| Tate & Lyle Plc. |
| Tereos Syral |
| Others |
Cost & Logistics Intelligence
Under-capacity in specialized wheat gluten processing facilities drives both premium pricing for high-protein variants and strategic investments by producers. This utilization dynamic influences both supplier behavior and the pricing posture across the gluten feed market.
Pricing Analysis
Geographic price spreads reflect regional supply-demand imbalances and varying logistics costs for gluten feed. The dominant pricing model for corn gluten feed often operates on a commodity spot basis, while specialized wheat gluten frequently involves contract-based long-term offtake agreements. Price differentiation stems from protein content and quality grade, particularly for premium pet food and aquaculture applications, alongside geographic delivery costs. Pricing softness reflects input price volatility for corn, driven by its use in the ethanol sector, and competition from alternative protein sources. Livestock feed for ruminants represents the most price-sensitive segment, contrasted with the less sensitive premium pet food sector.
Supply Chain Analysis
Extended payment terms are increasingly common for large-volume buyers in the gluten feed market, influencing supplier-financing dynamics. Supply concentration for corn gluten feed centers on major grain-producing regions in the United States and Brazil, while China and Germany represent significant consumption hubs. Raw material dependencies primarily involve corn and wheat, co-products of their respective wet-milling processes. Mycotoxin contamination risk presents a structural supply chain risk, imposing stringent regulatory restrictions from bodies like the European Food Safety Authority. Distribution runs through direct sales channels to large-scale livestock and aquaculture operations, complemented by wholesalers serving smaller feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gluten Feed market faces high-growth disruption, driven by the European Union's Green Deal promoting sustainable agricultural co-products. This regulatory inflection creates new opportunities for value-added differentiation.
For Market Incumbents: Build intellectual property moats around advanced processing technologies to differentiate gluten feed products. Invest in advanced enzymatic processing to enhance nutritional profiles for premium applications, addressing the threat of substitution from alternative protein sources. Secure long-term supply agreements with ethanol producers to stabilize raw material input and mitigate price volatility. Focus on certification investment for verifiable product attributes, such as non-GMO status, to meet discerning customer demands.
For New Entrants and Emerging Players: Niche applications in premium pet food formulations in Europe represent the most penetrable entry point for new gluten feed market players. Target high-protein wheat gluten for aquaculture in Southeast Asia, where expanding industries seek economical protein sources. Pursue specialized blends for organic livestock feed, leveraging verifiable product attributes and supply chain traceability as a key go-to-market angle. Focus on regional market development where local grain availability supports production.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialized gluten feed processing, driven by technology adoption and quality control requirements. Long-term viability rests on sustainable sourcing and value-added product development over the next decade. Acquisition targets should include vertically integrated plant-based ingredient specialists with strong R&D capabilities in feed nutrition. Adoption rates of advanced enzymatic processing technologies serve as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Enzymatic Processing Investment | Enhances nutritional profiles for premium aquaculture applications. |
| Supply Chain Traceability System Deployment | Meets evolving customer demands for verified origin and quality. |
| Geographic Market Expansion in Southeast Asia | Captures growing demand from expanding livestock and aquaculture industries. |
| Long-term Offtake Agreements with Ethanol Producers | Stabilizes raw material supply and mitigates input price volatility. |
| Product Line Diversification for Premium Pet Food | Addresses the expanding market for high-protein, grain-based pet food ingredients. |
Research Approach
Desk research of academic journals, industry reports, company financial filings, and government publications preceded structured interviews with feed formulators, grain processors, animal nutritionists, and regulatory compliance officers. This approach combined primary insights from industry stakeholders with secondary validation from diverse public and proprietary data sources. Bottom-up data aggregation and top-down market sizing provided comprehensive triangulation.
Assumptions regarding a stable regulatory environment and consistent grain harvest yields were held fixed across the analysis window. The forecast framework modeled market dynamics across product type, end-user, application, distribution channel, and key regional markets like the USA, China, Germany, Brazil, and India. Compound annual growth rates were derived from historical trends and projected future demand, with global grain production volumes and livestock population growth rates serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global economic growth, energy prices, or agricultural commodity prices would shift the trajectory. Forecasts reflect these assumptions, acknowledging that unforeseen trade barriers or new feed ingredient regulations could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Rolled Oats Market
Grains
Ghana Grain Market
Grains
IQF Rice Market
Grains
Wheat Fiber Market
Grains
Sorghum Flour Market
Grains
00 Flour Market
Grains
Africa Maize Market
Grains
White Beans Market
Grains
Europe Maize Market
Grains
Organic Rice Flour Market
Grains
Grain Augers Market
Grains
Brown Rice Market
Grains
North America Rice Market
Grains
Organic Rice Market
Grains
Pea Grits Market
Grains
Millet Flour Market