
 Dried Spent Grain Market | 2026-2036
Dried Spent Grain Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Spent Grain Market Foresight
A capital-intensity divergence between integrated brewers and independent processors is unwinding competitive stability in the dried spent grain landscape. AB InBev leverages captive brewery networks to secure upstream feedstock volumes at negligible marginal cost. ReGrained differentiates through proprietary dehydration technology that extends shelf life for food-grade applications. Cargill, Incorporated anchors downstream distribution through existing animal nutrition channels spanning multiple continents.
Dried spent grain comprises the residual solid fraction remaining after mashing and lautering in beer production, typically containing 20-30% protein and 10-15% fiber on a dry basis, with moisture reduction to below 12% enabling stable storage and transport. The animal feed segment dominates value capture due to established inclusion protocols in dairy and beef rations, while the food ingredient category registers the fastest trajectory as clean-label brands seek upcycled grain fractions for bakery and snack applications. Biofuel applications occupy a narrower margin pool constrained by energy density competition with purpose-grown feedstocks.
The EPA's Renewable Fuel Standard and the EU Green Deal's circular economy action plan jointly shape waste-to-value compliance pathways for brewery operators across North America and Europe. FDA feed safety regulations and the EU's Feed Hygiene Regulation establish microbiological thresholds that determine which drying and handling investments qualify producers for commercial distribution. Stakeholders must monitor evolving sustainability certification schemes that increasingly govern procurement decisions by multinational food and feed buyers.
Market Dynamics
Brewery consolidation is compressing feedstock access for independent processors while integrated operators capture circular economy premiums through captive dehydration infrastructure.
Growth Catalysts
- EU Green Deal circular economy mandates:Bavarian brewing clusters must valorize waste streams under binding reduction targets, creating guaranteed offtake volumes for dried spent grain processors.
- Dairy farm cost optimization:Midwest United States cattle operations are substituting soybean meal with dried spent grain protein fractions to reduce feed expenditure amid volatile commodity markets.
- Low-temperature vacuum drying:This dehydration method preserves heat-labile nutrients for food-grade applications, opening bakery and snack ingredient channels previously closed to conventional kiln-dried product.
Market Restraints
- Natural gas price volatility:Thermal drying consumes substantial energy input, exposing margin structures to European and North American utility market fluctuations.
- Feedstock concentration risk:Bavaria and Milwaukee metropolitan brewing corridors control disproportionate raw material volumes, creating geographic supply bottlenecks.
- Protein digestibility limitations:Ruminant nutrition science establishes inclusion rate ceilings that constrain volume absorption in dairy and beef segments.
Strategic Opportunities
- India emerging market penetration:FSSAI feed safety harmonization with CODEX standards would unlock brewery waste valorization in rapidly expanding dairy states.
- Bioplastics feedstock pivot:Polyhydroxyalkanoate fermentation from lignin-rich grain fractions converges with packaging sector decarbonization requirements.
- Direct-to-bakery channel development:Clean-label brands in Germany and the Netherlands are establishing procurement relationships that bypass traditional ingredient distributors.
Industry Challenges
- Food-grade certification timelines:BRC and IFS accreditation processes extend 12-18 months, delaying revenue recognition for dehydration facility upgrades.
- Moisture uniformity control:Batch-to-batch variability in initial grain moisture complicates automated drying curve optimization and finished product specification compliance.
- Supply chain reconfiguration friction:Brewery waste logistics networks require refrigerated collection coordination that conflicts with existing ambient-temperature feed distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Spent Grain Market |
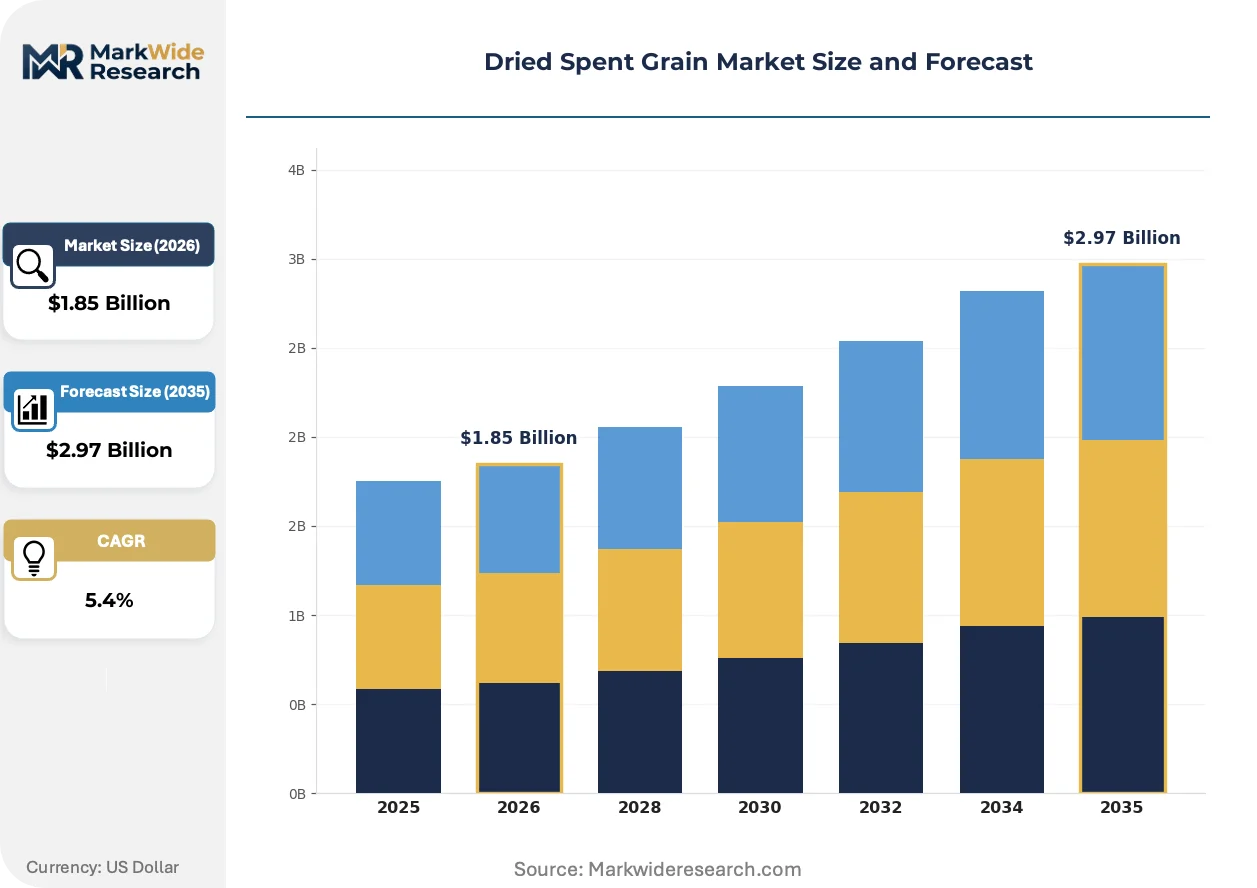
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Feed, Biofuel, Fertilizer, Food Ingredient End User: Dairy Farms, Livestock Producers, Breweries, Bioenergy Facilities Packaging Type: Bags, Bulk, Pallets, Containers Distribution Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Grain Processing Corporation, AB InBev, Malteurop Group, Brewers Grain Ltd., EverGrain Ingredients, Molson Coors Beverage Company, Cargill, Incorporated, ReGrained, Leiber GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Spent Grain Market Shifts & Advancements
Mechanical and thermal process intensification is redefining product quality tiers while regulatory compliance frameworks harden entry barriers for new dehydration capacity.
Enzymatic pre-treatment is decomposing lignocellulosic matrices in spent grain prior to dehydration, improving protein accessibility for monogastric feed formulations. Poultry integrators in the Netherlands are piloting this approach at commercial scale. The technology is decomposing traditional ruminant-feed-only market boundaries by enabling swine and poultry inclusion protocols.
REACH authorization requirements for chemical processing aids are tightening residual solvent thresholds in food-grade grain fractionation. This industrial consequence accelerates aqueous extraction method adoption. German ingredient manufacturers are most affected, responding with closed-loop water recovery system investments.
Clean-label procurement committees at multinational bakery brands now mandate upcycled ingredient certification with third-party chain-of-custody documentation. Traditional commodity grain suppliers face displacement by verified circular economy providers. This behavioral shift is most visible in Scandinavian retail channels where consumer willingness-to-pay premiums for sustainability claims exceeds continental European benchmarks.
Dried Spent Grain Market Segmentation
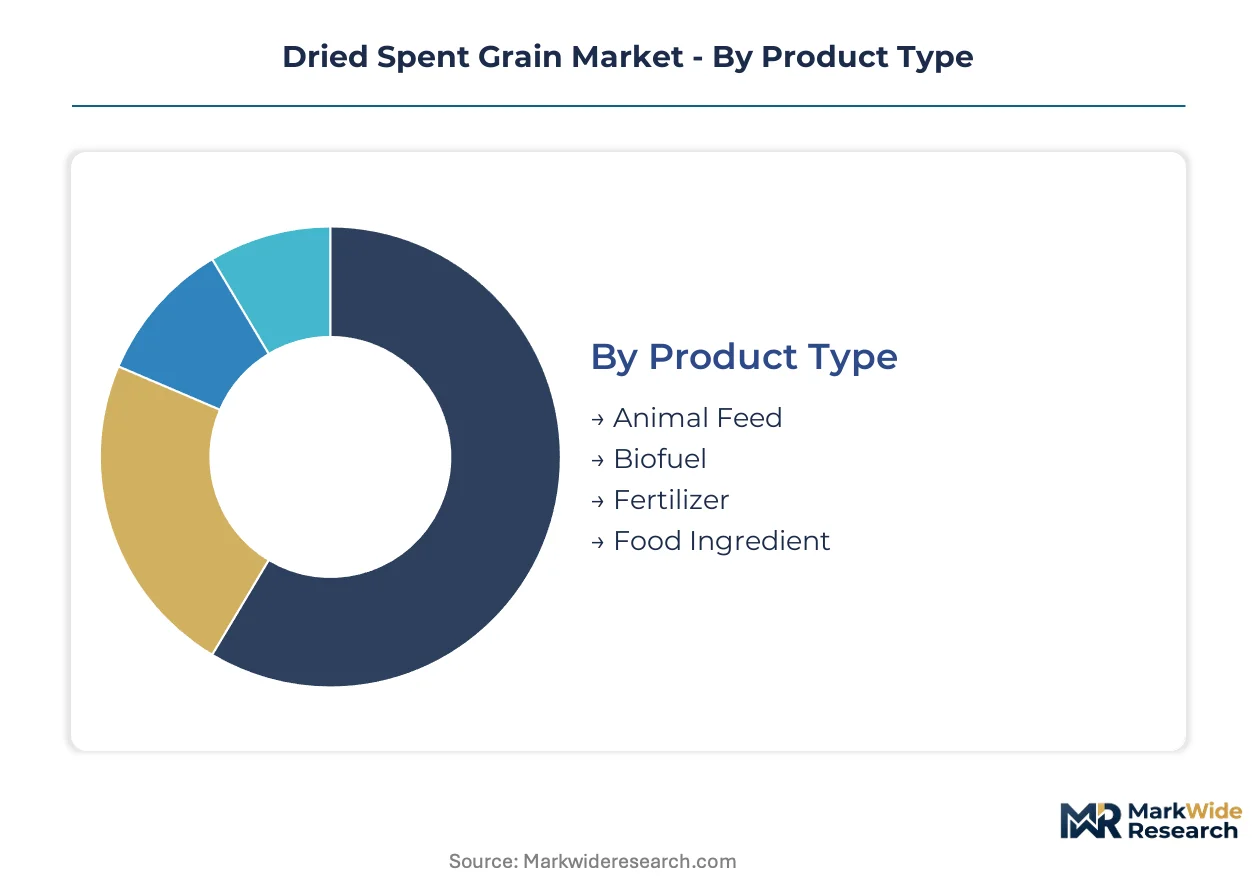
Segmentation in dried spent grain markets reveals how dehydration specifications, certification tiers, and logistics infrastructure fragment value capture across distinct buyer workflows. Channel alignment determines which product forms command premium positioning versus commodity throughput.
Product Type:
Animal feed fractions flow through established agricultural distributors with bulk handling infrastructure, while food-grade and biofuel channels require discrete certification pathways and specialized offtake contracts.
- Animal Feed:Comprises protein-rich fractions with 20-30% crude protein and 10-15% fiber content, kiln-dried to below 12% moisture for stable storage. Dairy farms across Wisconsin and Bavaria concentrate procurement here, constrained by ruminant nutrition science that caps inclusion rates in total mixed rations.
- Food Ingredient:Demands low-temperature vacuum drying to preserve heat-labile nutrients and achieve food-grade microbiological thresholds. Clean-label bakery brands in Germany and the Netherlands source directly, bypassing traditional ingredient distributors to secure upcycled grain fractions with third-party chain-of-custody documentation.
- Biofuel:Lignin-rich fractions diverted toward anaerobic digestion or combustion applications under EPA Renewable Fuel Standard compliance pathways.
- Fertilizer:Composted or pelletized organic matter distributed through agricultural cooperatives for soil amendment programs.
By volume, Animal Feed leads. By growth pace, Food Ingredient is climbing the fastest.
End User:
Cost tier stratification separates large-scale integrated operations with captive dehydration infrastructure from independent processors purchasing third-party dried grain.
- Dairy Farms:Midwest United States operations substitute soybean meal with dried spent grain protein to reduce feed expenditure amid volatile commodity markets, establishing inclusion protocols through nutritionist-formulated total mixed rations.
- Livestock Producers:Beef cattle feedlots and poultry integrators in the Netherlands pilot enzymatic pre-treatment to improve protein accessibility for monogastric species, decomposing traditional ruminant-only market boundaries.
- Breweries:Integrated operators like AB InBev deploy captive dehydration infrastructure to capture circular economy premiums and secure upstream feedstock at negligible marginal cost.
- Bioenergy Facilities:Anaerobic digestion and biomass combustion operators procuring under EPA Renewable Fuel Standard and EU Green Deal waste-to-value mandates.
Procurement scale favors Dairy Farms. Margin capture concentrates with integrated Breweries.
Packaging Type:
Volume throughput and handling automation requirements dictate packaging selection, with bulk formats dominating commodity flows and unitized packaging serving food-grade channels.
- Bulk:Unpackaged dried grain delivered via pneumatic or auger systems to large dairy operations and feed mills with dedicated receiving infrastructure.
- Bags:Multi-wall paper or woven polypropylene sacks for mid-scale livestock producers lacking bulk handling equipment.
- Pallets:Unitized loads for food-grade ingredient distribution to bakery manufacturing facilities with forklift access and batch-scale receiving.
- Containers:Intermodal shipping containers for export flows from Bavarian brewing clusters to international animal nutrition markets.
By tonnage moved, Bulk dominates. By value per kilogram, Pallets command premium positioning.
Distribution Channel:
Customer type and order scale determine channel selection, with direct relationships anchoring large-volume flows and intermediaries serving fragmented buyer bases.
- Direct Sales:Long-term supply agreements between integrated brewers and large dairy cooperatives, or between specialized processors and multinational food manufacturers, eliminating intermediary margins.
- Distributors:Agricultural supply cooperatives and ingredient distributors managing inventory, credit terms, and last-mile logistics for dispersed livestock producers and regional bakeries.
- Online Sales:Emerging platform-based procurement for specialty food-grade fractions, enabling small-scale clean-label brands to access verified upcycled ingredients with documentation.
- Retailers:Garden centers and farm supply stores moving bagged fertilizer and hobby-scale animal feed products to consumer and smallholder segments.
Direct Sales anchors volume throughput. Online Sales is gaining share fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German processors commanding premium tiers for food-grade fractions, while Midwest United States operators compete on volume throughput for dairy feed contracts.
Germany
Bavarian brewing clusters generate concentrated byproduct volumes for circular economy valorization, with dairy farms and clean-label bakeries competing for limited food-grade output. The EU Green Deal's circular economy action plan mandates binding waste reduction targets that guarantee offtake volumes for dehydration facilities. Munich and Nuremberg metropolitan corridors anchor production gravity, where integrated brewers deploy captive infrastructure to capture sustainability premiums.
United States
Midwest dairy operations across Wisconsin and Illinois substitute soybean meal with dried spent grain protein to reduce feed expenditure amid volatile commodity markets. The EPA's Renewable Fuel Standard redirects brewery waste streams toward bioenergy applications, creating compliance-driven demand bifurcation. Milwaukee's metropolitan brewing corridor controls disproportionate raw material volumes, forcing independent processors into long-haul logistics arrangements.
Netherlands
Poultry integrators pilot enzymatic pre-treatment to improve protein accessibility for monogastric species, decomposing traditional ruminant-feed-only market boundaries. ECHA's REACH authorization requirements for chemical processing aids accelerate aqueous extraction method adoption among ingredient manufacturers. Rotterdam and Amsterdam logistics hubs facilitate export flows to Scandinavian retail channels where consumer willingness-to-pay premiums for sustainability claims exceeds continental benchmarks.
India
Rapidly expanding dairy states in Maharashtra and Gujarat present untapped brewery waste valorization potential contingent upon regulatory harmonization. FSSAI feed safety alignment with CODEX standards would unlock commercial-scale procurement by organized dairy cooperatives. Bangalore and Pune brewing clusters generate concentrated byproduct volumes currently diverted to informal feed channels lacking dehydration infrastructure.
Canada
Health Canada and PMRA feed safety regulations establish microbiological thresholds that determine qualification for commercial distribution across provincial dairy networks. Ontario and Quebec brewing corridors face refrigerated collection coordination challenges that conflict with existing ambient-temperature feed distribution infrastructure. Toronto metropolitan processors invest in closed-loop water recovery systems to meet emerging sustainability certification requirements from multinational buyers.
Dried Spent Grain Market Competitive Landscape
Concentration sits with integrated beverage conglomerates leveraging captive brewery networks to secure upstream feedstock at negligible marginal cost. The vendor base stratifies across three tiers: multinational agribusinesses with existing animal nutrition channels, specialized upcycling technology firms, and regional dehydration operators serving fragmented livestock producer bases. Dominant competitive moves include backward integration into brewery waste sourcing and proprietary dehydration technology licensing for shelf-life extension.
Among integrated beverage operators, AB InBev and Molson Coors Beverage Company exemplify the captive infrastructure archetype, converting proprietary waste streams into circular economy revenue. Cargill, Incorporated anchors the agribusiness tier through continent-spanning distribution networks. ReGrained occupies a specialist position representing technology-differentiated upcycling, while Leiber GmbH exemplifies European regional concentration in feed-grade processing.
| Leading Market Players |
|---|
| Grain Processing Corporation |
| AB InBev |
| Malteurop Group |
| Brewers Grain Ltd. |
| EverGrain Ingredients |
| Molson Coors Beverage Company |
| Cargill, Incorporated |
| ReGrained |
| Leiber GmbH |
| Others |
Supply & Pricing Matrix
Forty-five to sixty days of finished goods inventory separates food-grade processors from commodity feed operators, with this working capital intensity amplifying pricing power for BRC-certified facilities while compressing margins at kiln-dried bulk suppliers serving Midwest dairy cooperatives.
Pricing Analysis
The configured-to-order premium for low-temperature vacuum-dried fractions runs 40-60% above standard kiln-dried bulk pricing. Contract-based long-term offtake agreements dominate volume flows, with price differentiation hinging on certification grade and geographic delivery cost. Cost compression in commodity feed tiers is intensifying because natural gas price volatility exposes thermal drying operations to margin erosion. Dairy cooperatives exhibit highest price sensitivity, while clean-label bakery brands demonstrate lowest sensitivity due to sustainability procurement mandates.
Supply Chain Analysis
Germany and the United States anchor dehydration capacity, with Bavarian brewing clusters and Milwaukee metropolitan corridors controlling disproportionate raw material volumes. Feedstock logistics draw from refrigerated collection networks for wet spent grain, while finished distribution feeds from pneumatic bulk systems and unitized pallet loads. Single-source vulnerability concentrates in natural gas supply for thermal drying operations. Distribution runs through agricultural cooperatives for animal feed and direct sales channels for food-grade fractions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature vacuum drying technology is disrupting traditional kiln-dried commodity economics, with EU Green Deal circular economy mandates accelerating capital redeployment toward food-grade certification infrastructure.
For Market Incumbents: Compound captive brewery network advantages through backward integration into refrigerated collection infrastructure, defending against independent processors seeking long-haul feedstock arbitrage. Prioritize BRC accreditation investment to capture clean-label bakery procurement committees displacing commodity suppliers. For New Entrants and Emerging Players: FSSAI-CODEX harmonization fast-tracks entry into Maharashtra and Gujarat dairy states, where organized cooperatives currently lack dehydration infrastructure. Target India as the most penetrable geography, leveraging aqueous extraction technology to bypass REACH-constrained European competitors. For Investors and Strategic Acquirers: Long-term, this sits as a circular economy infrastructure play because sustainability certification requirements harden entry barriers while concentrating procurement relationships with multinational food manufacturers. Monitor enzymatic pre-treatment pilot scale-up at Netherlands poultry integrators as the signal indicating monogastric feed market expansion beyond traditional ruminant boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Food-Grade Certification Investment | BRC and IFS accreditation unlocks clean-label bakery procurement channels in Germany and the Netherlands. |
| Backward Integration into Collection | Refrigerated logistics networks secure upstream feedstock volumes at negligible marginal cost for integrated brewers. |
| Enzymatic Pre-Treatment Scale-Up | Protein accessibility improvements enable swine and poultry inclusion protocols beyond traditional ruminant applications. |
| Aqueous Extraction Method Adoption | Closed-loop water recovery systems satisfy ECHA REACH authorization requirements for chemical processing aid reduction. |
| Direct-to-Bakery Channel Development | Bypassing traditional ingredient distributors captures sustainability premiums from clean-label brands seeking chain-of-custody documentation. |
Research Methodology
The analysis maps animal feed, food ingredient, biofuel, and fertilizer sub-sectors, each validated through dehydration facility operators, dairy cooperative procurement managers, clean-label bakery brand sourcing directors, and brewery sustainability officers. Primary interview insights triangulate against secondary sources including EPA Renewable Fuel Standard compliance filings, EU Green Deal circular economy action plan documentation, FDA feed safety guidance, and FSSAI regulatory harmonization notices. Bottom-up capacity installation tracking and top-down demand modeling from dairy ration formulation data converge to establish volume estimates.
Consistency checks against external benchmarks validate output ranges across the projection horizon. The analytical framework segments by product type, end user, packaging format, and distribution channel, with additional dimensioning by certification tier and dehydration technology. CAGRs derive from installed capacity expansion schedules and inclusion rate evolution in ruminant nutrition science. Forecast inputs incorporate natural gas price trajectory assumptions and sustainability certification adoption curves.
Underlying assumptions cover regulatory harmonization timelines and feedstock availability from brewery production volumes, with deviation risk concentrated in FSSAI-CODEX alignment delays and enzymatic pre-treatment commercialization pace. Recalibration cycles align with material shifts in EU Green Deal enforcement stringency and Midwest dairy farm cost optimization behavior.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Brown Rice Market
Grains
Organic Cereals Market
Grains
Paraguay Grains Market
Grains
Grain Roller Market
Grains
Cornmeal Market
Grains
South American Maize Market
Grains
Africa Wheat Protein Market
Grains
Green Pea Grits Market
Grains
Gluten Free Ancient Grain Market
Grains
Spain Rice Market
Grains
Asia-Pacific Wheat Market
Grains
Grain-Based Flours Market
Grains
North America Oats Market
Grains
Barley Market
Grains
Asia-Pacific Guar Market
Grains
Green Banana Flour Market