
 Asia-Pacific Guar Market | 2026-2036
Asia-Pacific Guar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Guar Market Outlook
Commodity broker networks connecting Rajasthan processors to Southeast Asian food manufacturers is rewriting procurement geography across the Asia-Pacific Guar Market. India Glycols leverages backward integration into seed crushing to control raw material costs. Altrafine Gums anchors premium pharmaceutical-grade output through dedicated refining lines. Lucas Meyer Cosmetics Asia Pacific specializes in hydrolyzed guar derivatives for hair-care formulations.
Guar comprises a galactomannan polysaccharide derived from Cyamopsis tetragonoloba seeds, with mannose-to-galactose ratios near 2:1 determining viscosity performance in industrial applications. The gum functions primarily as a hydratable thickener in hydraulic fracturing fluids and as a stabilizer in processed foods. Guar Gum occupies the dominant value share due to its irreplaceable role in oilfield chemistry, while Guar Powder segments command premium pricing in pharmaceutical binders. Food Industry end-use applications exhibit the fastest volume expansion as clean-label demand spreads through Southeast Asian retail channels.
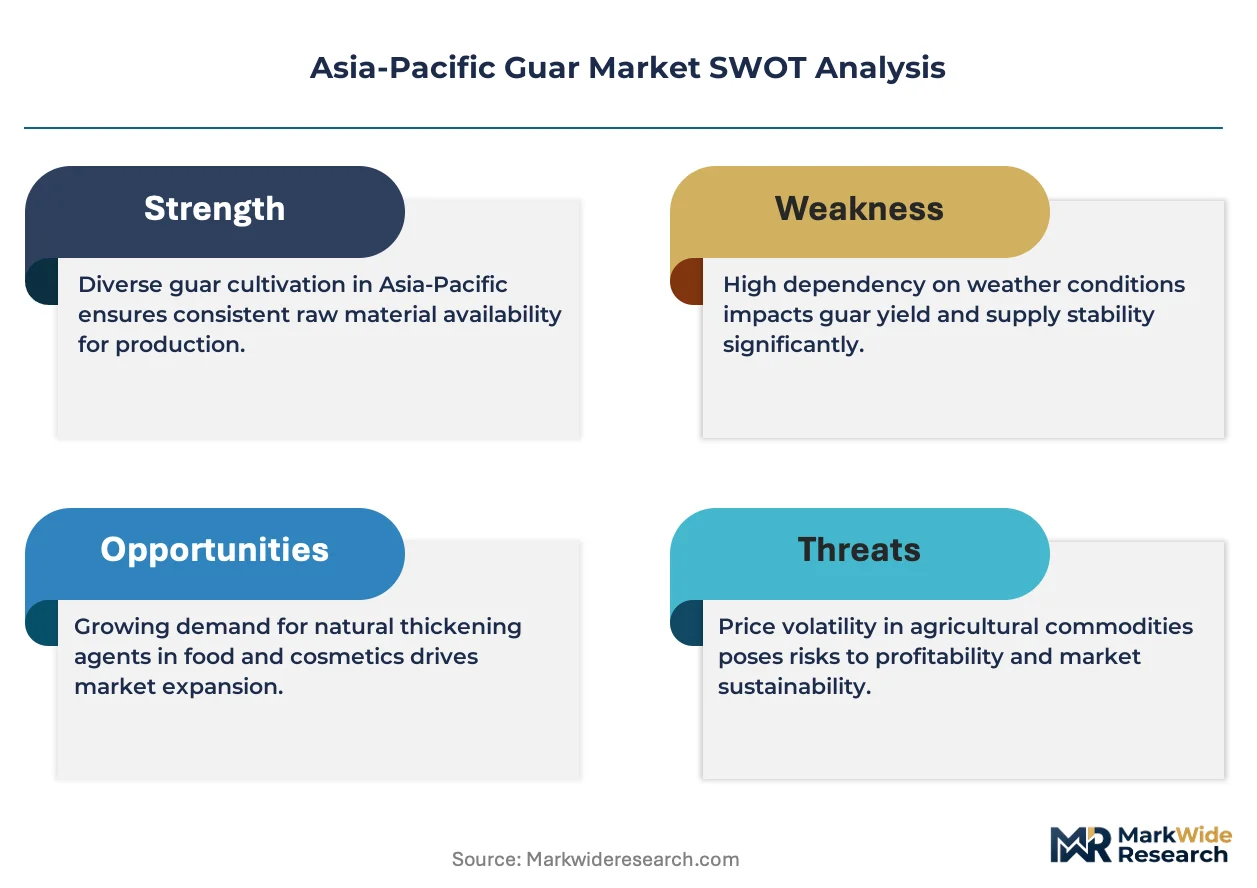
India's BIS and FSSAI frameworks enforce pesticide residue limits and microbial specifications on food-grade exports, while Australia's TGA regulates pharmaceutical-grade imports through therapeutic goods standards. These multi-layered compliance requirements shape formulation choices and testing expenditures for processors serving cross-border buyers. Stakeholders must monitor evolving biofuel substitution threats to oilfield guar demand alongside seed supply volatility from monsoon-dependent Indian agriculture.
Market Dynamics
Shale exploration intensity across Australia and Papua New Guinea is redirecting guar procurement flows, as oilfield operators bypass traditional Middle East supply chains in favor of Rajasthan processing clusters with dedicated fracturing-grade output lines.
Growth Catalysts
- Fracturing fluid specification tightening:Australian oilfield service providers now mandate higher viscosity retention under downhole temperature stress, favoring guar derivatives over synthetic polymer alternatives in high-pressure shale zones.
- BIS purity mandates:India's Bureau of Indian Standards 2024 revisions on pesticide residue limits and microbial specifications for food-grade exports are forcing processor consolidation, eliminating sub-scale competitors and concentrating certified supply.
- Hydrolyzed derivative demand:Personal care formulators in Thailand and Indonesia are specifying cationic guar hydroxypropyltrimonium chloride for sulfate-free shampoo systems, pulling premium-grade output away from commodity food applications.
Market Restraints
- Monsoon-dependent seed supply:Rajasthan and Gujarat guar seed production remains hostage to Indian monsoon variability, with three consecutive deficient rainfall years since 2022 compressing crushing margins and triggering raw material rationing.
- Xanthan gum substitution:Oilfield operators in Australia's Cooper Basin are piloting fermentation-derived xanthan systems for low-temperature wells, threatening guar's viscosity-performance monopoly in marginal drilling economics.
- Refining capacity concentration:Over 70 percent of Asia-Pacific pharmaceutical-grade refining capacity sits within 200 kilometers of Jodhpur, creating single-point vulnerability to Rajasthan logistics disruptions or state-level regulatory intervention.
Strategic Opportunities
- Vietnam food processing penetration:Ho Chi Minh City-based sauce and convenience food manufacturers remain under-supplied with certified halal-grade guar, presenting first-mover positioning for BIS-compliant Indian exporters.
- Cellulosic ethanol adjacency:Guar gum's seed hull fraction is attracting interest from Indian biofuel pilot projects under the national ethanol blending mandate, creating alternative revenue streams for integrated crushers.
- E-commerce ingredient channels:Direct-to-manufacturer platforms are collapsing traditional broker layers between Rajasthan processors and Southeast Asian small-batch food producers, compressing procurement cycles from 45 days to under 10 days.
Industry Challenges
- Pharmaceutical-grade certification timelines:CDSCO and TGA dual-registration requirements for excipient-grade exports extend approval cycles to 18-24 months, freezing working capital and favoring incumbent registrants with established dossiers.
- Seed quality heterogeneity:Gujarat's unorganized farmgate procurement lacks standardized moisture and foreign-matter testing, forcing processors to absorb yield variability through blending losses and reprocessing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Guar Market |
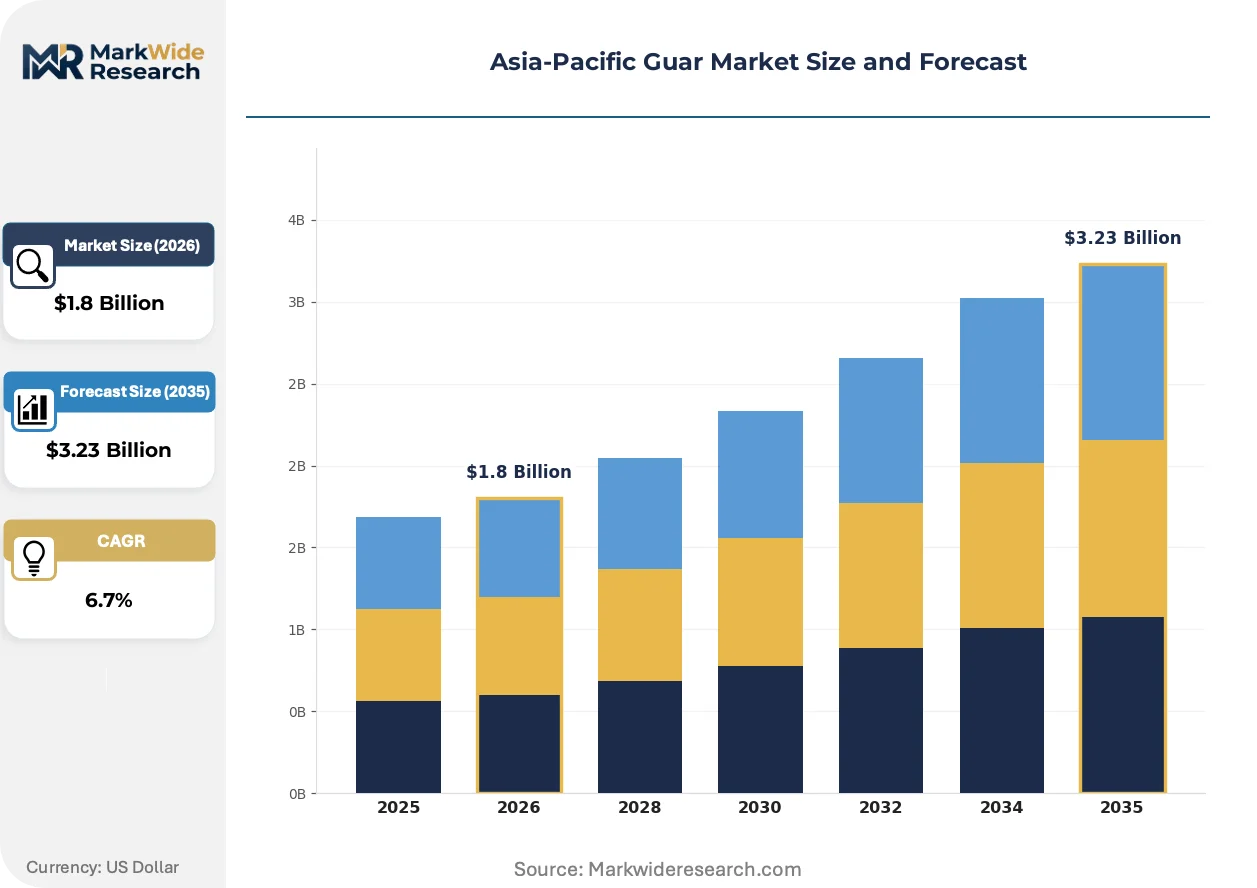
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guar Gum, Guar Meal, Guar Splits, Guar Powder End User: Food Industry, Oil & Gas, Personal Care, Pharmaceuticals Application: Thickening Agent, Fracturing Fluid, Stabilizer, Emulsifier Distribution Channel: Online Retail, Distributors, Wholesalers, Direct Sales |
| Companies Covered | India Glycols, Guar Resources, Altrafine Gums, Lucas Meyer Cosmetics Asia Pacific, Vimal International, Ashland Asia Pacific, Huanghai Vegetable Oil, Procter & Gamble Asia Pacific, Unilever Asia Pacific, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Guar Market Strategic Shifts
Digital traceability systems and clean-label formulation mandates are converging to reshape specification requirements across food, pharmaceutical, and oilfield applications in the Asia-Pacific guar value chain.
Near-infrared spectroscopy coupled with blockchain lot-tracking is digitizing quality verification at Rajasthan processing facilities. Australian oilfield procurement teams now require spectroscopic viscosity prediction certificates prior to shipment acceptance, compressing laboratory turnaround from seven days to four hours and eliminating disputed claims at port of discharge.
BIS harmonization with CODEX Alimentarius standards for food-grade guar is tightening additive labeling requirements across ASEAN markets. Processors serving Thailand and Vietnam must now declare specific galactomannan ratios on export documentation, forcing reformulation of legacy product lines and accelerating third-party certification expenditures.
Clean-label bakery and dairy alternatives in Indonesian retail channels are specifying non-GMO project verification for stabilizer inputs. Domestic formulators are bypassing traditional import distributors and contracting directly with Rajasthan processors holding dual BIS-EU Organic certification, collapsing margin layers and demanding dedicated batch-run minimums.
Asia-Pacific Guar Market Segmentation
Segmentation in the Asia-Pacific guar market reveals how product specifications, end-use requirements, and channel economics create divergent margin profiles across the value chain. Procurement cycles vary dramatically—from spot-market fracturing fluid tenders to 18-month pharmaceutical excipient qualification timelines—shaping inventory strategies and working capital needs for Rajasthan-based processors.
Product Type:
Cycle times range from immediate-delivery fracturing-grade guar gum to multi-quarter pharmaceutical powder certification batches, creating distinct cash-flow profiles across product lines.
- Guar Gum:The hydratable galactomannan polysaccharide retains irreplaceable viscosity performance in high-pressure hydraulic fracturing fluids. Australian shale operators in the Cooper Basin and Papua New Guinea's emerging plays now mandate spectroscopic viscosity prediction certificates prior to shipment, compressing laboratory turnaround from seven days to four hours and eliminating disputed claims at discharge ports.
- Guar Powder:Finely milled derivatives command premium positioning in pharmaceutical binders and cosmetic formulations. Thailand and Indonesian personal care manufacturers specify cationic guar hydroxypropyltrimonium chloride for sulfate-free shampoo systems, pulling premium-grade output away from commodity food applications and tightening supply availability for BIS-compliant exporters.
- Guar Splits:The dehusked seed endosperm serves as the intermediate feedstock for downstream gum refinement. Rajasthan's Jodhpur processing clusters concentrate over 70 percent of Asia-Pacific pharmaceutical-grade refining capacity within 200 kilometers, creating single-point vulnerability to logistics disruptions.
- Guar Meal:Protein-rich byproduct from seed crushing finds secondary markets in animal feed formulations. Indian biofuel pilot projects under the national ethanol blending mandate are exploring cellulosic ethanol applications for the seed hull fraction, creating alternative revenue streams for integrated crushers.
Guar Gum anchors the volume base while Guar Powder gains share at the steepest rate.
End User:
Cost tier differentiation separates commodity-grade food and oilfield buyers from premium pharmaceutical and personal care purchasers with stringent certification requirements.
- Oil & Gas:Australian oilfield service providers mandate higher viscosity retention under downhole temperature stress, favoring guar derivatives over synthetic polymer alternatives in high-pressure shale zones. Procurement teams now bypass traditional Middle East supply chains in favor of Rajasthan processing clusters with dedicated fracturing-grade output lines.
- Food Industry:Clean-label bakery and dairy alternatives in Indonesian retail channels specify non-GMO project verification for stabilizer inputs. BIS harmonization with CODEX Alimentarius standards forces processors serving Thailand and Vietnam to declare specific galactomannan ratios on export documentation, accelerating third-party certification expenditures.
- Pharmaceuticals:Excipient-grade exports face CDSCO and TGA dual-registration requirements extending approval cycles to 18-24 months, freezing working capital and favoring incumbent registrants with established dossiers. The therapeutic goods standards enforced by Australia's TGA regulate import quality through documented microbial specifications.
- Personal Care:Hydrolyzed guar derivatives for hair-care formulations require dedicated refining lines with cationic modification capability. Ho Chi Minh City-based manufacturers remain under-supplied with certified halal-grade inputs, presenting first-mover positioning for compliant Indian exporters.
Oil & Gas commands the largest revenue share while Food Industry applications expand most quickly through Southeast Asian retail channel penetration.
Application:
Volume concentration in industrial thickeners contrasts with margin concentration in specialized stabilizer and emulsifier functions.
- Thickening Agent:The dominant functional application spans food processing and oilfield chemistry with divergent specification requirements. BIS 2024 revisions on pesticide residue limits and microbial specifications for food-grade exports are forcing processor consolidation, eliminating sub-scale competitors and concentrating certified supply.
- Fracturing Fluid:High-viscosity hydration performance under thermal stress defines specification requirements for Australian shale exploration. Xanthan gum substitution pilots in Australia's Cooper Basin threaten guar's viscosity-performance monopoly in marginal drilling economics with low-temperature well applications.
- Stabilizer:Clean-label processed foods across ASEAN markets drive demand for declared additive transparency. Direct-to-manufacturer e-commerce platforms are collapsing traditional broker layers between Rajasthan processors and Southeast Asian small-batch food producers, compressing procurement cycles from 45 days to under 10 days.
- Emulsifier:Pharmaceutical and cosmetic formulations require precise galactomannan ratio control for shelf-stability performance. Gujarat's unorganized farmgate procurement lacks standardized moisture and foreign-matter testing, forcing processors to absorb yield variability through blending losses and reprocessing costs.
Thickening Agent applications dominate absolute volume while Fracturing Fluid specifications tighten most aggressively.
Distribution Channel:
Customer type segmentation separates large-volume direct buyers from fragmented small-batch purchasers served through intermediary layers.
- Direct Sales:Australian oilfield operators and major food manufacturers contract directly with Rajasthan processors for certified batch production. Near-infrared spectroscopy coupled with blockchain lot-tracking is digitizing quality verification, enabling real-time specification confirmation prior to shipment acceptance.
- Distributors:Traditional procurement layers persist for mid-scale pharmaceutical and personal care formulators lacking dedicated sourcing teams. Margin compression from e-commerce penetration is forcing distributor consolidation across Southeast Asian import hubs.
- Wholesalers:Bulk commodity guar gum moves through established trading networks connecting Rajasthan crushing facilities to regional processing centers. Monsoon-dependent seed supply variability from three consecutive deficient rainfall years since 2022 has triggered raw material rationing and compressed crushing margins.
- Online Retail:Emerging direct-to-manufacturer platforms target small-batch food producers in Vietnam and Indonesia with certified halal-grade offerings. These channels collapse geographic distance between Rajasthan processors and ASEAN formulators, demanding dedicated batch-run minimums and dual BIS-EU Organic certification.
Direct Sales captures the highest value transactions while Online Retail climbs the fastest as digital procurement penetrates Southeast Asian manufacturing bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Australian oilfield buyers during monsoon-deficient years, while Indian processors capture margin premiums through BIS-certified pharmaceutical-grade exports to Southeast Asian formulators.
India
Rajasthan and Gujarat crushing clusters supply over seventy percent of Asia-Pacific pharmaceutical-grade refining capacity within two hundred kilometers of Jodhpur. BIS and FSSAI frameworks enforce pesticide residue limits and microbial specifications on food-grade exports, forcing processor consolidation. Jodhpur-based facilities are digitizing quality verification through near-infrared spectroscopy coupled with blockchain lot-tracking.
Australia
Shale exploration intensity across the Cooper Basin and Papua New Guinea's emerging plays redirects guar procurement flows toward Rajasthan processing clusters. TGA therapeutic goods standards regulate pharmaceutical-grade imports through documented microbial specifications. Perth-based oilfield service providers now mandate spectroscopic viscosity prediction certificates prior to shipment acceptance.
Thailand
Personal care formulators specify cationic guar hydroxypropyltrimonium chloride for sulfate-free shampoo systems, pulling premium-grade output away from commodity food applications. The country's national food regulator enforces additive labeling requirements aligned with CODEX Alimentarius standards. Bangkok-based manufacturers remain under-supplied with certified halal-grade inputs.
Indonesia
Clean-label bakery and dairy alternatives in Jakarta and Surabaya retail channels specify non-GMO project verification for stabilizer inputs. National food safety mandates require declared galactomannan ratios on import documentation. Domestic formulators are contracting directly with Rajasthan processors holding dual BIS-EU Organic certification.
Vietnam
Ho Chi Minh City-based sauce and convenience food manufacturers present first-mover positioning opportunities for BIS-compliant Indian exporters. The country's national standards body is harmonizing with ASEAN guidelines on food additive specifications. Direct-to-manufacturer e-commerce platforms are collapsing traditional broker layers, compressing procurement cycles from forty-five days to under ten days.
Asia-Pacific Guar Market Competitive Environment
Backward-integrated seed crushers and specialty-grade refiners split the market between commodity volume plays and premium certification-driven positioning. Rajasthan's Jodhpur corridor concentrates capacity, yet single-point vulnerability to logistics disruptions creates defensive incentives for geographic diversification. Three strategic archetypes dominate: integrated crushers controlling raw material costs, pharmaceutical-grade specialists with dedicated refining lines, and hydrolyzed derivative manufacturers serving personal care formulators. Competitive moves center on dual BIS-EU Organic certification acquisition and direct e-commerce channel establishment bypassing traditional distributor layers.
Among India-based processors, India Glycols exemplifies backward-integrated seed crushing operations, Altrafine Gums occupies a position within pharmaceutical-grade refining specialists, and Lucas Meyer Cosmetics Asia Pacific represents hydrolyzed derivative manufacturers targeting personal care applications. These three anchors illustrate how geographic concentration near Jodhpur intersects with divergent certification requirements across oilfield, food, and cosmetic end-uses. Each archetype faces distinct working capital pressures: integrated crushers manage monsoon-dependent seed supply volatility, pharmaceutical specialists absorb eighteen-to-twenty-four month CDSCO and TGA dual-registration timelines, and personal care derivative producers respond to sulfate-free formulation trends pulling premium-grade output from commodity channels.
| Leading Market Players |
|---|
| India Glycols |
| Guar Resources |
| Altrafine Gums |
| Lucas Meyer Cosmetics Asia Pacific |
| Vimal International |
| Ashland Asia Pacific |
| Huanghai Vegetable Oil |
| Procter & Gamble Asia Pacific |
| Unilever Asia Pacific |
| Others |
Value Chain & Pricing Dynamics
Jodhpur's processing corridor concentrates over seventy percent of Asia-Pacific pharmaceutical-grade guar refining capacity within two hundred kilometers, handing Rajasthan crushers outsized leverage over premium-grade pricing during monsoon-deficient crop cycles. Australian oilfield buyers capture spot-market discounts on fracturing-grade gum when seed supply loosens, while BIS-certified food and pharmaceutical exports command fixed premiums regardless of commodity swings.
Pricing Analysis
The customization-premium spread separates spectroscopically-certified pharmaceutical batches from standard food-grade powder, with cationic hydrolyzed derivatives for Thai personal care formulators pricing at multiples of commodity gum. Price differentiation hinges on dual BIS-EU Organic certification and real-time viscosity prediction documentation. Cost compression in standard food-grade tiers is intensifying as Vietnamese manufacturers adopt direct e-commerce procurement, collapsing traditional broker margins. Small-batch halal-certified buyers exhibit highest price sensitivity; Australian shale operators with long-term offtake contracts show least.
Supply Chain Analysis
Contract-manufacturing concentration sits with Jodhpur-based integrated crushers and dedicated pharmaceutical refiners holding CDSCO-registered facilities. Geographic supply concentrates in India, Australia, and Thailand. Raw material dependencies rest on Rajasthan and Gujarat monsoon-dependent seed harvests, imported process chemicals for cationic modification, and specialized milling equipment from European suppliers. Single-source vulnerability to Rajasthan logistics disruptions poses structural risk. Distribution runs through direct sales for oilfield and pharmaceutical buyers, with e-commerce platforms penetrating Southeast Asian small-batch food channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific guar market is staging a cyclical recovery anchored to Australian shale exploration intensity and tightening BIS purity mandates that eliminate sub-scale competitors. Monsoon normalization would accelerate margin restoration across Rajasthan processing clusters.
For Market Incumbents: Harden defensibility by deepening backward integration into seed crushing to capture raw material cost control, and accelerate dual BIS-TGA certification investment to lock in eighteen-to-twenty-four month approval timelines that freeze out challengers. Xanthan gum substitution pilots in Australia's Cooper Basin threaten viscosity-performance monopoly; spectroscopic quality verification capabilities provide the counter-lever. For New Entrants and Emerging Players: Build out halal-certified food-grade supply to under-served Ho Chi Minh City sauce and convenience food manufacturers, where first-mover positioning remains available. Vietnam's national standards body is harmonizing with ASEAN guidelines, lowering regulatory entry barriers. Direct-to-manufacturer e-commerce channels offer the most penetrable go-to-market angle, compressing procurement cycles from traditional forty-five day broker timelines to under ten days. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-grade specialists with established CDSCO and TGA dossiers over commodity gum traders. Long-term viability across the five-to-ten year window rests on clean-label formulation tailwinds and oilfield demand durability against biofuel substitution. Acquisition target archetype: Jodhpur-based refiners with cationic modification capability and dual organic certification. The signal to watch is BIS harmonization with CODEX Alimentarius standards enforcement intensity across ASEAN import checkpoints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Crushing | India Glycols exemplifies captive raw material cost control through in-house crushing operations. |
| Spectroscopic Quality Verification Deployment | Near-infrared blockchain lot-tracking compresses laboratory turnaround from seven days to four hours. |
| Dual BIS-EU Organic Certification | Indonesian clean-label formulators now bypass distributors for certified Rajasthan processors. |
| Cationic Derivative Refining Capacity | Thai sulfate-free shampoo demand pulls premium output from commodity food channels. |
| Direct E-Commerce Channel Establishment | Platforms collapse geographic distance between Rajasthan and Vietnam small-batch manufacturers. |
Study Parameters
A spread of perspectives from Rajasthan seed crushing operators, Australian oilfield procurement leads, Thai personal care formulators, Vietnamese food manufacturing executives, and BIS regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, FSSAI export certification records, Australian TGA therapeutic goods filings, and ASEAN food additive harmonization documentation. Bottom-up seed production estimates and top-down end-use consumption models were triangulated against processor capacity utilization surveys.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, certification level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted consumption trajectories. Industry-specific forecast inputs incorporated monsoon rainfall indices for Rajasthan agricultural yields and Australian shale well completion rates.
Stress conditions across monsoon deficiency duration, xanthan substitution adoption curves, and BIS enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding seed supply recovery and clean-label penetration rates. Quarterly review of Australian shale drilling permits and Rajasthan monsoon precipitation anomalies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Wheat Flour Market
Grains
Argentina Maize Market
Grains
Canada Pulses Market
Grains
Ancient Grain Market
Grains
Africa Wheat Protein Market
Grains
Asia-Pacific Wheat Market
Grains
Soybean Market
Grains
Organic Cereals Market
Grains
South Africa Grain Market
Grains
South American Maize Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Red Rice Market
Grains
Global Oats Market
Grains
Low Fat Rice Market
Grains
Masa Corn Products Market
Grains
Global Maize Market