
 United States Maize Market | 2026-2036
United States Maize Market Size, Share, and Industry Trends Forecast 2026-2036
United States Maize Market Analytics
Non-GMO Project verification and organic certification under USDA National Organic Program standards is bifurcating the supplier base into credentialed and conventional tiers. Archer Daniels Midland Company leverages its origination network across the Midwest to sustain elevator capacity and processing throughput. Cargill Inc. anchors its position through direct farmer contracting programs that secure identity-preserved supply chains. Syngenta AG competes on seed genetics and trait platforms that differentiate yield performance under variable climate stress.
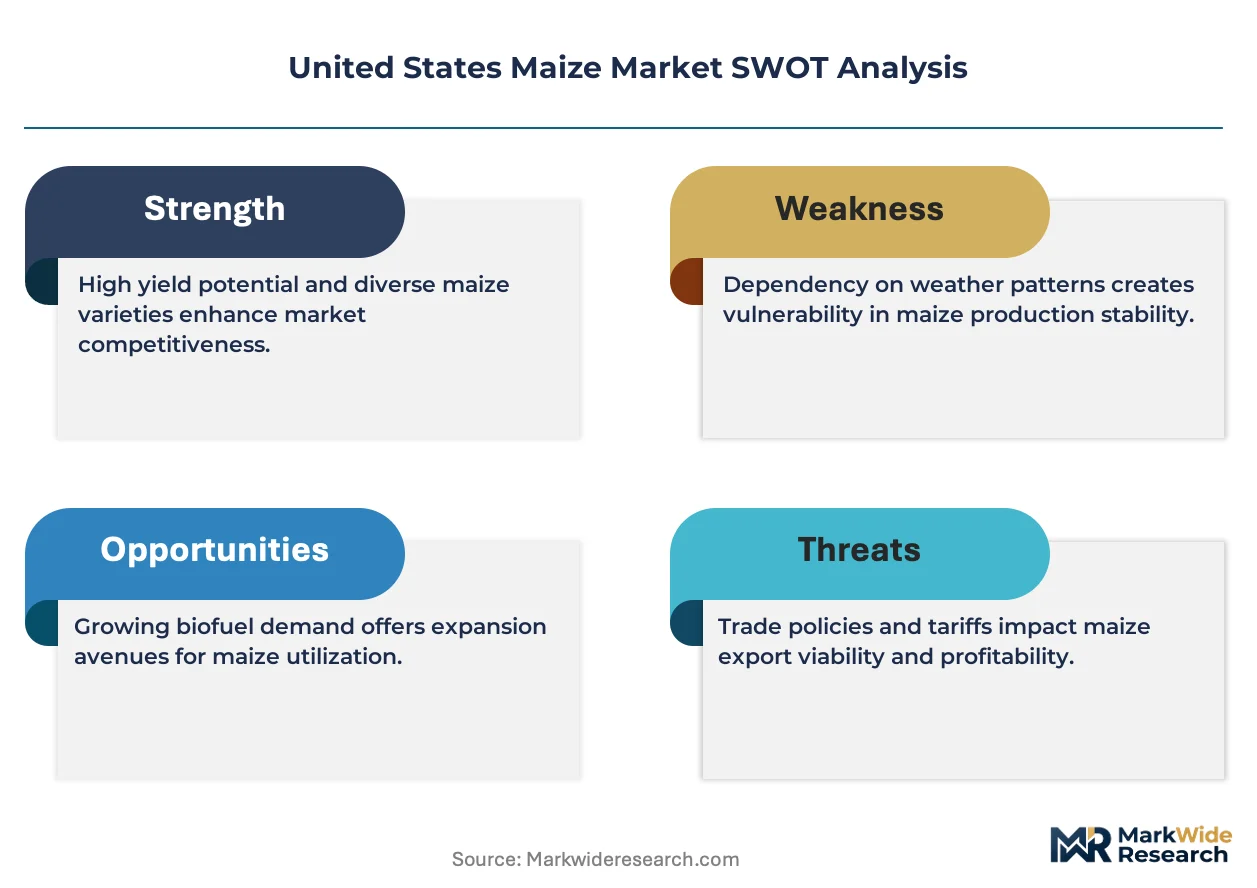
Maize, Zea mays, is a cereal grain with kernel compositions ranging from 60-75% starch, 8-12% protein, and 3-5% oil by dry weight, processed through dry milling for grits and flour or wet milling for starch, syrup, and ethanol extraction. Field corn dominates volume flows into animal feed and ethanol channels where margin pools concentrate in large-scale origination and processing. Sweet corn occupies a premium position in retail and foodservice packaging formats with higher per-unit value but smaller acreage footprint. Biofuels represents the fastest-expanding end use as renewable diesel and sustainable aviation fuel buildouts pull additional bushels from traditional feed markets.
The EPA administers Renewable Fuel Standard obligations that mandate minimum ethanol blending volumes, while the USDA operates crop insurance and conservation programs that influence planting decisions and price discovery. FDA food safety rules under FSMA govern mycotoxin thresholds and traceability requirements for human-grade maize products. Stakeholders must monitor how evolving carbon intensity scoring for biofuels and state-level low-carbon fuel standards reshape the value premium for climate-smart production practices.
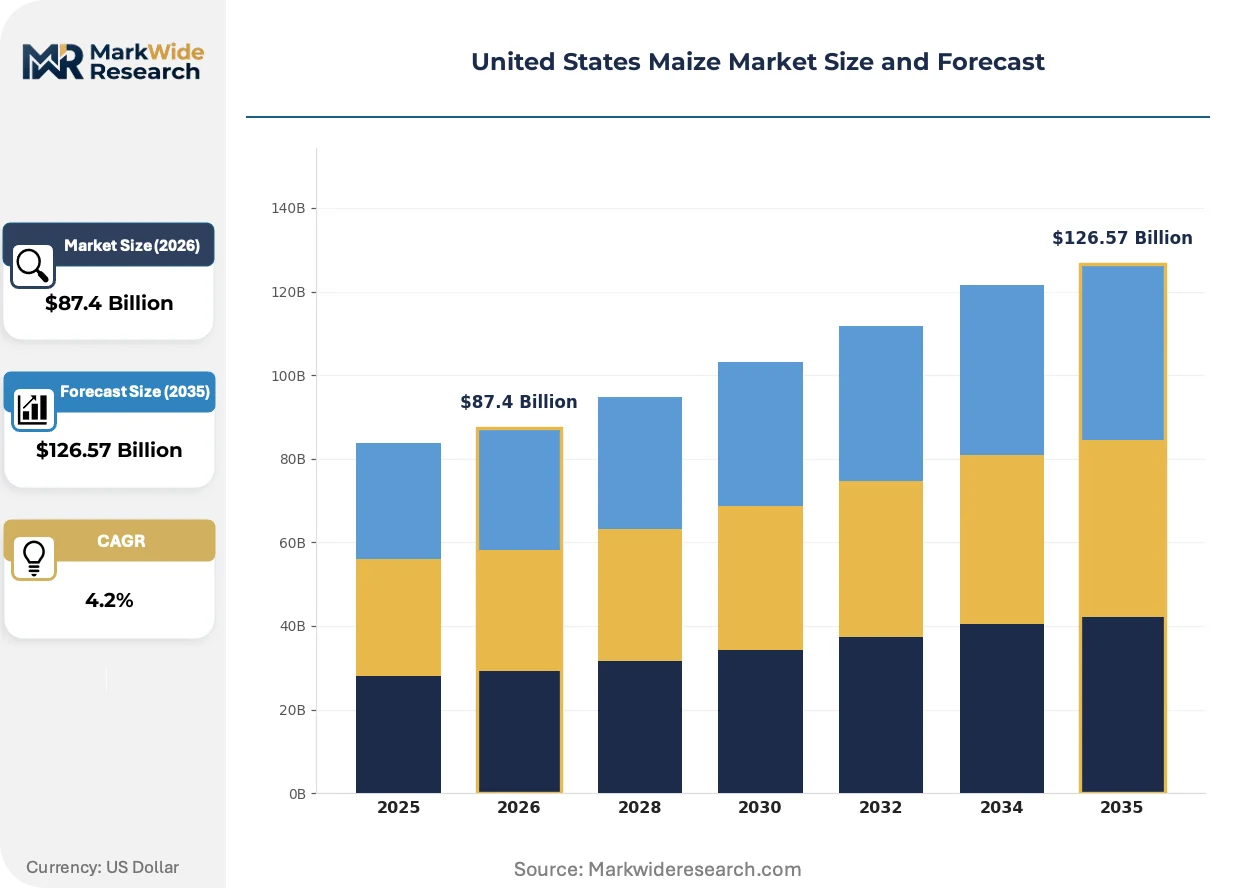
Market Dynamics
The Renewable Fuel Standard administered by the EPA is tightening blending mandates faster than processing capacity can expand, pulling field corn away from feed channels and into ethanol refineries concentrated in Iowa and Illinois.
Growth Catalysts
- EPA Renewable Fuel Standard:Escalating ethanol volume obligations under the RFS program are structurally expanding demand from biofuel producers. Corn Belt processing infrastructure is scaling to capture these mandated flows.
- Sustainable aviation fuel buildouts:Renewable diesel and SAF offtake agreements are creating new demand anchors beyond traditional road fuel blending. Midwest refiners are retooling to supply these higher-value biofuel channels.
- Carbon intensity scoring:California's Low Carbon Fuel Standard and similar state programs are attaching premiums to climate-smart production practices. Farmers adopting reduced-tillage and cover-crop rotations capture price advantages at origination.
Market Restraints
- Input cost volatility:Fertilizer and diesel prices swing with natural gas and crude benchmarks, compressing margins for Corn Belt growers. The USDA crop insurance program partially buffers this exposure but cannot eliminate cash-flow pressure.
- Supply concentration risk:Iowa and Illinois together originate over one-third of national production, creating systemic vulnerability to localized drought or flood events. Climate stress in these two states ripples through national price discovery.
- Substitution threat:Brazilian safrinha corn and Ukrainian exports compete for international feed and ethanol feedstock demand. Import parity pricing caps domestic originator margins during surplus harvests abroad.
Strategic Opportunities
- Identity-preserved channels:Non-GMO Project verification and USDA National Organic Program certification command premiums in food-grade and export markets. Elevator networks with segregation capabilities capture margin pools unavailable to commodity handlers.
- Regenerative agriculture incentives:The USDA Conservation Reserve Program and emerging carbon credit markets reward soil carbon sequestration practices. Early adopters of cover-crop and no-till systems stack multiple revenue streams per acre.
- Precision fermentation feedstocks:Biotechnology applications for alternative proteins and bio-based materials are scouting for consistent, traceable starch supplies. Corn processors with food-grade certification are piloting supply agreements with fermentation startups.
Industry Challenges
- Identity-preserved logistics:Segregating organic, non-GMO, and conventional streams through shared elevator infrastructure requires rigorous cleaning protocols and documentation. Cross-contamination events destroy premium valuations and trigger contract penalties.
- FSMA compliance timelines:FDA traceability rules under the Food Safety Modernization Act impose record-keeping burdens on handlers supplying human-grade channels. Smaller elevators lack IT infrastructure to meet these requirements without costly upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Maize Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $126.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Corn, Field Corn, Popcorn, Flaked Corn End Use Industry: Food & Beverage, Animal Feed, Industrial, Biofuels Distribution Channel: Direct Sales, Wholesale, Retail, Export Packaging Type: Bags, Bulk Containers, Boxes, Pallets |
| Companies Covered | Archer Daniels Midland Company, Cargill Inc., Bunge Limited, Syngenta AG, Corteva, Bayer, Premierbiz, Kore20 LLC, DCR Harvest LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Maize Market Evolving Landscape
Gene-edited trait platforms and digital agronomy tools are rewriting yield optimization protocols, while regulatory carbon accounting and buyer sustainability requirements are redefining what constitutes premium-grade supply.
CRISPR-edited drought-tolerance traits are fragmenting the seed market away from stacked-transgenic dominance toward precision-edited varieties with shorter development cycles. Seed companies are licensing these platforms to regional breeders serving variable soil and climate zones. The technology is fragmenting market share concentration among the largest genetics providers as smaller players gain competitive footing.
The EPA's evolving treatment of electricity and hydrogen as RFS compliance pathways is redirecting investment toward biogas capture and power-to-liquid projects at existing ethanol facilities. Refiners are evaluating carbon capture retrofits to access 45Q tax credits under the Inflation Reduction Act. Corn Belt processors with pipeline access to geologic storage are most aggressively pursuing these capital-intensive conversions.
Large livestock integrators are consolidating feed procurement under direct origination agreements with specific elevators, bypassing traditional cash-market intermediation. Tyson Foods and JBS USA are contracting directly with Iowa and Nebraska handlers for specified mycotoxin levels and moisture content. This concentration of buying power is most visible in the Southern Plains, where cattle-on-feed density supports dedicated supply chains.
United States Maize Market Segmentation
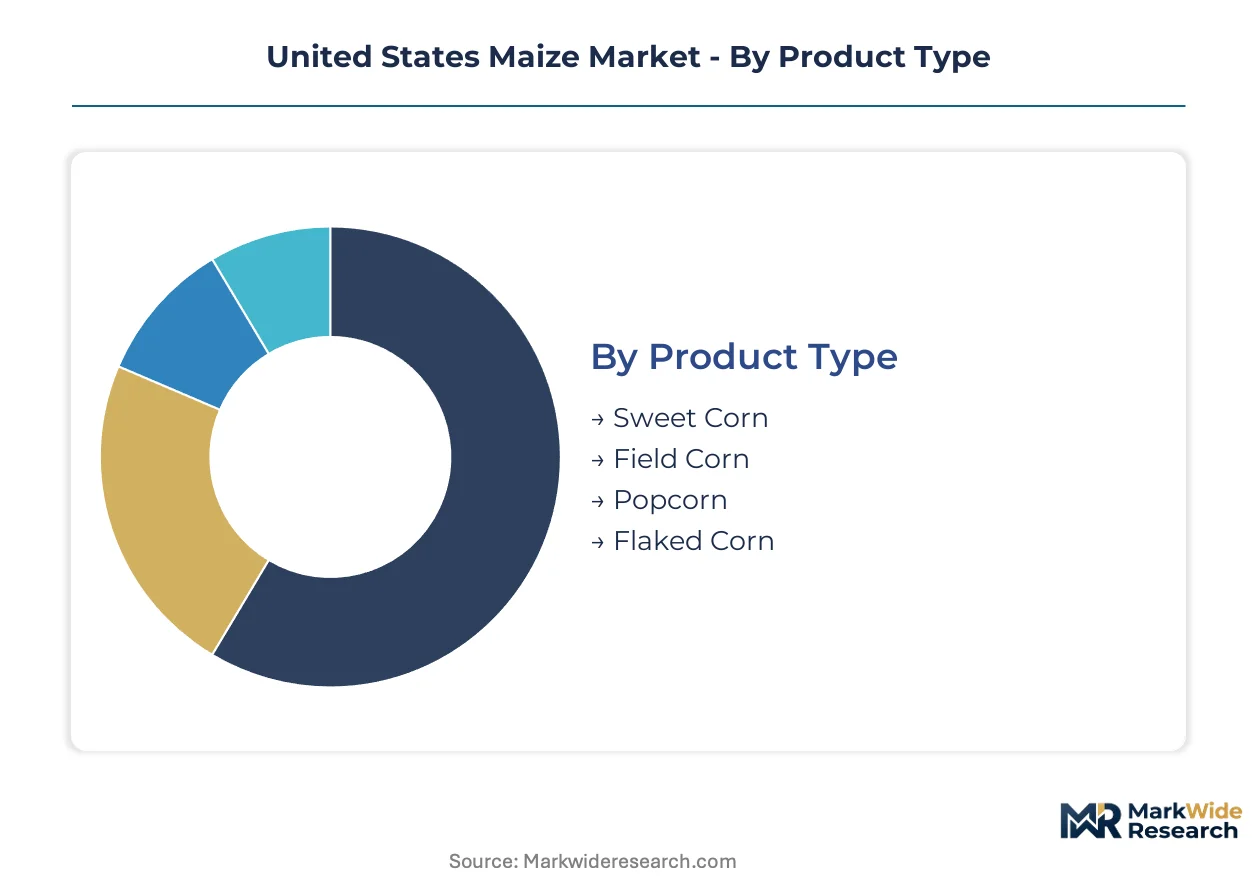
Maize segmentation in the United States reflects divergent margin structures across product grades and end-use channels. Field corn and sweet corn operate under entirely different pricing regimes, while biofuel and food-grade procurement systems demand incompatible supply chain configurations.
Product Type:
Field corn faces the most acute substitution pressure from Brazilian safrinha exports and Ukrainian supply, forcing domestic originators to defend position through origination infrastructure rather than price alone.
- Field Corn:Starch-dense kernels with 60-75% carbohydrate content by dry weight serve ethanol refineries and livestock integrators in Iowa and Illinois. Demand concentrates in Corn Belt processing corridors where elevator density creates procurement gravity for high-volume biofuel and feed channels.
- Sweet Corn:Higher sugar content (15-20% sucrose at harvest) commands per-unit premiums in retail and foodservice packaging. Consumption clusters around summer harvest windows with regional processing plants in Minnesota and Washington state supplying branded frozen and canned product lines.
- Popcorn:Specialized endosperm structure requires specific expansion ratios for concession and retail microwave segments.
- Flaked Corn:Steam-processed feed ingredient serving dairy operations in Wisconsin and New York with enhanced digestibility profiles.
Field corn anchors the volume base while sweet corn gains share at the steepest rate through branded retail and foodservice expansion.
End Use Industry:
Margin tiering separates commodity feed and fuel applications from premium food-grade channels where certification requirements create defensive moats.
- Biofuels:Ethanol refineries in Iowa, Nebraska, and Illinois consume the dominant share of field corn output under EPA Renewable Fuel Standard mandates. Capacity expansions for renewable diesel and sustainable aviation fuel are pulling additional bushels from traditional livestock feed markets.
- Food & Beverage:Wet milling operations extract starch, high-fructose syrup, and food-grade oil for packaged goods manufacturers. Human-grade channels impose FDA FSMA traceability requirements and mycotoxin thresholds that exclude commodity elevator supply.
- Animal Feed:Cattle-on-feed operations in Texas, Kansas, and Nebraska represent concentrated demand for dry-rolled and flaked corn.
- Industrial:Starch derivatives supply paper, textile, and adhesive manufacturers with specifications distinct from fuel or feed grades.
Animal feed historically anchored volume offtake while biofuels climbs the fastest as RFS obligations tighten and SAF buildouts accelerate.
Distribution Channel:
Customer type determines whether supply moves through arm's-length cash markets or captive origination networks with quality specifications.
- Direct Sales:Large livestock integrators and ethanol refiners contract directly with specific elevators for moisture content, mycotoxin levels, and delivery timing. Tyson Foods and JBS USA have consolidated procurement under direct origination agreements bypassing traditional intermediaries.
- Wholesale:Regional grain merchants aggregate elevator receipts for resale to processors lacking origination infrastructure.
- Retail:Sweet corn and specialty popcorn reach consumers through grocery and foodservice channels with branded packaging requirements.
- Export:Gulf Coast and Pacific Northwest terminals handle bulk shipments competing with Brazilian and Argentine supply in Asian feed markets.
Direct sales anchors the volume base for commodity grades while export channels face the steepest competitive pressure from South American supply.
Packaging Type:
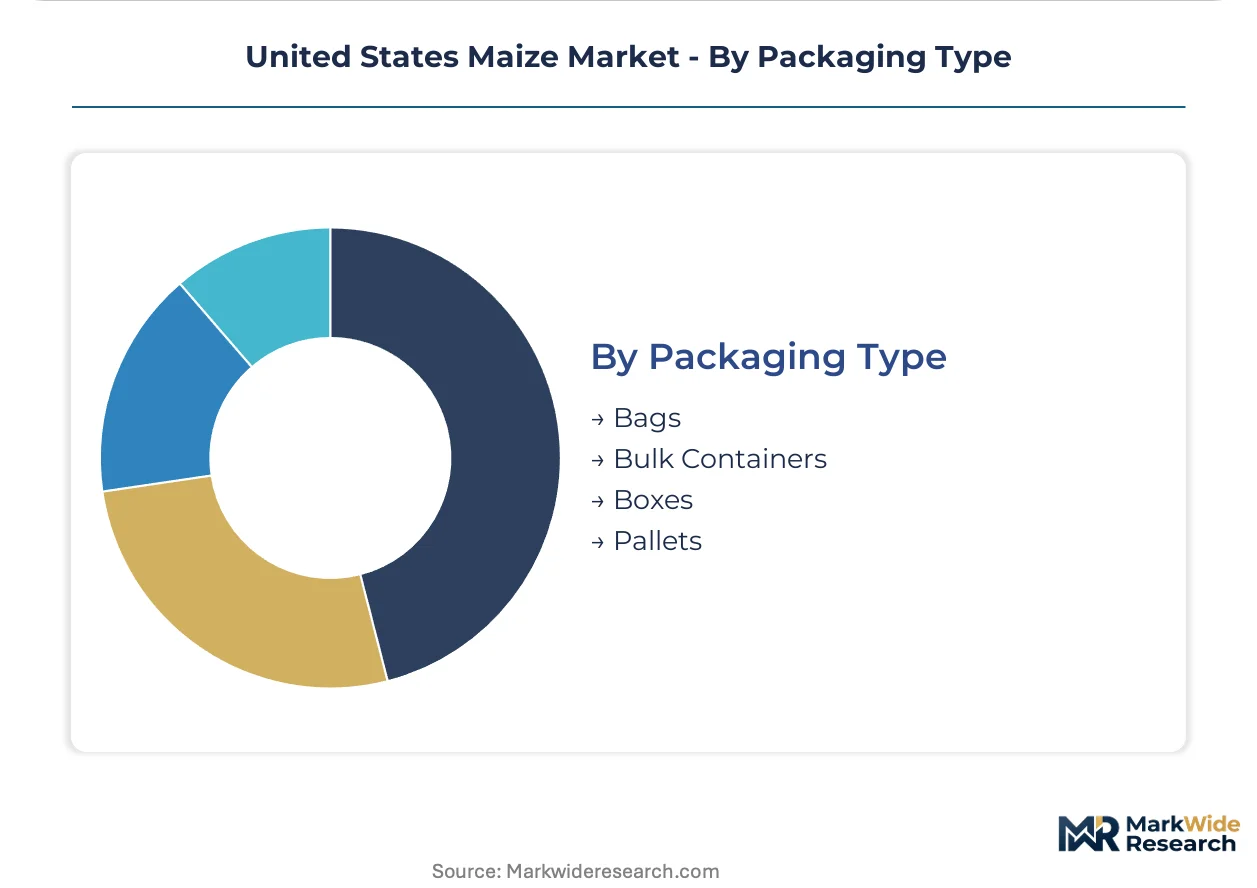
Scale economics favor bulk handling for ethanol and feed channels while food-grade and export segments require bagged or containerized configurations.
- Bulk Containers:Unit trains and barge movements dominate Corn Belt-to-Gulf logistics for ethanol and export origination. Rail siding access at Iowa and Illinois elevators determines competitive positioning for high-volume handlers.
- Bags:50-pound and bulk bags serve retail sweet corn, popcorn, and small-scale livestock operations with identity-preserved requirements.
- Boxes:Fresh sweet corn and value-added products use corrugated packaging for foodservice and retail distribution.
- Pallets:Unitized loads facilitate warehouse handling for processed ingredients and export container stuffing.
Bulk containers anchor the volume base for field corn origination while bags capture expanding share in organic and non-GMO identity-preserved channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethanol refiners and livestock integrators concentrate procurement in Corn Belt states where elevator density and processing infrastructure create localized demand gravity. USDA crop insurance and conservation programs shape planting decisions across sub-regions with divergent soil profiles and climate exposure.
Iowa
Ethanol refineries in Council Bluffs and Cedar Rapids consume the dominant share of field corn output under EPA Renewable Fuel Standard mandates. The USDA operates crop insurance frameworks that buffer revenue risk for growers adopting cover-crop rotations. Processing corridor density between Des Moines and Dubuque anchors origination gravity for high-volume biofuel channels.
Illinois
Decatur and Peoria wet milling complexes extract starch and high-fructose syrup for packaged goods manufacturers with FDA FSMA traceability requirements. The EPA administers RFS blending obligations that tighten faster than regional processing capacity expands. Rail siding access at Springfield and Champaign elevators determines competitive positioning for unit train movements to Gulf export terminals.
Nebraska
Cattle-on-feed operations in the Platte River Valley contract directly with elevators for specified mycotoxin levels and moisture content. USDA Conservation Reserve Program incentives reward reduced-tillage practices that sequester soil carbon for emerging credit markets. Omaha-based origination networks bypass traditional cash-market intermediation through captive procurement agreements with Tyson Foods and JBS USA.
Indiana
Renewable diesel and sustainable aviation fuel buildouts at Whiting and Mount Vernon refineries pull additional bushels from traditional livestock feed markets. State-level low-carbon fuel standards attach premiums to climate-smart production practices verified through third-party protocols. Lafayette and Muncie elevator clusters serve as aggregation points for identity-preserved organic and non-GMO channels commanding food-grade premiums.
Minnesota
Sweet corn processing plants in the Red River Valley supply branded frozen and canned product lines with regional harvest window constraints. The FDA governs mycotoxin thresholds and traceability requirements that exclude commodity elevator supply from human-grade channels. Rochester and Mankato food-grade certification facilities pilot supply agreements with precision fermentation startups scouting for consistent starch feedstocks.
United States Maize Market Competitive Landscape
Player mix skews toward integrated agribusiness conglomerates with origination networks spanning multiple Corn Belt states. Structure concentrates in handlers with elevator capacity and processing throughput rather than pure trading operations. Three archetypes dominate: seed genetics providers licensing trait platforms, grain merchants with direct farmer contracting programs, and diversified processors with wet and dry milling capabilities. Competitive moves center on strategic partnerships for identity-preserved supply chains and capacity expansions for renewable diesel feedstock pretreatment.
Among diversified processing conglomerates, Archer Daniels Midland Company and Cargill Inc. exemplify the integrated origination-to-processing archetype, while Syngenta AG occupies a position within the seed genetics tier. These entities represent contrasting strategic postures: the former anchor elevator density and processing throughput, the latter competes on trait differentiation and yield performance under variable climate stress. Bunge Limited sits within the merchant-handler segment with export terminal access.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Inc. |
| Bunge Limited |
| Syngenta AG |
| Corteva |
| Bayer |
| Premierbiz |
| Kore20 LLC |
| DCR Harvest LLC |
| Others |
Value Network & Pricing Analysis
Thirty-to-forty-five day elevator inventory cycles in Iowa and Illinois determine origination pricing power, compressing spot premiums when barge logistics back up and amplifying handler margins when rail capacity tightens during harvest windows.
Pricing Analysis
Cost-plus contracts indexed to the Chicago Board of Trade corn futures dominate field corn procurement between Corn Belt elevators and ethanol refiners. Price differentiation hinges on moisture content specifications and mycotoxin certification tiers required by FDA FSMA rules for human-grade channels. Pricing pressure stems from Brazilian safrinha corn import parity during surplus harvests, eroding domestic originator margins. Livestock integrators exhibit highest price sensitivity due to thin feed conversion economics, while sustainable aviation fuel offtakers absorb premiums for low-carbon intensity verified supply.
Supply Chain Analysis
The United States, Brazil, and Ukraine anchor global maize supply, with the Corn Belt originating over one-third of domestic production concentrated in Iowa and Illinois. Supply chains draw from phosphate fertilizer inputs tied to natural gas benchmarks, diesel for field operations, and specialized seed genetics from Syngenta and Corteva. Single-source vulnerability concentrates in Gulf Coast export terminals where hurricane disruptions ripple through international feed markets. Distribution runs through unit train corridors to ethanol refineries and barge movements to Pacific Northwest export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting services and regenerative agriculture verification represent the fastest-expanding recurring revenue layer, outpacing elevator handling fees as buyers attach sustainability premiums to origination contracts.
For Market Incumbents: Fortify elevator networks in Nebraska and Indiana with identity-preserved segregation infrastructure to capture organic and non-GMO premiums before Brazilian exporters scale certified supply. Defend against precision fermentation feedstock displacement by piloting direct contracts with biotechnology startups seeking traceable starch streams. Prioritize USDA Conservation Reserve Program enrollment support as a farmer-retention lever. For New Entrants and Emerging Players: Lead with carbon intensity scoring verification services for Indiana and Iowa growers supplying California Low Carbon Fuel Standard markets, where third-party protocol expertise remains undersupplied. Target small-to-midsize elevators lacking IT infrastructure for FDA FSMA traceability compliance. Position through SaaS-based documentation platforms that automate mycotoxin chain-of-custody records. For Investors and Strategic Acquirers: Long-term, this sits as a climate-infrastructure play because renewable diesel and sustainable aviation fuel buildouts structurally expand demand for low-carbon feedstocks beyond traditional ethanol channels. Acquisition targets cluster at regional elevator networks with rail siding access and existing organic certification capabilities. Monitor EPA Renewable Fuel Standard volume obligation announcements as the critical inflection signal for processing capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Identity-Preserved Infrastructure Investment | Segregation capabilities at Iowa and Illinois elevators capture organic premiums unavailable to commodity handlers. |
| Carbon Capture Retrofit Partnership | Ethanol facilities with pipeline access to geologic storage qualify for 45Q tax credits under the Inflation Reduction Act. |
| Direct Farmer Contracting Program | Cargill-style origination agreements bypass cash-market intermediation for Tyson Foods and JBS USA procurement. |
| Precision Fermentation Feedstock Pilot | Food-grade certified processors in Minnesota secure first-mover supply agreements with alternative protein startups. |
| Regenerative Agriculture Verification Service | Third-party soil carbon protocols unlock USDA Conservation Reserve Program and private credit market revenue stacking. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA crop insurance databases, EPA Renewable Fuel Standard compliance filings, and Chicago Board of Trade futures data. Primary interviews engaged elevator operators, ethanol refinery procurement managers, livestock integrator feed directors, and seed genetics platform executives. Secondary validation drew from USDA National Agricultural Statistics Service acreage reports, EIA biofuel production surveys, and FDA FSMA guidance documents. Bottom-up acreage and yield estimates triangulate against top-down processing capacity utilization across the Corn Belt.
Segmentation dimensions modeled include product type spanning field corn, sweet corn, and specialty grades; end-use industry covering biofuels, animal feed, and food-grade channels; and distribution channel structure from direct origination to export terminal movements. CAGRs derive from ethanol mandate trajectory analysis, sustainable aviation fuel offtake agreement pipelines, and livestock inventory cycle projections. Industry-specific inputs incorporate EPA RFS volume obligation schedules and state-level low-carbon fuel standard adoption patterns.
Forecasts assume regulatory continuity in EPA RFS administration and USDA crop insurance frameworks; material policy shifts would require re-modeling. Specific risks include Brazilian safrinha export surge volumes, Ukraine Black Sea corridor disruptions, and fertilizer price volatility tied to natural gas benchmarks. Recalibration cycles align with material shifts in biofuel mandate announcements and carbon intensity scoring protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Flour Market
Grains
China Wheat Protein Market
Grains
Grain Dryers Market
Grains
Global Maize Market
Grains
Africa Wheat Protein Market
Grains
White Rice Flour Market
Grains
Grain Storage Silos Market
Grains
Precooked Flour Market
Grains
Global Precooked Corn Flour Market
Grains
Mesquite Flour Market
Grains
North America Pulses Market
Grains
Canada Pulses Market
Grains
Brown Rice Market
Grains
Grain and Cereal Crop Market
Grains
Grain Storage Systems Market
Grains
Europe Maize Market