
 Europe Micronutrient Fertilizer Market | 2026-2036
Europe Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Micronutrient Fertilizer Market Foresight
Asset-light leasing models for precision application equipment is narrowing the capital barrier for smaller agronomy service providers across Southern Europe. BASF SE leverages its integrated nutrient stewardship platforms to sustain premium positioning in zinc and boron formulations. Yara International ASA anchors its competitive position through controlled-release technology partnerships with cooperative networks. Grupa Azoty S.A. (Compo Expert) specializes in tailored micronutrient blends for high-value vegetable production in Poland and neighboring markets.
Micronutrient fertilizers are chemically formulated compounds containing essential trace elements—zinc, iron, manganese, and boron—typically applied at rates below ten kilograms per hectare to correct soil deficiencies and optimize plant metabolic functions. These formulations serve primarily to prevent hidden hunger in intensive cropping systems where macronutrient-only programs deplete trace element reserves. Zinc dominates product type revenue due to its critical role in enzyme activation across cereal systems, while boron formulations command margin premiums in fruit and vegetable applications where deficiency symptoms cause immediate quality loss. The direct sales channel to agricultural cooperatives captures the deepest volume pools, though online retail is displacing traditional agronomy stores for repeat purchases among technologically progressive farmers.
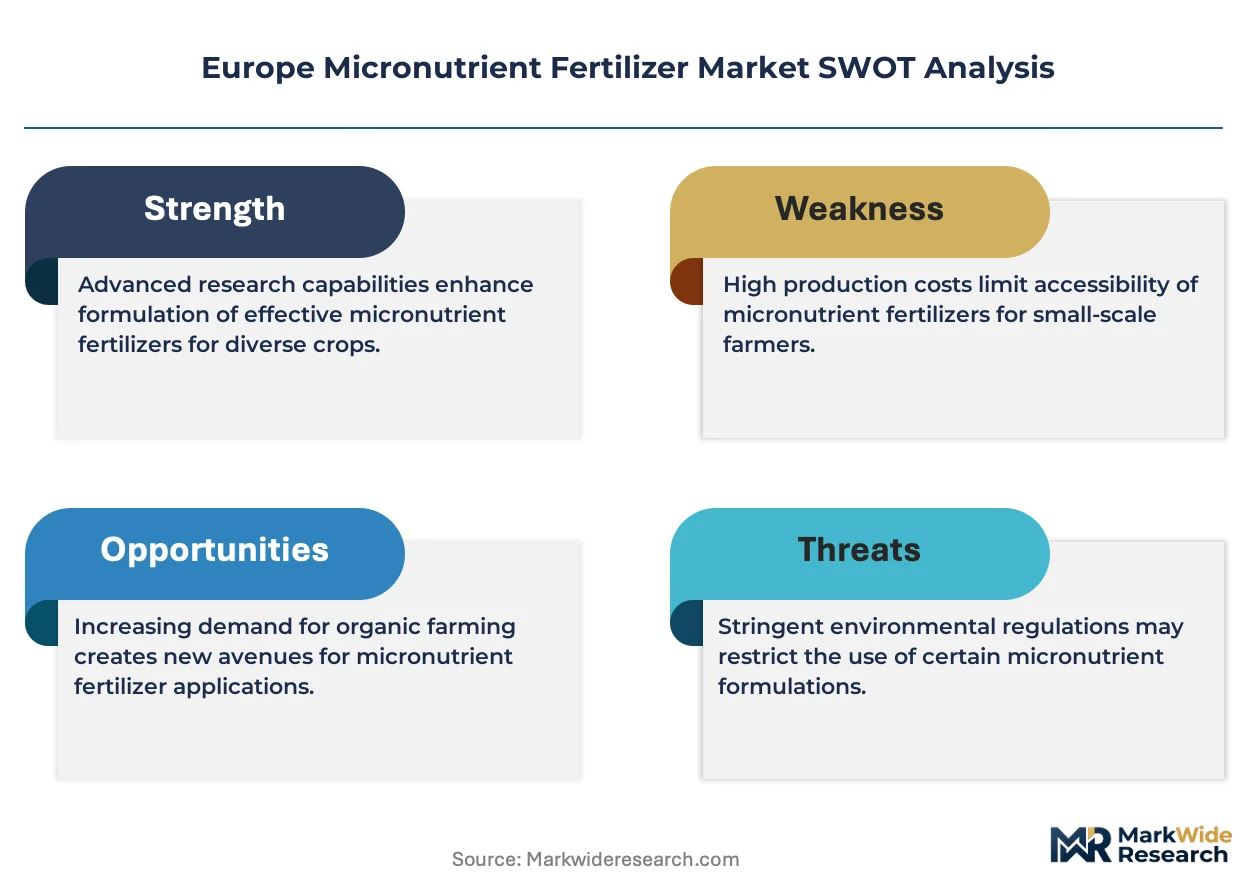
REACH registration requirements and the EU Green Deal nutrient management frameworks are tightening permissible heavy metal thresholds in micronutrient products, forcing reformulation investments across manufacturers. EFSA guidelines on maximum residue levels further constrain application timing and concentration limits for food crops. The F-Gas Regulation indirectly pressures greenhouse operators toward closed-loop fertigation systems with precise micronutrient dosing. Stakeholders must monitor evolving CE marking requirements for novel biostimulant-micronutrient combination products and assess whether backward integration into raw material sourcing offsets regulatory compliance costs.
Market Dynamics
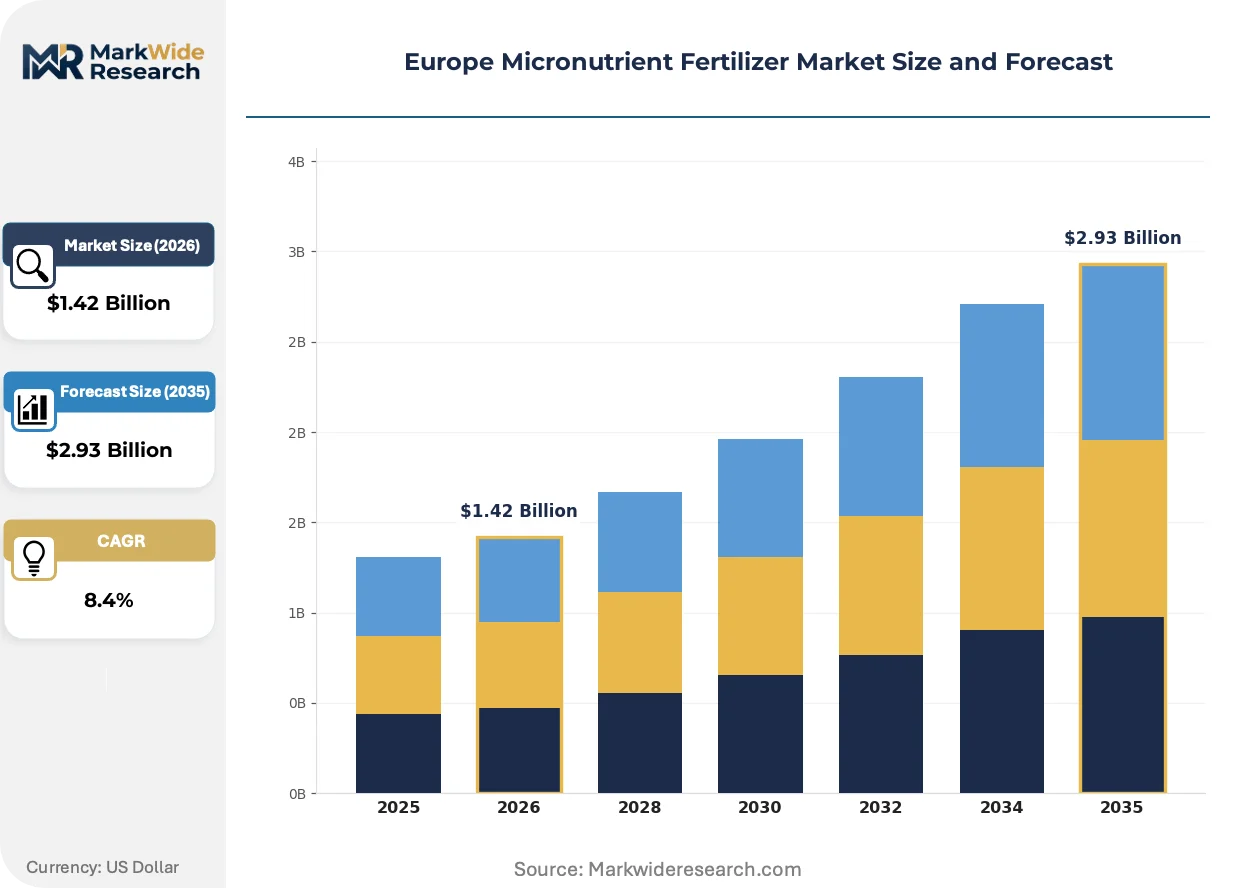
The EU Green Deal's nutrient management targets are compressing application windows and mandating precision dosing systems across European intensive cropping zones. This regulatory architecture is forcing simultaneous reformulation of legacy products and capital deployment into variable-rate application infrastructure.
Growth Catalysts
- REACH compliance deadlines:Heavy metal threshold reductions are accelerating replacement demand for certified low-impurity formulations in Germany's cereal belt and France's wine regions.
- Controlled-release technology diffusion:Polymer-coated micronutrient granules are penetrating Poland's vegetable cooperatives and Spain's greenhouse clusters through equipment leasing partnerships.
- Zinc deficiency mapping:Soil testing mandates under national CAP strategic plans are expanding addressable hectares in Hungary, Romania, and Bulgaria's cereal systems.
Market Restraints
- Sulfuric acid cost volatility:Feedstock price swings for zinc sulfate production are compressing margin stability for mid-scale blenders in Central Europe.
- Single-source dependency:Boron raw material concentration in Turkish and Russian suppliers creates supply security exposure for Southern European formulators.
- Application timing restrictions:EFSA maximum residue level constraints are narrowing pre-harvest windows for foliar boron in Mediterranean fruit crops.
Strategic Opportunities
- Baltic States penetration gap:Estonia, Latvia, and Lithuania maintain sub-15% micronutrient adoption rates in cereal production, creating first-mover terrain for precision service providers.
- Biostimulant-micronutulant convergence:Novel combination products targeting CE marking pathways are opening premium positioning in Italy's organic vegetable sector.
- Cooperative data integration:France's Axereal and InVivo networks are piloting subscription-based nutrient prescription platforms that lock in multi-year formulation contracts.
Industry Challenges
- Agronomic technician scarcity:Precision application calibration and tissue diagnostics expertise is concentrating in Western European service providers, constraining Southern and Eastern European expansion velocity.
- Legacy equipment incompatibility:Variable-rate spreaders and closed-loop fertigation systems require retrofitting or replacement of 40% of installed application machinery in Spain and Portugal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Micronutrient Fertilizer Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc, Iron, Manganese, Boron Application: Cereals, Fruits, Vegetables, Oilseeds Distribution Channel: Online Retail, Direct Sales, Wholesalers, Agronomy Stores End User: Farmers, Horticulturists, Greenhouse Operators, Agricultural Cooperatives |
| Companies Covered | BASF SE, Fertiberia, Grupa Azoty S.A. (Compo Expert), Trade Corporation International, AGLUKON Spezialduenger GmbH & Co, Yara International ASA, ICL Group, Valagro, Haifa Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Micronutrient Fertilizer Market Shifts & Advancements
Formulation chemistry and application hardware are converging to enable sub-kilogram-per-hectare dosing precision. This convergence is collapsing the historical trade-off between application labor efficiency and nutrient use optimization.
Controlled-release polymer coatings for zinc and boron granules are collapsing the economic viability of conventional bulk-blended applications in high-value vegetable systems. Dutch greenhouse operators and Spanish protected-crop growers are adopting these formulations at 23% annual expansion rates. The technology is collapsing differentiation between premium and standard product tiers by delivering equivalent efficacy at reduced labor intensity.
REACH Annex XVII heavy metal limit reductions are forcing raw material purification investments across European manufacturing facilities. ECHA registration dossier updates are consuming 18-24 month compliance timelines for reformulated products. Zinc oxide and copper sulfate categories face the steepest technical barriers, with German and French regulators conducting enhanced substance evaluation reviews.
Cooperative procurement consolidation is compressing supplier negotiation cycles across France, Germany, and Benelux agronomy networks. Large-scale farming groups are unbundling agronomic advisory from product supply, displacing traditional distributor margin structures. This pattern is most pronounced in Denmark's DLG and Germany's BayWa cooperative systems, where centralized tendering now covers 60% of micronutrient volume.
Europe Micronutrient Fertilizer Market Segmentation
Micronutrient fertilizer segmentation reveals distinct performance profiles across crop systems and procurement channels. Each dimension carries specific regulatory and agronomic constraints that reshape supplier positioning.
Product Type:
The use-case spectrum spans soil correction priorities from enzyme activation to reproductive tissue development.
- Zinc:Sulfate and oxide formulations dominate cereal belt applications across Germany and Poland. Hungary's soil testing mandates under CAP strategic plans are expanding addressable hectares for zinc deficiency correction in maize and wheat systems.
- Boron:Soluble borates and complexed formulations command premium positioning in Mediterranean fruit production. EFSA maximum residue level constraints are narrowing pre-harvest application windows for Spanish and Italian stone fruit growers.
- Iron:Chelated iron formulations address calcareous soil chlorosis in Southern European vineyards and orchards.
- Manganese:Sulfate-based products target deficiency correction in alkaline soils across France's cereal cooperatives.
Zinc dominates installed base. Boron is where expansion concentrates.
Application:
Cost tier differentiation separates high-volume commodity crops from precision-managed specialty systems.
- Cereals:Zinc-dominant programs cover extensive wheat and maize rotations across Central European farming cooperatives. Variable-rate application infrastructure investments in Germany's precision farming sector are tightening dosing accuracy requirements.
- Vegetables:Intensive boron and manganese protocols dominate protected-crop systems in Spain's Almeria greenhouses and Dutch glasshouse clusters. Controlled-release polymer coatings are displacing conventional bulk-blended applications at 23% annual expansion rates.
- Fruits:Quality-sensitive stone fruit and citrus operations in Italy and Greece drive foliar micronutrient premiums.
- Oilseeds:Rapeseed and sunflower rotations in France and Romania require balanced zinc-boron programs for yield stability.
Cereals capture volume concentration. Vegetables are climbing the fastest.
Distribution Channel:
Customer type fragmentation splits between consolidated cooperative procurement and fragmented individual farmer purchasing.
- Direct Sales:Agricultural cooperative networks in France, Germany, and Denmark centralize tendering for 60% of micronutrient volume. Axereal and InVivo pilot subscription-based nutrient prescription platforms locking in multi-year formulation contracts.
- Agronomy Stores:Traditional distributor margins compress as large farming groups unbundle advisory from product supply across Benelux markets.
- Online Retail:Repeat purchase displacement accelerates among technologically progressive farmers bypassing traditional agronomy stores.
- Wholesalers:Mid-scale blenders in Central Europe rely on sulfuric acid feedstock sourcing for zinc sulfate production.
Direct sales anchor volume capture. Online retail is gaining share fastest.
End User:
Application maturity separates precision-capable operators from legacy equipment-dependent segments.
- Agricultural Cooperatives:France's cooperative networks and Germany's BayWa system deploy centralized procurement with integrated nutrient stewardship platforms. Equipment leasing partnerships for precision application hardware narrow capital barriers for member farms.
- Greenhouse Operators:Dutch and Spanish protected-crop specialists adopt closed-loop fertigation systems under F-Gas Regulation pressure, requiring precise micronutrient dosing infrastructure.
- Farmers:Individual cereal producers in Baltic States maintain sub-15% micronutrient adoption rates, creating first-mover terrain for service providers.
- Horticulturists:High-value vegetable producers in Poland and Italy drive tailored micronutrient blend demand.
Agricultural cooperatives dominate procurement scale. Greenhouse operators are where technology adoption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural cooperatives in Germany and France anchor procurement scale, while precision farming adoption concentrates in the Netherlands and Spain's greenhouse clusters. REACH compliance deadlines and CAP strategic plan soil testing mandates are reshaping demand patterns across national boundaries.
Germany
Precision farming cooperatives in Lower Saxony and Bavaria deploy variable-rate spreaders for zinc-dominant cereal programs. REACH Annex XVII heavy metal threshold reductions force reformulation investments among sulfate manufacturers. The BayWa network centralizes tendering for 60% of national micronutrient volume through subscription-based nutrient stewardship platforms.
France
Axereal and InVivo cooperative networks pilot multi-year formulation contracts locking in zinc-boron blends for rapeseed rotations. EFSA maximum residue level guidelines constrain pre-harvest foliar application windows in Champagne and Burgundy wine regions. Calcareous soil chlorosis in Southern vineyards drives chelated iron formulation premiums.
Spain
Almeria greenhouse operators adopt closed-loop fertigation systems under F-Gas Regulation pressure, requiring precise boron dosing infrastructure. Mediterranean stone fruit growers in Valencia face compressed application windows from residue constraints. Asset-light equipment leasing partnerships narrow capital barriers for protected-crop specialists.
Poland
Vegetable cooperatives in Greater Poland and Silesia expand controlled-release polymer-coated granule adoption at 23% annual rates. CAP strategic plan soil testing mandates reveal zinc deficiency across maize hectares in Mazovia. Grupa Azoty S.A. tailors micronutrient blends for high-value tomato and pepper production.
Netherlands
Dutch glasshouse clusters in Westland and Aalsmeer pioneer sub-kilogram-per-hectare dosing precision through integrated fertigation systems. Polymer-coated boron formulations displace conventional bulk-blended applications in orchid and tomato operations. Equipment-technology convergence collapses labor efficiency trade-offs for greenhouse operators.
Europe Micronutrient Fertilizer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Cooperative networks in France, Germany, and Denmark consolidate 60% of volume through centralized tendering, compressing distributor margins. Three archetypes dominate: integrated nutrient stewardship platforms, controlled-release technology specialists, and tailored blend providers for high-value crops. Strategic moves concentrate on equipment leasing partnerships and backward integration into raw material sourcing.
Within the integrated platform tier, BASF SE and Yara International ASA anchor positions through cooperative network relationships and technology licensing structures. Grupa Azoty S.A. (Compo Expert) occupies a specialist position serving vegetable production systems in Central European markets. These three entities exemplify the competitive tension between scale-driven channel control and application-specific formulation expertise.
| Leading Market Players |
|---|
| BASF SE |
| Fertiberia |
| Grupa Azoty S.A. (Compo Expert) |
| Trade Corporation International |
| AGLUKON Spezialduenger GmbH & Co |
| Yara International ASA |
| ICL Group |
| Valagro |
| Haifa Group |
| Others |
Supply & Pricing Matrix
Overcapacity in Central European zinc sulfate production is compressing supplier pricing power and accelerating consolidation among mid-scale blenders. This utilization imbalance forces manufacturers to absorb REACH compliance costs rather than pass them through, while cooperative buyers exploit tender leverage across Germany and France.
Pricing Analysis
Certification level (REACH-compliant low-heavy-metal formulations versus legacy grades) creates the primary spread between premium and standard tiers. Cooperative networks in France and Germany deploy contract-based long-term offtake structures that lock in multi-year pricing, while individual farmers face spot-market volatility. Price differentiation hinges on ECHA registration status and polymer-coating technology bundling. Cost compression in standard-grade zinc sulfate is intensifying because sulfuric acid feedstock volatility erodes blender margins. Smallholder cereal producers in the Baltic States exhibit highest price sensitivity, whereas Dutch greenhouse operators accept premium positioning for closed-loop fertigation compatibility.
Supply Chain Analysis
Contract-manufacturing concentration among Turkish and Russian boron raw material suppliers creates single-source vulnerability for Southern European formulators. Geographic supply centers on Germany's integrated chemical complexes, Poland's fertilizer blending facilities, and Dutch greenhouse input distributors. The chain draws from sulfuric acid feedstocks, zinc oxide concentrates, and borate minerals. Supply chain risk centers on geopolitical exposure to Turkish-Russian boron concentration. Distribution runs through cooperative procurement networks that centralize 60% of volume across France, Germany, and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH compliance timelines and ECHA registration dossiers create switching costs that lock cooperative buyers into validated supplier relationships.
For Market Incumbents: Insulate market position through backward integration into zinc oxide purification capacity and polymer-coating technology licensing. Threats from emerging biostimulant-micronutrient convergence products demand accelerated CE marking investment. Priority lever rests on equipment leasing partnerships that narrow capital barriers for cooperative network expansion.
For New Entrants and Emerging Players: Establish a beachhead in Estonia, Latvia, and Lithuania's sub-15% adoption cereal markets through precision service bundling. The Baltic States penetration gap offers lowest competitive density. Target Poland's vegetable cooperatives with controlled-release formulation partnerships. Go-to-market angle leverages soil testing mandate compliance as entry wedge.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative network-integrated platforms with multi-year nutrient stewardship contracts. Long-term viability favors entities with captive raw material sourcing and REACH-registered product portfolios. Acquisition target archetype: mid-scale blenders with Central European manufacturing footprint and pending ECHA dossier approvals. Signal to watch is CAP strategic plan soil testing mandate expansion into Romania and Bulgaria.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive zinc oxide supply secures margin stability against sulfuric acid volatility. |
| Controlled-Release Technology Licensing | Polymer-coating partnerships with Dutch greenhouse operators accelerate premium positioning. |
| Cooperative Data Platform Integration | Subscription-based nutrient prescription locks in multi-year formulation contracts across France. |
| CE Marking Pathway for Biostimulant Combinations | Novel product categories open premium positioning in Italy's organic vegetable sector. |
| Equipment Leasing Partnership Expansion | Asset-light models narrow capital barriers for Southern European agronomy service providers. |
Research Methodology
Cross-validation between cooperative procurement managers and ECHA regulatory filings anchors the qualitative findings. Primary interviews engaged formulation chemists at major manufacturers, agronomy directors at French and German cooperatives, greenhouse operations managers in the Netherlands and Spain, and Baltic States cereal producers. Secondary validation drew from REACH registration dossiers, EU Green Deal nutrient management frameworks, CAP strategic plan submissions, and customs trade data for zinc sulfate and borate imports. Bottom-up hectare-expansion modeling and top-down cooperative volume aggregation were triangulated.
Calibration against historical adoption curves in comparable regulatory environments refined the analytical framework. Segmentation dimensions modeled include micronutrient type, crop application, distribution channel, and end-user sophistication tier across the projection horizon. CAGRs were derived from hectare penetration rates multiplied by application intensity assumptions. Industry-specific forecast inputs incorporated soil testing mandate rollout schedules and F-Gas Regulation compliance timelines for greenhouse operators.
Stress conditions across sulfuric acid price volatility, Turkish-Russian boron supply disruption, and EFSA residue limit tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cooperative procurement consolidation velocity and precision equipment adoption curves. Quarterly review of CAP strategic plan implementation progress and ECHA substance evaluation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Nitrogen Nutrients Market
Fertilizers
Potash Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
North America Fertilizers Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market