
 Quinoa Flour Market | 2026-2036
Quinoa Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Quinoa Flour Market Outlook
Asset-light contract milling and toll-processing arrangements is reconfiguring competitive entry barriers for mid-sized brands that lack capital for vertical milling infrastructure. Andean Naturals leverages direct farmer partnerships in Bolivia to sustain traceable organic supply chains. King Arthur Flour Company competes through premium positioning in specialty retail, while NorQuin anchors North American production with Canadian prairie sourcing. Bob's Red Mill Natural Foods differentiates via employee-owned governance and heritage brand equity in gluten-free channels.
Quinoa flour consists of finely milled seed meal from Chenopodium quinoa, typically containing 12-15% protein with a complete amino acid profile including lysine, and functions as a gluten-free structural agent in baked goods and extruded snacks. Organic quinoa flour commands premium shelf positioning as clean-label demand tightens ingredient provenance requirements, while conventional quinoa flour occupies mainstream food manufacturing where cost sensitivity dominates formulation decisions. Instant quinoa flour is gaining traction in ready-to-mix nutritional applications where hydration speed determines processing economics.
The USDA National Organic Program and EU Organic Regulation set cross-border compliance thresholds for pesticide residue and genetic integrity that filter which South American suppliers qualify for premium market access. Health Canada and FDA gluten-free labeling rules enforce the 20 ppm threshold that defines quinoa flour's celiac-safe positioning against wheat alternatives. Stakeholders must monitor how tightening Andean export quotas and evolving organic equivalency agreements reshape raw material availability before committing to long-term capacity expansion.
Market Dynamics
Quinoa flour supply chains face acute pressure from Andean export quota tightening and the USDA National Organic Program's residue threshold enforcement, which together filter which Bolivian and Peruvian suppliers retain premium market access.
Growth Catalysts
- Celiac-safe labeling alignment:FDA and Health Canada gluten-free thresholds at 20 ppm validate quinoa flour's structural role in bakery reformulations, expanding shelf space in North American retail channels.
- EU Novel Food regulatory clarity:Streamlined approval pathways for Andean grain derivatives accelerate import velocity into European food manufacturing.
- Instant flour hydration technology:Modified particle-size milling reduces water absorption time, unlocking ready-to-mix nutrition bars and beverage applications.
Market Restraints
- Andean supply concentration:Peru and Bolivia control upstream cultivation, exposing buyers to climate-induced yield volatility and export license delays.
- Organic certification cost burden:USDA National Organic Program compliance requires multi-year field conversion and residue testing that excludes smallholder cooperatives from premium tiers.
- Technical substitution by teff and sorghum:Alternative ancient grains with lower input costs and equivalent gluten-free positioning capture cost-sensitive formulation slots.
Strategic Opportunities
- Canadian prairie cultivation expansion:Saskatchewan and Alberta acreage under quinoa rotation is diversifying geographic supply beyond Andean dependence.
- Clean-label pet food crossover:Human-grade ingredient positioning opens specialty animal nutrition channels with margin premiums over conventional feed-grade flours.
- EU organic equivalency agreement expansion:Negotiated mutual recognition between EU Organic Regulation and Andean certification bodies reduces duplicate audit costs for exporters.
Industry Challenges
- Specialized milling technician scarcity:Quinoa saponin removal and tempering protocols require trained operators absent from standard grain processing labor pools.
- Legacy equipment retrofit costs:Wheat-dominant mills face capital outlays for segregated handling lines to prevent cross-contamination in gluten-free production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quinoa Flour Market |
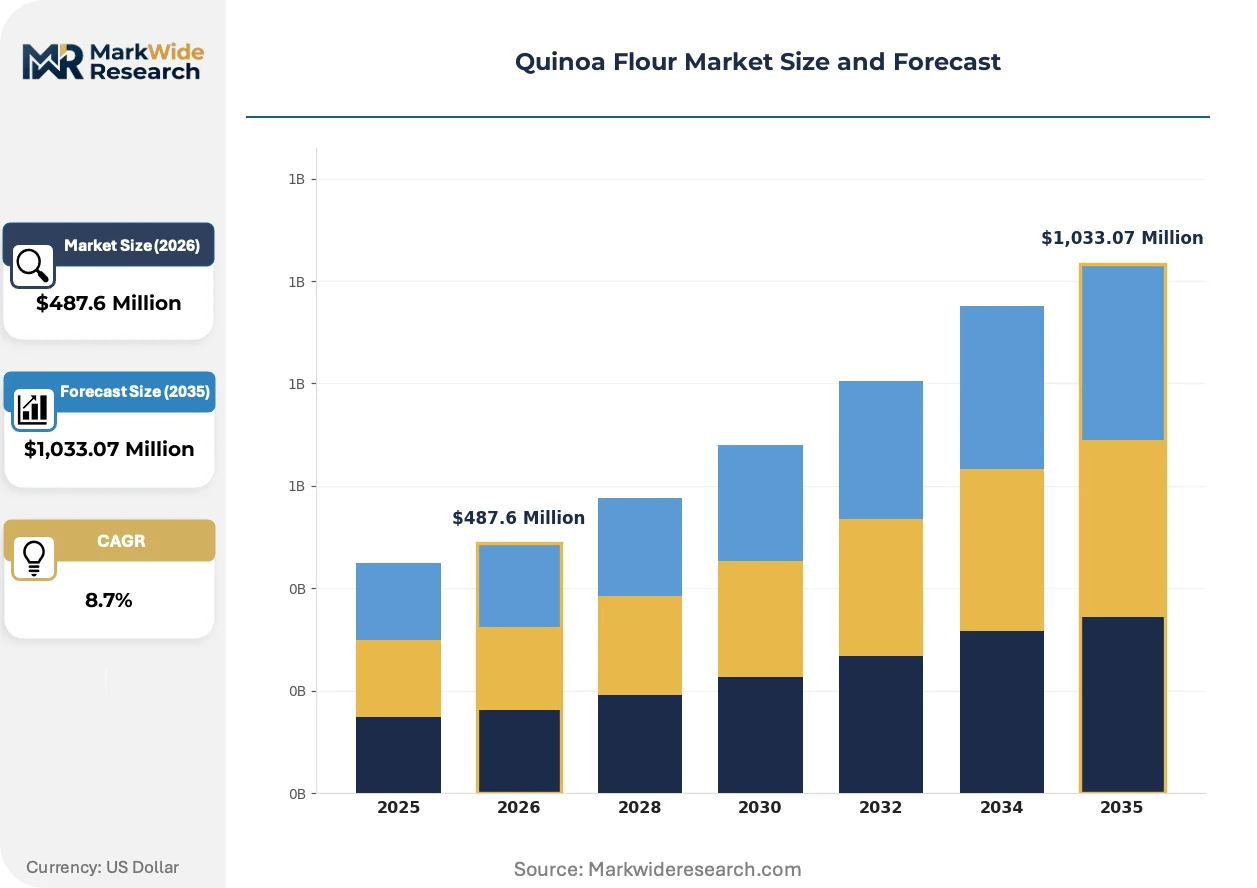
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Quinoa Flour, Conventional Quinoa Flour, Gluten-Free Quinoa Flour, Instant Quinoa Flour End Use: Baking, Food Processing, Snack Production, Nutritional Supplements Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Packaging Type: Bags, Bulk Containers, Pouches, Jars |
| Companies Covered | Grain Millers, Bob's Red Mill Natural Foods, Andean Naturals, General Mills, Avena Foods Limited, NorQuin, Andean Valley Corporation, King Arthur Flour Company, The British Quinoa Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quinoa Flour Market Strategic Shifts
Processing technology and certification protocols are converging to compress formulation timelines and tighten provenance verification, reshaping how quinoa flour moves from Andean fields to finished goods.
Modified atmospheric milling with nitrogen blanketing is hybridizing traditional stone-grinding with industrial roller systems, preserving heat-sensitive amino acids while achieving commercial throughput. Specialty bakeries and clean-label snack manufacturers are adopting these hybrid lines fastest, typically replacing legacy oat or rice flour infrastructure. The technology is hybridizing cost structures by narrowing the gap between artisan nutritional profiles and commodity-scale pricing.
EU F-Gas Regulation phase-down schedules are pressuring refrigeration-dependent storage and transport networks serving temperature-sensitive quinoa flour consignments. Cold-chain operators serving organic importers face equipment replacement cycles and refrigerant cost spikes that compress margins on South American cargo. European distributors are responding by shifting toward shorter sea-lanes and regional Canadian sourcing where feasible.
Direct-to-manufacturer contracting is displacing spot-market purchasing among mid-sized organic brands seeking multi-year supply security. This procurement consolidation concentrates volume commitments with fewer Bolivian cooperatives that can demonstrate traceability down to farm-plot level. The pattern is most pronounced in Pacific Northwest and Northeast US metropolitan clusters where clean-label food manufacturing density supports dedicated supply relationships.
Quinoa Flour Market Segmentation
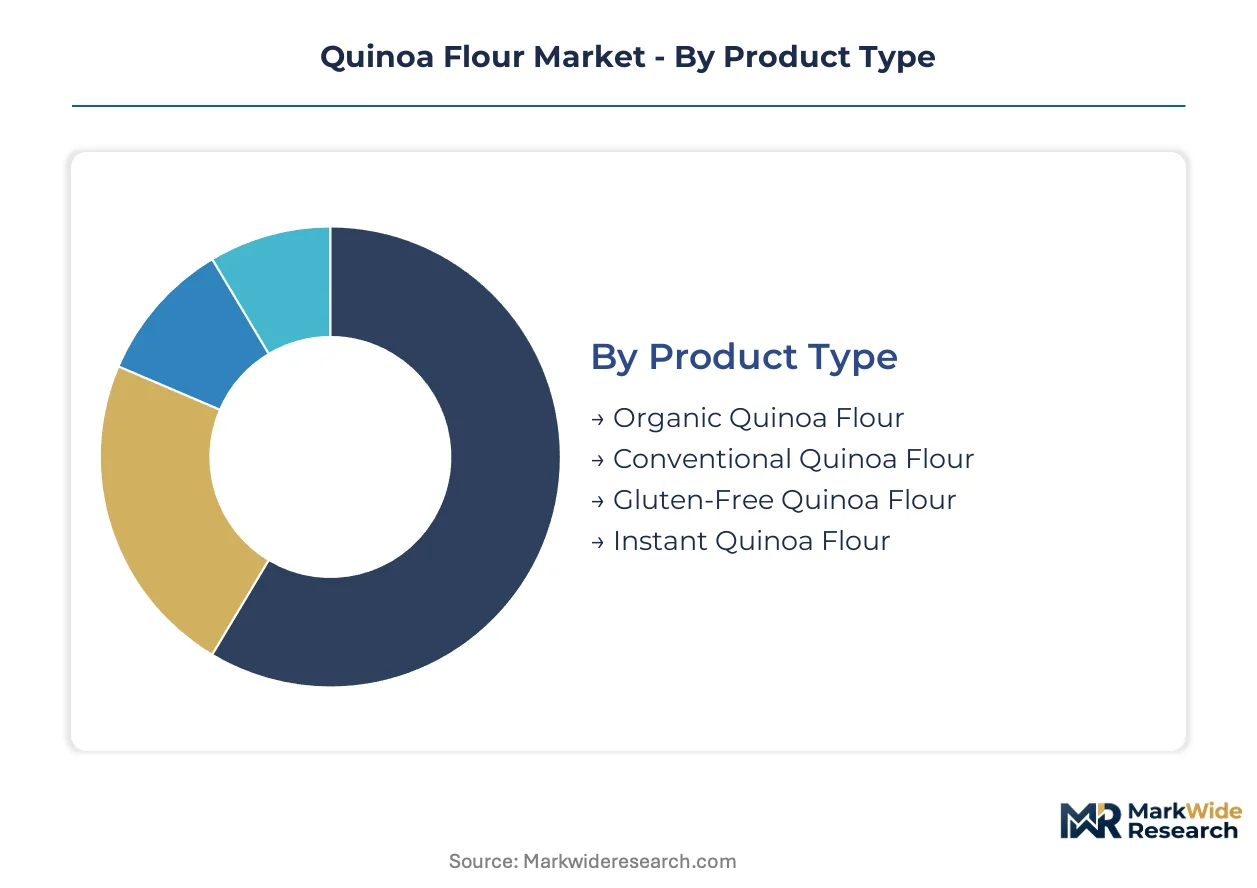
Quinoa flour segmentation reflects divergent supply chain economics across certification tiers, end-use functionality requirements, and channel-specific packaging protocols. Understanding these splits enables suppliers to align milling investments with margin structures and regulatory exposure.
Product Type:
Certification grade determines price positioning and geographic market access for quinoa flour suppliers competing across organic, conventional, and functional subcategories.
- Organic Quinoa Flour:Milled from USDA National Organic Program-certified grain with residue testing protocols and multi-year field conversion requirements. Premium shelf positioning in North American and European retail channels depends on equivalency agreements with Andean certification bodies.
- Conventional Quinoa Flour:Standard-milled product without organic certification occupies mainstream food manufacturing where cost sensitivity dominates formulation economics. Peruvian and Bolivian bulk exporters concentrate volume supply for this tier.
- Gluten-Free Quinoa Flour:Segregated processing under FDA and Health Canada 20 ppm thresholds validates celiac-safe labeling for bakery reformulations.
- Instant Quinoa Flour:Modified particle-size milling reduces hydration time for ready-to-mix nutrition bars and beverage applications.
Conventional quinoa flour commands the established base. The steepest expansion runs through instant quinoa flour.
End Use:
Application functionality shapes protein content specifications, particle size requirements, and saponin removal intensity across downstream industries.
- Baking:Structural agent in gluten-free bread, pastry, and cake formulations requiring complete amino acid profile with lysine content. North American specialty bakeries drive demand for fine-milled grades with consistent hydration behavior.
- Food Processing:Ingredient input for pasta, cereal, and extruded product manufacturing where bulk sourcing and standardized specifications predominate.
- Snack Production:Clean-label positioning supports premium chip, cracker, and bar applications targeting health-conscious consumers.
- Nutritional Supplements:High-protein concentrate applications in protein powders and meal replacement formulations.
Food processing absorbs the largest volume base. Nutritional supplements are climbing the fastest.
Distribution Channel:
Channel selection determines packaging format, margin capture, and traceability documentation requirements from mill to final purchaser.
- Online Retail:Direct-to-consumer platforms enable subscription models and specialty organic SKUs with detailed provenance storytelling.
- Supermarkets:Mass-market placement requires competitive unit economics and branded consumer recognition in gluten-free aisles.
- Health Food Stores:Independent retailers prioritize USDA Organic certification and local sourcing narratives.
- Specialty Stores:Gourmet and ethnic food retailers stock heritage varieties and single-origin Bolivian products.
Supermarkets anchor volume throughput. Online retail is gaining share fastest.
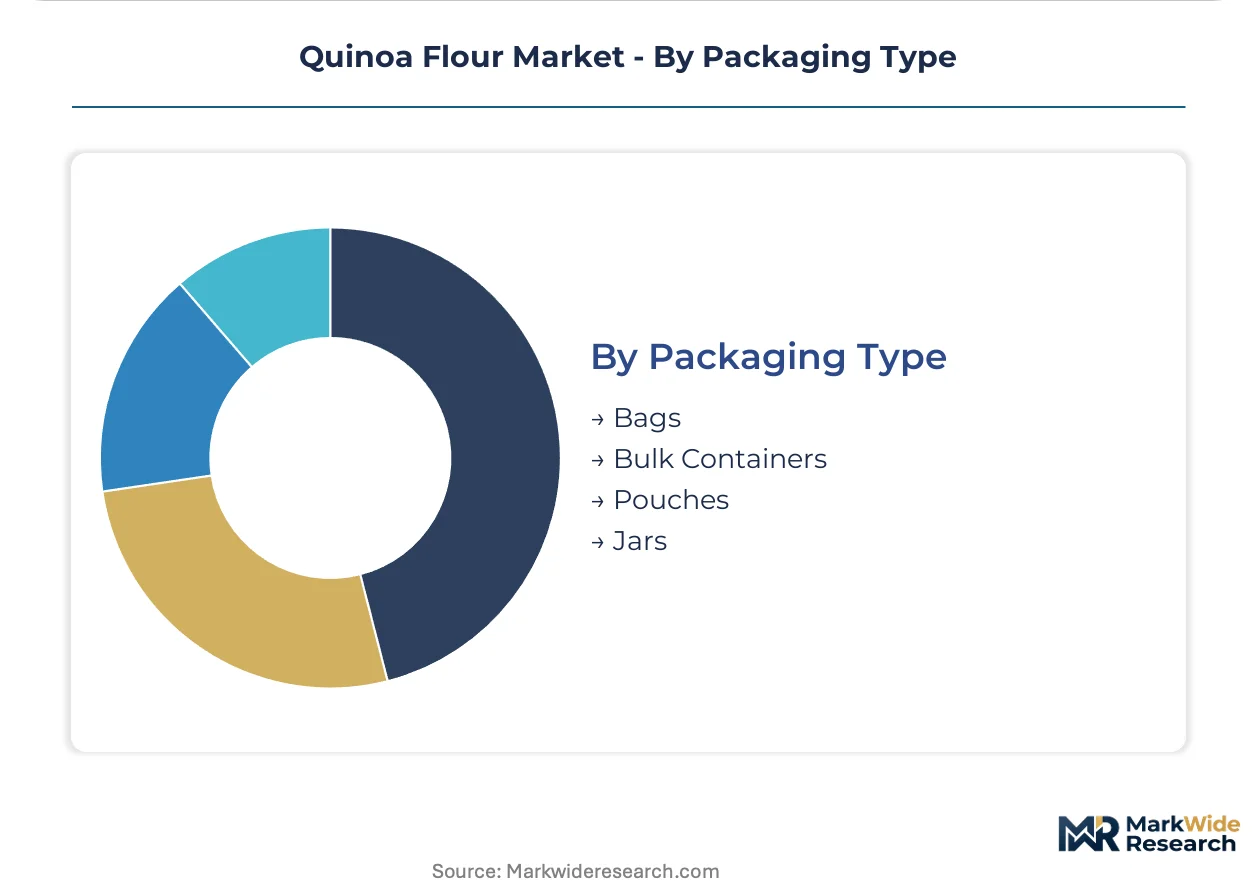
Packaging Type:
Packaging configuration aligns with channel economics, shelf-life requirements, and handling infrastructure from Andean export through final retail.
- Bags:Standard multi-layer paper or plastic sacks for food processing and bakery wholesale operations.
- Bulk Containers:Industrial totes and drums for large-scale manufacturing with minimal handling steps.
- Pouches:Stand-up flexible packaging dominates consumer-facing retail with resealability and shelf visibility.
- Jars:Glass or rigid plastic containers target premium positioning in specialty and gift markets.
Bags hold the volume base. Pouches show the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA National Organic Program equivalency agreements with Andean certification bodies determine which South American exporters retain premium market access. FDA and Health Canada gluten-free labeling rules at 20 ppm validate quinoa flour's structural positioning in North American retail channels. EU Novel Food regulatory clarity accelerates import velocity for Andean grain derivatives into European food manufacturing.
United States
Specialty bakeries in the Pacific Northwest and Northeast metropolitan clusters drive demand for fine-milled organic grades with consistent hydration behavior. FDA gluten-free labeling enforcement at 20 ppm validates celiac-safe positioning in mass-market retail channels. King Arthur Flour Company and Bob's Red Mill Natural Foods anchor premium distribution through employee-owned governance and heritage brand equity.
Canada
Health Canada gluten-free thresholds and organic equivalency protocols filter which Andean suppliers qualify for premium market entry. Saskatchewan and Alberta acreage under quinoa rotation diversifies geographic supply beyond Andean dependence. NorQuin anchors North American production with Canadian prairie sourcing and segregated gluten-free processing infrastructure.
Germany
EU Organic Regulation residue thresholds and Novel Food approval pathways shape import velocity from Bolivian and Peruvian exporters. ECHA chemical safety protocols and REACH compliance requirements influence packaging material selection for temperature-sensitive consignments. Berlin and Hamburg distribution clusters handle bulk consolidation for Central European food manufacturing.
United Kingdom
Post-Brexit organic equivalency negotiations with Andean certification bodies determine premium tier access for Bolivian cooperatives. The British Quinoa Company represents domestic cultivation experimentation in Cambridgeshire and East Anglia. London specialty retail channels prioritize single-origin provenance storytelling and heritage variety differentiation.
Peru
Export quota tightening and climate-induced yield volatility in the Andean highlands expose buyers to supply interruption risks. Ministry of Agriculture and Irrigation oversight governs organic field conversion protocols and residue testing requirements. Puno and Cusco cultivation zones concentrate upstream quinoa production for international flour milling.
Quinoa Flour Market Competitive Environment
On the supply side, the industry is bifurcated between vertically integrated Andean upstream operators and asset-light North American toll-processors. Tiered competitive positioning separates heritage specialty brands from commodity-scale millers serving food manufacturing. Three archetypes dominate: direct farmer partnership models, premium retail heritage brands, and contract milling specialists. Capacity expansion in Canadian prairie cultivation and M&A consolidation among mid-sized organic brands represent the dominant competitive moves.
Within the direct partnership archetype, Andean Naturals exemplifies traceable organic supply chain architecture through Bolivian farmer relationships. King Arthur Flour Company and Bob's Red Mill Natural Foods occupy positions in the premium heritage tier, leveraging employee-owned governance and specialty retail positioning. NorQuin anchors the geographic diversification vector with Canadian prairie sourcing that reduces Andean supply concentration exposure.
| Leading Market Players |
|---|
| Grain Millers |
| Bob's Red Mill Natural Foods |
| Andean Naturals |
| General Mills |
| Avena Foods Limited |
| NorQuin |
| Andean Valley Corporation |
| King Arthur Flour Company |
| The British Quinoa Company |
| Others |
Value Chain & Pricing Dynamics
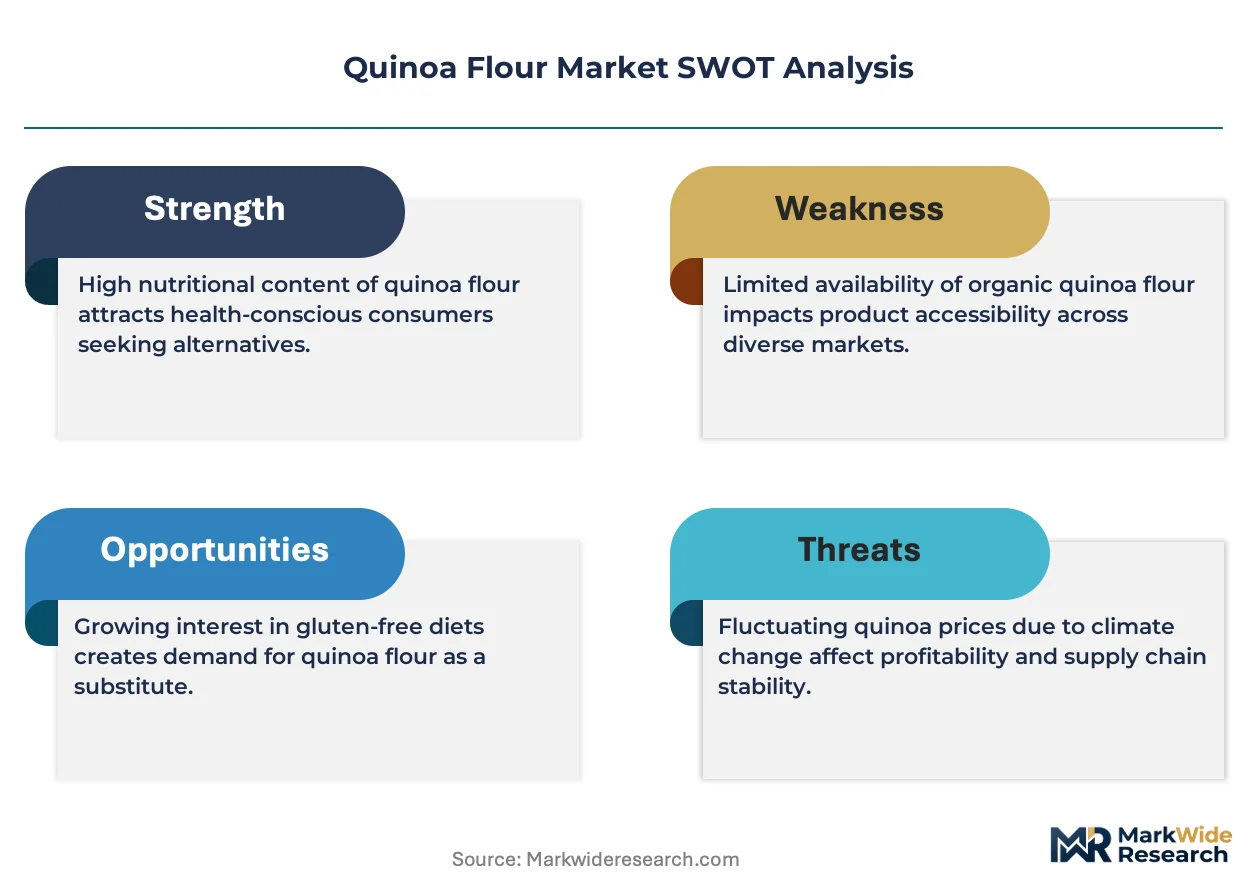
Andean export quota tightening determines both pricing tier spreads and supply chain shape, compressing margins on conventional flour while amplifying premiums for traceable organic grades that bypass quota-constrained channels.
Pricing Analysis
Certification level creates the primary spread between organic and conventional quinoa flour tiers. USDA National Organic Program compliance commands premium positioning in North American retail, while conventional product serves cost-sensitive food manufacturing. Pricing pressure stems from teff and sorghum substitution in gluten-free formulations, eroding share in budget bakery segments. Food processing buyers exhibit highest price sensitivity; specialty health food channels absorb premiums with minimal volume elasticity.
Supply Chain Analysis
Export license delays under Peru's Ministry of Agriculture and Irrigation regime restrict flow velocity for non-preferred suppliers. Raw material sourcing draws from Puno and Cusco cultivation zones in Peru, plus Oruro and Potosí regions in Bolivia. Single-source vulnerability concentrates in Andean highland production, where climate-induced yield volatility interrupts scheduled milling runs. Distribution runs through Pacific Northwest and Northeast US metropolitan consolidation hubs serving clean-label manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized milling technician scarcity constrains capacity expansion, as quinoa saponin removal and tempering protocols demand trained operators absent from standard grain processing labor pools.
For Market Incumbents: Pre-empt teff and sorghum encroachment by securing multi-year organic supply contracts with Bolivian cooperatives demonstrating farm-plot traceability. Invest in nitrogen-blanketed milling infrastructure to preserve heat-sensitive amino acids and justify premium positioning against commodity-scale competitors. For New Entrants and Emerging Players: Pursue Canadian prairie sourcing partnerships in Saskatchewan and Alberta to bypass Andean quota exposure and establish segregated gluten-free processing lines. Target ready-to-mix nutrition bar manufacturers with instant quinoa flour formulations where hydration speed determines procurement decisions. For Investors and Strategic Acquirers: EU organic equivalency agreement expansion reshapes the acquisition landscape, reducing duplicate audit costs for Andean exporters and improving margin structures on premium-tier volume. Focus on mid-sized organic brands with direct farmer partnership architectures. Watch for Andean export quota relaxation as the signal indicating supply constraint easing and valuation multiple compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Andean Cultivation | Direct farmer partnerships in Bolivia secure traceable organic supply chains against quota volatility. |
| Canadian Prairie Capacity Expansion | Saskatchewan and Alberta acreage diversification reduces geographic supply concentration risk. |
| Nitrogen-Blanketed Milling Infrastructure | Modified atmospheric processing preserves amino acid profiles for premium nutritional applications. |
| EU Organic Equivalency Certification | Mutual recognition agreements eliminate duplicate audit costs for European market access. |
| Instant Flour Technology Licensing | Particle-size modification unlocks ready-to-mix nutrition bar and beverage formulation slots. |
Study Parameters
The analysis maps organic certification tiers, instant flour technology adoption, and gluten-free processing infrastructure, each validated through primary interviews with quinoa mill operators, organic certification auditors, specialty bakery procurement managers, and Andean cooperative export directors. Secondary validation draws from USDA National Organic Program equivalency filings, EU Novel Food approval registries, Health Canada gluten-free labeling guidance, and customs trade data on Andean grain shipments. Bottom-up volume estimates from milling capacity and top-down demand segmentation from end-use consumption patterns undergo cross-triangulation for convergence.
Assumptions held fixed include current USDA-EU organic equivalency protocols, FDA 20 ppm gluten-free thresholds, and Andean export licensing procedures; variables tested include Canadian prairie acreage expansion rates and instant flour technology penetration curves. Segmentation dimensions span certification grade, end-use application, particle-size specification, and regional sourcing origin. CAGRs derive from fitted growth curves against historical volume trajectories, with inputs including quinoa rotation yields, saponin removal efficiency rates, and specialty retail shelf-space allocation trends.
Macroeconomic conditions sit as an overlay; deviation in freight rates, organic grain commodity indices, or clean-label consumer expenditure would shift the trajectory. Forecasts reflect documented assumptions on regulatory stability and climate yield patterns. Material shifts in Andean export quota policy or EU Novel Food approval timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Grain Mill Products Market
Grains
Europe Wheat Market
Grains
Global Maize Market
Grains
Precooked Flour Market
Grains
Global Wheat Market
Grains
Asia-Pacific Guar Market
Grains
Wheat Bran Market
Grains
United States Rice Market
Grains
Grain Bins Market
Grains
Bangladesh Rice Market
Grains
Oat Flour Market
Grains
Cameroon Grains Market
Grains
Global Cassava Flour Market
Grains
Gluten Free Ancient Grain Market
Grains
Cornmeal Market
Grains
Green Pea Grits Market