
 Grain Bins Market | 2026-2036
Grain Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Bins Market Foresight
North American capacity expansion is rewriting competitive dynamics across grain storage manufacturing. AGCO Corporation leverages its GSI brand infrastructure to dominate large-scale commercial installations across the Corn Belt. Sukup Manufacturing anchors its position through deep vertical integration into galvanized steel fabrication, controlling cost structures that competitors struggle to match. AGI extends its reach through a diversified portfolio spanning handling equipment alongside storage, reducing customer procurement complexity.
Grain bins are cylindrical steel structures engineered to store bulk agricultural commodities, typically fabricated from corrugated galvanized steel sheets with aeration floors and temperature monitoring systems to preserve grain quality. These installations protect harvested crops from moisture, pests, and spoilage while enabling extended holding periods for price optimization. Steel bins command the largest installed base due to durability and structural load capacity, though hopper bins capture disproportionate growth in on-farm applications where unloading efficiency reduces labor requirements. Commercial storage applications generate the highest revenue per unit through custom-engineered configurations, while small-scale capacity segments face margin compression from commoditized regional competition.
The USDA's Grain Inspection, Packers and Stockyards Administration enforces structural integrity standards that elevate engineering requirements for commercial facilities. OSHA's grain handling facility standards mandate specific anchoring, access, and ventilation configurations that shape product design across domestic manufacturers. Stakeholders must monitor evolving EPA air quality regulations around grain dust emissions, as compliance investments could redirect capital from capacity expansion toward environmental controls.
Market Dynamics
Commercial grain elevators are consolidating purchasing power across the U.S. Corn Belt, forcing manufacturers to engineer larger-diameter bins with automated aeration controls that reduce post-harvest losses. This buyer concentration is compressing margins for standardized capacity while rewarding suppliers capable of turnkey installation and remote monitoring integration.
Growth Catalysts
- USDA structural integrity mandates:Elevated engineering requirements for commercial facilities are accelerating replacement cycles among aging on-farm storage infrastructure.
- IoT-enabled grain monitoring:Wireless temperature and moisture sensors embedded in bin floors are reducing spoilage losses and extending profitable holding periods for commodity price arbitrage.
- Nebraska-to-Iowa production corridor:Corn and soybean density in this cluster sustains continuous demand for expanded commercial elevator capacity and on-farm replacement bins.
Market Restraints
- Galvanized steel price volatility:Hot-rolled coil cost fluctuations compress fabrication margins and destabilize project quoting for large-diameter commercial installations.
- Domestic steel mill concentration:Reliance on a limited number of North American galvanized coil suppliers creates delivery timeline risk during peak agricultural construction seasons.
- Concrete silo substitution:Permanent concrete grain storage retains preference among certain cooperative elevators for fire resistance and structural longevity in high-value applications.
Strategic Opportunities
- EPA grain dust emission standards:Pending air quality regulations will mandate upgraded filtration and containment systems, creating retrofit and new-build specification advantages for compliant manufacturers.
- Drone-based exterior inspection:Automated structural assessment services bundled with bin sales are opening recurring revenue streams beyond one-time equipment transactions.
- Kansas wheat belt expansion:Underpenetrated commercial storage capacity in western Kansas and eastern Colorado offers geographic diversification from Corn Belt saturation.
Industry Challenges
- Welding technician scarcity:Certified structural steel fabricators command premium wages, constraining production scaling during compressed spring installation windows.
- OSHA confined space compliance:Grain bin entry safety certification requirements extend project timelines and inflate labor costs for maintenance-access system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Bins Market |
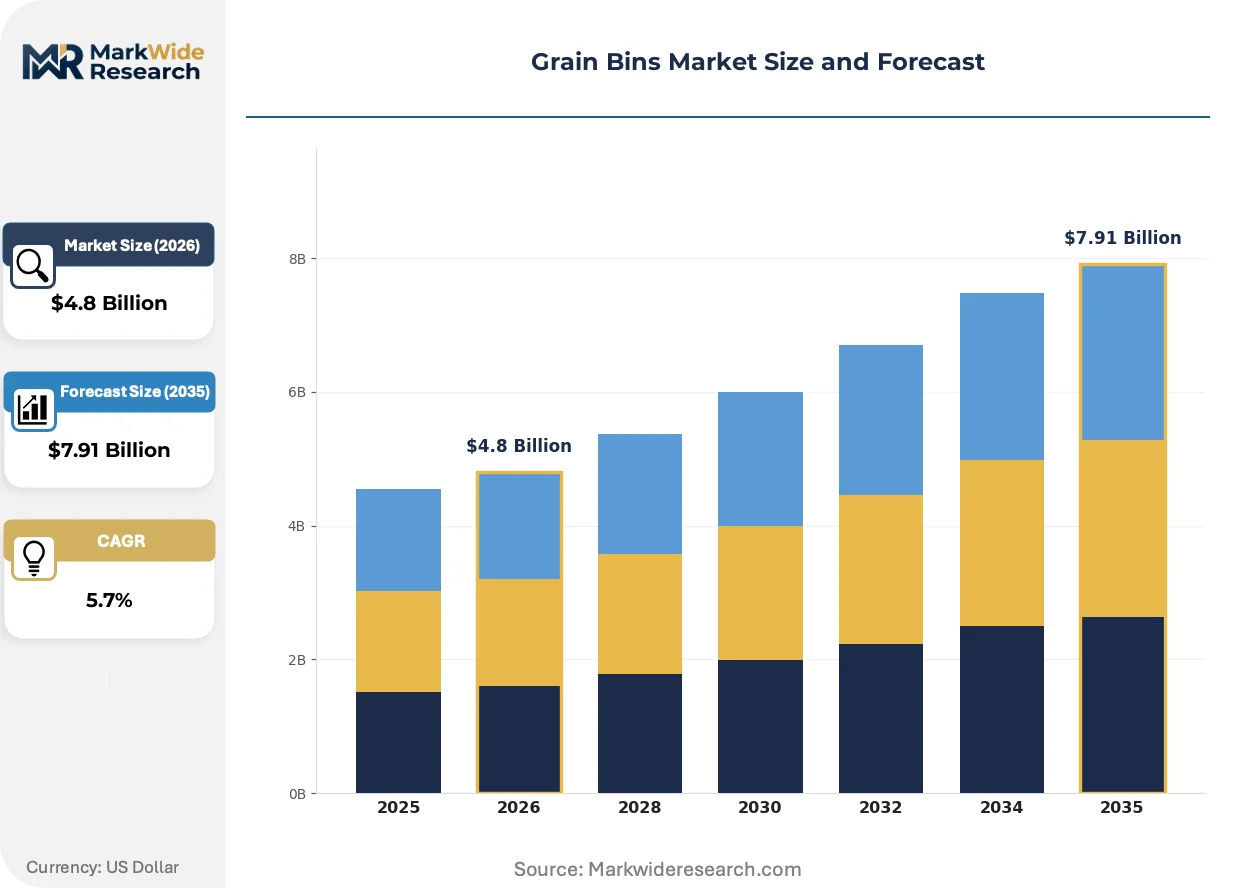
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Bins, Corrugated Bins, Smooth Wall Bins, Hopper Bins Application: Agricultural Storage, Commercial Storage, On-Farm Storage, Feed Storage Capacity: Small Scale, Medium Scale, Large Scale, Custom Capacity Distribution Channel: Direct Sales, Retailers, Online Sales, Distributors |
| Companies Covered | AGCO Corporation, AGI, Sukup Manufacturing, Westman Group, Behlen, SCAFCO Grain Systems, CTB, Superior Grain Equipment, Sioux Steel Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Bins Market Shifts & Advancements
Digital infrastructure is penetrating grain storage faster than physical capacity expansion, with sensor networks and predictive analytics commanding R&D investment priority over incremental steel gauge improvements. This shift is redefining supplier value propositions from cubic-foot sellers to grain-quality guarantors.
Remote bin monitoring platforms are virtualizing the traditional role of on-site grain managers. These systems aggregate temperature, moisture, and carbon dioxide readings into centralized dashboards accessible via cellular networks. Large commercial elevators in Illinois and Indiana are adopting these platforms fastest, compressing labor requirements while enabling precise aeration scheduling that cuts energy costs and spoilage risk simultaneously.
OSHA's updated grain handling facility standards are mandating enhanced anchor bolt configurations and reinforced access platforms for structures exceeding certain capacity thresholds. Manufacturers serving commercial elevator clients must now engineer custom foundation interfaces that satisfy these structural load requirements. The compliance burden falls heaviest on retrofit projects, where legacy bin footprints constrain redesign options and inflate engineering hours.
Integrated service contracts are displacing equipment-only transactions across the commercial segment. Buyers now expect suppliers to assume responsibility for installation, commissioning, and multi-year maintenance scheduling within single-source agreements. This bundling trend is most pronounced among regional grain cooperatives in Minnesota and Wisconsin, where capital constraints favor operational expenditure models over upfront equipment purchases.
Grain Bins Market Segmentation
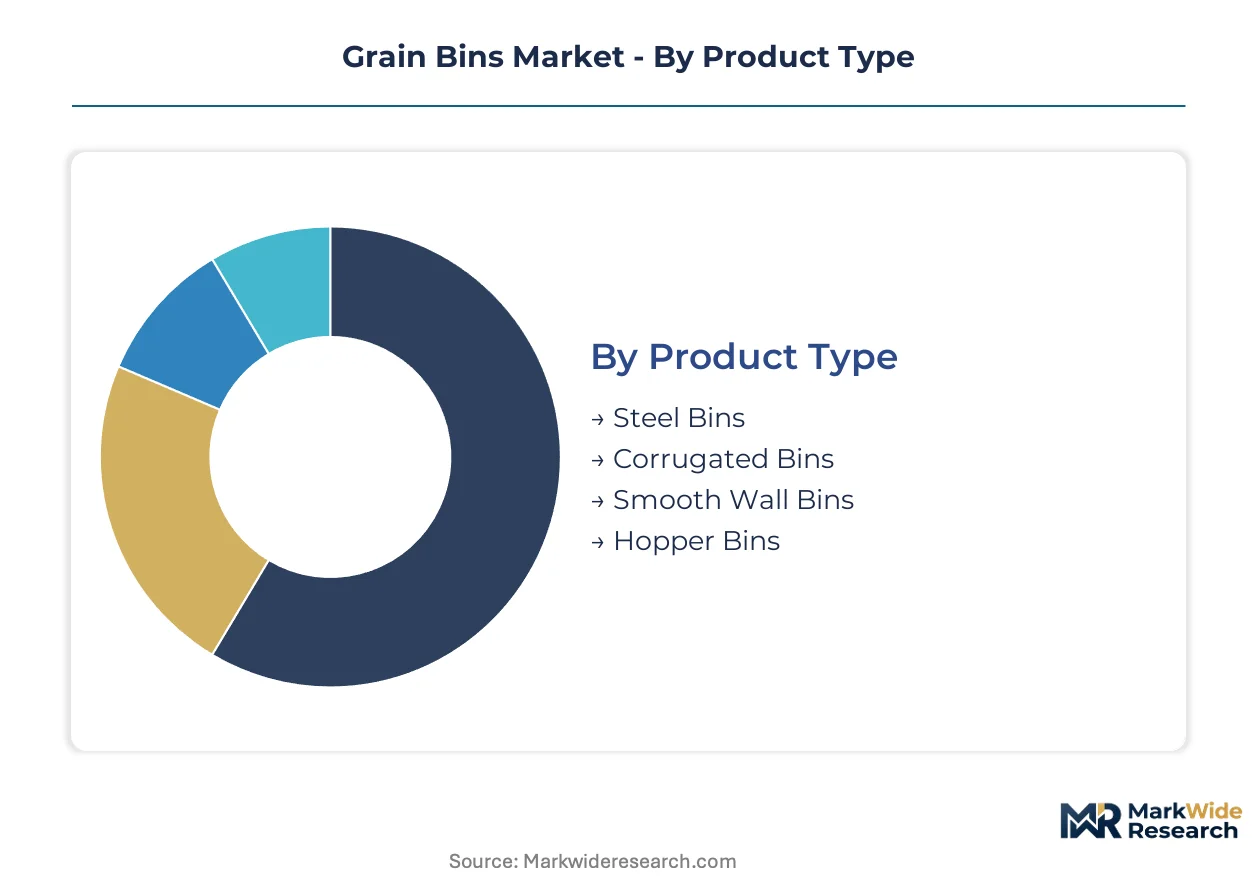
Grain bin manufacturers engineer distinct product configurations to match divergent holding requirements across commodity types and operational scales. Segmentation in this market reflects the tension between standardized fabrication economies and site-specific structural demands.
Product Type:
Cost tier differentiation separates commodity-grade fabrication from engineered premium structures.
- Steel Bins:Fabricated from corrugated galvanized steel sheets with bolted panel construction, these structures dominate commercial elevator installations. Corn Belt grain handlers specify steel bins for load-bearing capacity exceeding 500,000 bushels. USDA structural integrity mandates accelerate replacement of aging welded-steel infrastructure.
- Hopper Bins:Conical-bottom designs enable gravity discharge without auger assistance, reducing labor for on-farm operations. Iowa and Illinois soybean producers specify hopper configurations under 10,000 bushels for rapid truck loading during harvest windows. OSHA confined space compliance adds cost to access system integration.
- Corrugated Bins:Standardized panel rolling delivers cost-efficient capacity for cooperative storage expansion.
- Smooth Wall Bins:Seamless interior surfaces reduce grain hang-up for specialty seed and food-grade applications.
Steel Bins holds installed capacity. Hopper Bins is rotating up the share rankings.
Application:
Customer type concentration determines specification complexity and service bundling requirements.
- Commercial Storage:Custom-engineered configurations serve grain elevator consolidation across the Nebraska-to-Iowa corridor. Automated aeration controls and remote monitoring integration command premium pricing. EPA grain dust emission standards mandate upgraded filtration for new builds.
- On-Farm Storage:Smaller-diameter bins with basic temperature monitoring preserve harvest quality for price arbitrage. Kansas wheat belt expansion drives demand for standalone installations beyond Corn Belt saturation.
- Agricultural Storage:General-purpose designs accommodate multi-commodity rotation across growing seasons.
- Feed Storage:Dairy and livestock operations specify moisture-resistant configurations for ration preservation.
Commercial Storage commands revenue per unit. On-Farm Storage is gaining share fastest.
Capacity:
Volume segmentation aligns with capital availability and land constraints across buyer types.
- Large Scale:Diameters exceeding 105 feet serve regional elevator consolidation, requiring custom foundation engineering. Commercial buyers in Minnesota and Wisconsin favor integrated service contracts over equipment-only transactions. Welding technician scarcity constrains production scaling during compressed construction seasons.
- Custom Capacity:Site-specific engineering addresses irregular topography and existing infrastructure retrofit constraints. Legacy bin footprints limit redesign options for OSHA-compliant anchor configurations.
- Medium Scale:Standardized dimensions balance fabrication efficiency with operational flexibility.
- Small Scale:Commoditized regional competition compresses margins for sub-5,000 bushel configurations.
Large Scale dominates capital deployment. Custom Capacity is climbing the fastest.
Distribution Channel:
Supply concentration shapes procurement patterns and margin capture across the value chain.
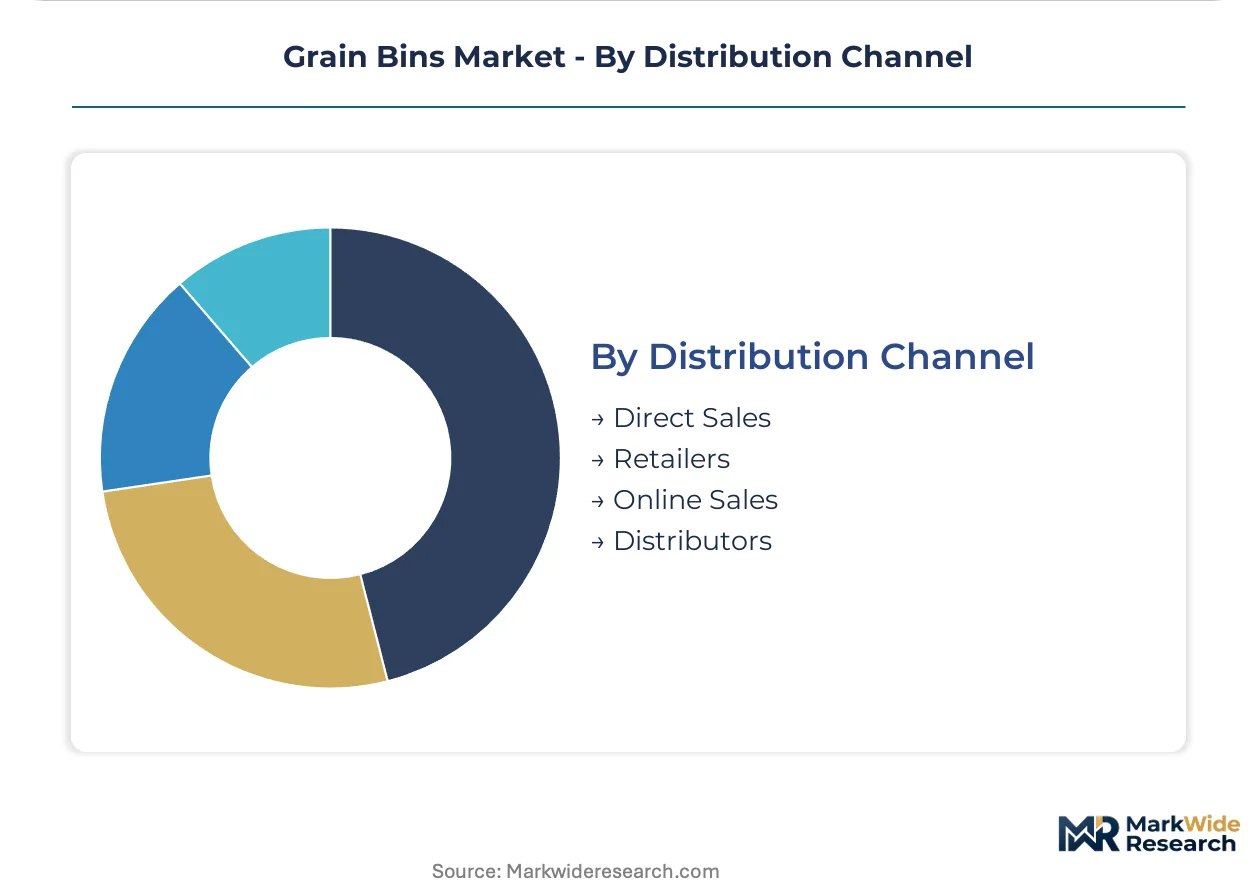
- Direct Sales:Manufacturer-employed engineers specify foundation interfaces and aeration systems for turnkey commercial installations. AGCO Corporation and Sukup Manufacturing leverage direct relationships to control project quoting during volatile steel price cycles.
- Distributors:Regional inventory positioning reduces delivery timeline risk from domestic steel mill concentration.
- Retailers:Farm supply cooperatives serve replacement demand for standardized small-scale capacity.
- Online Sales:Digital quoting platforms penetrate accessory and component segments.
Direct Sales captures specification control. Distributors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA structural integrity mandates anchor North American demand, with specific regulatory pressures varying sharply across national agricultural frameworks. Corn belt density and wheat belt expansion create divergent storage investment patterns.
United States
Corn and soybean production density across Iowa, Illinois, and Nebraska sustains continuous bin replacement cycles. OSHA grain handling facility standards mandate reinforced anchor bolt configurations for commercial elevators exceeding capacity thresholds. The Nebraska-to-Iowa corridor concentrates automated aeration control adoption among regional cooperatives.
Canada
Prairie province wheat and canola handlers drive demand for cold-weather structural specifications. Health Canada and PMRA coordinate grain quality preservation standards that elevate temperature monitoring requirements. Manitoba and Saskatchewan elevator consolidation accelerates large-diameter installation contracts.
Brazil
Soybean export corridor expansion through Mato Grosso and Goiás strains existing storage infrastructure. ANVISA food safety protocols intersect with agricultural ministry grain quality regulations. The Sorriso-Sinop cluster in northern Mato Grosso exhibits fastest commercial elevator capacity addition.
Argentina
Pampas region corn and wheat production requires seasonal surge storage for export timing optimization. The national agricultural technology institute enforces moisture control standards for commercial facilities. Rosario port-zone elevators command premium engineering for high-throughput configurations.
Australia
Wheat belt harvest concentration across Western Australia and New South Wales creates seasonal storage bottlenecks. TGA and state agricultural departments coordinate fumigation and residue standards for export compliance. The Esperance-Albany corridor drives remote monitoring adoption for isolated site management.
Grain Bins Market Competitive Landscape
Capability concentration sits with vertically integrated fabricators; scale advantage sits with diversified agricultural equipment conglomerates. The vendor base organizes around three strategic archetypes: steel-rolling specialists controlling input costs, full-line agricultural equipment suppliers leveraging distribution infrastructure, and regional fabrication shops serving replacement demand. Dominant competitive moves include backward integration into galvanized coil supply and geographic expansion through distributor network acquisition.
Within the steel-integrated tier, Sukup Manufacturing exemplifies cost-structure control through captive galvanizing capacity. AGCO Corporation anchors the diversified equipment constellation, leveraging GSI brand infrastructure across commercial installation channels. AGI occupies a position spanning handling equipment and storage, reducing procurement complexity for elevator operators seeking single-source relationships.
| Leading Market Players |
|---|
| AGCO Corporation |
| AGI |
| Sukup Manufacturing |
| Westman Group |
| Behlen |
| SCAFCO Grain Systems |
| CTB |
| Superior Grain Equipment |
| Sioux Steel Company |
| Others |
Supply & Pricing Matrix
Galvanized steel coil price volatility determines both the spread between premium custom-engineered bins and commoditized small-scale capacity, and the geographic clustering of fabrication capacity around North American steel mill locations. Hot-rolled coil cost fluctuations compress margins for standardized corrugated bins while rewarding suppliers with captive galvanizing operations that buffer input spikes.
Pricing Analysis
Midwest commercial elevator operators pay premium rates for large-diameter installations compared to Plains-state on-farm buyers, reflecting project complexity and foundation engineering requirements. Three-tier pricing structure across premium, standard, and economy levels separates custom-engineered commercial configurations from standardized cooperative storage and commoditized sub-5,000 bushel farm bins. Price differentiation rests on automation integration and remote monitoring bundling versus basic temperature monitoring. Cost compression in small-scale segments is intensifying because regional fabricators compete on delivery speed during compressed spring windows. Cooperative buyers exhibit highest price sensitivity due to capital constraints favoring operational expenditure models.
Supply Chain Analysis
Hot-dip galvanized steel coil feeds from domestic mills concentrated in Indiana, Ohio, and Pennsylvania, with limited secondary sourcing alternatives during peak agricultural construction seasons. Corrugated panel rolling, bolted connection hardware, and aeration floor systems constitute the three critical component streams. Single-source vulnerability runs through the concentrated North American galvanized coil supplier base, creating delivery timeline risk when harvest-driven demand surges. Distribution runs through manufacturer-employed engineers for commercial turnkey installations, regional distributors for inventory positioning, and farm supply cooperatives for replacement small-capacity demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT-enabled grain monitoring systems are accelerating competitive disruption as buyers shift procurement criteria from cubic-foot capacity to grain-quality guarantee contracts. This technological inflection compresses margins for equipment-only suppliers while rewarding integrated service providers.
For Market Incumbents: Entrench position through backward integration into galvanized steel coil supply and captive sensor manufacturing to control cost structures that emerging competitors cannot replicate. Expand large-diameter engineering capacity in the Nebraska-to-Iowa corridor where commercial elevator consolidation concentrates demand. Defend against concrete silo substitution threat by emphasizing faster installation timelines and remote monitoring integration that permanent structures cannot match.
For New Entrants and Emerging Players: Pursue underpenetrated commercial storage capacity in western Kansas and eastern Colorado wheat belt expansion zones where Corn Belt incumbents maintain weaker distributor relationships. Target drone-based exterior inspection services as a recurring revenue wedge that bypasses capital-intensive fabrication requirements. Lead with bundled maintenance contracts that convert capital-constrained regional cooperatives from equipment purchasers to operational expenditure clients.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fabricators with captive galvanizing capacity and established commercial elevator relationships. Long-term viability hinges on sensor network integration capabilities and service contract recurring revenue streams rather than pure equipment manufacturing scale. Acquisition target archetype: mid-cap regional fabricators with strong Plains-state distributor networks and underdeveloped digital service offerings. Watch EPA grain dust emission standard finalization timing as the signal for compliance-driven retrofit demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanized Coil Supply | Captive steel supply insulates margin structures from hot-rolled coil price volatility during peak construction seasons. |
| Remote Monitoring Platform Development | Sensor network integration transforms supplier relationships from equipment transactions to grain-quality guarantee contracts. |
| Drone-Based Inspection Service Launch | Automated structural assessment opens recurring revenue streams beyond one-time bin sales for commercial elevator clients. |
| Geographic Expansion through Distributor Acquisition | Control over Kansas and Colorado distribution networks captures wheat belt capacity expansion away from Corn Belt saturation. |
| EPA Compliance Filtration System Integration | Pending emission standards create specification advantages for manufacturers with pre-certified containment engineering. |
Research Methodology
Desk research of USDA grain handling facility standards, OSHA confined space regulations, and domestic steel trade data preceded structured interviews with grain elevator operations managers, agricultural cooperative procurement directors, structural steel fabrication plant managers, and IoT sensor platform developers. Secondary validation drew from SEC filings of diversified agricultural equipment manufacturers, American Iron and Steel Institute production statistics, and EPA regulatory dockets. Bottom-up capacity installation tracking and top-down agricultural commodity storage demand modeling were triangulated against regional construction permit databases.
Assumptions held fixed include current USDA structural integrity mandate enforcement intensity and prevailing galvanized steel coil supply concentration; variables tested include EPA grain dust emission standard timing and IoT sensor adoption curves across commercial versus on-farm segments. The analytical framework segmented by product type, application, capacity tier, and distribution channel across the projection horizon. CAGRs were derived from installation volume trends correlated with corn and soybean production density maps. Forecast inputs incorporated welding technician labor market constraints and compressed spring installation window duration.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price cycles, interest rate environments affecting cooperative capital expenditure, or galvanized steel tariff structures would shift the trajectory. Cross-checking against USDA National Agricultural Statistics Service grain storage capacity surveys and state-level construction permit filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Oats Market
Grains
Wheat Flour Market
Grains
Argentina Grains Market
Grains
Durum Wheat Flour Market
Grains
Heritage Grain Market
Grains
Non-Basmati Rice Market
Grains
North America Maize Market
Grains
Green Banana Flour Market
Grains
Spelt Wheat Market
Grains
Cultured Wheat Market
Grains
Lentil Market
Grains
00 Flour Market
Grains
Gluten Free Ancient Grain Market
Grains
Global Maize Market
Grains
Asia-Pacific Wheat Market
Grains
United States Maize Market