
 Global Seed Colorant Market | 2026-2036
Global Seed Colorant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seed Colorant Market Foresight
Buyer concentration among multinational seed producers is restructuring procurement dynamics for colorant suppliers. BASF SE leverages its integrated crop science portfolio to bundle colorants with seed treatment packages. Sensient Technologies Corporation anchors North American supply through specialized pigment manufacturing. Clariant AG competes on REACH-compliant water-based formulations for European seed houses.
Seed colorants are surface-applied pigments and dyes, typically iron oxide or organic azo compounds at 0.5-2% loading by seed weight, that enable visual differentiation, treated-seed identification, and brand recognition in commercial agriculture. Water-based formulations lead volume due to environmental compliance advantages, while UV-curable coatings represent the fastest-expanding segment as precision seed treatment lines adopt inline curing for throughput gains. Oil-based systems retain margin pools in tropical markets where humidity tolerance determines performance.
EPA registration under FIFRA governs colorant co-formulation with crop protection actives in the United States, while REACH and the EU Green Deal restrict certain heavy-metal pigments across European seed supply chains. Brazil's national agricultural regulator, MAPA, enforces treated-seed labeling standards that directly specify approved colorant chemistries. Stakeholders must monitor evolving polymer-binding requirements that link colorant adhesion performance to treatment equipment warranties.
Market Dynamics
Seed treatment equipment warranties now tie directly to polymer-binding performance specifications, forcing colorant suppliers to co-develop formulations with machinery OEMs rather than sell standalone pigments.
Growth Catalysts
- EPA FIFRA Registration Pathways:Streamlined co-formulation approvals for colorants bundled with crop protection actives accelerate commercialization timelines for US seed houses.
- Hybrid Seed Corridors:India's expanding hybrid rice and maize programs generate concentrated demand for visual differentiation systems in commercial multiplication fields.
- Inline UV-Curing Systems:Precision seed treatment lines adopt instant-cure coating technology, pulling compatible colorant formulations into new equipment specifications.
Market Restraints
- Iron Oxide Supply Concentration:Pigment feedstock sourcing clusters in Chinese metallurgical processing regions, exposing formulators to geopolitical supply disruptions.
- REACH Heavy-Metal Restrictions:ECHA substance evaluations phase out legacy chromate pigments, forcing European seed houses to absorb reformulation costs and performance trade-offs.
- Humidity-Tolerant Oil-Based Systems:Tropical agriculture's reliance on solvent-borne coatings conflicts with tightening volatile organic compound ceilings in major formulation hubs.
Strategic Opportunities
- MAPA Labeling Standards in Brazil:Mandatory treated-seed color specifications create captive demand for approved chemistries in the world's largest soybean seed market.
- EU Green Deal Biopolymer Mandates:Binding requirements for bio-based seed coatings open formulation partnerships between colorant suppliers and starch-derived polymer developers.
- Direct-to-Farm Digital Channels:Precision agriculture platforms enable colorant suppliers to bypass distributor markups and capture margin in identity-preserved specialty seed segments.
Industry Challenges
- Polymer-Binding Expertise Gap:Formulation chemistry talent shortages delay R&D pipelines for adhesion-optimized colorant systems compatible with high-speed treaters.
- Multi-Jurisdiction Registration Timelines:Synchronized EPA, REACH, and MAPA approval processes extend time-to-revenue for novel pigment chemistries to 36-48 months.
- Legacy Equipment Compatibility:Existing seed treatment infrastructure in developing markets requires backward-compatible water-based formulations that sacrifice performance margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seed Colorant Market |
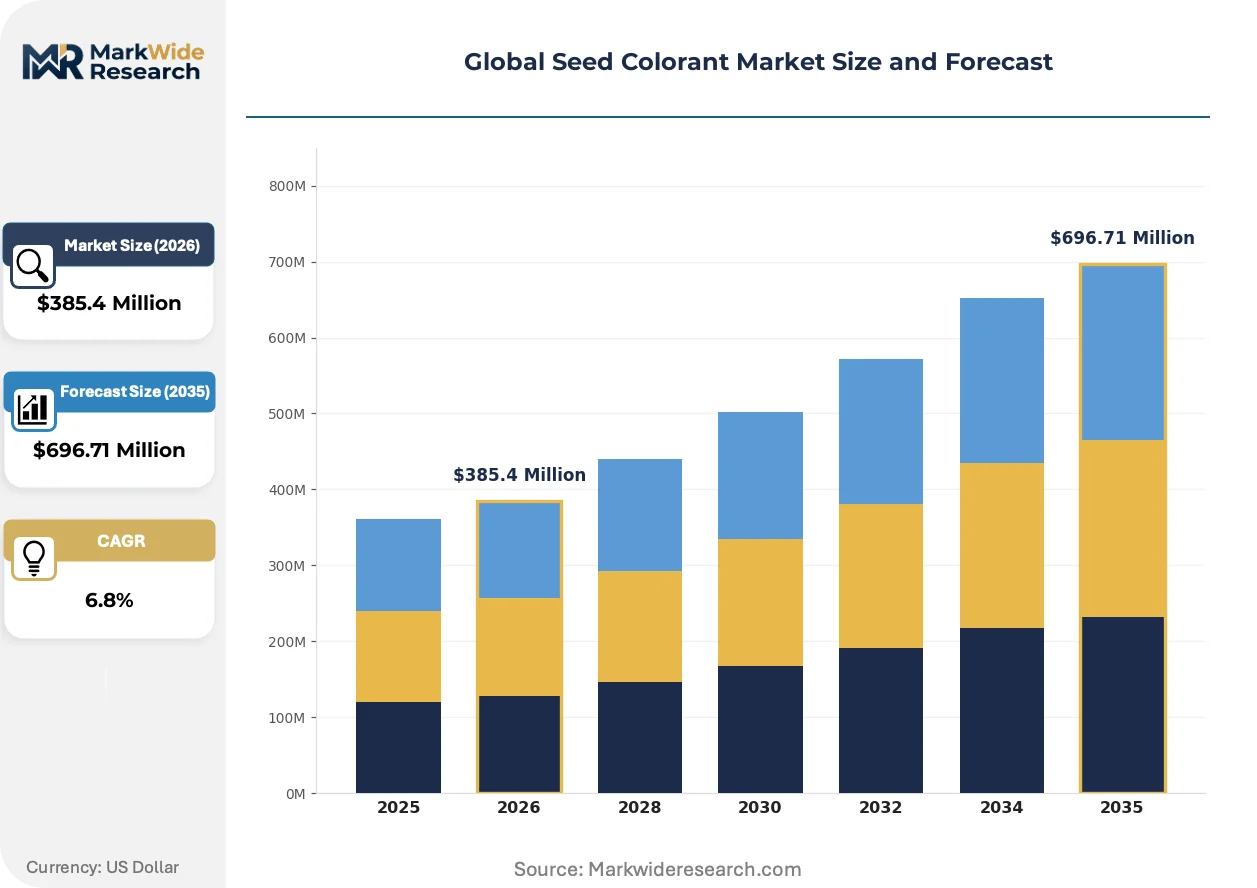
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, UV-Curable, Oil-Based, Powder Coating Application: Seed Identification, Pest Control, Germination Enhancement, Seed Treatment, Quality Assurance End User: Seed Producers, Agricultural Experiment Stations, Biotech Firms, Crop Protection Companies, Research Institutes Packaging Type: Bottles, Drums, Sachets, Bulk Containers, Capsules |
| Companies Covered | BASF SE, Sensient Technologies Corporation, Milliken & Company, Chromatech Incorporated, Heubach GmbH, Clariant AG, Bayer CropScience AG, Lanxess AG, Sun Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seed Colorant Market Shifts & Advancements
Formulation chemistry and application hardware are converging faster than regulatory frameworks can adapt, compressing product development cycles and rewarding suppliers with captive equipment partnerships.
UV-curable colorant systems are unifying pigment dispersion with instant polymerization on seed surfaces. Major seed treatment OEMs specify these chemistries for new inline curing modules capable of 40,000+ seeds per minute throughput. The technology is compressing the traditional drying stage, enabling treater footprints one-third the size of conventional setups while locking colorants against abrasion during pneumatic handling.
REACH authorization lists are forcing systematic substitution of cobalt-containing pigments across European seed supply chains. ECHA's 2024 sunset date for certain inorganic colorants triggered accelerated reformulation programs at major seed houses. Suppliers with pre-validated iron oxide alternatives capture switching premiums while laggards face stockout risks in Germany and France.
Identity-preserved procurement contracts now specify colorant provenance and batch-level traceability. Brazilian soybean processors audit seed treatment records to verify non-GMO chain-of-custody claims, embedding colorant documentation into commodity certification workflows. This behavioral shift concentrates purchasing authority at processor-level procurement desks rather than distributor sales teams.
Global Seed Colorant Market Segmentation
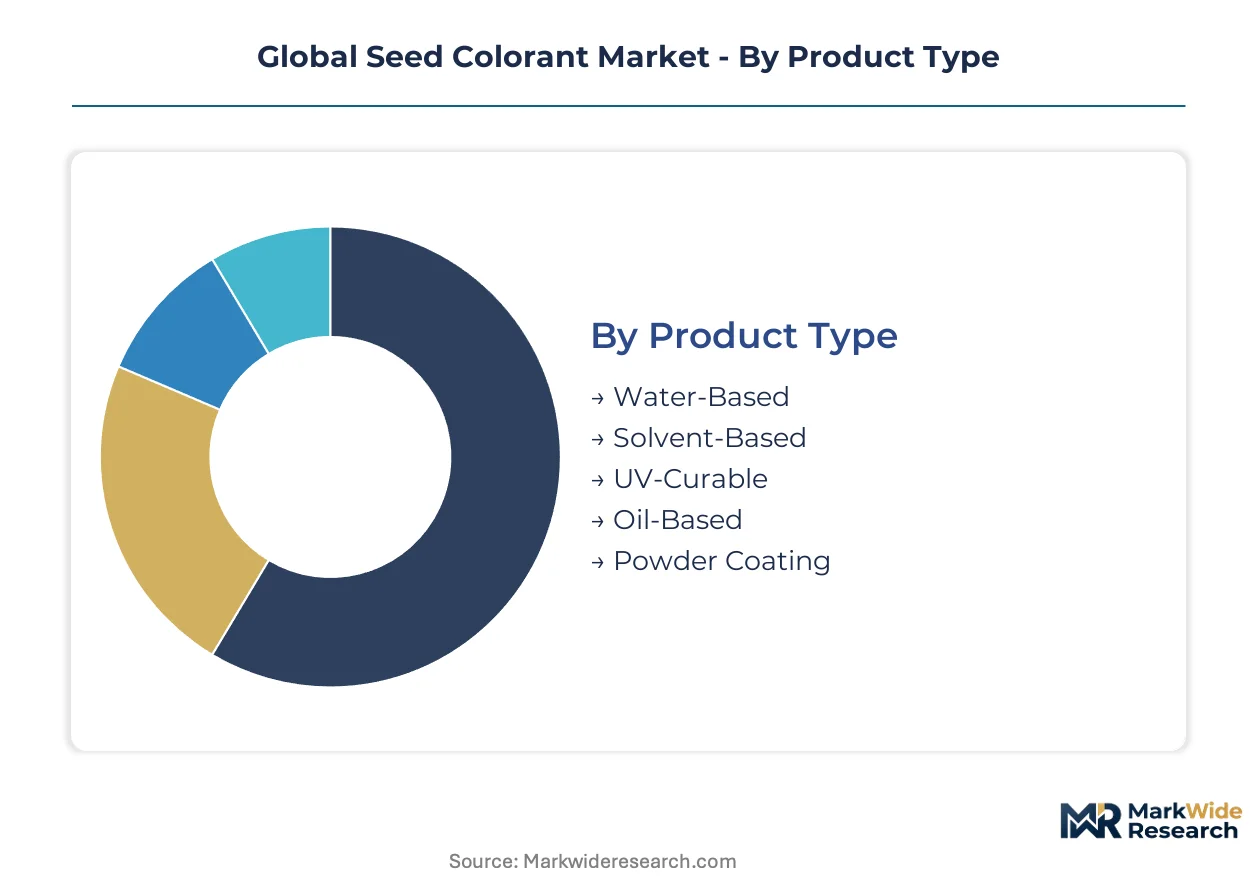
Seed colorant buyers prioritize adhesion performance, regulatory compliance, and equipment compatibility in fundamentally different ways. Segmentation reveals how formulation chemistry, application purpose, and procurement scale reshape supplier relationships across commercial agriculture.
Product Type:
Equipment warranties and environmental regulations split buyers between legacy compatibility and next-generation performance.
- Water-Based:Iron oxide and organic azo pigments suspended in aqueous polymer carriers dominate commercial volumes. Brazil's MAPA labeling standards and India's hybrid seed corridors drive concentrated procurement for soybean and rice multiplication programs.
- UV-Curable:Photoinitiator-activated systems polymerize instantly under inline curing lamps, enabling 40,000+ seeds per minute throughput on precision treaters. Inline UV-curing modules at major OEMs specify these chemistries, pulling demand from conventional drying-stage equipment.
- Solvent-Based:Hydrocarbon carriers deliver humidity tolerance for tropical storage conditions. REACH volatile organic compound ceilings constrain European formulation while Southeast Asian buyers retain procurement for monsoon-exposed seed stocks.
- Oil-Based:Hydrophobic binders resist moisture penetration in high-humidity climates. Procurement concentrates among palm oil and tropical cereal producers where seed longevity determines treatment economics.
- Powder Coating:Dry pigment-polymer blends suit small-batch specialty seed operations and remote treatment sites lacking liquid handling infrastructure.
Volume sits with Water-Based; growth tilts toward UV-Curable.
Application:
Commercial purpose determines whether colorants serve traceability mandates, treatment efficacy, or downstream processing requirements.
- Seed Identification:Visual differentiation enables variety segregation in multiplication fields and elevator intake. Identity-preserved soybean contracts in Brazil and non-GMO certification workflows embed colorant documentation into chain-of-custody audits.
- Seed Treatment:Colorant co-formulation with crop protection actives requires EPA FIFRA registration in the United States and synchronized REACH compliance in Europe. Registration timelines extending 36-48 months favor incumbent suppliers with validated polymer-binding systems.
- Pest Control:Repellent pigments signal treated status to reduce bird and rodent predation in open-field sowing. Demand clusters in sunflower and sorghum programs where untreated seed losses justify premium colorant loading.
- Germination Enhancement:Thermochromic and photoactive pigments indicate optimal soil temperature and moisture conditions for sowing timing. Precision agriculture platforms integrate these visual indicators into decision-support tools for direct-to-farm seed sales.
- Quality Assurance:Batch-level color consistency verification supports processor audits and export certification. European seed houses facing ECHA sunset dates for cobalt pigments absorb reformulation costs to maintain quality control workflows.
Procurement scale concentrates in Seed Identification; regulatory complexity peaks in Seed Treatment.
End User:
Buyer sophistication spans multinational R&D budgets to government research appropriations with diverging specification authority.
- Seed Producers:Multinational firms bundle colorants with proprietary treatment packages, capturing economies in high-volume hybrid corn and soybean programs. BASF SE and integrated crop science portfolios dominate procurement desks through captive formulation partnerships.
- Crop Protection Companies:Co-formulation registration strategies require colorant suppliers to align with agrochemical active ingredient portfolios. EPA FIFRA streamlined pathways reward suppliers with existing registration infrastructure.
- Biotech Firms:Trait-stacked seed varieties demand colorant systems compatible with stacked treatment layers and gene expression markers. R&D procurement prioritizes batch traceability over unit cost.
- Agricultural Experiment Stations:Public breeding programs specify colorants for variety release trials and foundation seed multiplication. Budget constraints favor water-based formulations with established performance databases.
- Research Institutes:Germplasm conservation and genetic diversity studies use colorants for accession tracking in gene bank operations. Low-volume, high-SKU procurement patterns stress supplier logistics.
Contract value peaks with Seed Producers; specification influence concentrates at Crop Protection Companies.
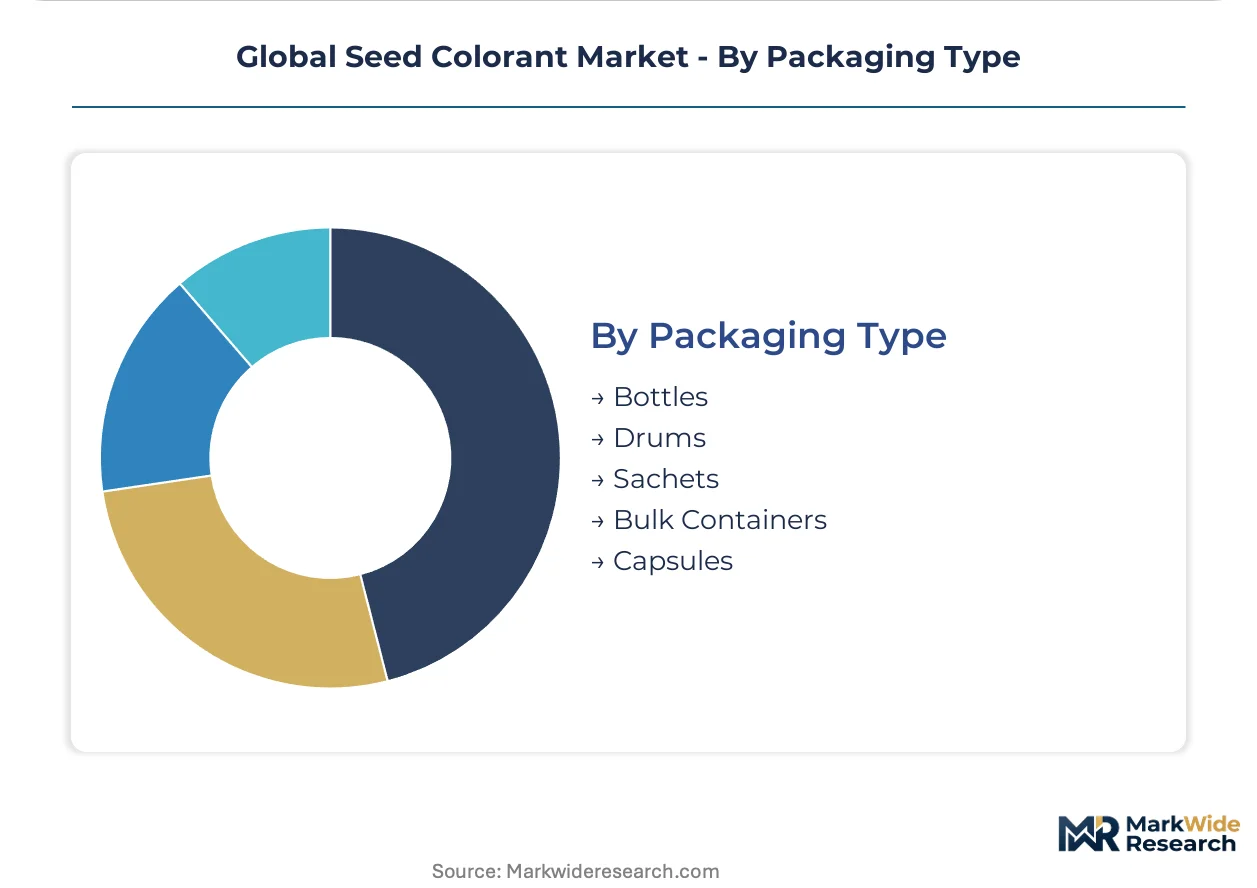
Packaging Type:
Logistics infrastructure and treatment scale determine whether buyers prioritize portability, bulk efficiency, or precision dosing.
- Bulk Containers:Intermediate bulk containers and tanker deliveries serve high-throughput treaters at commercial seed conditioning facilities. Brazilian soybean belt operations and US Corn Belt processors specify bulk to minimize handling labor.
- Drums:Standard 200-liter steel and polymer drums balance portability with volume efficiency for mid-scale seed houses. India's hybrid seed corridors and European cooperatives favor this format for multi-product treatment lines.
- Bottles:Liter-scale packaging suits research trials, specialty seed lots, and backup supply security. Biotech firms and research institutes absorb per-unit premiums for formulation flexibility.
- Sachets:Pre-measured single-batch packets enable field-level treatment in remote multiplication sites lacking liquid metering equipment. African and Southeast Asian smallholder seed programs specify sachets for distribution logistics.
- Capsules:Unit-dose encapsulation supports precision seed coating equipment with automated dispensing systems. Emerging in high-value vegetable seed operations where loading accuracy determines germination uniformity.
Shipment volume concentrates in Bulk Containers; format innovation targets Capsules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial grain producers in Brazil and India generate the steepest demand curves for seed colorants, while regulatory divergence between EPA FIFRA pathways and REACH authorization lists fragments formulation strategies across major agricultural economies.
United States
EPA FIFRA registration requirements govern colorant co-formulation with crop protection actives, compressing commercialization timelines for bundled seed treatment packages. The Corn Belt's high-throughput conditioning facilities specify water-based iron oxide systems compatible with existing pneumatic handling infrastructure. Midwestern seed houses absorb reformulation costs to maintain equipment warranty compliance.
Brazil
MAPA's mandatory treated-seed labeling standards create captive demand for approved colorant chemistries across the soybean belt. National agricultural regulators enforce visual differentiation requirements that directly specify pigment loadings for commercial multiplication programs. São Paulo-based seed conditioners dominate procurement volumes for identity-preserved non-GMO supply chains.
Germany
ECHA substance evaluations under REACH phase out cobalt-containing pigments, forcing systematic substitution toward iron oxide alternatives. Bavarian seed houses face 2024 sunset dates for legacy chromate colorants, accelerating reformulation programs. The Rhine-Ruhr industrial corridor concentrates pigment manufacturing capacity for EU-compliant water-based formulations.
India
Expanding hybrid rice and maize programs in Telangana and Karnataka generate concentrated demand for visual differentiation systems. The national agricultural research system specifies colorants for foundation seed multiplication and variety release trials. Haryana's seed processing clusters adopt water-based azo pigments for budget-constrained public breeding programs.
China
Iron oxide feedstock sourcing clusters in metallurgical processing regions expose formulators to geopolitical supply disruption risks. The national chemical safety regulator enforces environmental compliance standards for pigment manufacturing that reshape export-oriented formulation strategies. Shandong Peninsula pigment producers supply both domestic seed houses and international colorant formulators.
Global Seed Colorant Market Competitive Landscape
German chemical conglomerates anchor one tier through integrated crop science portfolios; North American pigment specialists hold formulation partnerships with seed treatment OEMs. The vendor base splits between consolidated multinationals with captive registration infrastructure and mid-scale suppliers competing on REACH compliance speed. Three archetypes dominate: integrated agrochemical-colorant bundlers, standalone pigment manufacturers with equipment partnerships, and regional formulators serving tropical humidity requirements. Competitive moves concentrate on co-development agreements with seed treatment machinery OEMs and synchronized multi-jurisdiction registration filings.
Within the integrated bundler tier, BASF SE exemplifies the crop science conglomerate archetype through captive formulation capabilities spanning colorants, polymers, and crop protection actives. Sensient Technologies Corporation occupies a position among North American specialists focused on pigment manufacturing rather than downstream seed treatment integration. Clariant AG represents the REACH-compliant formulation archetype, with water-based systems tailored to European regulatory sunset dates and ECHA authorization timelines. These three anchors illustrate how geographic regulatory divergence rewards divergent capability builds rather than universal product strategies.
| Leading Market Players |
|---|
| BASF SE |
| Sensient Technologies Corporation |
| Milliken & Company |
| Chromatech Incorporated |
| Heubach GmbH |
| Clariant AG |
| Bayer CropScience AG |
| Lanxess AG |
| Sun Chemical Corporation |
| Others |
Supply & Pricing Matrix
MAPA labeling standard compliance in Brazil forces seed houses to absorb reformulation costs for approved chemistries, compressing margins in water-based formulations while elevating premiums for REACH-validated alternatives in Europe. This demand-side specification pressure reshapes supplier pricing power across tropical and temperate agricultural corridors.
Pricing Analysis
Volume concentrates in water-based iron oxide systems at economy price points, while UV-curable formulations command premium positioning tied to equipment warranty compliance. Price differentiation hinges on REACH certification tier and polymer-binding performance guarantees. Pricing pressure stems from iron oxide feedstock volatility in Chinese metallurgical regions. Public breeding programs in India exhibit highest price sensitivity; multinational seed producers in Brazil absorb premiums for identity-preserved traceability systems.
Supply Chain Analysis
Iron oxide pigment supply rests on Chinese metallurgical processing clusters, with secondary concentration in German specialty chemical manufacturing and Indian azo compound production. Formulation chemistry draws from petroleum-derived photoinitiators, bio-based starch polymers, and solvent carriers. Single-source vulnerability in Chinese feedstock exposes formulators to geopolitical disruption. Distribution runs through seed treatment OEM technical partnerships rather than commodity chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-curable inline curing systems are displacing conventional drying-stage equipment across precision seed treatment lines, compressing development cycles for compatible colorant-polymer formulations. This technology transition rewards suppliers with captive machinery partnerships and validated registration infrastructure.
For Market Incumbents: To counter iron oxide supply concentration in Chinese processing regions, BASF SE and integrated agrochemical bundlers should deepen backward integration into captive pigment manufacturing and accelerate REACH-compliant water-based formulation partnerships with European seed houses. Certification investment in synchronized EPA-REACH-MAPA registration pathways preserves incumbent switching costs against mid-scale challengers. For New Entrants and Emerging Players: The price-point gap between premium UV-curable systems and economy water-based formulations creates entry space for mid-tier hybrid chemistries targeting India's hybrid seed corridors and Southeast Asian tropical humidity requirements. New suppliers should prioritize biopolymer-binding expertise partnerships with starch-derived polymer developers to capture EU Green Deal mandate premiums. For Investors and Strategic Acquirers: The window for entry favors regional formulators with validated equipment partnerships and multi-jurisdiction registration infrastructure. Long-term viability concentrates in suppliers bridging legacy water-based compatibility with next-generation UV-curable performance. Watch for ECHA authorization timeline acceleration as inflection signal for European reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iron Oxide Feedstock | Captive supply from Chinese metallurgical regions reduces geopolitical exposure for major formulators. |
| UV-Curable Formulation Partnerships | Equipment OEM specifications at precision treater manufacturers lock in premium chemistry demand. |
| Biopolymer-Binding R&D Investment | EU Green Deal mandates for bio-based seed coatings open formulation collaboration opportunities. |
| Synchronized Multi-Jurisdiction Registration | Streamlined EPA-REACH-MAPA pathways compress time-to-revenue for novel pigment chemistries. |
| Direct-to-Farm Digital Channel Development | Precision agriculture platforms bypass distributor markups in identity-preserved specialty seed segments. |
Research Methodology
Document review covered EPA FIFRA registration databases, ECHA authorization lists, and MAPA labeling standards, complemented by interviews with seed treatment equipment OEM technical directors, formulation chemistry R&D leads at multinational agrochemical firms, procurement managers at Brazilian soybean processors, and regulatory affairs specialists at European seed houses. Secondary validation drew from customs trade data, SEC 10-K filings of listed pigment manufacturers, and national agricultural regulator enforcement notices. Bottom-up volume estimates from seed treatment line throughput data were triangulated against top-down market sizing from agrochemical industry association reports.
Segment-level projections across water-based, UV-curable, solvent-based, oil-based, and powder coating chemistries were modeled against application purpose and end-user procurement scale dimensions throughout the forecast period. CAGRs were derived from equipment installation rates at precision seed treatment facilities and regulatory mandate implementation timelines. Key inputs included polymer-binding performance specifications tied to machinery warranty requirements and iron oxide feedstock pricing volatility indices.
Underlying measurement precision varies by segment; UV-curable and water-based formulations carry tighter precision than powder coating and oil-based categories due to equipment specification transparency. Forecasts reflect assumptions about ECHA sunset date adherence and MAPA enforcement consistency. A small set of triggers—iron oxide supply disruption, REACH authorization acceleration, and UV-curing equipment adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
Feed Micronutrients Market