
 Soy Grits Market | 2026-2036
Soy Grits Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Grits Market Analytics
The EU Green Deal's protein diversification targets is pivoting European food manufacturers toward domestically processed soy ingredients. Cargill Inc. leverages its North American crush capacity to supply food-grade grits to European bakery and meat-alternative producers. Archer Daniels Midland Company anchors its position through integrated origination-to-processing infrastructure across the US Midwest. Fuji Oil Holdings Inc. specializes in Asian market formulations, competing on texture optimization for snacks and breakfast applications.
Soy grits are coarsely ground, toasted soybean particles typically retaining 40-50% protein content, produced through extrusion or conventional milling to serve as textured protein carriers, binders, and nutritional fortifiers in formulated foods. Food grade grits command premium positioning against feed grade variants as clean-label bakery and meat-alternative applications expand. The meat alternatives segment is outpacing conventional baking in growth velocity, while organic product type variants capture margin pools from health-conscious home cooks and nutritionist-directed formulations.
USDA grading standards and FDA food safety regulations govern protein content claims and allergen labeling, directly shaping product specifications for food manufacturers. REACH compliance in Europe and China's GB standards for plant-based foods establish divergent technical thresholds that exporters must navigate for market access. Stakeholders should monitor evolving protein content thresholds across jurisdictions to anticipate reformulation requirements and certification investments.
Market Dynamics
Plant-based meat manufacturers are consolidating procurement around food-grade soy grits as textured protein demand accelerates, compressing supplier margins and favoring crush-to-food-grade integrated processors with certified allergen controls.
Growth Catalysts
- EU Green Deal protein diversification:The European Commission's Farm to Fork Strategy mandates reducing reliance on imported animal feed proteins, redirecting bakery and meat-alternative manufacturers toward domestically processed soy ingredients with verified sustainability credentials.
- Extrusion technology advancement:High-moisture extrusion systems now produce meat-analog textures from coarse grits without secondary binding agents, cutting formulation costs for alternative protein startups.
- China's domestic crush expansion:New food-grade processing lines in Shandong and Jiangsu provinces are displacing imported grits volumes as regional food manufacturers localize supply chains.
Market Restraints
- Soybean price volatility:Weather-driven harvest variability in Brazil and Argentina transmits directly to grits input costs, squeezing margin-stability for long-term contract manufacturers.
- Allergen labeling complexity:FDA's Food Allergen Safety, Treatment, Education, and Research Act requires prominent soy disclosure, limiting formulation flexibility in clean-label product development.
- Pea protein substitution:Extracted pea concentrates with comparable emulsification properties are capturing share in premium meat-alternative applications where protein content claims matter less than allergen avoidance.
Strategic Opportunities
- Organic certification tier:USDA Organic and EU Organic certified grits command 40-60% price premiums as health-conscious home cooks and clinical nutritionists specify non-GMO, pesticide-free ingredients.
- Direct-to-manufacturer platforms:Digital procurement channels connecting crush facilities with mid-sized food formulators are compressing traditional distributor markups in North American and European markets.
- Precision fermentation convergence:Hybrid formulations combining soy grits carriers with fermented protein isolates enable texture optimization while reducing overall soy allergen load per serving.
Industry Challenges
- Food safety certification timelines:BRCGS and FSSC 22000 audits require 6-12 month implementation periods, delaying market entry for new crush-to-food-grade facilities.
- Extrusion operator skill scarcity:High-moisture extrusion demands precise moisture-protein-temperature calibration that experienced technicians command premium wages to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Grits Market |
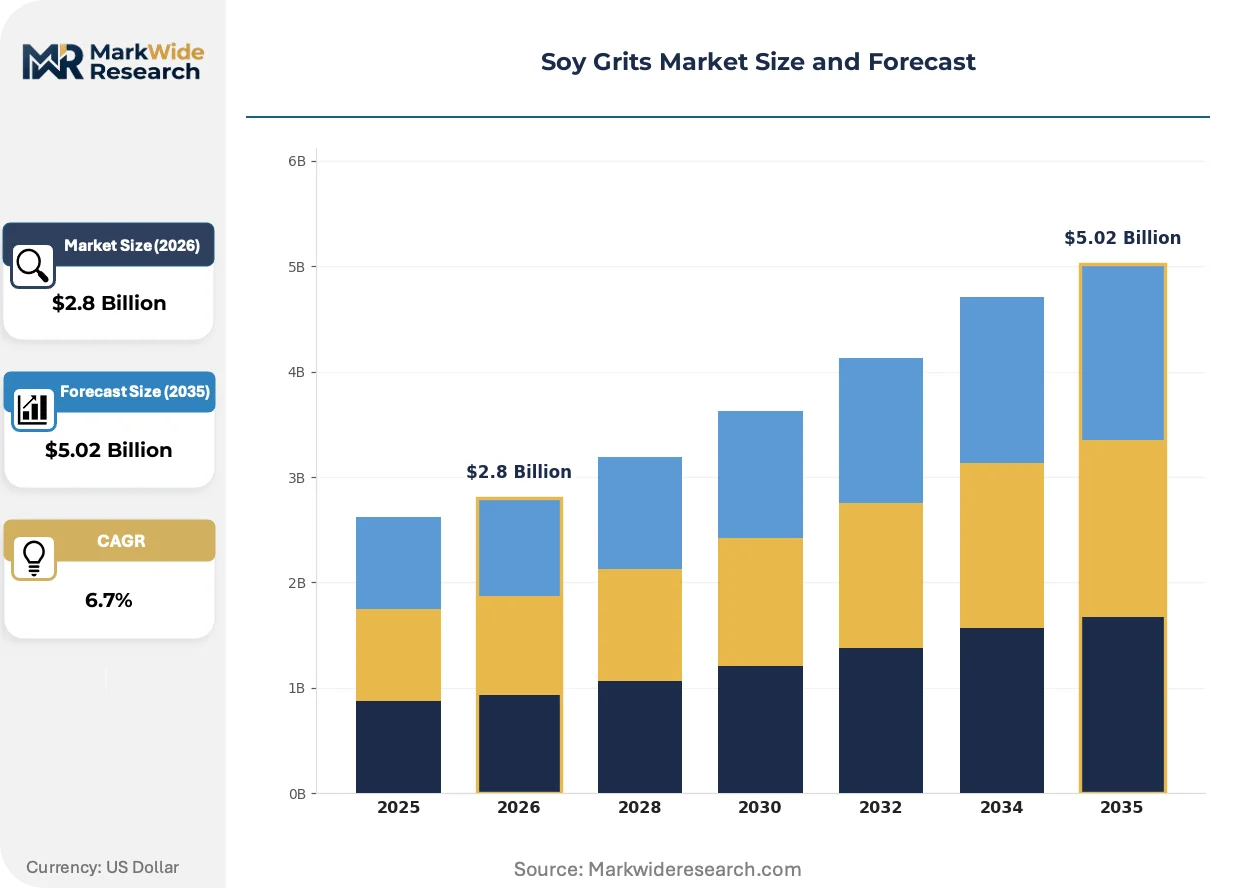
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Feed Grade, Organic, Conventional Application: Baking, Snacks, Meat Alternatives, Breakfast Foods Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Food Service End User: Food Manufacturers, Restaurants, Home Cooks, Nutritionists |
| Companies Covered | Wilmar International, Ag Processing Inc., Cargill Inc., Fuji Oil Holdings Inc., Crown Soya Protein Group, Archer Daniels Midland Company, CHS Inc., Gujarat Ambuja Exports Ltd., Bunge Global SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Grits Market Evolving Landscape
Extrusion technology refinement and regulatory protein-content thresholds are compressing traditional formulation approaches while opening precision-engineered texture categories for next-generation meat alternatives.
High-moisture extrusion is integrating shear-cell technology that aligns protein fibers without mechanical cooling, enabling whole-muscle analog production. Plant-based steak and seafood formulators in Germany and the Netherlands are adopting these systems at pilot scale. The technology is integrating formerly separate texturization and binding process steps, reducing capital intensity for mid-scale production facilities.
REACH compliance in Europe is tightening residual solvent limits for hexane-extracted protein ingredients, forcing crush facilities to document extraction method transparency. Food manufacturers sourcing EU-bound grits now require certificates of analysis specifying extraction chemistry. Bakery and meat-alternative segments with EU export exposure are reformulating around expeller-pressed or aqueous-extracted alternatives to maintain market access.
Buyer concentration among multinational meat-alternative brands is consolidating procurement around single-source, multi-year supply agreements with integrated crush-to-food-grade processors. Traditional commodity distributors serving regional bakeries are losing volume to direct mill relationships. This pattern is most visible in the US Midwest and Germany's Ruhr industrial corridor where Cargill and ADM anchor supply security for Impossible Foods, Beyond Meat, and Rügenwalder Mühle.
Soy Grits Market Segmentation
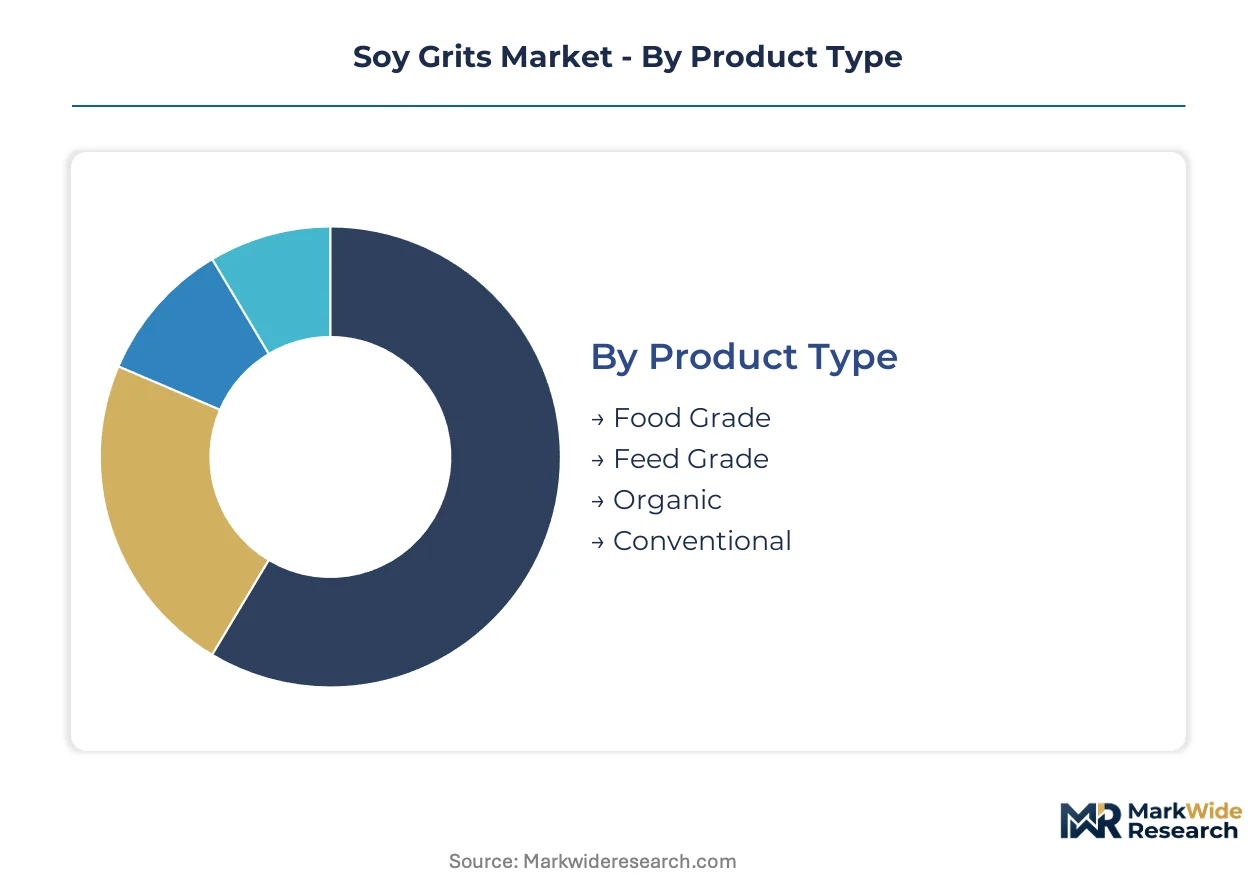
Segmentation in soy grits tracks the divergence between commodity feed inputs and premium food-grade specifications. Protein content thresholds, extraction methods, and allergen certification tiers determine pricing power across end-use applications.
Product Type:
Protein retention rates and extraction chemistry distinguish commercial tiers, with solvent documentation now mandatory for EU-bound shipments.
- Food Grade:Retains 40-50% protein content through controlled toasting and milling parameters. Meat-alternative manufacturers in Germany and the Netherlands specify food-grade grits for high-moisture extrusion systems that align protein fibers without secondary binders.
- Organic:USDA Organic and EU Organic certified variants command substantial premiums from health-conscious home cooks and clinical nutritionists directing pesticide-free formulations. Certification requires documented non-GMO seed stock and prohibited substance audits across the crush-to-package chain.
- Feed Grade:Lower protein retention suited for aquaculture and livestock compound feeds. Pricing tracks soybean futures with minimal specification premiums.
- Conventional:Standard cultivation with glyphosate-tolerant varieties. Dominates volume in price-sensitive bakery applications where protein content claims are secondary to cost control.
Mature deployment sits with Conventional. Newer deployment is concentrated in Organic.
Application:
End-use differentiation tracks texture requirements and binding functionality demanded by specific food manufacturing processes.
- Meat Alternatives:High-moisture extrusion demands precise moisture-protein-temperature calibration that shear-cell technology now delivers without mechanical cooling. Beyond Meat and Impossible Foods procurement contracts specify food-grade grits with certified allergen controls.
- Baking:Coarse particles provide structure and moisture retention in commercial bread formulations. Clean-label bakery trends in France and Italy are displacing modified wheat gluten with soy protein fortification.
- Snacks:Extruded puffs and crisps leverage soy grits as carriers for flavor systems and protein fortification. Asian snack manufacturers optimize texture through particle size distribution control.
- Breakfast Foods:Cereal and granola applications require toasted grits with specific browning profiles. Nutritionist-directed formulations specify organic certification for pediatric and clinical diet segments.
Volume concentration remains in Baking. Value expansion is climbing fastest in Meat Alternatives.
Distribution Channel:
Channel structure reflects buyer scale and certification documentation requirements.
- Food Service:Direct mill relationships with institutional bakery and meat-alternative producers bypass traditional distributor markups. Multi-year supply agreements predominate.
- Supermarkets:Packaged retail grits for home cooks concentrate in organic and conventional tiers. Shelf placement tracks regional dietary trends.
- Online Retail:Digital procurement platforms connect small-scale food formulators with certified crush facilities. Transparency on extraction methods drives purchase decisions.
- Health Food Stores:Specialist retailers curate organic and non-GMO verified SKUs for nutritionist-directed clientele. Staff training emphasizes protein content claims.
Established volume flows through Food Service. Emerging volume is gaining share fastest through Online Retail.
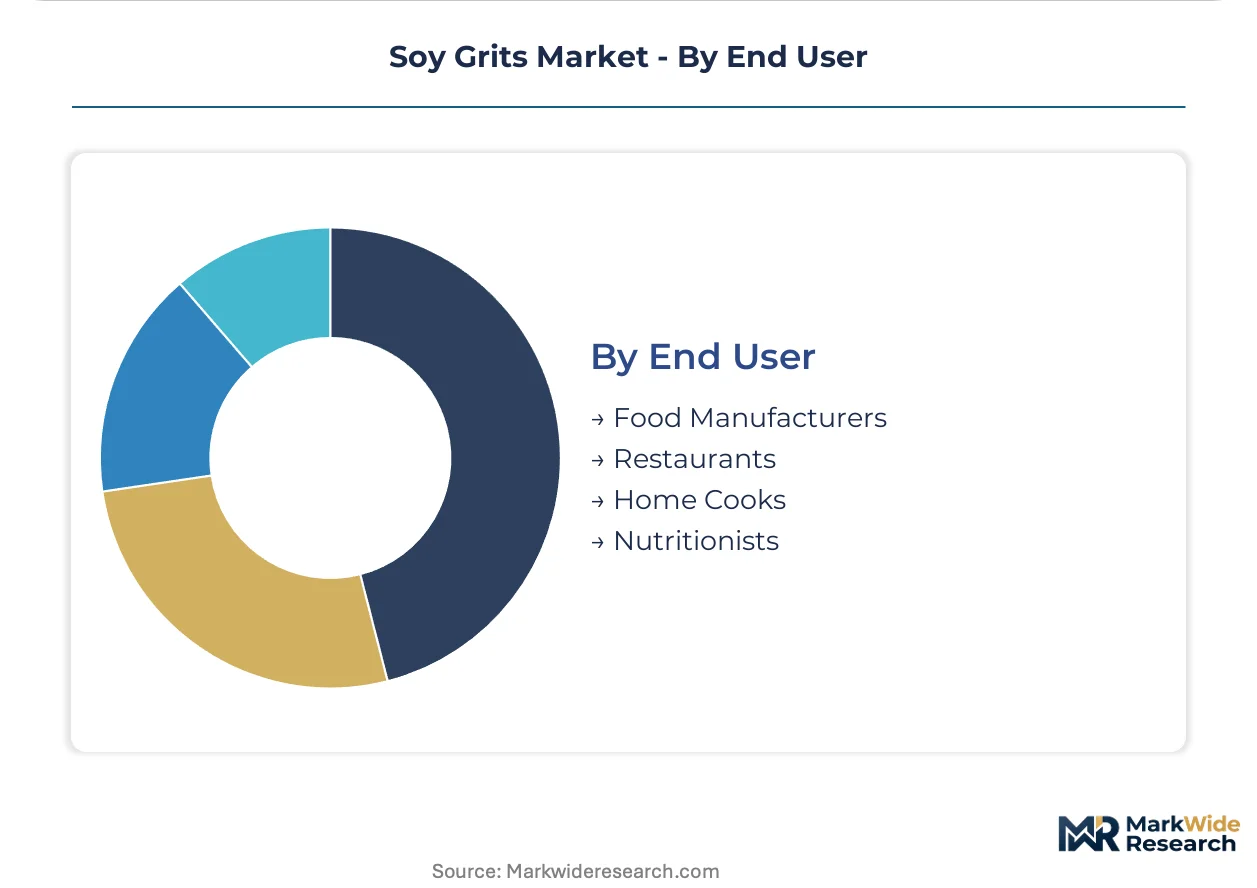
End User:
User categories track formulation expertise and specification authority.
- Food Manufacturers:Integrated procurement teams negotiate direct supply agreements with crush-to-food-grade processors. BRCGS and FSSC 22000 certification gates supplier qualification.
- Nutritionists:Clinical dietitians specify organic grits for therapeutic nutrition formulations. Documentation requirements exceed standard food-grade thresholds.
- Restaurants:Plant-based menu development drives spot purchasing of textured protein ingredients. Supply reliability outweighs price sensitivity.
- Home Cooks:Retail package sizes dominate. Purchase drivers center on organic certification and allergen labeling clarity.
Procurement scale concentrates with Food Manufacturers. Specification influence is expanding most quickly through Nutritionists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in crushing corridors while consumption clusters in food manufacturing hubs. Brazil and Argentina supply raw soybeans to processors in China, Germany, and the United States. This geographic split creates logistics dependencies that shape procurement strategies across food-grade grits markets.
United States
Midwest crushing facilities in Iowa and Illinois supply food-grade grits to meat-alternative manufacturers. FDA allergen labeling requirements under FASTER Act compliance shape formulation specifications for bakery and protein analog producers. Chicago and Minneapolis anchor procurement teams negotiating multi-year supply agreements with integrated crush-to-food-grade processors.
China
Domestic crush expansion in Shandong and Jiangsu provinces displaces imported grits volumes as regional food manufacturers localize supply chains. GB standards for plant-based foods establish protein content thresholds that exporters must navigate for market access. Qingdao and Nantong host new food-grade processing lines serving snack and breakfast food formulators.
Germany
EU Green Deal protein diversification targets redirect bakery and meat-alternative manufacturers toward domestically processed soy ingredients. REACH compliance tightens residual solvent limits for hexane-extracted ingredients, forcing documentation of extraction chemistry. Cologne and Hamburg industrial corridors concentrate extrusion technology adoption for whole-muscle analog production.
Brazil
Weather-driven harvest variability in Mato Grosso and Paraná transmits directly to global grits input costs. ANVISA food safety regulations govern export certification for food-grade specifications. Santos port infrastructure handles crush facility outputs destined for European and Asian food manufacturers.
India
Gujarat and Maharashtra processing hubs serve domestic bakery fortification and emerging meat-alternative segments. FSSAI standards for plant protein ingredients establish labeling and safety thresholds. Ahmedabad and Mumbai food manufacturers specify organic certification tiers for nutritionist-directed formulations.
Soy Grits Market Competitive Landscape
The competitive structure tilts toward integrated crush-to-food-grade processors with certified allergen controls. Supplier consolidation favors multi-facility operators capable of multi-year supply agreements with multinational meat-alternative brands. Three archetypes dominate: North American grain traders with Midwest crush infrastructure, Asian specialists in texture optimization, and diversified agribusiness conglomerates with origination-to-processing integration. Capacity expansion and direct-to-manufacturer platform development constitute the dominant competitive moves.
Among North American integrated processors, Cargill Inc. and Archer Daniels Midland Company exemplify the crush-to-food-grade archetype with origination infrastructure across the US Midwest. Fuji Oil Holdings Inc. represents Asian market specialization in texture optimization formulations. Wilmar International anchors the diversified agribusiness tier with multi-continental crush and processing footprints. These three occupy positions that illustrate the geographic and capability segmentation defining procurement relationships.
| Leading Market Players |
|---|
| Wilmar International |
| Ag Processing Inc. |
| Cargill Inc. |
| Fuji Oil Holdings Inc. |
| Crown Soya Protein Group |
| Archer Daniels Midland Company |
| CHS Inc. |
| Gujarat Ambuja Exports Ltd. |
| Bunge Global SA |
| Others |
Value Network & Pricing Analysis
Multinational meat-alternative brand procurement teams concentrate demand around multi-year supply agreements, anchoring pricing power with integrated crush-to-food-grade processors rather than commodity distributors. This buyer consolidation compresses margins for fragmented suppliers while rewarding certified allergen-controlled facilities with contract stability.
Pricing Analysis
Margin tightening in food-grade tiers reflects buyer consolidation around BRCGS-certified suppliers. Three-tier pricing structure across organic, food-grade, and feed-grade levels separates premium certification tiers from commodity variants. Cost compression accelerates as high-moisture extrusion technology cuts binding agent requirements. Regional bakery formulators exhibit highest price sensitivity; clinical nutritionists directing organic specifications show least.
Supply Chain Analysis
Direct-to-manufacturer platforms connect crush facilities with mid-sized food formulators, compressing traditional distributor markups. Supply concentrates in the United States, Brazil, and China. Raw material flows draw from Mato Grosso soy harvests, Shandong processing lines, and Iowa crush infrastructure. Commodity price volatility from weather-driven Brazilian harvest variability constitutes the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-moisture extrusion technology is displacing conventional texturization methods, creating transition-phase positioning stakes for suppliers capable of shear-cell fiber alignment without mechanical cooling.
For Market Incumbents: Anchor supply security through backward integration into food-grade crush capacity across the US Midwest and Germany's Ruhr corridor. Invest in BRCGS and FSSC 22000 certification ahead of buyer qualification gates. Counter pea protein substitution threats by developing hybrid formulations with fermented protein isolates. For New Entrants and Emerging Players: Enter via organic certification tiers serving nutritionist-directed formulations in India and European clinical diet segments. Target white-space in aqueous-extracted grits production for EU-bound shipments facing REACH solvent limits. Pursue digital procurement platform partnerships to bypass established distributor networks. For Investors and Strategic Acquirers: The window for entry favors integrated crush-to-food-grade processors with multi-facility footprints and established multinational brand relationships. Long-term viability centers on origination-to-processing infrastructure capable of weathering commodity volatility cycles. Monitor EU Green Deal protein diversification implementation velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Food-Grade Crush Capacity Expansion | Positions suppliers for Beyond Meat and Impossible Foods procurement contracts. |
| Organic Certification Investment | Captures 40-60% price premiums from clinical nutritionist-directed formulations. |
| High-Moisture Extrusion Technology Adoption | Enables whole-muscle analog production for German and Dutch formulators. |
| Direct-to-Manufacturer Platform Development | Compresses distributor markups in North American and European markets. |
| REACH-Compliant Extraction Method Transition | Maintains EU market access as residual solvent limits tighten. |
Research Methodology
USDA crop reports, FDA food safety filings, and EU Farm to Fork Strategy documentation formed the secondary backbone. Primary interviews with crush facility operators, meat-alternative procurement directors, and bakery formulation scientists combined with trade flow databases. Bottom-up volume estimates and top-down value triangulation anchored segmentation outputs.
Historical trendline analysis tracked protein content threshold evolution and extrusion technology diffusion patterns across the analysis window. Segmentation modeled product type tiers, application end-uses, and distribution channel structures. CAGRs derived from fitted growth curves applied to baseline consumption estimates. Forecast inputs incorporated EU Green Deal implementation timelines and China's domestic crush expansion trajectories.
Revisions become necessary when soybean harvest variability exceeds modeled ranges or when regulatory protein content thresholds shift materially. Forecasts reflect assumptions regarding sustained meat-alternative demand growth and certification standard stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
United States Rice Market
Grains
Oat Bran Market
Grains
Asia-Pacific Rice Market
Grains
Corn Market
Grains
North America Maize Market
Grains
Oat Flour Market
Grains
Oatmeal Market
Grains
Basmati Rice Market
Grains
IQF Rice Market
Grains
Wheat Protein Market
Grains
Europe Wheat Market
Grains
South Africa Maize Market
Grains
Wild Rice Market
Grains
Wheat Flour Market
Grains
Asia-Pacific Wheat Market
Grains
Asia Pacific Maize Market