
 Recycled Plastic Envelope Market | 2026-2036
Recycled Plastic Envelope Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Plastic Envelope Market Analytics
A capital-intensity divergence between integrated resin producers and downstream converters is bifurcating competitive dynamics in recycled plastic envelopes. Amcor Plc leverages captive recycling infrastructure to secure rPET supply chains across multiple continents. Berry Global Inc. anchors its position through blown film extrusion scale that lowers unit costs for bubble and padded envelope grades. UFlex Limited competes on flexible packaging specialization, extending its India-based manufacturing footprint into Middle Eastern e-commerce corridors.
Recycled plastic envelopes are protective mailing vessels manufactured from reprocessed polyethylene or polyester resins, typically containing 30-100% post-consumer content and engineered to specified burst strengths for parcel transit. Their primary commercial purpose is to replace virgin polymer mailers in business-to-consumer and business-to-business shipping workflows. LDPE-based bubble envelopes currently occupy the largest volume share due to compatibility with existing blown film infrastructure and cushioning performance, while PET flat envelopes represent the fastest-expanding margin pool as brand owners pursue higher visible recycled content for sustainability messaging. E-commerce end users drive the steepest demand curve, though logistics providers are consolidating procurement around standardized HDPE specifications to simplify sortation at material recovery facilities.
FDA food-contact clearance requirements, EPA recycled content procurement guidelines, and EU REACH substance restrictions collectively shape formulation choices and market access for cross-border envelope suppliers. The EU Packaging and Packaging Waste Regulation tightens recyclability design standards, forcing non-compliant producers to reformulate adhesives and multilayer structures. Stakeholders must monitor evolving extended producer responsibility fee structures and decide whether to absorb compliance costs or pass them through to price-sensitive e-commerce platform customers.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement is compressing formulation timelines for multilayer adhesive systems, forcing converters to choose between accelerated R&D spend or market exit. This regulatory compression cascades through resin procurement, equipment retrofitting, and customer qualification protocols.
Growth Catalysts
- EU Green Deal packaging mandates:Post-consumer recycled content minimums for e-commerce mailers activate capacity investments across blown film extrusion lines. Germany's mail-order retail density accelerates compliance-driven procurement.
- LDPE bubble envelope compatibility:Existing infrastructure reuse lowers capital barriers for converters pivoting from virgin to recycled feedstock. Cushioning performance parity sustains adoption in fragile goods shipping.
- Amazon's plastic-free packaging pledge:Platform-level sustainability commitments transmit demand signals through third-party seller networks, consolidating specification standards for padded mailers.
Market Restraints
- Post-consumer rPET supply concentration:Collection infrastructure gaps in Eastern Europe limit feedstock availability for flat envelope producers seeking visible recycled content ratios.
- Multilayer barrier performance:Oxygen and moisture transmission rates in recycled polyethylene structures lag virgin equivalents, restricting adoption in humidity-sensitive product categories.
- Adhesive reformulation costs:EU REACH substance restrictions on conventional hot-melt chemistries require solvent-free system validation, extending qualification cycles by 8-14 months.
Strategic Opportunities
- India e-commerce corridor expansion:Flipkart and Meesho fulfillment networks lack compliant padded mailer supply, creating first-mover positioning for rPE bubble envelope specialists.
- Blockchain-enabled provenance tracking:Integration with digital product passports allows premium pricing for verified post-consumer content claims in luxury goods shipping.
- Reverse logistics packaging reuse:Closed-loop rental models for durable polypropylene mailers capture value from return-rate differentials in apparel subscription services.
Industry Challenges
- Blow molding technician scarcity:Specialized knowledge of co-extrusion die design for recycled content blends concentrates in aging workforce cohorts across Midwest US manufacturing clusters.
- Sortation facility contamination:Multilayer bubble structures with incompatible adhesive layers disrupt automated near-infrared separation at material recovery facilities, triggering downstream rejection fees.
- ISO 18601 certification timelines:Extended producer responsibility compliance documentation requirements delay market entry for mid-scale converters lacking dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Plastic Envelope Market |
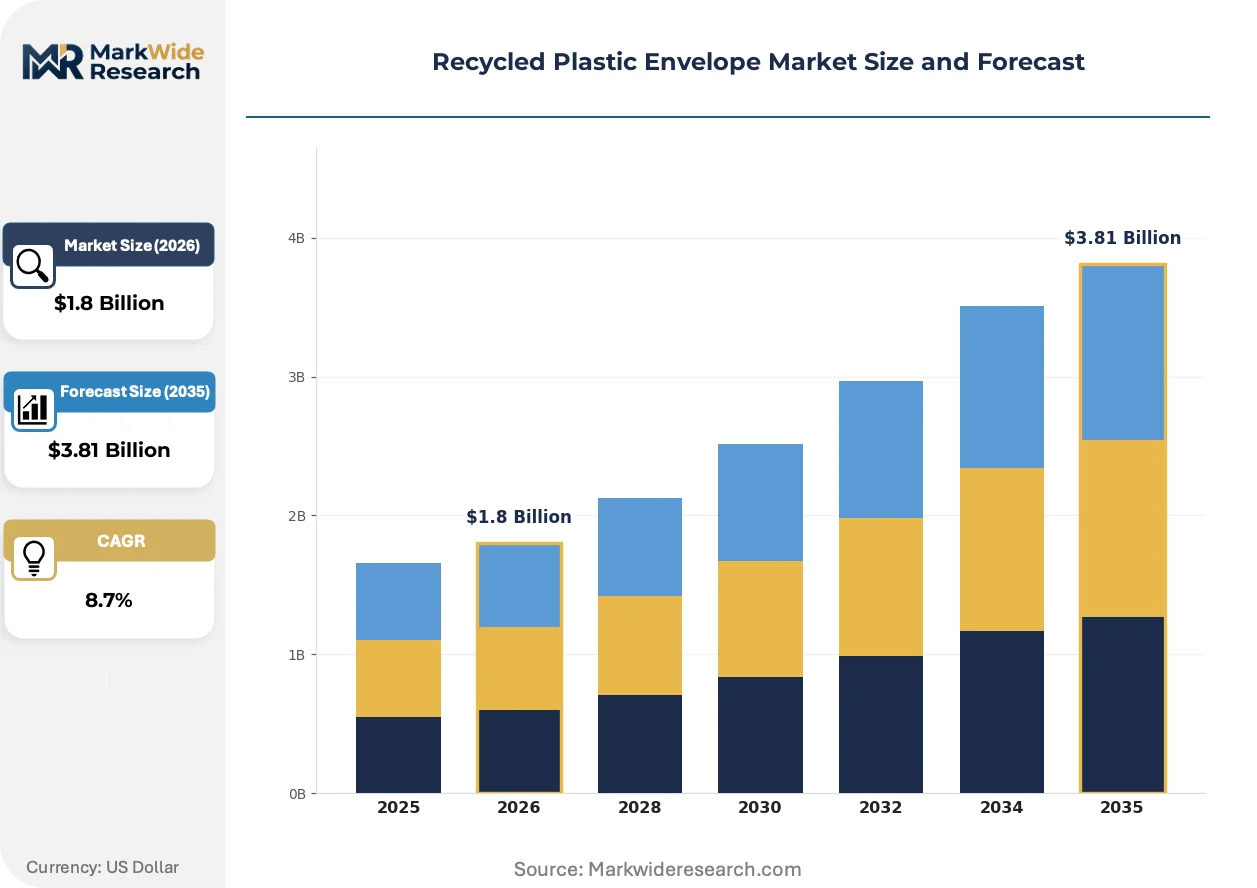
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jumbo Envelopes, Bubble Envelopes, Padded Envelopes, Flat Envelopes Material: LDPE, HDPE, PET, Polypropylene End User: Retail, E-commerce, Logistics, Office Supplies Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Amcor Plc, Berry Global Inc., Sonoco Products Company, Sealed Air Corporation, Indorama Ventures Public Co., Ltd, ALPLA Werke Alwin Lehner GmbH & Co KG, Plastipak Holdings, Inc., UFlex Limited, Placon Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Plastic Envelope Market Evolving Landscape
Digital printing integration and mono-material design protocols are converging to redefine envelope customization and end-of-life performance. These shifts compress production batch economics while elevating recyclability credentials.
Water-based inkjet printing systems for variable data and branding are miniaturizing run-length economics for e-commerce platform sellers. Mid-volume merchants now access lot-size-one customization previously reserved for enterprise accounts. This capability is miniaturizing minimum order thresholds and fragmenting converter customer portfolios toward higher SKU complexity.
EU REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from food-adjacent mailer applications. Reformulation toward silicone-based alternatives raises unit costs by 12-18% for compliant producers. Bakery and specialty food subscription services in France and Germany absorb these premiums to maintain single-stream recyclability claims.
Direct-to-brand procurement models are displacing distributor intermediaries in enterprise envelope purchasing. Sustainability officers at major retailers now negotiate specifications directly with resin producers and extrusion houses. This pattern concentrates most visibly in German automotive parts logistics, where BMW and Volkswagen Group have consolidated padded mailer contracts under centralized packaging engineering teams.
Recycled Plastic Envelope Market Segmentation
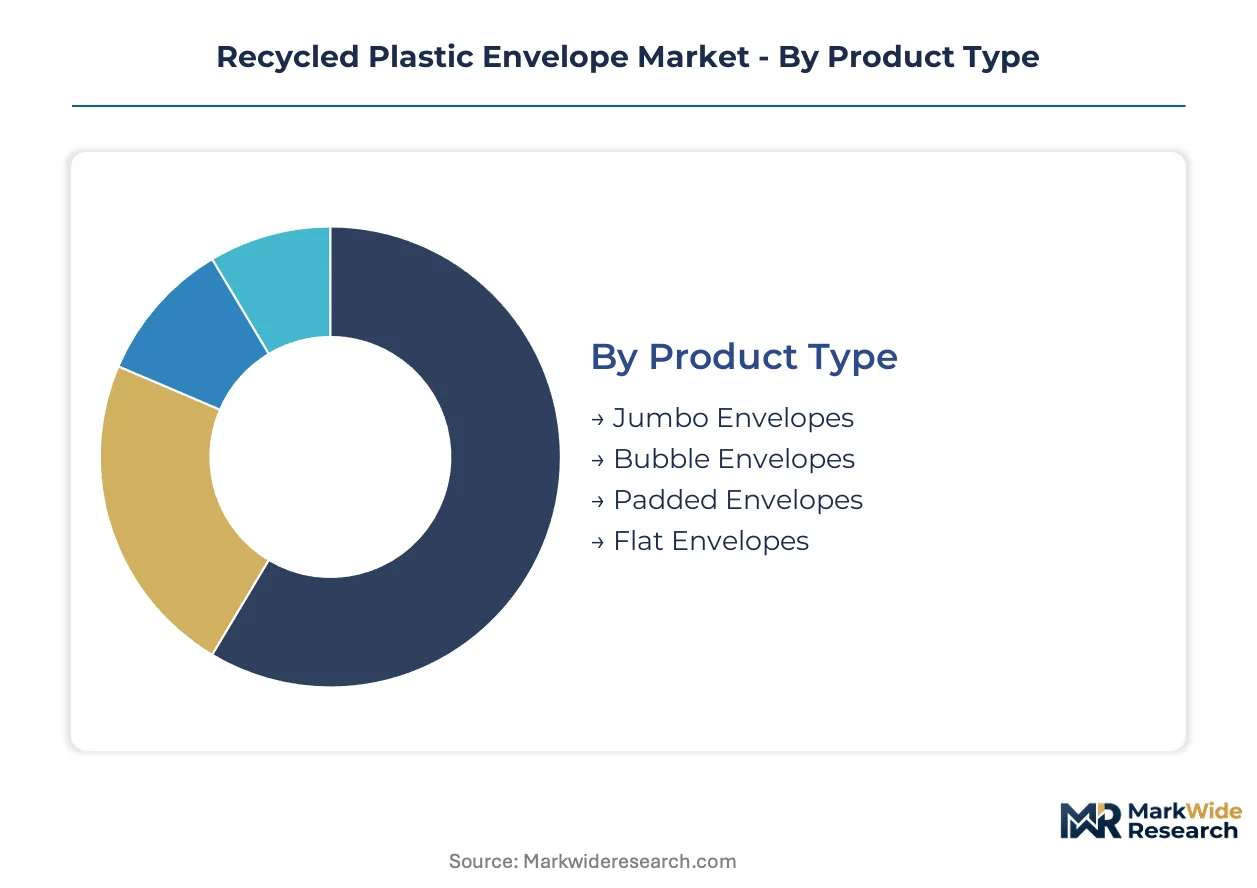
Segmentation in recycled plastic envelopes reveals where substitution pressures from paper mailers and reusable packaging bite hardest. Understanding these fault lines helps converters allocate R&D budgets and resin procurement toward defensible positions.
Product Type:
Bubble envelopes face the sharpest substitution threat from corrugated bubble wrap and honeycomb paper structures in premium e-commerce channels.
- Bubble Envelopes:Co-extruded LDPE films with trapped air pockets provide impact protection for electronics and cosmetics. Demand concentrates in German mail-order retail, where the EU Green Deal's recycled content mandates have accelerated rPE specification adoption.
- Flat Envelopes:Single-layer PET or HDPE constructions maximize visible recycled content for sustainability messaging. Apparel subscription services in France drive procurement, though moisture barrier limitations restrict adoption in humid climates.
- Jumbo Envelopes:Oversized LDPE formats for bulk document shipping and soft goods.
- Padded Envelopes:Fiber-filled alternatives to bubble structures for lightweight cushioning.
Bubble envelopes retain volume leadership; flat envelopes hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity recyclates from premium food-grade rPET, with mid-tier rHDPE capturing logistics standardization benefits.
- LDPE:Dominant feedstock for blown film extrusion, compatible with existing bubble envelope infrastructure. E-commerce fulfillment networks in India source rLDPE from domestic agricultural film recovery streams.
- PET:Highest post-consumer visibility and FDA food-contact clearance potential. German automotive parts logistics specify rPET flat envelopes for component documentation shipping.
- HDPE:Stiffness and sortation compatibility make it the logistics provider standard for automated material recovery facilities.
- Polypropylene:Durable closed-loop rental mailer applications in apparel subscription services.
LDPE dominates tonnage throughput; PET gains share fastest in brand-direct procurement.
End User:
Application maturity varies sharply, with e-commerce platforms consolidating specifications while office supplies segments lag in compliance adoption.
- E-commerce:Platform-level sustainability commitments transmit through third-party seller networks. Amazon's plastic-free packaging pledge consolidates padded mailer standards across North American and European fulfillment centers.
- Logistics:DHL and FedEx procurement teams standardize on HDPE specifications to simplify sortation at material recovery facilities. Reverse logistics packaging reuse pilots target this segment.
- Retail:Mail-order catalog operations in Germany drive compliance-driven procurement for bubble envelope grades.
- Office Supplies:Fragmented demand with slower adoption of recycled content minimums.
E-commerce commands the largest procurement volumes; logistics providers set the technical specifications others follow.
Distribution Channel:
Customer type concentration is displacing traditional distributor intermediaries as sustainability officers negotiate direct with resin producers and extrusion houses.
- Direct Sales:BMW and Volkswagen Group packaging engineering teams consolidate padded mailer contracts under centralized procurement. Bypassing distributors captures 8-12% cost savings at enterprise scale.
- Online Retail:Mid-volume merchants access lot-size-one customization through digital printing integration. Water-based inkjet systems miniaturize run-length economics previously reserved for enterprise accounts.
- Wholesale:Traditional stock-and-serve model for standardized envelope formats.
- Specialty Stores:Niche channels for premium branded mailer solutions.
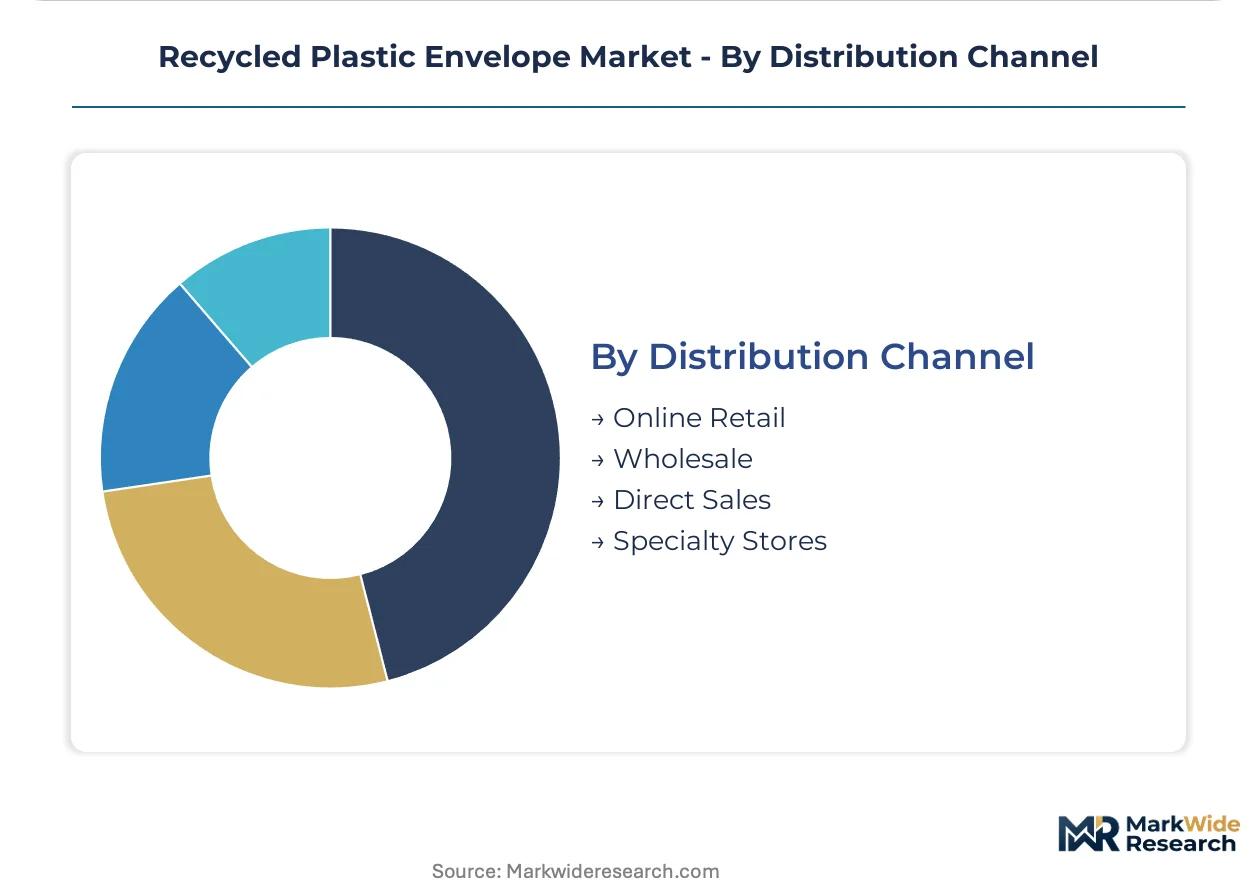
Direct sales expands most quickly; wholesale retains the broadest SKU coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb compliance premiums without volume contraction, while Indian e-commerce platforms demand price-competitive rLDPE grades that sacrifice visible recycled content ratios. This elasticity gap shapes where converters allocate capacity investments versus margin defense.
Germany
Mail-order retail density and automotive parts logistics sustain premium procurement for rPET flat envelopes. The EU Packaging and Packaging Waste Regulation enforces recyclability design standards that disqualify non-compliant adhesive systems. North Rhine-Westphalia hosts blown film extrusion clusters where converters retrofit lines for post-consumer recycled content blends.
United States
Amazon's plastic-free packaging pledge consolidates padded mailer specifications across third-party seller networks. EPA recycled content procurement guidelines shape federal supply chain requirements. Midwest manufacturing clusters face blow molding technician scarcity that delays co-extrusion die upgrades for recycled content blends.
India
Flipkart and Meesho fulfillment networks generate unmet demand for compliant padded mailers in domestic e-commerce corridors. The BIS certification framework for recycled plastics remains under development, creating interim specification uncertainty. Gujarat-based converters source rLDPE from agricultural film recovery streams to serve price-sensitive platform merchants.
France
Bakery and specialty food subscription services absorb silicone-based coating premiums to maintain single-stream recyclability claims. EU REACH substance restrictions on per- and polyfluoroalkyl substances eliminated legacy grease-resistant chemistries. The Île-de-France region anchors direct-to-brand procurement negotiations between major retailers and resin producers.
China
Cross-border e-commerce export fulfillment drives demand for lightweight shipping envelopes compatible with international postal weight bands. The MIIT circular economy action plan targets post-consumer plastic utilization rates in packaging applications. Yangtze River Delta converters balance domestic rPET collection gaps with imported feedstock dependencies.
Recycled Plastic Envelope Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in recycled plastic envelope supply. Integrated resin producers with captive recycling infrastructure command supply security advantages during post-consumer feedstock crunches. Specialist converters compete on blown film extrusion scale or flexible packaging customization. Capacity expansion and direct-to-brand procurement consolidation represent the dominant competitive moves reshaping distributor displacement.
Within the integrated tier, Amcor Plc and Berry Global Inc. exemplify divergent strategic positions—Amcor through multi-continent rPET supply chain control, Berry through blown film scale economics. UFlex Limited anchors the specialist vector as an India-based flexible packaging fabricator extending manufacturing presence into Middle Eastern e-commerce corridors. These three occupy positions that illustrate how capital intensity and geographic footprint stratify competitive advantage.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Sonoco Products Company |
| Sealed Air Corporation |
| Indorama Ventures Public Co., Ltd |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Plastipak Holdings, Inc. |
| UFlex Limited |
| Placon Corp. |
| Others |
Value Network & Pricing Analysis
Blown film extrusion scale in North Rhine-Westphalia and Gujarat determines regional price floors, with German converters absorbing EU Green Deal compliance premiums while Indian producers sacrifice visible recycled content ratios to serve price-sensitive platform merchants.
Pricing Analysis
After-sales service contracts for co-extrusion die maintenance and adhesive system validation drive lifetime value for mid-scale converters. Three-tier pricing structure across premium rPET flat envelopes, standard rLDPE bubble grades, and economy rHDPE logistics specifications prevails. Cost compression in economy tiers intensifies because Flipkart and Meesho procurement teams prioritize unit economics over certification documentation. Logistics providers exhibit lowest price sensitivity, while Indian e-commerce platform merchants demonstrate highest elasticity.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains rPET feedstock flows into German flat envelope producers, elevating inbound logistics costs during peak e-commerce seasons. Manufacturing concentrates in Germany, India, and China, with Yangtze River Delta converters drawing from imported post-consumer resin streams. Raw material dependencies center on agricultural film recovery streams, municipal collection infrastructure, and food-grade rPET flake. Single-source vulnerability to Eastern European collection gaps threatens supply security. Distribution runs through direct-to-brand procurement channels that displace traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation enforcement window compresses formulation timelines, creating a high-growth disruption as converters must pivot multilayer adhesive systems or exit.
For Market Incumbents: Shield market position through captive rPET supply chain investments and accelerated solvent-free adhesive R&D. The EU REACH substance restriction timeline threatens non-compliant producers with 8-14 month qualification delays. Backward integration into post-consumer collection infrastructure secures feedstock during Eastern European supply crunches. For New Entrants and Emerging Players: Mid-volume merchant digital printing demand represents an underserved service layer where incumbents under-serve lot-size-one customization needs. India's domestic e-commerce corridor offers lowest competitive density for rPE bubble envelope specialists. Blockchain-enabled provenance tracking provides differentiated go-to-market positioning for luxury goods shipping verticals. For Investors and Strategic Acquirers: Regional flexible packaging specialists with blown film extrusion capabilities and established BIS certification pathways present attractive acquisition targets. Long-term viability hinges on regulatory compliance infrastructure rather than commodity resin access. Watch for EU extended producer responsibility fee structure announcements as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Blown film extrusion line retrofits in Gujarat capture Flipkart fulfillment network procurement. |
| Backward Integration | Captive agricultural film recovery secures rLDPE feedstock for Indian e-commerce corridor supply. |
| Green Manufacturing Transition | Solvent-free adhesive validation aligns with EU REACH substance restriction compliance timelines. |
| Long-term Supply Agreement | Direct-to-brand contracts with BMW and Volkswagen Group packaging engineering consolidate automotive logistics. |
| Joint Venture | Blockchain provenance partnerships with luxury goods shippers enable premium pricing for verified content claims. |
Research Methodology
Cross-validation between converter production data and e-commerce platform procurement disclosures anchors the qualitative findings in this study. Primary interviews with blown film extrusion plant managers, sustainability officers at German mail-order retailers, logistics procurement leads at DHL and FedEx, and adhesive system R&D directors combined with secondary validation from EU Packaging and Packaging Waste Regulation enforcement documentation, BIS certification framework development records, and SEC filings from integrated resin producers. Bottom-up capacity assessments and top-down demand modeling from e-commerce fulfillment network expansion plans provided triangulation.
Sensitivity analysis around post-consumer recycled content ratio assumptions and adhesive reformulation cost trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-user industry, and regional regulatory cluster. CAGRs derived from capacity utilization trends and substitution elasticity parameters. Industry-specific forecast inputs encompass EU extended producer responsibility fee structure evolution and India BIS certification timeline uncertainty.
Forecasts assume regulatory continuity in EU REACH substance restrictions and EU Packaging and Packaging Waste Regulation enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Global Plastic Tarpaulin Market