
 Biofoam Packaging Market | 2026-2036
Biofoam Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Biofoam Packaging Market Outlook
REACH compliance is shifting the cost-of-entry calculus for biofoam formulations entering European commercial channels. BASF SE leverages its Ludwigshafen polymer research campus to sustain pilot-line capacity for starch-PLA copolymers. Sealed Air Corporation anchors North American food-service supply through its Cryovac insulation division, while Ecovative Design LLC differentiates via mycelium-based grow-it-local manufacturing partnerships with regional distributors.
Biofoam packaging denotes cellular-structured materials derived from renewable biomass feedstocks, typically exhibiting densities between 20–80 kg/m³ and thermal conductivity values comparable to expanded polystyrene, produced through fermentation, extrusion-expansion, or mycelial growth processes. The primary commercial purpose is protective containment and temperature-stable shipment of temperature-sensitive and fragile goods. Poly-Lactic Acid formulations currently occupy the premium tier of material type segmentation due to petrochemical price linkage and compostability certification requirements. Starch-Based grades dominate volume in emerging markets where cassava and corn feedstock costs undercut PLA by substantial margins. The cushioning application within electronics end-use commands the densest margin pools, as anti-static and precision-fit specifications justify formulation premiums.
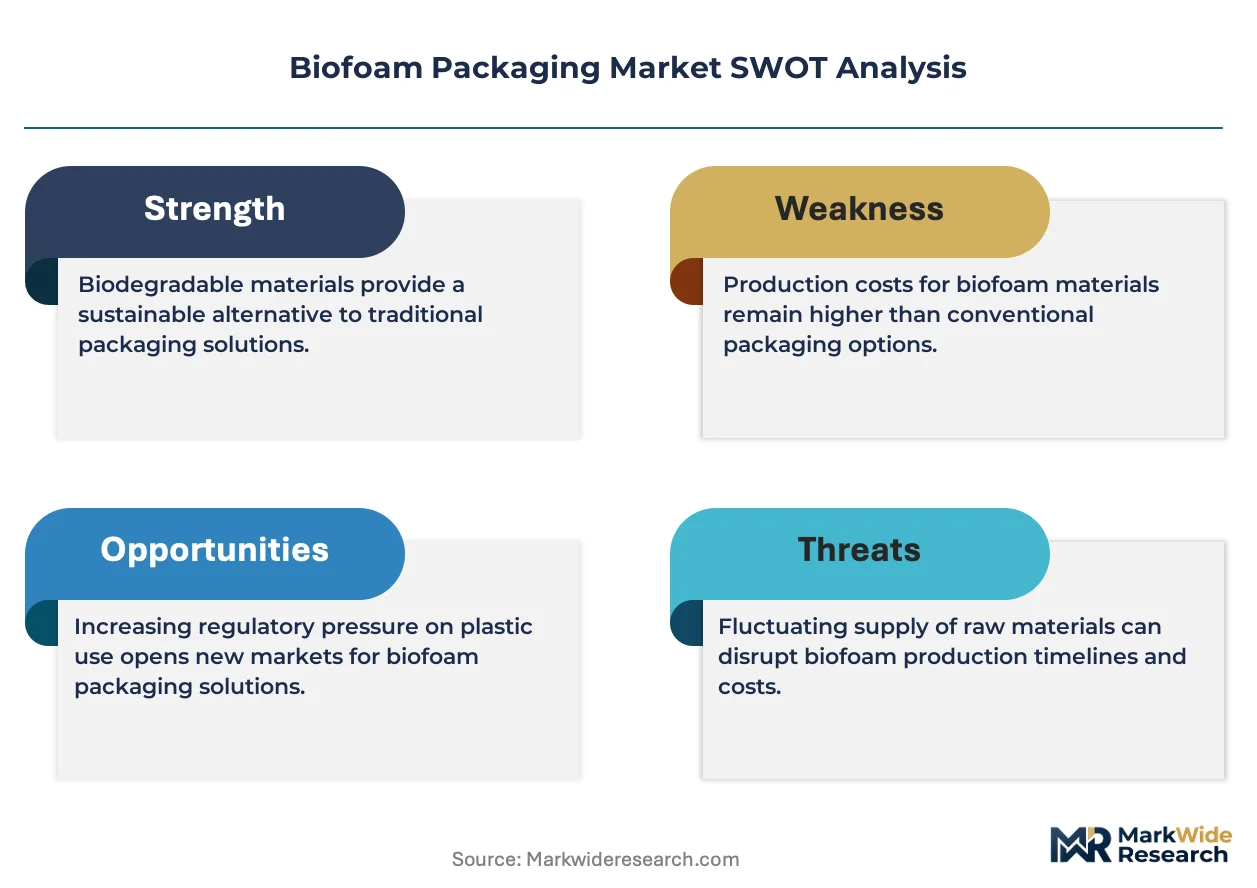
The EU Green Deal and F-Gas Regulation are tightening embodied-carbon thresholds for thermal insulation applications, directly elevating biofoam substitution economics against synthetic alternatives. FDA food-contact notifications and BIS certification requirements in India govern migration limits and additive permissibility, shaping regional product development roadmaps. Stakeholders must monitor composting infrastructure buildout rates against certification scheme proliferation to avoid stranded asset risk in materials that meet industrial but lack home-composting standards.
Market Dynamics
REACH compliance is compressing formulation freedom for petroleum-derived foams while elevating bio-based alternatives in European commercial channels. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds, forcing incumbent suppliers to reconfigure material sourcing or exit thermal insulation segments entirely.
Growth Catalysts
- EU Green Deal embodied-carbon thresholds:Thermal insulation applications face tightening F-Gas Regulation limits, directly improving biofoam substitution economics against expanded polystyrene in cold-chain logistics.
- Food service chain de-plasticization:North American quick-service restaurants are replacing petroleum-based foam containers with molded fiber and mycelium alternatives under zero-waste commitments.
- Composting infrastructure buildout:Industrial composting facility expansion in Germany and France validates premium PLA-grade certifications, reducing stranded asset risk for certified biofoam producers.
Market Restraints
- Feedstock cost volatility:Corn and cassava starch prices fluctuate with agricultural commodity cycles, compressing margin buffers for volume-grade biofoam producers in emerging markets.
- Supply concentration in PLA resin:Polymerization capacity clusters in the US Midwest and Thailand, creating geographic dependency for European compounders seeking food-contact compliant grades.
- Home-composting standard gaps:Industrial-only certification schemes limit addressable market scope, as municipal composting access remains uneven across North American metropolitan areas.
Strategic Opportunities
- Electronics anti-static cushioning:Precision-fit mycelium formats command formulation premiums in semiconductor shipping, where electrostatic discharge specifications justify dense-margin product development.
- India BIS certification pathway:Food-contact notification requirements for bio-based materials create first-mover advantage for PLA-starch copolymers meeting migration limit standards.
- Regional grow-it-local manufacturing:Distributed mycelium cultivation partnerships reduce freight costs and carbon intensity for temperature-sensitive agricultural produce packaging in peri-urban zones.
Industry Challenges
- Additive migration testing timelines:FDA food-contact notification protocols extend product launch cycles by 18-24 months for novel biofoam formulations containing processing aids.
- Extrusion-expansion technician scarcity:Fermentation-based cellular structure engineering requires specialized polymer processing expertise that outpaces current vocational training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofoam Packaging Market |
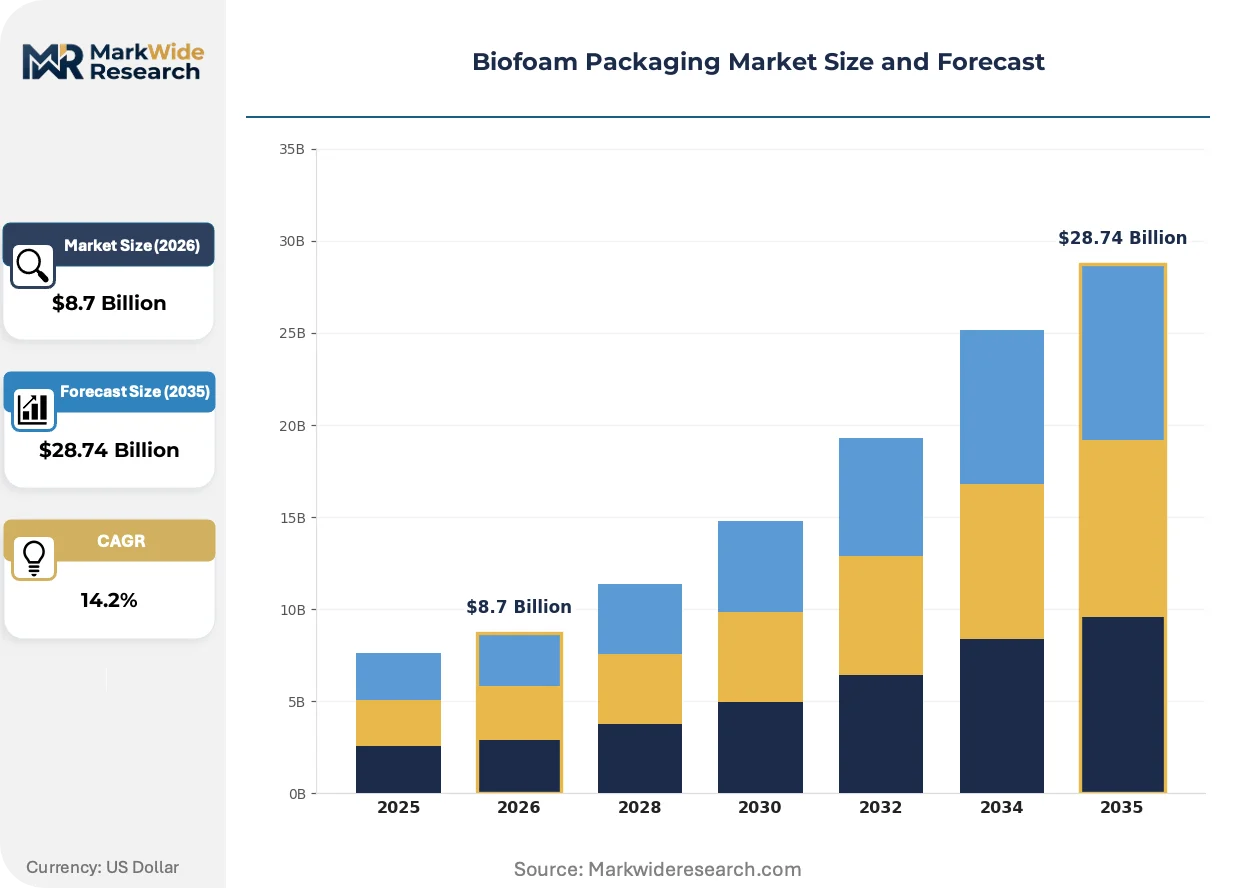
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Starch-Based, Poly-Lactic Acid, Microbial Biomass, Others End User: Food Service, Electronics, Consumer Goods, Healthcare Distribution Channel: Online Retail, Wholesale, Direct Sales, Supermarkets Application: Packaging, Insulation, Cushioning, Disposables |
| Companies Covered | BASF SE, Sealed Air Corporation, BEWi Group, NatureWorks LLC, Synbra Technology BV, Ecovative Design LLC, Stora Enso, Novamont S.p.A., Recticel Insulation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofoam Packaging Market Strategic Shifts
Mycelium-based manufacturing is disrupting conventional foam production economics through distributed cultivation models that eliminate petrochemical feedstock dependency. Three converging developments are compressing technology adoption cycles and reshaping competitive positioning.
Mycelial growth processes harness fungal biomass to generate cellular-structured packaging without thermal expansion equipment. Electronics manufacturers in the Pacific Northwest are integrating these formats into precision-fit cushioning for semiconductor shipments. This biological manufacturing pathway is electrifying regional supply chain reconfiguration, enabling short-haul distribution networks that bypass centralized resin production entirely.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents in synthetic foam insulation, elevating bio-based alternatives in cold-chain applications. Thermal conductivity parity with expanded polystyrene now satisfies pharmaceutical shipment specifications. German logistics operators are retrofitting refrigerated vehicle fleets with mycelium-PLA composite panels to preempt compliance deadlines.
Certification-driven procurement is consolidating buyer preference around dual-standard products meeting both industrial and home-composting criteria. Food service distributors in France and Belgium now require BPI and OK Compost HOME labels for thermal container contracts. This specification compression is squeezing uncertified competitors from premium channel access while rewarding early certification investment.
Biofoam Packaging Market Segmentation
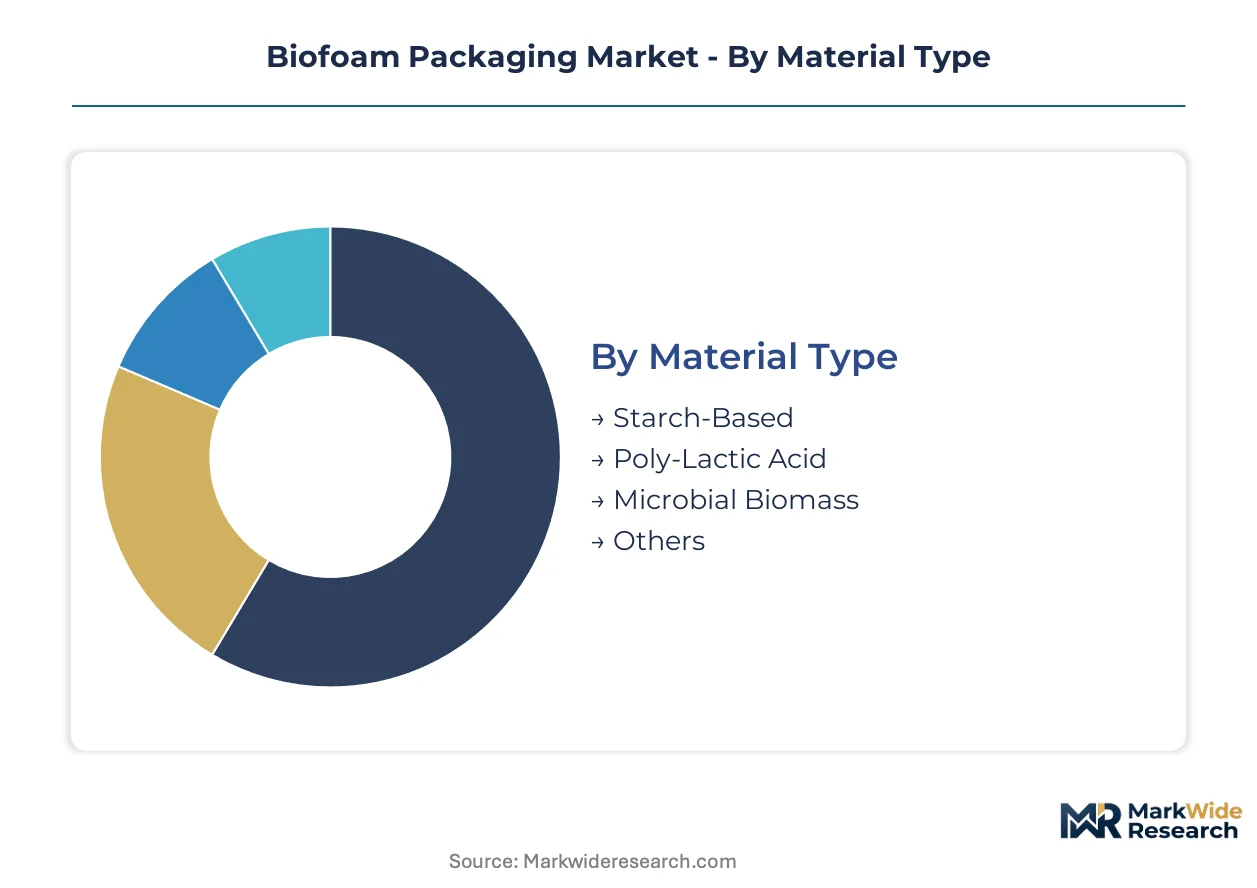
Segmentation in biofoam packaging reveals how feedstock economics, end-use performance requirements, and distribution logistics create distinct competitive arenas. Buyers prioritize thermal conductivity specifications in cold-chain applications while electronics manufacturers demand anti-static precision-fit formats.
Material Type:
Cost tier differentiation separates commodity-grade buyers from premium specification seekers.
- Starch-Based:Derived from cassava, corn, or potato feedstocks through extrusion-expansion processes. Density ranges of 20-40 kg/m³ suit lightweight protective formats. Demand concentrates in India and Southeast Asia where agricultural commodity costs undercut synthetic alternatives by substantial margins, though price volatility compresses margin buffers during drought cycles.
- Poly-Lactic Acid:Polymerized from fermented corn sugar or sugarcane dextrose, exhibiting crystalline structure and compostability certification alignment. German food-service distributors and French cold-chain operators specify PLA for EU Green Deal compliance, paying formulation premiums for industrial composting pathway validation.
- Microbial Biomass:Mycelium-based cellular structures grown through distributed cultivation without petrochemical inputs. Pacific Northwest electronics manufacturers integrate these formats for semiconductor shipping precision.
- Others:Protein-based and cellulose-derived experimental grades from academic-industry partnerships, currently pre-commercial.
Starch-Based leads volumes today; Poly-Lactic Acid is gaining share fastest.
End User:
Application-specific performance thresholds determine procurement specification intensity.
- Food Service:Quick-service restaurant chains across Germany and France mandate molded-fiber and mycelium alternatives to petroleum-based foam under zero-waste commitments. Thermal container contracts now require dual BPI and OK Compost HOME certification.
- Electronics:Anti-static and precision-fit specifications for semiconductor and server component shipping justify dense-margin formulation premiums. Electrostatic discharge protection requirements exceed standard cushioning performance thresholds.
- Consumer Goods:E-commerce fulfillment centers specify biofoam void fill for unboxing experience differentiation and returns logistics compliance.
- Healthcare:Pharmaceutical cold-chain shipments face tightening F-Gas Regulation limits on synthetic insulation, elevating biofoam substitution economics for temperature-stable vaccine distribution.
Food Service dominates current procurement volumes; Electronics shows the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and certification verification needs.
- Online Retail:Small-batch specialty biofoam formats for artisan food producers and boutique electronics manufacturers. Certification documentation and technical datasheets accompany digital procurement workflows.
- Wholesale:Volume-grade starch-based and PLA formats distributed through industrial packaging distributors serving regional manufacturing clusters.
- Direct Sales:Large food-service chains and electronics OEMs negotiate multi-year supply agreements with compounders for customized formulation development and locked pricing.
- Supermarkets:Consumer-facing protective formats for fragile produce and premium grocery items, typically starch-based loose fill or molded trays.
Wholesale channels move the greatest tonnage; Direct Sales contracts are climbing the fastest.
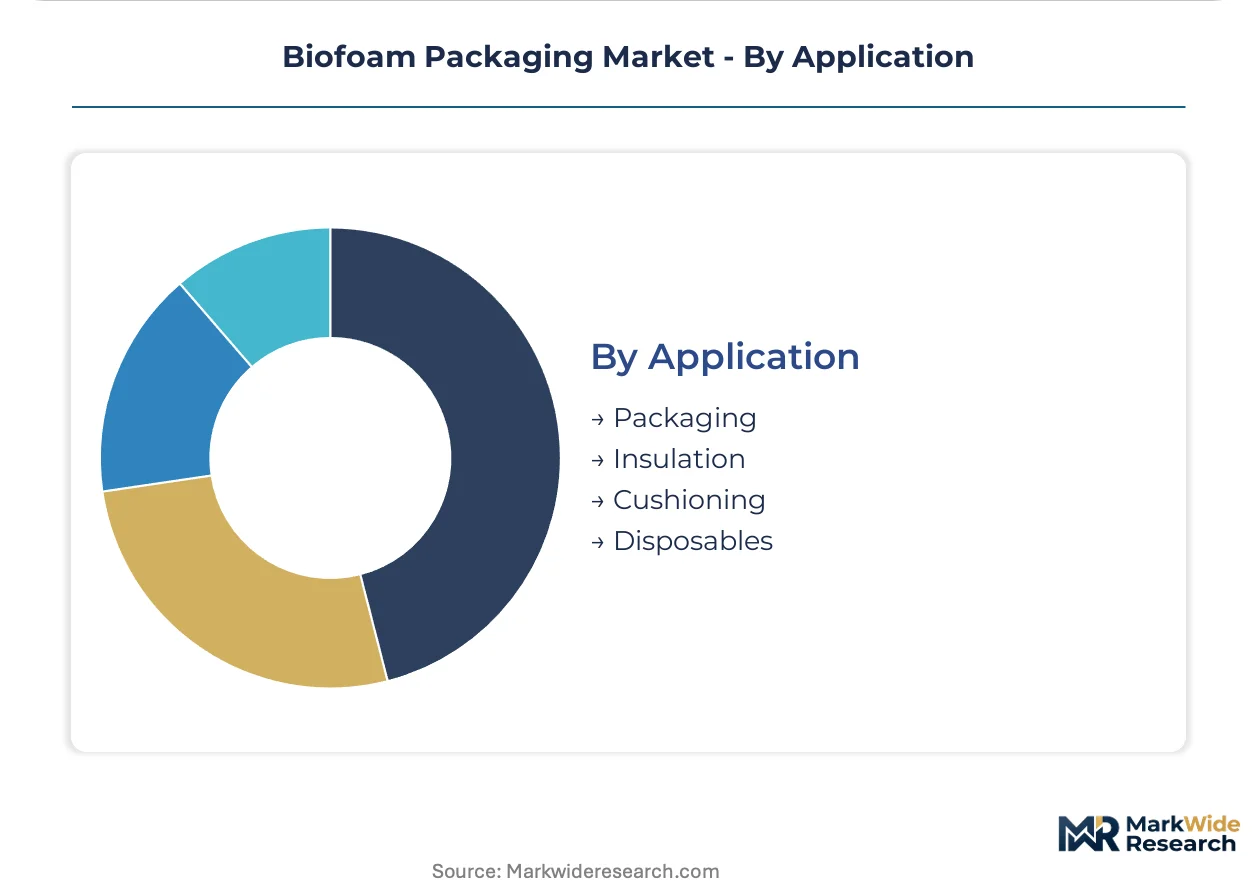
Application:
Functional performance requirements and regulatory exposure vary sharply across use cases.
- Packaging:Primary containment formats for food, electronics, and consumer goods. REACH compliance and FDA food-contact notifications govern additive permissibility and migration limits.
- Insulation:Thermal barrier applications in refrigerated vehicles and pharmaceutical shipments. German logistics operators retrofit fleets with mycelium-PLA composite panels to preempt F-Gas Regulation phase-down deadlines.
- Cushioning:Impact protection for fragile goods during transit. Precision-fit mycelium formats command formulation premiums where dimensional accuracy prevents damage.
- Disposables:Single-use food-service containers and utensils subject to extended producer responsibility schemes under EU Packaging and Packaging Waste Regulation.
Packaging applications absorb the most material today; Insulation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial biofoam production first achieved scale in Germany during the early 2000s, when BASF SE piloted polylactic acid polymerization at its Ludwigshafen campus. That German foundation established the technical and regulatory template now diffusing across industrialized markets.
Germany
Food-service distributors and cold-chain operators specify PLA grades for EU Green Deal compliance, paying premiums for industrial composting certification. REACH and the EU Packaging and Packaging Waste Regulation mandate minimum recycled content thresholds, forcing reformulation of legacy petroleum-based foams. The Ludwigshafen polymer research campus anchors starch-PLA copolymer pilot capacity, while Berlin-Brandenburg logistics operators retrofit refrigerated fleets with mycelium-PLA composite panels.
United States
Quick-service restaurant chains across the Pacific Northwest and Northeast Corridor are replacing petroleum-based foam containers with molded fiber alternatives under zero-waste commitments. FDA food-contact notification protocols govern migration limits and additive permissibility for novel biofoam formulations. Sealed Air Corporation anchors North American food-service supply through its Cryovac insulation division, with Ecovative Design operating grow-it-local manufacturing partnerships in regional distribution zones.
France
Industrial composting facility expansion in the Île-de-France and Auvergne-Rhône-Alpes regions validates premium PLA-grade certifications, reducing stranded asset risk for certified producers. The EU F-Gas Regulation phases down hydrofluorocarbon blowing agents, elevating bio-based alternatives in pharmaceutical cold-chain shipments. Food service distributors in Paris and Lyon now require dual BPI and OK Compost HOME labels for thermal container contracts.
India
Cassava and corn starch feedstock costs undercut PLA by substantial margins in Maharashtra and Gujarat, where agricultural commodity volatility compresses margin buffers during drought cycles. BIS certification requirements for food-contact bio-based materials create first-mover advantage for PLA-starch copolymers meeting migration limit standards. The Delhi-NCR logistics corridor is emerging as a testbed for starch-based protective packaging in e-commerce fulfillment.
Thailand
Sugarcane dextrose feedstock availability supports fermentation-based PLA resin polymerization capacity serving compounders across Southeast Asia. The country's national industrial standards regulator is aligning certification schemes with EU industrial composting protocols to facilitate export market access. Bangkok and surrounding industrial zones concentrate extrusion-expansion equipment for volume-grade starch-based formats bound for regional consumer goods markets.
Biofoam Packaging Market Competitive Environment
The competitive structure tilts toward integrated petrochemical incumbents repurposing polymer research infrastructure for bio-based transitions. Three archetypes dominate: diversified chemical conglomerates with captive PLA polymerization capacity, specialized insulation and protective packaging manufacturers, and mycelium-based biological manufacturing startups. Capacity expansion and strategic partnerships constitute the primary competitive moves, with distributed cultivation licensing displacing centralized resin production economics in select regional markets.
Among diversified chemical conglomerates, BASF SE exemplifies the integrated archetype leveraging polymer research campuses for starch-PLA copolymer development. Sealed Air Corporation occupies a position on the protective packaging vector, anchoring North American food-service supply chain relationships. Ecovative Design LLC represents the biological manufacturing archetype, situating grow-it-local partnerships as an alternative to petrochemical feedstock dependency.
| Leading Market Players |
|---|
| BASF SE |
| Sealed Air Corporation |
| BEWi Group |
| NatureWorks LLC |
| Synbra Technology BV |
| Ecovative Design LLC |
| Stora Enso |
| Novamont S.p.A. |
| Recticel Insulation |
| Others |
Value Chain & Pricing Dynamics
Captive PLA polymerization capacity in the US Midwest and Thailand anchors supply positions and pricing power for European compounders seeking food-contact compliant grades. This geographic concentration forces buyers into long-term offtake negotiations or premium spot-market sourcing, compressing margin buffers for uncertified volume-grade producers.
Pricing Analysis
Certification-bundled service splits dominate procurement contracts, with industrial composting pathway validation and dual BPI-OK Compost HOME labels commanding substantial premiums over uncertified alternatives. Price differentiation rests on feedstock origin and thermal conductivity performance tiers, with pharmaceutical cold-chain specifications justifying dense-margin formulation premiums. Cost compression in starch-based grades is intensifying because agricultural commodity volatility in India and Southeast Asia erodes producer margins during drought cycles. Quick-service restaurant chains exhibit highest price sensitivity, while electronics OEMs prioritize anti-static precision-fit performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German food-service distributors and Pacific Northwest electronics manufacturers, bypassing wholesale markups for customized formulation development. Supply concentrates in Thailand for sugarcane dextrose fermentation, the US Midwest for PLA resin polymerization, and Germany for starch-PLA copolymer compounding. Raw material dependencies include cassava and corn starch, fermented sugarcane dextrose, and mycelial biomass substrates. Single-source vulnerability in PLA resin creates structural risk for European compounders lacking backward integration into fermentation capacity. Distribution runs through industrial packaging distributors serving regional manufacturing clusters, with grow-it-local mycelium partnerships emerging in peri-urban zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biofoam packaging market functions as a stable compounder, with EU Green Deal embodied-carbon thresholds and F-Gas Regulation compliance deadlines generating predictable substitution demand against petroleum-based foams.
For Market Incumbents: Extend certification coverage to capture dual-standard procurement requirements before specification compression squeezes uncertified competitors from premium channels. BASF SE and Sealed Air Corporation should accelerate starch-PLA copolymer pilot capacity at Ludwigshafen and Cryovac insulation divisions respectively, defending against mycelium-based biological manufacturing entrants through captive polymer research infrastructure. For New Entrants and Emerging Players: Mycelium-based precision-fit formats offer a technology-first wedge into semiconductor shipping applications where electrostatic discharge specifications justify formulation premiums. Target India's BIS certification pathway for PLA-starch copolymers meeting migration limit standards, leveraging first-mover advantage before regulatory harmonization closes the window. Deploy grow-it-local manufacturing partnerships in peri-urban agricultural zones to reduce freight costs and carbon intensity for temperature-sensitive produce packaging. For Investors and Strategic Acquirers: Roll-up economics work for regional mycelium cultivation specialists because distributed manufacturing partnerships bypass centralized resin production capital intensity entirely. Long-term viability centers on composting infrastructure buildout rates validating certification scheme proliferation. Target acquisition archetypes include industrial composting facility operators and extrusion-expansion equipment fabricators facing technician scarcity. The signal to watch is municipal composting access expansion across North American metropolitan areas closing home-composting standard gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive sugarcane dextrose supply from Thai feedstock secures PLA resin polymerization for European compounders. |
| Dual Certification Investment | Simultaneous BPI and OK Compost HOME validation opens French and Belgian food-service distributor contracts. |
| Regional Grow-it-Local Partnerships | Distributed mycelium cultivation in Pacific Northwest peri-urban zones reduces pharmaceutical cold-chain freight carbon intensity. |
| Anti-Static Formulation Development | Precision-fit mycelium formats meeting electrostatic discharge specifications penetrate semiconductor shipping margin pools. |
| Long-term Supply Agreement with Quick-Service Chains | Locked pricing contracts with North American zero-waste commitment restaurants de-risk agricultural commodity volatility exposure. |
Study Parameters
Multiple input streams — technical R&D directors at polymer research campuses, procurement leads at German food-service distributors, plant managers at Thai fermentation facilities, and channel partners in industrial packaging distribution — were reconciled against secondary validation from ECHA REACH registration databases, EU Packaging and Packaging Waste Regulation compliance filings, and customs trade data tracking starch and PLA resin flows. Bottom-up capacity and demand modeling was cross-referenced with top-down macroeconomic drivers across the analysis window.
Historical capacity utilization rates and forward panel input from compounders and end-users were cross-referenced to anchor projection trajectories. Segmentation dimensions modeled include material type tier, end-use application performance requirements, distribution channel structure, and regional regulatory cluster alignment. CAGRs were derived from reconciled volume and value outputs across the modeling period. Industry-specific forecast inputs encompassed composting facility buildout timelines and F-Gas Regulation phase-down compliance deadlines.
The model holds under stable EU Green Deal implementation and REACH enforcement intensity; deviation in agricultural commodity price volatility or home-composting infrastructure deployment would shift substitution economics and certification value premiums. Forecasts reflect documented assumptions regarding polymerization capacity expansion and regulatory harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market