
 Global Bioplastic Multi-Layer Films Market | 2026-2036
Global Bioplastic Multi-Layer Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioplastic Multi-Layer Films Market Foresight
Food retailer procurement channels is rewriting sourcing standards for sustainable packaging across European and Asian supply chains. BASF SE leverages its polymer science heritage to anchor high-barrier film formulations for perishable goods. NatureWorks LLC sustains feedstock security through integrated corn-based PLA production in Nebraska. Novamont S.p.A. dominates Italian retail channels with Mater-Bi certified compostable multi-layer structures.
Global bioplastic multi-layer films consist of laminated or co-extruded structures combining PLA, PHA, or starch-derived polymers with barrier layers of ethylene vinyl alcohol or metallized substrates, achieving oxygen transmission rates below 1 cc/m²/day for shelf-life extension in sensitive applications. Polylactic acid occupies the largest product position due to mature resin availability and FDA food-contact clearance, while polyhydroxyalkanoates represent the fastest-expanding segment driven by marine biodegradability certifications. Co-extrusion technology leads processing methods for multi-layer precision, though blown film lines are capturing share in Asian contract manufacturing for agricultural mulch films.
The European Chemicals Agency enforces REACH substance restrictions on petroleum-derived additives migrating into food-contact layers, while the EU Green Deal mandates recycled and bio-based content thresholds that reshape film layer specifications. FDA maintains food-contact notification requirements for novel biopolymer adhesives between layers, creating compliance lead times for non-US formulations. Stakeholders must monitor evolving compostability certification divergence between BPI, TÜV Austria, and home-composting standards before committing capital to regional production assets.
Market Dynamics
REACH substance restrictions on petroleum-derived additives are forcing resin formulators to redesign entire lamination chemistries, while EU Green Deal bio-based content mandates are compressing qualification timelines for new multi-layer structures.
Growth Catalysts
- EU Green Deal bio-based thresholds:Mandatory recycled and bio-based content requirements are accelerating film layer substitutions across German and Italian retail supply chains.
- Extended producer responsibility frameworks:EU member state EPR schemes are creating direct financial incentives for compostable multi-layer adoption in food packaging applications.
- Marine biodegradability certifications:PHA-based barrier films are capturing demand from seafood exporters facing port-state plastic waste regulations.
Market Restraints
- Feedstock price volatility:Corn and sugarcane resin feedstocks expose PLA producers to agricultural commodity swings that petroleum-based films do not face.
- Barrier layer supply concentration:Ethylene vinyl alcohol and metallized substrate production concentrates in Northeast Asian chemical conglomerates, creating import dependency for European converters.
- Composting infrastructure gaps:Industrial composting facility shortages in Eastern European markets limit addressable demand regardless of film certification status.
Strategic Opportunities
- Agricultural mulch film conversion:Japanese prefectural governments are piloting PHA-based multi-layer films for soil-biodegradable crop protection, opening a volume channel beyond food packaging.
- Home-composting certification divergence:TÜV Austria OK Compost HOME differentiation creates premium positioning for e-commerce direct-to-consumer brands in German-speaking markets.
- Blown film line technology:Asian contract manufacturers are capturing agricultural film share through capital-light processing methods that bypass European co-extrusion equipment bottlenecks.
Industry Challenges
- Interlayer adhesion chemistry:Novel biopolymer adhesives between barrier and structural layers trigger FDA food-contact notification delays that extend product launch timelines by 18-24 months.
- Certification standard fragmentation:BPI industrial composting, TÜV Austria home-composting, and emerging soil-biodegradable standards require parallel testing investments before regional market entry.
- Multi-layer delamination for recycling:Current mechanical recycling infrastructure cannot separate bonded bioplastic layers, forcing reliance on nascent chemical recycling partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioplastic Multi-Layer Films Market |
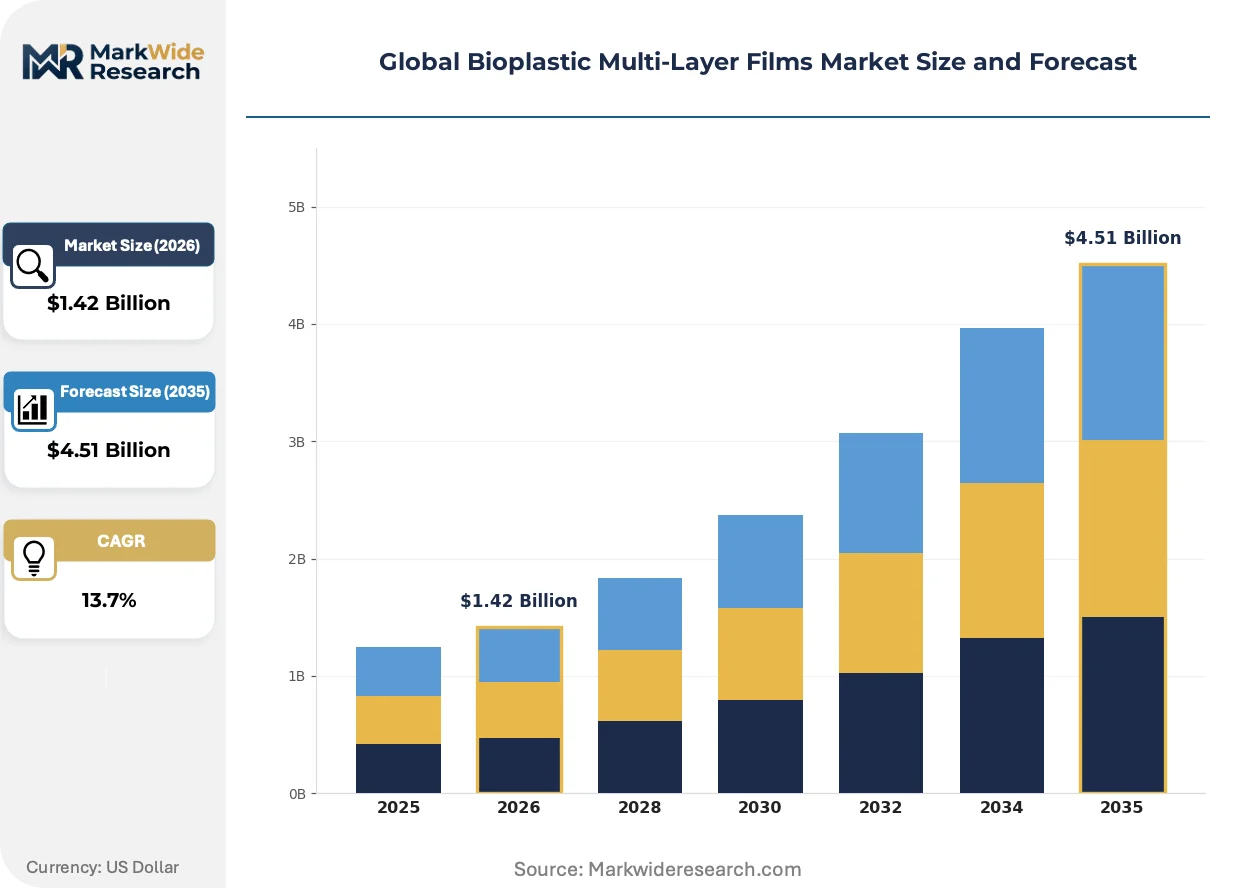
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polylactic Acid, Polyhydroxyalkanoates, Starch Blends, Cellulose-Based, Polybutylene Succinate Application: Food Packaging, Pharmaceutical Wrapping, Agriculture Films, Cosmetic Packaging, Electronics Protection End User Industry: Food & Beverage, Pharmaceuticals, Agriculture, Personal Care, Electronics Manufacturing Processing Technology: Co-extrusion, Lamination, Coating, Blown Film, Cast Film |
| Companies Covered | BASF SE, NatureWorks LLC, Novamont S.p.A., FKuR Kunststoff GmbH, Biome Bioplastics Limited, Cortec Corporation, Kingfa Sci. & Tech. Co., Ltd., Futamura Chemicals Co., Ltd., BioBag Americas, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioplastic Multi-Layer Films Market Shifts & Advancements
Active barrier technologies and certification-driven procurement specifications are compressing traditional film development cycles while opening new performance tiers in perishable goods protection.
Metallized biopolymer substrates are collapsing the performance gap between conventional aluminum-foil laminates and compostable alternatives. German organic food retailers are specifying these structures for coffee and dried fruit applications where oxygen transmission requirements previously excluded bio-based options. The technology is collapsing legacy twelve-to-eighteen-month shelf-life extension contracts into six-month renewable agreements tied to batch-level compostability certification.
REACH substance restrictions on petroleum-derived additives are triggering wholesale adhesive reformulation across European converter networks. The European Chemicals Agency enforcement timeline is compressing qualification windows for existing multi-layer food-contact products. Italian packaging converters are responding with accelerated biopolymer adhesive development partnerships to maintain EU market access.
Retailer-led sustainable packaging scorecards are displacing brand-driven material specifications in European fresh produce supply chains. German and Dutch supermarket chains are consolidating purchasing through centralized technical teams that mandate BPI or TÜV Austria certification as a gatekeeping criterion. This concentration is most visible in prepared salad and ready-to-eat fruit categories where private-label penetration exceeds sixty percent.
Global Bioplastic Multi-Layer Films Market Segmentation
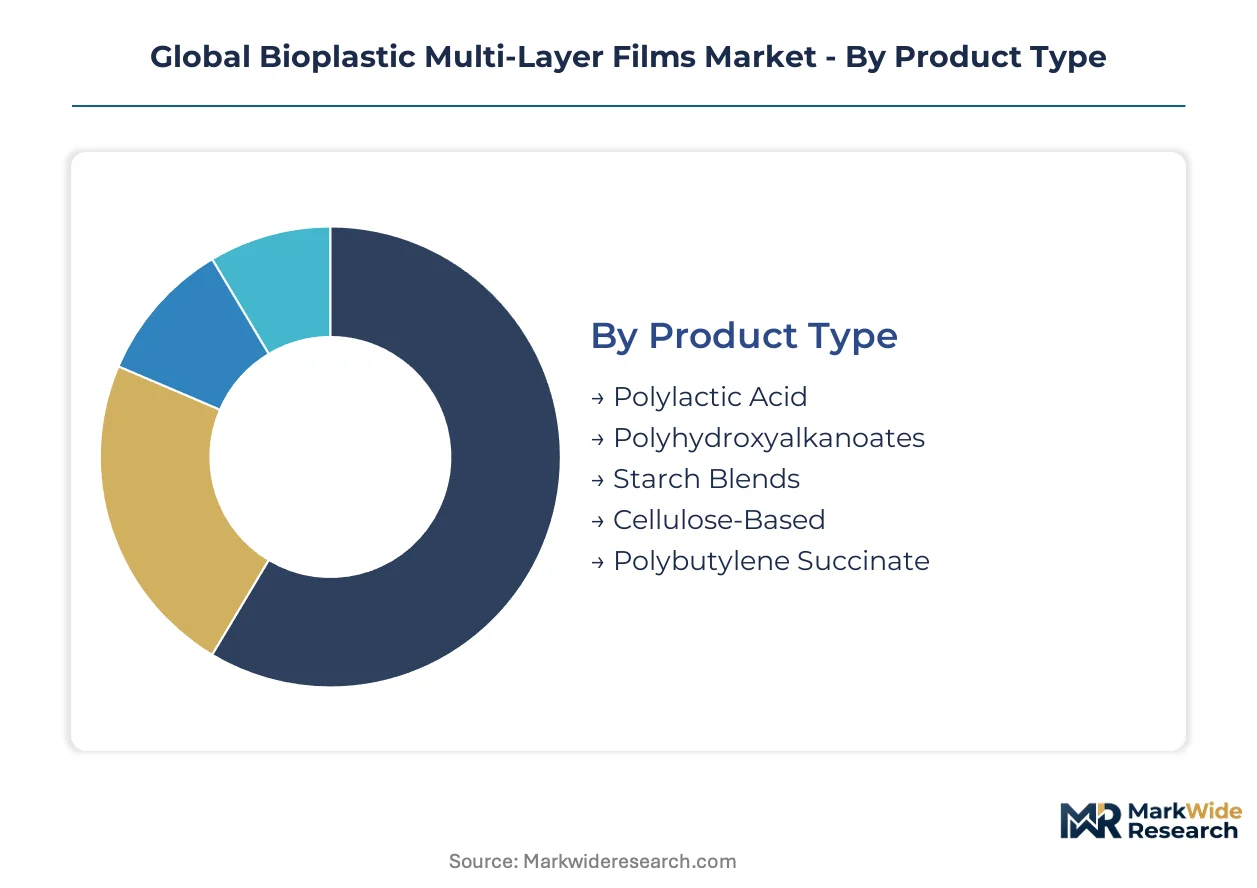
Bioplastic multi-layer films fragment across resin chemistry, end-use performance requirements, and processing infrastructure compatibility. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape capital allocation decisions for converters and brand owners.
Product Type:
Resin chemistry determines barrier performance, compostability certification pathways, and feedstock cost structure for multi-layer constructions.
- Polylactic Acid:Corn-derived aliphatic polyester delivers clarity and heat-seal integrity for food-contact layers. German and Italian retailers specify PLA-dominant structures for fresh produce packaging under EU Green Deal bio-based thresholds. FDA food-contact clearance and mature Nebraska-based resin supply chains anchor volume leadership despite agricultural commodity price swings.
- Polyhydroxyalkanoates:Bacterial fermentation polymers achieve marine biodegradability certifications that PLA cannot match. Japanese seafood exporters and coastal agriculture applications in Mediterranean markets drive qualification investments. TÜV Austria OK Compost HOME certification creates premium positioning for direct-to-consumer channels.
- Starch Blends:Thermoplastic starch formulations reduce material costs in non-barrier structural layers. Italian converters integrate Mater-Bi certified grades into certified compostable multi-layer stacks.
- Cellulose-Based:Regenerated cellulose films provide grease resistance and dead-fold characteristics for confectionery wrapping. Japanese pharmaceutical blister packs specify cellulose barrier substrates.
- Polybutylene Succinate:Bio-based succinic acid polymers bridge performance gaps between PLA flexibility and PHA biodegradation rates. South Korean agricultural mulch film trials incorporate PBS tie layers.
Polylactic Acid commands the established base. The steepest expansion runs through Polyhydroxyalkanoates.
Application:
End-use performance specifications dictate barrier layer complexity, shelf-life targets, and composting infrastructure requirements.
- Food Packaging:Oxygen transmission rates below 1 cc/m²/day protect perishables through metallized biopolymer substrates or ethylene vinyl alcohol coextrusion. German organic food retailers specify these structures for coffee and dried fruit applications. EPR frameworks in EU member states create direct financial incentives for compostable multi-layer adoption.
- Pharmaceutical Wrapping:Moisture vapor transmission and light-blocking requirements exceed standard food-contact specifications. Cellulose-based barrier layers with metallized substrates satisfy Japanese PMDA stability testing protocols.
- Agriculture Films:Soil-biodegradable multi-layer mulch films require UV stabilization and controlled mechanical degradation timelines. Japanese prefectural government pilots for PHA-based crop protection open volume channels beyond food packaging.
- Cosmetic Packaging:Aesthetic clarity and fragrance barrier demands favor co-extruded PLA structures with ethylene vinyl oxygen barriers. German-speaking premium brands specify TÜV Austria home-composting certification.
- Electronics Protection:Anti-static and moisture barrier specifications drive lamination of cellulose substrates with vapor-deposited coatings. South Korean electronics contract manufacturers qualify bio-based alternatives for EU-bound product shipments.
Food Packaging anchors current volume. Agriculture Films are climbing the fastest as soil-biodegradable standards mature.
End User Industry:
Customer procurement sophistication ranges from centralized technical teams with mandatory certification gates to fragmented price-sensitive buyers.
- Food & Beverage:Retailer-led sustainable packaging scorecards displace brand-driven specifications in European fresh produce supply chains. German and Dutch supermarket chains mandate BPI or TÜV Austria certification as gatekeeping criteria.
- Pharmaceuticals:Stability validation timelines and regulatory filing requirements extend qualification cycles. FDA food-contact notification delays for novel biopolymer adhesives stretch product launches.
- Agriculture:Government subsidy programs and soil-biodegradable certification requirements reshape procurement in Japan and Mediterranean markets.
- Personal Care:Premium positioning strategies leverage home-composting certification differentiation for German-speaking direct-to-consumer brands.
- Electronics Manufacturing:Supply chain sustainability scorecards from EU-bound OEMs drive bio-based packaging qualification for South Korean and Japanese component suppliers.
Food & Beverage holds the revenue concentration. Pharmaceuticals present the longest conversion timelines.
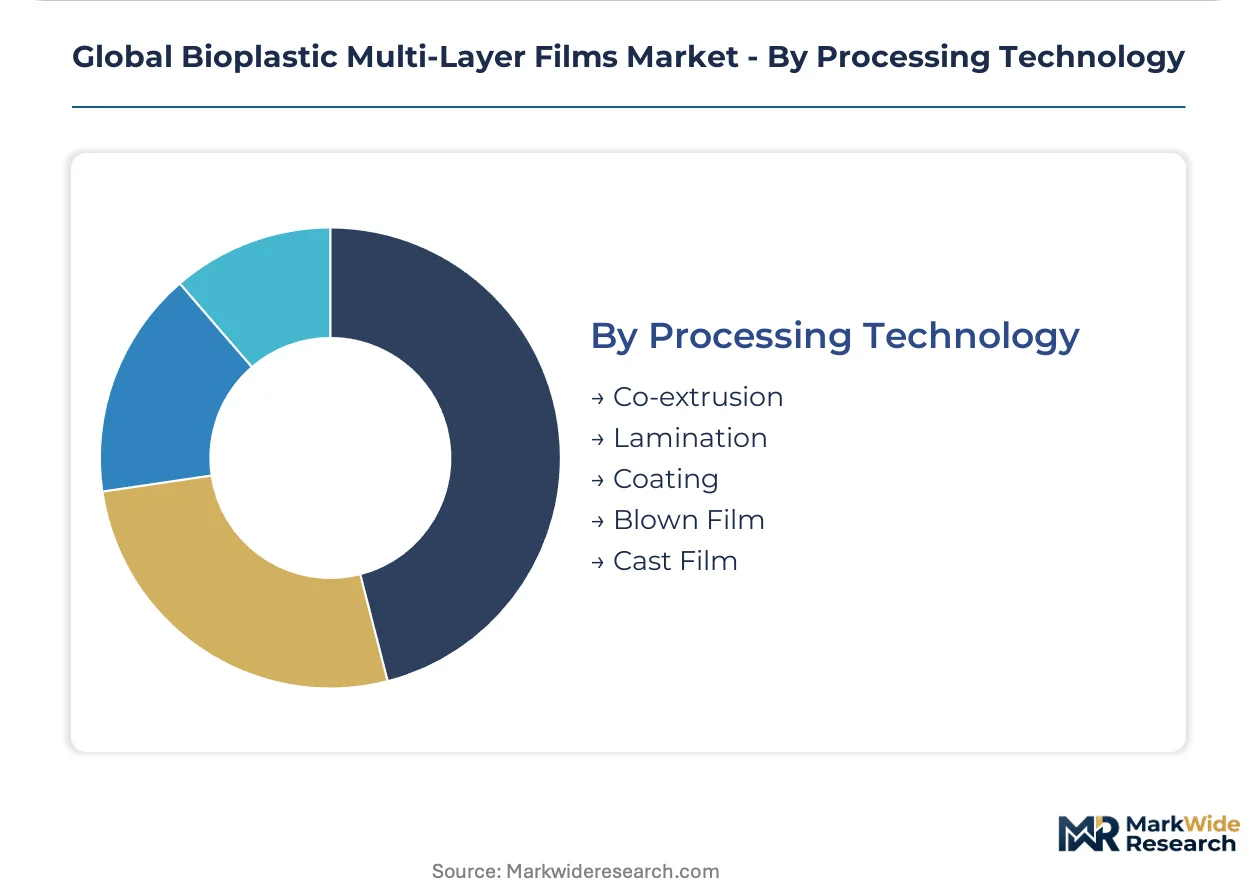
Processing Technology:
Equipment capital intensity and layer precision requirements create regional specialization patterns across converter networks.
- Co-extrusion:Multi-layer precision with five to eleven discrete layers achieves oxygen barrier performance for sensitive perishables. European converters dominate this capital-intensive segment with equipment bottlenecks limiting new entrant capacity.
- Blown Film:Lower capital requirements and agricultural film thickness tolerances enable Asian contract manufacturing expansion. Chinese and Southeast Asian producers capture share in mulch film applications through capital-light processing.
- Lamination:Adhesive bonding of pre-formed webs allows rapid formulation changes for short-run specialty applications. REACH substance restrictions on petroleum-derived adhesives trigger wholesale chemistry redesigns across European converter networks.
- Coating:Vapor-deposited or solution-coated barrier layers on biopolymer substrates collapse performance gaps with aluminum foil laminates. German organic food retailers specify metallized biopolymer coatings for coffee packaging.
- Cast Film:Flat die extrusion delivers superior optical clarity and gauge uniformity for cosmetic and pharmaceutical visibility requirements. Japanese pharmaceutical blister pack producers favor cast cellulose substrates.
Co-extrusion retains the precision-critical applications. Blown Film is gaining share fastest in Asian agricultural film manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command pricing premiums through REACH-compliant formulations, while Chinese blown-film manufacturers undercut on agricultural mulch volumes. This asymmetry concentrates high-margin food packaging in Western Europe and commodity film production in East Asia.
Germany
Organic food retailers in Berlin and Munich mandate TÜV Austria OK Compost HOME certification for private-label packaging. The EU Green Deal bio-based thresholds compress qualification timelines for converters in the Rhine-Ruhr industrial belt. BASF SE anchors high-barrier film development in Ludwigshafen, supplying metallized biopolymer substrates to coffee packagers nationwide.
Italy
Novamont S.p.A. dominates retail channels through Mater-Bi certified compostable structures for fresh produce. Extended producer responsibility frameworks in Lombardy and Emilia-Romagna create direct financial incentives for multi-layer adoption. Converter clusters in Bologna and Milan accelerate biopolymer adhesive partnerships to maintain EU market access under REACH substance restrictions.
Japan
Seafood exporters in Tokyo and Osaka drive PHA-based barrier film demand facing port-state plastic waste regulations. Prefectural governments in Shizuoka and Hokkaido pilot soil-biodegradable multi-layer mulch films for crop protection. Futamura Chemicals Co., Ltd. supplies cellulose-based barrier substrates to pharmaceutical blister pack producers in the Kanto region.
United States
FDA food-contact notification requirements delay novel biopolymer adhesive launches by 18-24 months for Nebraska-based PLA producers. NatureWorks LLC sustains feedstock security through integrated corn-based resin production. California and New York procurement teams specify BPI certification for state-contracted food service packaging, creating coastal demand concentration.
China
Blown-film lines in Zhejiang and Jiangsu provinces capture agricultural film share through capital-light processing methods. Kingfa Sci. & Tech. Co., Ltd. exemplifies scale-driven manufacturing for domestic mulch applications. Import dependency for ethylene vinyl alcohol barrier layers concentrates Northeast Asian chemical supply chains around Shanghai port logistics.
Global Bioplastic Multi-Layer Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on resin and barrier substrate supply. The vendor base organizes around three strategic archetypes: integrated polymer science platforms, regional compostable film converters, and agricultural mulch specialists. Consolidation pressures concentrate among European REACH-compliant formulators, while Asian contract manufacturers expand through equipment-light blown-film technology. Dominant competitive moves include backward integration into resin production and certification-driven geographic expansion.
Within the integrated polymer science tier, BASF SE and NatureWorks LLC exemplify platform-scale players with captive feedstock control. Novamont S.p.A. occupies a distinctive position among Italian compostable film specialists, leveraging Mater-Bi certification dominance in Mediterranean retail channels. Kingfa Sci. & Tech. Co., Ltd. represents the scale-driven Asian manufacturing archetype, while FKuR Kunststoff GmbH and Biome Bioplastics Limited sit within the European converter specialization cluster focused on REACH-compliant formulations.
| Leading Market Players |
|---|
| BASF SE |
| NatureWorks LLC |
| Novamont S.p.A. |
| FKuR Kunststoff GmbH |
| Biome Bioplastics Limited |
| Cortec Corporation |
| Kingfa Sci. & Tech. Co., Ltd. |
| Futamura Chemicals Co., Ltd. |
| BioBag Americas, Inc. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit agricultural commodity volatility directly into PLA resin cost structures, amplifying price spreads between standard grades and REACH-certified custom formulations while concentrating negotiating leverage among German retail procurement teams.
Pricing Analysis
Configured-to-order premiums for TÜV Austria OK Compost HOME certification run 15-25 percent above standard BPI-industrial grades, with price differentiation anchored in certification tier and volume scale. Three-tier pricing structure across premium, standard, and economy levels is hardening as EPR frameworks in EU member states create direct cost pass-through mechanisms for compostable films. Pricing pressure stems from corn and sugarcane feedstock swings that petroleum-based competitors do not face. Agricultural mulch film buyers in Asian contract manufacturing channels exhibit highest price sensitivity, while German organic food retailers absorb premium tiers with minimal volume elasticity.
Supply Chain Analysis
Blown-film contract manufacturers in Zhejiang and Jiangsu provinces hold expanding capacity for commodity agricultural applications, while European co-extrusion specialists dominate precision food-contact layer production. Supply concentrates in China for ethylene vinyl alcohol barrier substrates, Nebraska for NatureWorks PLA resin, and Italy for Novamont starch-blend formulations. Raw material dependencies center on corn-derived lactic acid, bio-based succinic acid, and metallized biopolymer substrates. Single-source vulnerability concentrates in Northeast Asian EVOH production. Distribution runs through converter-direct relationships for European food packaging and distributor networks for Asian agricultural film.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through German and Dutch supermarket chain procurement consolidation, with centralized technical teams now mandating certification gates that displace fragmented brand-driven specifications.
For Market Incumbents: Pre-empt REACH substance restriction enforcement by accelerating biopolymer adhesive qualification partnerships before European Chemicals Agency timelines compress. Secure backward integration into Nebraska or Italian feedstock supply to defend margin position against agricultural commodity swings. Channel control through direct retailer scorecard relationships offers defensive moats against Asian blown-film entrants. For New Entrants and Emerging Players: Build out soil-biodegradable mulch film capacity targeting Japanese prefectural subsidy programs and Mediterranean government pilot schemes where certification barriers remain lower than food-contact applications. Agricultural film segments present the most penetrable white-space given capital-light blown-film processing and limited incumbent REACH compliance overhead. Go-to-market positioning through regional distributor partnerships bypasses European retailer gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded bioplastic film assets lacking certification investment discipline. Long-term viability hinges on composting infrastructure buildout pace across Eastern European markets. Signal to monitor: industrial composting facility permitting velocity in Poland and Romania as inflection indicator for addressable demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive corn-based lactic acid production insulates NatureWorks from agricultural commodity volatility. |
| Certification-Driven Geographic Expansion | TÜV Austria OK Compost HOME positioning unlocks premium pricing in German-speaking direct-to-consumer channels. |
| Co-Extrusion Capacity Addition | Five-to-eleven layer precision equipment bottlenecks protect European converters from Asian blown-film competition. |
| Biopolymer Adhesive Partnership | Italian converters accelerate reformulation to maintain EU market access under REACH substance restrictions. |
| Agricultural Film Joint Venture | Japanese prefectural pilots for PHA-based mulch films open volume channels beyond food packaging saturation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of European Chemicals Agency enforcement timelines, EU Green Deal bio-based threshold documentation, and BPI certification databases. Conversations with resin procurement managers at German retailers, technical directors at Italian converter clusters, and sustainability officers at Japanese seafood exporters informed demand-side validation. Secondary sources included customs trade data for ethylene vinyl alcohol imports, SEC filings from integrated polymer science platforms, and TÜV Austria certification registries. Bottom-up resin consumption estimates and top-down packaging spend allocations were triangulated to anchor volume figures.
Forecast inputs span resin chemistry segmentation, processing technology equipment intensity, and composting infrastructure penetration by member state. Modeled dimensions include product type, application performance requirements, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and substitution rate assumptions across the analysis window. Industry-specific inputs incorporated REACH substance restriction phase-in schedules and EPR framework financial incentive structures.
Stress conditions across corn futures volatility, EVOH import tariff exposure, and industrial composting facility buildout delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on certification standard convergence and retailer procurement centralization trajectories. Quarterly review of ECHA enforcement actions, prefectural subsidy program approvals in Japan, and BPI-TÜV certification divergence trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Global Biodegradable Tableware Market