
 Tray Forming Machine Market | 2026-2036
Tray Forming Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tray Forming Machine Market Analytics
CE-marked servo-driven specifications is redrawing competitive boundaries in the Tray Forming Machine landscape. Wayne Automation leverages in-house control engineering to dominate high-speed food packaging installations across North America. Wexxar Packaging sustains technology leadership through precision vacuum-forming mechanics for corrugated tray applications. AFA Systems specializes in compact footprint designs that anchor its position among mid-volume pharmaceutical contract packagers.
A tray forming machine is an industrial packaging device that erects flat blanks into rigid trays through mechanical folding, adhesive application, or interlocking tab formation, typically operating at speeds from 15 to 120 trays per minute depending on blank complexity and automation tier. Its primary commercial purpose is to supply stable, stackable containers for product protection, retail display, and automated downstream handling in high-throughput manufacturing environments. Automatic systems command the largest installed base due to labor cost arbitrage in developed manufacturing economies, while robotic configurations represent the fastest-expanding segment as collaborative palletizing and tray handling converge on single-platform architectures. Paperboard material demand is accelerating fastest among sustainability-focused food brands, though plastic retains margin depth in moisture-barrier pharmaceutical and fresh produce applications.
The US Food and Drug Administration enforces 21 CFR Part 110 sanitary standards that shape stainless steel specification requirements for tray forming equipment deployed in food contact environments. The European Machinery Directive 2006/42/EC mandates CE conformity assessment for all automated tray forming systems placed on the EU market, creating compliance cost barriers for non-European entrants. China's National Medical Products Administration imposes packaging material biocompatibility rules that filter equipment selection in pharmaceutical tray applications. Stakeholders must monitor how diverging national sustainability mandates recalibrate material compatibility roadmaps against existing mechanical platform investments.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing food packaging manufacturers to accelerate capital expenditure on paperboard-compatible tray forming equipment, redrawing material roadmaps and equipment replacement cycles across European converter networks.
Growth Catalysts
- REACH compliance deadlines:Chemical safety protocols are pushing pharmaceutical packagers toward stainless steel servo-driven systems that eliminate lubricant contamination risks in cleanroom environments.
- Bakery automation:German ready-meal and artisan bread producers are expanding automated tray forming lines to address labor shortages in high-throughput baking operations.
- CE marking harmonization:Machinery Directive 2006/42/EC conformity assessment is streamlining cross-border equipment trade, reducing certification duplication costs for multi-national packaging groups.
Market Restraints
- Aluminum price volatility:Raw material swings for heated tooling components are compressing margins for mid-tier equipment manufacturers serving price-sensitive corrugated converters.
- Control system supplier concentration:Dependence on German and Japanese PLC vendors creates vulnerability for North American machine builders facing semiconductor allocation constraints.
- Plastic substitution limits:Moisture-barrier requirements in fresh produce and pharmaceutical cold chains prevent complete paperboard displacement, fragmenting R&D investment.
Strategic Opportunities
- India contract packaging:Domestic pharmaceutical outsourcing is creating demand for compact footprint tray formers that fit constrained cleanroom footprints in Mumbai and Hyderabad manufacturing clusters.
- Robotic palletizing convergence:Integration of collaborative arm technology with tray forming stations is enabling single-operator cell configurations for mid-volume food processors.
- China dual carbon targets:Provincial energy efficiency mandates are accelerating interest in servo-electric forming mechanisms that eliminate pneumatic consumption in Shanghai and Jiangsu packaging hubs.
Industry Challenges
- Mechatronics talent scarcity:Shortage of engineers fluent in both mechanical tooling design and servo control programming is extending commissioning timelines for automated installations.
- Legacy system interoperability:Retrofitting paperboard-compatible forming heads onto existing corrugated-focused machine frames requires custom mechanical engineering that strains OEM service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tray Forming Machine Market |
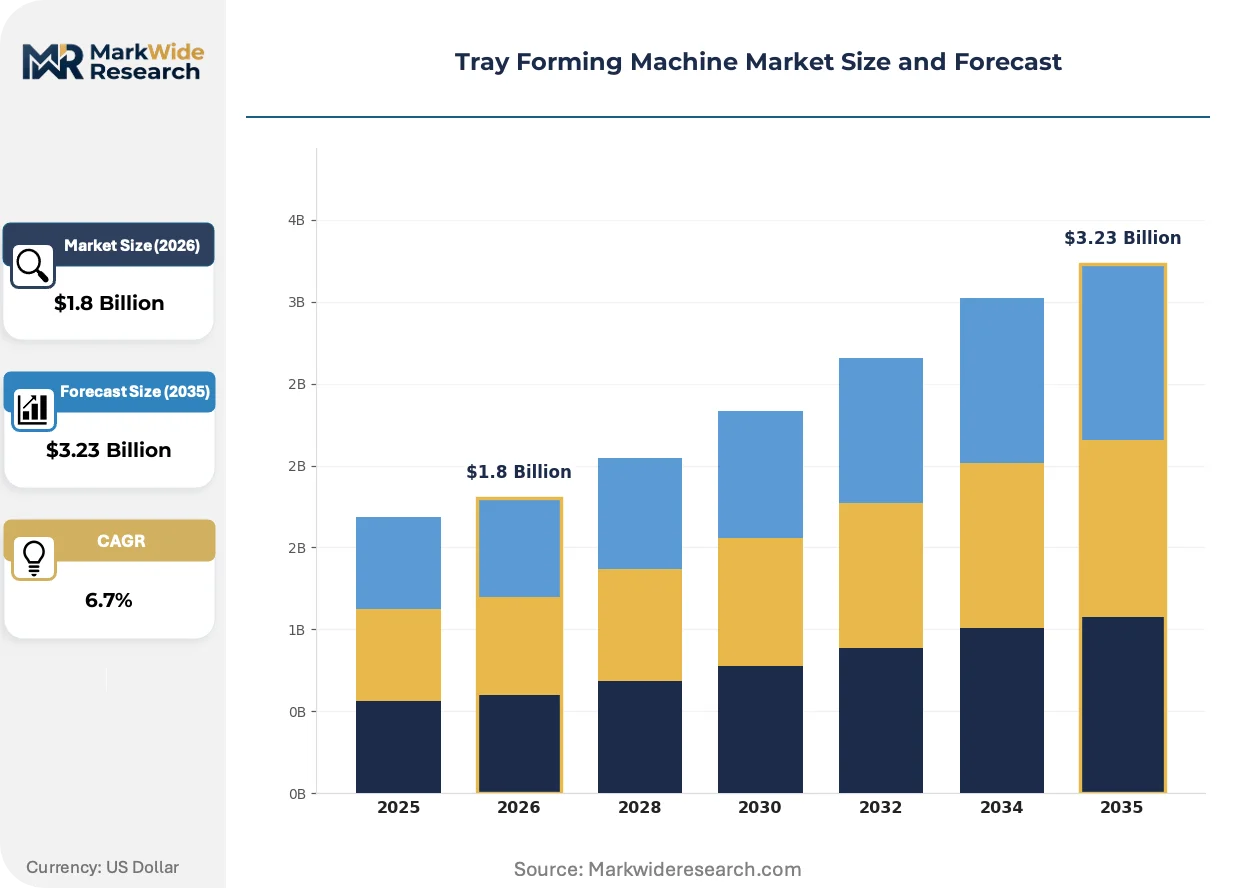
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Robotic End User: Food Packaging, Electronics, Pharmaceuticals, Consumer Goods Operation Mode: Continuous, Batch, On-Demand, Hybrid Material: Plastic, Paperboard, Aluminum, Others |
| Companies Covered | Wayne Automation, Wexxar Packaging, AFA Systems, ADCO Manufacturing, Combi Packaging Systems, Paxiom, DS Smith, Sacmi Packaging, Gebo Cermex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tray Forming Machine Market Evolving Landscape
Active developments across three domains are compressing equipment replacement cycles and redefining competitive differentiation: control architecture evolution, regulatory material mandates, and procurement model restructuring.
Modular servo drive architectures are decomposing the traditional monolithic machine controller into distributed motor-drive units with embedded safety logic. Pharmaceutical contract packagers in Switzerland and Germany are adopting these configurations to reduce cabinet footprint and simplify validation documentation. This decomposition is compressing the competitive advantage of legacy PLC-centric suppliers who lack in-house motion control engineering depth.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating oil-repellent coatings previously standard on paperboard tray forming tooling. European converters must now specify plasma-treated or wax-alternative surface finishes that maintain release properties without fluorinated chemistry. Bakery and ready-meal producers in France and Italy are most affected, accelerating trials of laser-etched forming dies that reduce mechanical adhesion without chemical treatments.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-volume food manufacturers seeking to align packaging capacity with seasonal demand fluctuation. Third-party financing entities are acquiring machine assets and charging per-formed-tray fees, transferring uptime risk to OEM service organizations. This shift is most visible in Benelux dairy and cheese packaging operations where private equity-backed contract manufacturers prioritize balance sheet flexibility over asset ownership.
Tray Forming Machine Market Segmentation
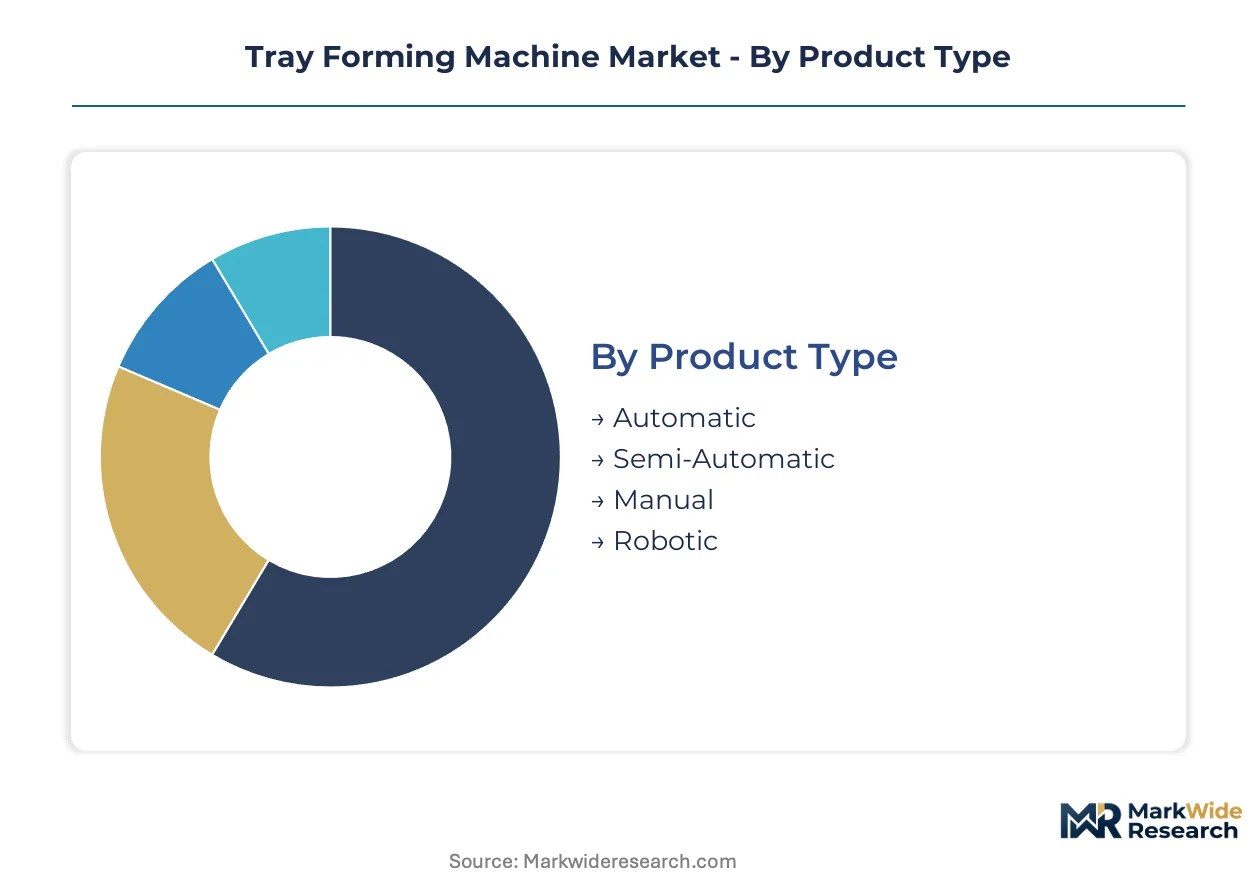
Tray forming machine procurement patterns diverge sharply across automation tiers and material specifications. Food packaging converters in Germany and pharmaceutical contract manufacturers in Switzerland drive premium segment premiums, while mid-tier corrugated applications concentrate procurement among domestic North American converters.
Product Type:
Automatic systems dominate export-led procurement from German and Japanese OEMs, while semi-automatic and manual configurations serve price-sensitive domestic markets in India and Southeast Asia.
- Automatic:These systems integrate servo-driven forming heads with continuous blank feeding mechanisms operating at 60-120 trays per minute. Demand concentrates among German bakery and ready-meal producers addressing labor shortages through capital substitution. CE marking requirements under Machinery Directive 2006/42/EC filter supplier selection toward European-certified builders.
- Robotic:Collaborative arm configurations merge tray forming with downstream palletizing in single-operator cells. Swiss pharmaceutical contract packagers and Benelux dairy processors are expanding these installations to reduce cleanroom headcount. The convergence of forming and handling functions is compressing floor space requirements by 30-40% versus traditional line layouts.
- Semi-Automatic:Intermediate automation tier serving mid-volume food processors in Poland and Czech Republic with intermittent blank loading and manual quality inspection stations.
- Manual:Foot-pedal or hand-lever operated units for artisan bakeries and small-batch specialty producers in Italy and Spain with throughput below 15 trays per minute.
Automatic configurations hold the largest share; momentum sits with robotic systems integrating collaborative handling.
End User:
Application-specific requirements reshape machine specification across hygiene grades, speed tolerances, and validation documentation intensity.
- Food Packaging:Stainless steel construction with 21 CFR Part 110 sanitary compliance dominates bakery, ready-meal, and dairy installations. FDA enforcement of sanitary design standards filters equipment selection toward washdown-capable architectures in US meat and poultry processing.
- Pharmaceuticals:Cleanroom-compatible servo systems with eliminated lubricant contamination risks serve contract packaging clusters in Mumbai and Hyderabad. REACH compliance deadlines are accelerating replacement of hydraulic actuation with oil-free electric forming mechanisms.
- Electronics:ESD-protected forming environments for semiconductor tray applications with ionization bars and conductive material handling surfaces.
- Consumer Goods:Corrugated tray specifications for retail display and e-commerce fulfillment with printed graphic registration requirements.
Food packaging commands the dominant procurement volume; pharmaceuticals exhibit the steepest specification escalation trajectory.
Operation Mode:
Throughput continuity requirements and demand volatility shape capital deployment between dedicated high-speed lines and flexible batch configurations.
- Continuous:Uninterrupted blank feeding for 24/7 production environments with automatic splicing and buffer accumulation. German automotive component suppliers and French dairy cooperatives deploy these for stable demand profiles.
- Batch:Programmed cycle operation with quick-change forming heads for seasonal SKU rotation. Italian wine and specialty food producers favor this flexibility for harvest-period volume spikes.
- On-Demand:Triggered forming synchronized with upstream production signals to minimize work-in-process inventory in lean manufacturing environments.
- Hybrid:Switchable continuous/batch logic for contract manufacturers serving multiple end-use verticals with divergent throughput requirements.
Continuous mode retains the largest installed base; hybrid configurations are climbing the fastest among multi-vertical contract packagers.
Material:
EU Packaging and Packaging Waste Regulation material recovery targets are recalibrating equipment compatibility roadmaps across European converter networks.
- Paperboard:Recyclable fiber-based substrates with plasma-treated or wax-alternative surface finishes replacing per- and polyfluoroalkyl substance coatings. French and Italian bakery producers are accelerating trials of laser-etched forming dies to maintain release properties under REACH restrictions.
- Plastic:Moisture-barrier polymers retaining specification in pharmaceutical cold chains and fresh produce applications where complete paperboard displacement remains technically constrained. Margin depth persists in high-barrier pharmaceutical tray specifications.
- Aluminum:Heated tooling applications for tray forming with temperature-controlled crease formation in premium ready-meal segments.
- Others:Molded fiber and compostable biopolymer substrates emerging in sustainability-focused brand owner trials.
Paperboard demand is expanding most quickly under regulatory pressure; plastic retains margin concentration in barrier-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led equipment flows from German and Japanese builders dominate cross-border procurement, while import dependency shapes specification choices in emerging converter markets across Asia and Latin America.
Germany
Bakery automation and ready-meal capital expenditure drive equipment procurement velocity. Machinery Directive 2006/42/EC CE marking requirements filter supplier selection toward certified European builders. North Rhine-Westphalia packaging machinery clusters concentrate servo-driven forming line manufacturing for export to Benelux dairy processors.
United States
Food contact sanitary standards and labor cost arbitrage sustain automatic system demand. FDA 21 CFR Part 110 enforcement shapes stainless steel washdown specifications for meat and poultry tray forming installations. Chicago-area dairy and cheese packaging operations anchor Midwest equipment deployment.
China
Provincial dual carbon targets and energy efficiency mandates accelerate servo-electric mechanism interest. NMPA pharmaceutical packaging material biocompatibility rules filter equipment selection in contract manufacturing clusters. Shanghai and Jiangsu packaging hubs concentrate cleanroom-compatible tray former procurement for domestic pharmaceutical outsourcing.
India
Domestic pharmaceutical contract packaging expansion creates demand for compact footprint configurations fitting constrained cleanroom environments. CDSCO regulatory compliance shapes specification requirements for oil-free electric forming mechanisms. Mumbai and Hyderabad manufacturing clusters anchor mid-volume tray forming equipment deployment.
Switzerland
Pharmaceutical contract packaging precision requirements sustain premium-tier equipment procurement. Swissmedic regulatory frameworks enforce validation documentation intensity for cleanroom-compatible servo systems. Basel-area life sciences manufacturing concentrates high-specification tray forming line installations.
Tray Forming Machine Market Competitive Landscape
Concentration sits with control-engineering specialists and precision mechanics fabricators who anchor premium-tier positioning through in-house motion control depth. The vendor base stratifies across three tiers: high-speed food packaging specialists with integrated servo architectures, corrugated-focused mechanics experts with vacuum-forming expertise, and compact-footprint designers serving pharmaceutical cleanroom constraints. Dominant competitive moves include M&A activity targeting control system capabilities and strategic partnerships bridging forming and palletizing functions.
Within the control-engineering tier, Wayne Automation and Wexxar Packaging exemplify divergent specialization vectors. Wayne Automation represents North American high-speed food packaging integration through in-house control engineering depth. Wexxar Packaging occupies a position among corrugated mechanics specialists with precision vacuum-forming expertise. AFA Systems anchors the compact-footprint archetype among mid-volume pharmaceutical contract packagers.
| Leading Market Players |
|---|
| Wayne Automation |
| Wexxar Packaging |
| AFA Systems |
| ADCO Manufacturing |
| Combi Packaging Systems |
| Paxiom |
| DS Smith |
| Sacmi Packaging |
| Gebo Cermex |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with German and Japanese PLC vendors lock in servo drive supply access while freezing component pricing visibility for North American machine builders facing semiconductor allocation constraints. This contract structure concentrates procurement power among OEMs with sufficient balance sheet depth to pre-commit volume, compressing margin flexibility for mid-tier equipment manufacturers serving price-sensitive corrugated converters.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium CE-marked servo systems, standard automatic configurations, and economy semi-automatic units. Price differentiation hinges on certification grade under Machinery Directive 2006/42/EC and after-sales service bundling including spare parts availability and field commissioning support. Cost compression in the economy tier is intensifying because aluminum price volatility for heated tooling components strains mid-tier manufacturer margins. Pharmaceutical contract packagers in Switzerland exhibit the lowest price sensitivity due to validation documentation requirements, while artisan bakeries in Italy and Spain drive economy-tier procurement.
Supply Chain Analysis
Extended lead times for servo motors and motion controllers from German and Japanese suppliers have compressed inventory buffers across North American machine builder networks. Manufacturing concentration centers on Germany, Japan, and the United States for precision forming mechanics and control engineering. Supply chain risk rests on single-source vulnerability for high-performance PLC modules and linear actuator assemblies. Distribution runs through direct OEM sales channels for large food packaging groups and specialized machinery distributors serving mid-volume pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of engineers fluent in both mechanical tooling design and servo control programming is extending commissioning timelines and constraining OEM service capacity expansion. This capability gap favors incumbents with captive training pipelines and documented commissioning protocols.
For Market Incumbents: Compound control engineering depth through targeted acquisition of motion control specialists or in-house apprenticeship programs scaling servo programming talent. Defend margin position by locking long-term capacity reservations with Japanese PLC vendors before semiconductor allocation constraints worsen. Prioritize documentation libraries that accelerate pharmaceutical validation timelines for Swiss and German contract packagers. For New Entrants and Emerging Players: Lead with compact footprint robotic configurations targeting Indian pharmaceutical contract packaging clusters in Mumbai and Hyderabad where constrained cleanroom environments filter equipment selection. Penetrate the mid-volume food processor segment in Poland and Czech Republic with hybrid continuous/batch operation modes that address seasonal SKU rotation without requiring full automatic system capital commitment. Position through equipment-as-a-service financing partnerships that transfer uptime risk and reduce balance sheet barriers. For Investors and Strategic Acquirers: Capital is best deployed toward control-engineering specialists with in-house servo architecture capabilities and established pharmaceutical validation track records. The long-term viability window favors OEMs capable of bridging forming and palletizing functions through collaborative arm integration. Watch for inflection signals in provincial Chinese energy efficiency mandate enforcement that would accelerate pneumatic-to-servo-electric conversion demand in Shanghai and Jiangsu packaging hubs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Manufacturing | Captive supply of motion controllers insulates North American builders from Japanese semiconductor allocation constraints. |
| Equipment-as-a-Service Financing Partnership | Per-formed-tray contracting transfers uptime risk to OEMs while unlocking Benelux dairy processor procurement. |
| Collaborative Arm Convergence Development | Single-operator cell configurations compress floor space requirements 30-40% for Swiss pharmaceutical cleanrooms. |
| Laser-Etched Forming Die Technology | Plasma-treated surface finishes maintain release properties under REACH per- and polyfluoroalkyl substance restrictions. |
| Pharmaceutical Validation Documentation Library | Pre-assembled compliance packages accelerate Swissmedic and FDA 21 CFR Part 110 approval timelines. |
Research Methodology
A spread of perspectives from plant engineers at German bakery automation lines, procurement leads at Indian pharmaceutical contract manufacturers, aftermarket service heads at North American OEMs, and regulatory affairs specialists at Swiss packaging operations converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Machinery Directive 2006/42/EC conformity assessment databases, FDA 21 CFR Part 110 guidance documents, and customs trade flows for packaging machinery imports. Bottom-up equipment deployment counts triangulated against top-down converter capital expenditure surveys.
Segmentation dimensions modeled include automation tier, material compatibility specification, end-use vertical, and geographic regulatory cluster across the projection horizon. CAGRs were derived from installed base growth rates and replacement cycle compression under EU Packaging and Packaging Waste Regulation mandates. Industry-specific forecast inputs incorporated servo-electric mechanism adoption curves and REACH compliance deadline impacts on oil-free forming system procurement.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated Chinese provincial energy mandates would require recalibration. Forecasts reflect documented assumptions regarding semiconductor supply normalization and mechatronics talent pipeline expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Triangle Tea Bag Packaging Machinery Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Thermoform Fill Sealing Machine Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Vial Capping Machines Market