
 Biodegradable Lids Market | 2026-2036
Biodegradable Lids Market Size, Share, and Industry Trends Forecast 2026-2036
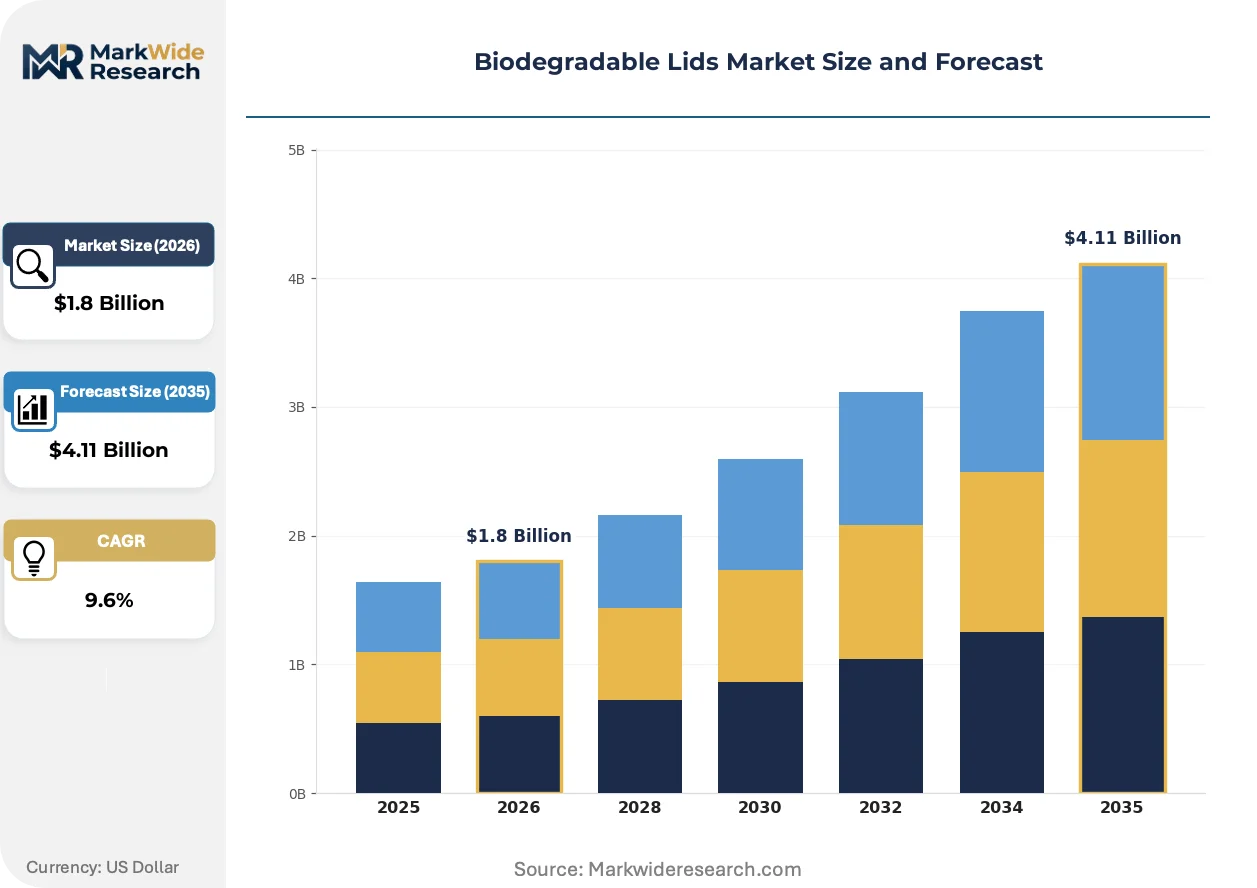
Biodegradable Lids Market Outlook
Quick-service restaurants are unwinding long-term contracts with conventional plastic suppliers as cafeteria operators and food retailers accelerate compostable procurement. Eco-Products dominates North American distribution channels through its captive supply of PLA resin. Vegware specializes in bagasse-lid formulations for hot-beverage applications where thermal performance determines contract awards. Huhtamaki Oyj anchors European manufacturing scale with multi-plant extrusion capacity serving quick-service chains.
Biodegradable lids are thermoformed or injection-molded closures manufactured from plant-derived polymers or agricultural residues, designed to seal beverage cups and food containers while meeting ASTM D6400 or EN 13432 compostability standards. PLA material formulations lead commercial deployment due to clarity and seal strength parity with conventional plastics, though bagasse variants are capturing hot-fill applications where temperature resistance defines performance. Food service applications concentrate the largest volume commitments, while retail-branded private-label lids concentrate margin pools through sustainability certification premiums.
The EU Single-Use Plastics Directive and FDA food-contact substance notifications jointly reshape product standards, with EN 13432 compostability certification becoming a de facto market-access requirement in Europe and material migration limits governing PLA formulations in the United States. Municipal composting availability remains the binding constraint on realized demand, creating divergent growth trajectories between regions with industrial composting infrastructure and those relying on landfill diversion alone. Stakeholders must monitor composting facility expansion timelines and certification harmonization between ASTM and EN frameworks before committing to regional capacity investments.
Market Dynamics
The EU Single-Use Plastics Directive is compressing petroleum-based lid supply chains while municipal composting infrastructure expansion determines which regions can absorb displaced volume. This regulatory-material mismatch creates divergent growth corridors between composting-enabled markets and landfill-dependent territories.
Growth Catalysts
- EN 13432 Certification Mandate:The EU directive eliminates conventional plastic lids from food service, forcing quick-service chains to source compostable alternatives. Germany's municipal composting network validates certified product acceptance.
- PLA Resin Capacity Expansion:Agricultural feedstock processing is scaling industrial lactic acid fermentation for polymer-grade material. Food packaging converters are securing multi-year resin offtake agreements.
- Quick-Service Restaurant Procurement:North American fast-casual chains are unwinding legacy plastic contracts and inserting compostable specifications into RFP templates. Cafeteria operators are following with volume commitments.
Market Restraints
- Industrial Composting Infrastructure Gaps:Regions without municipal composting facilities cannot process certified biodegradable lids, creating demand leakage to landfill diversion. Rural and suburban markets remain structurally excluded.
- PLA Feedstock Price Volatility:Corn and sugarcane commodity swings transmit directly to resin costs, compressing converter margins during agricultural price spikes. Bio-based material premiums widen unpredictably.
- Thermal Performance Limitations:PLA formulations soften above 55°C, disqualifying them from hot-beverage lid applications where bagasse alternatives carry supply concentration risk.
Strategic Opportunities
- Bagasse Hot-Fill Applications:Sugarcane fiber lids withstand temperatures above 90°C, opening quick-service coffee and soup container markets where PLA fails. Thermal performance parity with conventional plastics unlocks premium pricing.
- Private-Label Retail Certification:Supermarket chains are launching house-brand compostable packaging lines with sustainability premiums. Third-party ASTM D6400 certification enables margin capture beyond commodity food service.
- US Industrial Composting Buildout:EPA landfill diversion incentives are accelerating municipal facility construction in California, Washington, and Oregon. Early-mover lid suppliers secure long-term supply agreements with waste management operators.
Industry Challenges
- ASTM-EN Certification Harmonization Delays:Divergent testing protocols between US and European compostability standards force dual certification costs. Product development cycles extend by 8-12 months for cross-Atlantic distribution.
- Composting Facility Contamination Controls:Industrial composters are rejecting loads with non-certified bioplastics, requiring lid suppliers to invest in traceability systems and batch-level documentation.
- Legacy Thermoforming Equipment Retrofit Costs:Conventional plastic lid manufacturers face capital expenditure burdens to reconfigure extrusion and forming lines for PLA and bagasse processing parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Lids Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Containers, Cups Material: PLA, Wheat Straw, Bagasse, Starch Blends Application: Food Service, Packaging, Catering, Retail End User: Restaurants, Cafeterias, Food Retailers, Events |
| Companies Covered | Biopak, Eco-Products, Vegware, Greenware, World Centric, Bio-Lids, Packnwood, NatureWorks, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Lids Market Strategic Shifts
Material science advances are decomposing the thermal-performance barrier that historically segmented biodegradable lid applications, while regulatory frameworks accelerate specification lock-in across food service procurement.
PLA-PHA copolymer formulations are decomposing the temperature ceiling that restricted biodegradable lids to cold beverages. Quick-service chains in California and Washington are piloting these materials for hot-coffee applications at 500-unit scale. The technology is decomposing the application segmentation between PLA and bagasse, compressing supplier specialization advantages.
REACH restrictions on persistent organic pollutants are tightening migration limits for food-contact substances across EU member states. PLA converters must reformulate additives and processing aids to maintain compliance, extending product recertification timelines. Hot-beverage lid suppliers serving German and French quick-service markets are absorbing the largest compliance burdens.
Certification-driven procurement is consolidating buyer preferences around third-party-verified compostable products. Food service distributors are delisting uncertified bioplastic alternatives, replacing them with ASTM D6400 or EN 13432 validated SKUs. This preference compression is most visible in US coastal metropolitan markets where municipal composting mandates intersect with corporate sustainability commitments.
Biodegradable Lids Market Segmentation
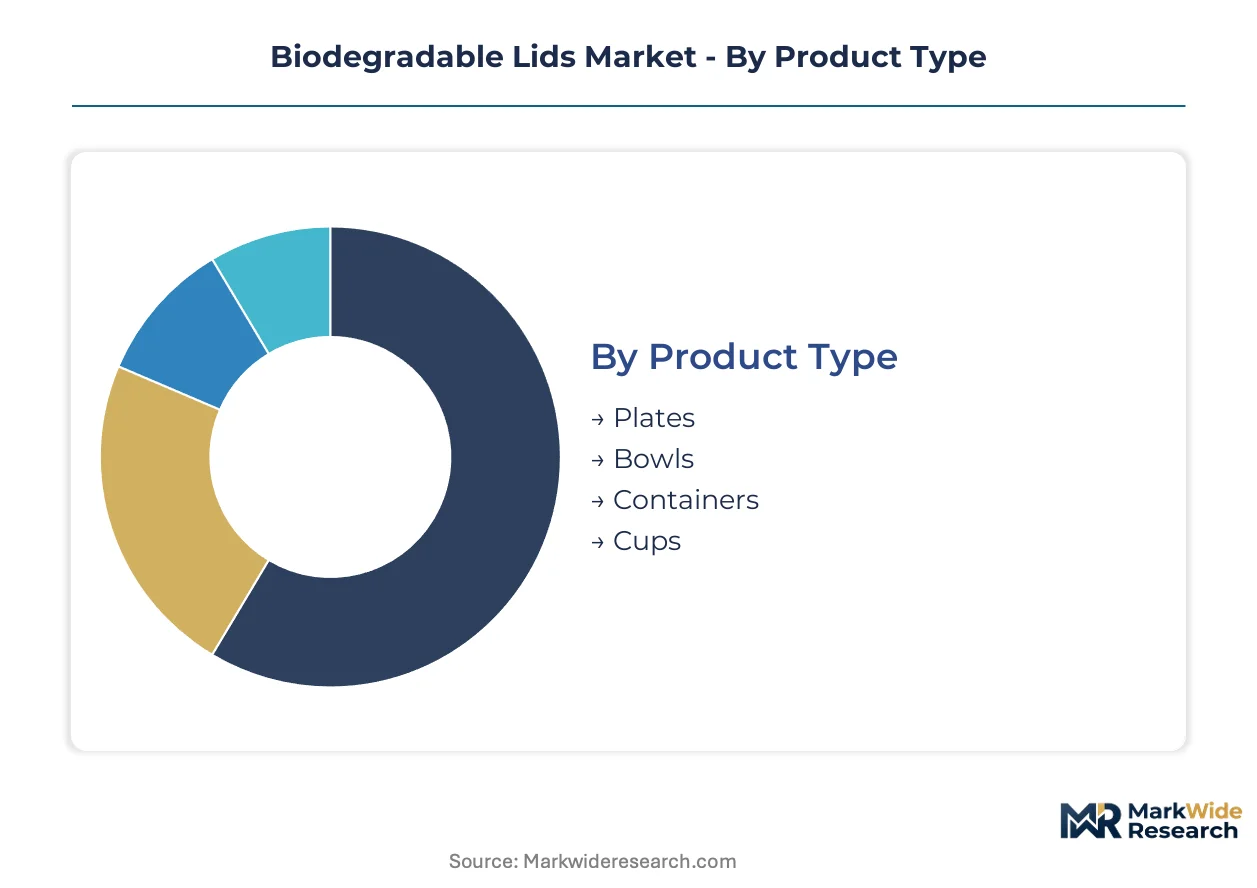
Biodegradable lid procurement patterns diverge sharply across material certifications, thermal performance requirements, and composting infrastructure availability. Understanding these segment boundaries clarifies where PLA clarity premiums command pricing power versus where bagasse thermal resistance wins contract awards.
Product Type:
Domestic demand concentrates in cup-lid formats across quick-service chains, while export volumes favor container-lid systems for prepared meal packaging.
- Plates:Flat-lid designs for plate covers use bagasse or molded fiber for steam retention in cafeteria tray service. German institutional catering contracts specify these for municipal composting compliance.
- Bowls:Domed and vented configurations serve soup and grain bowls where thermal insulation extends consumption windows. California quick-service chains are standardizing bowl-lid bundles for delivery-platform compatibility.
- Containers:Rectangular and compartmentalized lids seal prepared meals for retail chilled cases. French supermarket private-label programs are driving specification consolidation around EN 13432-certified variants.
- Cups:Straw-slot and sip-lid geometries dominate cold-beverage applications with PLA clarity matching conventional plastic visual standards. Washington State municipal composting mandates are accelerating cup-lid replacement timelines.
Cup lids hold the largest share; momentum sits with container lids as meal-prep retail expands.
Material:
Cost tiers separate premium fermentation-derived polymers from agricultural residue formulations, with starch blends occupying a mid-market positioning.
- PLA:Fermented corn sugar yields optically clear, sealable lids for cold beverages where visual parity with conventional plastics determines procurement. FDA food-contact notifications and ASTM D6400 certification enable US coastal market access, though thermal ceiling limitations exclude hot-fill applications.
- Wheat Straw:Agricultural residue processing creates fiber-reinforced lids with intermediate temperature tolerance and muted earth-tone aesthetics. Italian quick-service chains are piloting wheat-straw lids for ambient-temperature prepared foods where compostability certification outweighs optical clarity requirements.
- Bagasse:Sugarcane fiber withstands temperatures above 90°C, unlocking hot-beverage and soup-container markets where PLA softens. Supply concentrates in South Asian and Brazilian processing facilities serving European importers.
- Starch Blends:Thermoplastic starch formulations cost-position below PLA while meeting basic compostability standards for price-sensitive food service procurement. Spanish cafeteria operators are adopting starch-blend lids for volume applications where certification compliance suffices.
PLA commands the revenue premium; bagasse is climbing the fastest as hot-beverage specifications convert.
Application:
Customer-type concentration separates high-volume contract food service from certification-premium retail channels.
- Food Service:Quick-service chains and institutional cafeterias specify certified compostable lids at billion-unit procurement scale. Oregon and Vermont municipal composting mandates are embedding these specifications into franchise operating standards.
- Packaging:Prepared meal and delivery-platform compatibility drives tamper-evident lid requirements. UK supermarket chains are requiring packaging suppliers to demonstrate industrial composting pathway validation.
- Catering:Event and institutional catering demands disposable solutions with sustainability credentials for client reporting. Netherlands catering cooperatives are pooling procurement to secure volume pricing on EN 13432-certified lids.
- Retail:Private-label and branded consumer packaged goods carry certification premiums for shelf differentiation. California retail chains are launching house-brand compostable lines with third-party verified claims.
Food Service holds the largest share; Retail is expanding most quickly as private-label programs proliferate.
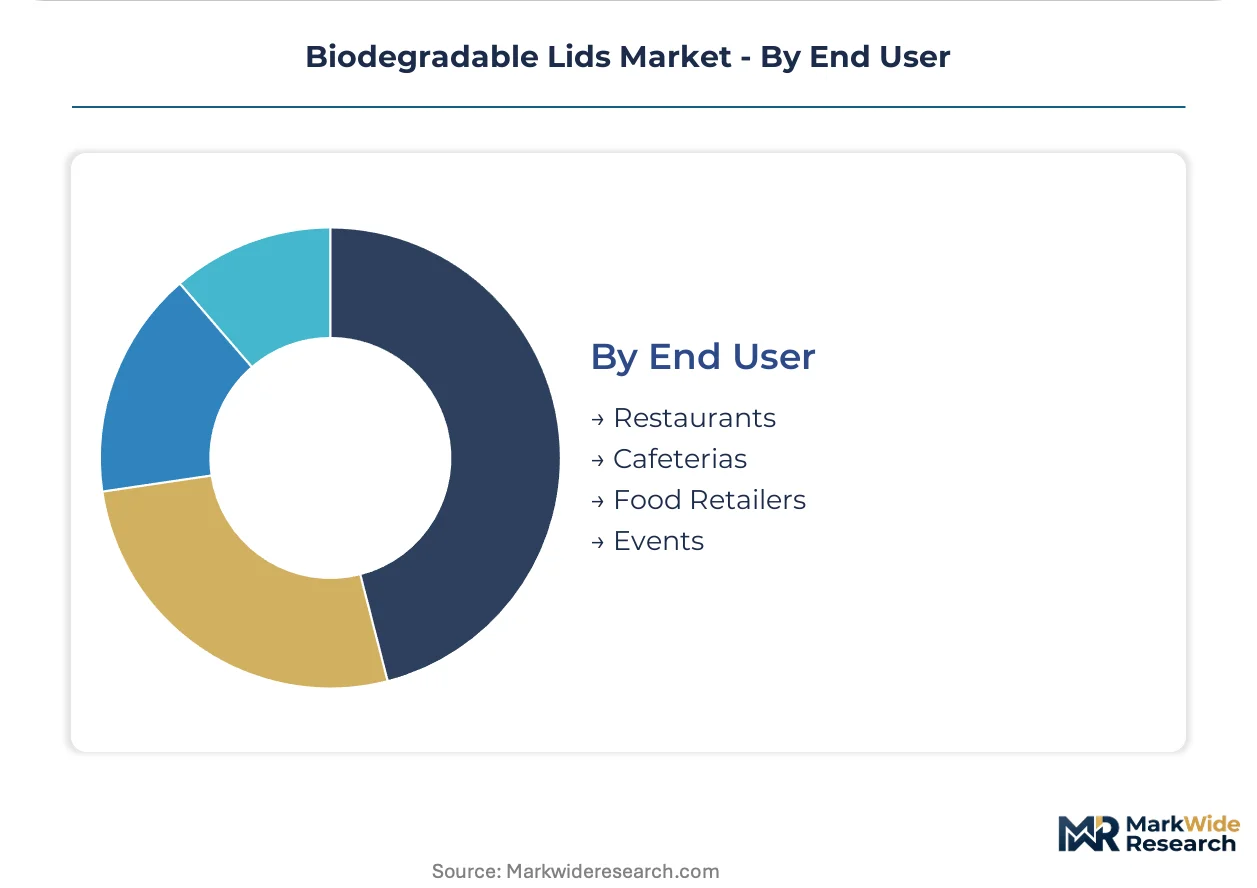
End User:
Volume scale and certification sophistication separate enterprise procurement from fragmented event-based demand.
- Restaurants:Full-service and fast-casual chains unwind legacy plastic contracts through multi-year compostable supply agreements. Washington State quick-service operators are leading regional conversion timelines.
- Cafeterias:Corporate, university, and hospital food service operations specify certified lids for sustainability reporting compliance. German municipal procurement frameworks are standardizing cafeteria compostable packaging requirements.
- Food Retailers:Supermarket delis, bakeries, and prepared-food counters adopt certified lids for private-label differentiation. French retail chains are integrating lid specifications into broader packaging sustainability scorecards.
- Events:Festival, stadium, and conference catering generates episodic high-volume demand with variable certification enforcement. California outdoor event permitting is beginning to mandate compostable serviceware including lids.
Restaurants hold the largest share; Food Retailers are gaining share fastest as private-label programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure underwrites Europe's gateway position for bagasse fiber imports from South Asian processing facilities. This logistics backbone channels certified biodegradable packaging materials into German and French quick-service supply chains.
United States
California's municipal composting mandates in Los Angeles and San Francisco accelerate quick-service restaurant procurement timelines. EPA landfill diversion incentives drive facility construction in Washington and Oregon. Seattle-based food service distributors consolidate procurement specifications around ASTM D6400 certification.
Germany
Municipal composting networks in Bavaria and North Rhine-Westphalia validate EN 13432-certified lid acceptance at industrial scale. The EU Single-Use Plastics Directive eliminates petroleum-based alternatives across federal procurement frameworks. Berlin's institutional cafeteria operators standardize compostable packaging requirements for sustainability reporting compliance.
France
Parisian quick-service chains pilot PLA-PHA copolymer lids for hot-beverage applications at district-scale deployment. REACH restrictions on persistent organic pollutants tighten migration limits for food-contact substances. Lyon-based supermarket private-label programs integrate lid specifications into packaging sustainability scorecards.
United Kingdom
London's food service distributors delist uncertified bioplastic alternatives in favor of validated SKUs. The Environment Agency's industrial composting pathway requirements govern retail chilled-case packaging. Manchester's prepared meal manufacturers specify tamper-evident container lids for delivery-platform compatibility.
India
Maharashtra's sugarcane processing clusters supply bagasse fiber to European lid manufacturers seeking thermal performance above 90°C. FSSAI food-contact substance notifications govern PLA formulation compliance for domestic quick-service chains. Gujarat's agricultural residue processing facilities scale fiber-reinforced lid production for export markets.
Biodegradable Lids Market Competitive Environment
Concentration sits with multi-plant converters and specialized agricultural residue processors. The vendor base separates into fermentation-derived polymer specialists, fiber-based thermal performance providers, and integrated food packaging conglomerates. Three archetypes dominate: captive resin producers securing multi-year offtake agreements, bagasse specialists capturing hot-fill contract awards, and diversified packaging groups leveraging extrusion scale. Capacity expansion and certification harmonization represent the dominant competitive vectors.
Among North American distribution-focused players, Eco-Products anchors the PLA resin supply tier through captive fermentation capacity. Vegware exemplifies the agricultural residue specialization archetype with bagasse-lid formulations for thermal-intensive applications. Huhtamaki Oyj occupies the integrated manufacturing position with multi-plant extrusion scale serving European quick-service chains. These three represent distinct capability configurations rather than interchangeable competitors.
| Leading Market Players |
|---|
| Biopak |
| Eco-Products |
| Vegware |
| Greenware |
| World Centric |
| Bio-Lids |
| Packnwood |
| NatureWorks |
| Huhtamaki Oyj |
| Others |
Value Chain & Pricing Dynamics
Bagasse fiber substitution for PLA in hot-beverage lid applications is simultaneously shifting procurement geography toward South Asian processing clusters and compressing price premiums for thermal-resistant formulations. This material migration is redrawing supplier power maps as quick-service chains unwind legacy resin contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates biodegradable lid procurement, with EN 13432 certification grade and volume scale as primary differentiation drivers. Premium tiers capture sustainability certification premiums for private-label retail, while economy tiers serve price-sensitive cafeteria operators with basic ASTM D6400 compliance. Cost compression in standard-tier PLA formulations is intensifying because agricultural commodity volatility transmits directly to resin pricing. Cafeteria operators exhibit highest price sensitivity; supermarket private-label buyers accept certification premiums with minimal negotiation.
Supply Chain Analysis
Rotterdam port congestion and container availability fluctuations on Asia-Europe trade lanes are elevating inbound logistics costs for bagasse fiber shipments. Supply concentrates in India, Thailand, and Brazil for agricultural residue processing, with PLA resin production anchored in US corn-belt fermentation facilities. The chain draws from corn and sugarcane feedstocks, sugarcane bagasse fiber, and polymer-grade lactic acid as critical inputs. Single-source vulnerability in South Asian bagasse processing creates exposure to monsoon-driven harvest volatility. Distribution runs through food service distributors and retail packaging converters with direct quick-service chain relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where EN 13432 and ASTM D6400 certification entrenchment creates switching costs that lock quick-service chains into validated supplier relationships.
For Market Incumbents: Shield market position by securing captive PLA resin supply through backward integration into lactic acid fermentation capacity, and accelerate EN 13432 recertification investments ahead of REACH migration limit tightening. Emerging bagasse specialists from South Asia pose substitution threats in hot-beverage segments where thermal performance determines contract awards. For New Entrants and Emerging Players: Private-label retail certification services represent an underserved layer where incumbents under-serve supermarket chains seeking third-party verified sustainability claims. Target US West Coast municipal composting corridors where infrastructure buildout outpaces supplier capacity, and pursue white-label certification bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed food packaging converters holding multi-year quick-service offtake agreements but lacking bagasse thermal capability. The five-to-ten-year viability window favors platforms with dual PLA and fiber-based production flexibility. Acquisition targets should demonstrate industrial composting facility partnerships in California, Washington, or Germany. The signal to watch is municipal composting permit issuance velocity as inflection indicator for regional demand absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Fermentation | Captive PLA resin supply locks in margin control against agricultural commodity swings. |
| Dual Certification Investment (ASTM D6400 + EN 13432) | Cross-Atlantic market access extends addressable buyer base for quick-service chains. |
| Bagasse Hot-Fill Capacity Expansion | Thermal performance above 90°C unlocks coffee and soup container contract awards. |
| Municipal Composting Facility Partnerships | Waste management operator agreements secure offtake pathway validation for retail buyers. |
| Private-Label Certification Services Launch | Third-party verification bundling captures supermarket sustainability scorecard requirements. |
Study Parameters
Desk research of EU regulatory filings, municipal composting infrastructure databases, and food service procurement RFP templates preceded structured interviews with quick-service chain sustainability officers, packaging converter plant managers, and industrial composting facility operators. Primary fieldwork with PLA resin suppliers and bagasse fiber processors was cross-validated against customs trade data and FDA food-contact substance notifications. Bottom-up volume modeling triangulated against top-down market sizing from packaging industry associations.
Variance-decomposition framing separated volume growth drivers across material type, thermal performance tier, and composting infrastructure availability throughout the forecast period. Segmentation dimensions included product geometry, polymer versus fiber material class, food service versus retail channel, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of procurement contract values and facility capacity expansion announcements. Feedstock price elasticity and certification timeline assumptions shaped scenario boundaries.
Underlying assumptions cover continued EU Single-Use Plastics Directive enforcement, municipal composting facility construction timelines in US coastal states, and REACH migration limit stability, with deviation risk concentrated in agricultural commodity volatility and ASTM-EN harmonization delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market