
 Biodegradable Packaging Market | 2026-2036
Biodegradable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Packaging Market Insights
EU Green Deal is recalibrating the cost-of-entry calculus for European converters, forcing legacy equipment upgrades and certified compostability testing. Amcor leverages its film extrusion footprint to anchor premium pouch supply for regulated European retail chains. Mondi competes through integrated kraft paper and barrier coating operations that sustain margin capture across tray and wrap segments.
Biodegradable packaging comprises materials engineered to decompose through microbial action into carbon dioxide, water, and biomass under industrial composting conditions, typically achieving 90% disintegration within 180 days at 58°C per EN 13432. Polylactic acid dominates current film and tray production due to its thermoplastic processability and optical clarity for food contact applications, though polyhydroxyalkanoates represent the fastest-expanding material class as bacterial fermentation yields improve and unit economics narrow. Starch-based polymers occupy the economy tier of the market, serving agriculture and industrial bulk packaging where moisture sensitivity limits performance requirements but cost thresholds dominate procurement decisions.
The EU F-Gas Regulation and REACH chemical standards constrain fluorinated barrier coatings, redirecting R&D toward bio-based alternatives. EMA food contact guidelines and national composting certifications in France, Italy, and the Netherlands fragment compliance requirements across the value chain. Stakeholders must monitor regulatory divergence between industrial and home composting standards to avoid stranded inventory and misaligned capacity investments.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing converters to retool extrusion lines and certify compostability under EN 13432, creating a bifurcation between compliant premium supply and stranded legacy capacity.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds and extended producer responsibility schemes are pulling starch-based films into German retail supply chains.
- Industrial composting infrastructure:Expansion of anaerobic digestion facilities in France and the Netherlands is creating offtake certainty for certified biodegradable trays.
- Food contact applications:Fresh produce and ready-to-eat meal segments are specifying barrier-coated kraft paper to replace multi-layer plastics.
Market Restraints
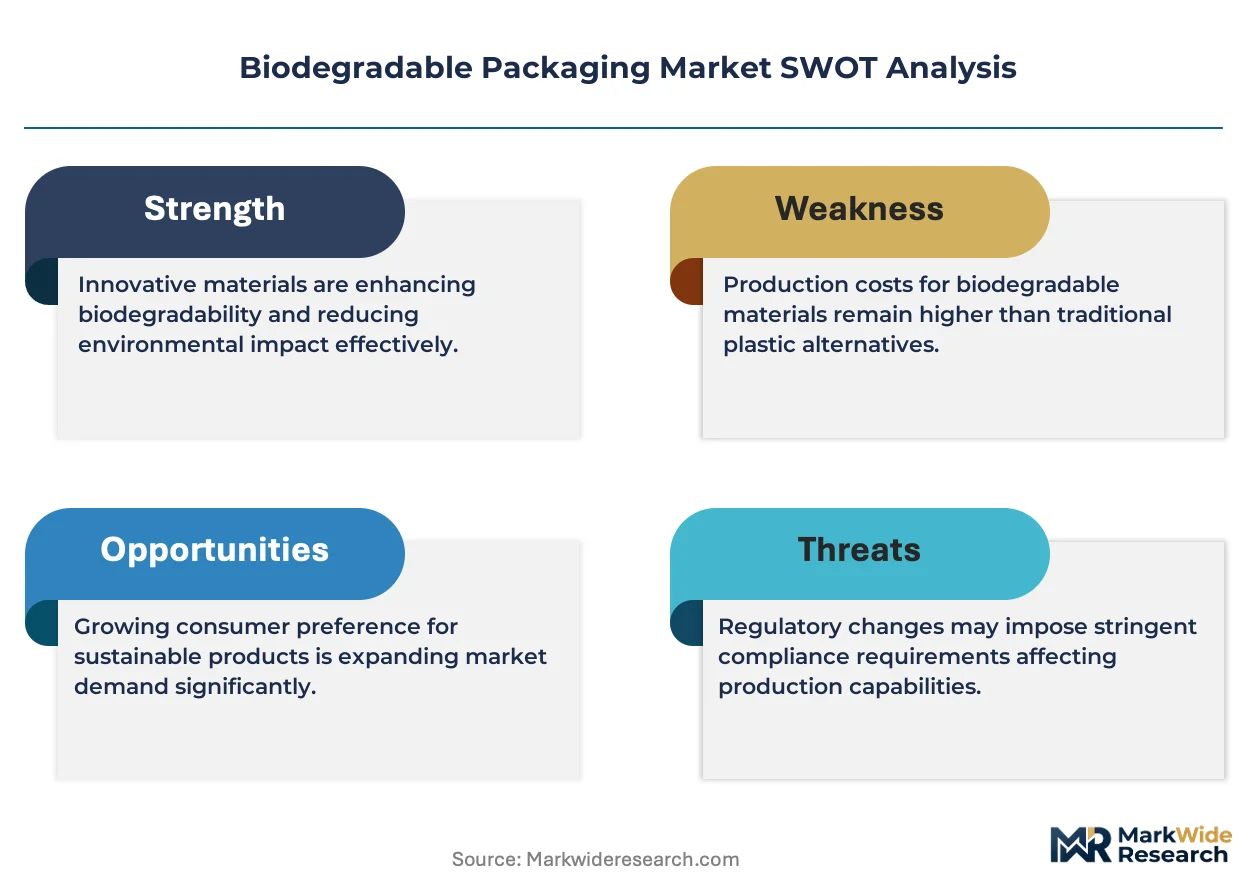
- PLA resin supply concentration:Fermentation capacity for lactic acid feedstock clusters in Thailand and Nebraska, exposing converters to freight cost volatility and currency risk.
- Moisture sensitivity of starch blends:Performance degradation above 65% relative humidity limits deployment in chilled distribution networks without secondary barrier films.
- Home composting standard divergence:France's NF T 51-800 and Italy's UNI 11183 create conflicting disintegration timelines, forcing SKU duplication for cross-border retail.
Strategic Opportunities
- PHAs from agricultural waste streams:Bacterial fermentation of sugarcane bagasse and corn stover is narrowing unit economics against conventional polypropylene in Brazilian and Indian bulk packaging.
- Reusable container-as-a-service models:Loop-style platforms in Nordic markets are creating demand for durable biodegradable crates with 50+ use cycles before industrial composting.
- EU F-Gas Regulation phase-down:Fluorinated barrier coating restrictions are redirecting R&D spend toward bio-based oxygen scavengers and nanocellulose laminates.
Industry Challenges
- Compostability certification timelines:EN 13432 testing requires 180-day industrial validation, delaying product launches and freezing working capital in inventory.
- Extrusion equipment retrofitting:Legacy blown film lines require screw and die modifications to process PLA's narrower thermal window, demanding capex commitments amid uncertain volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Packaging Market |
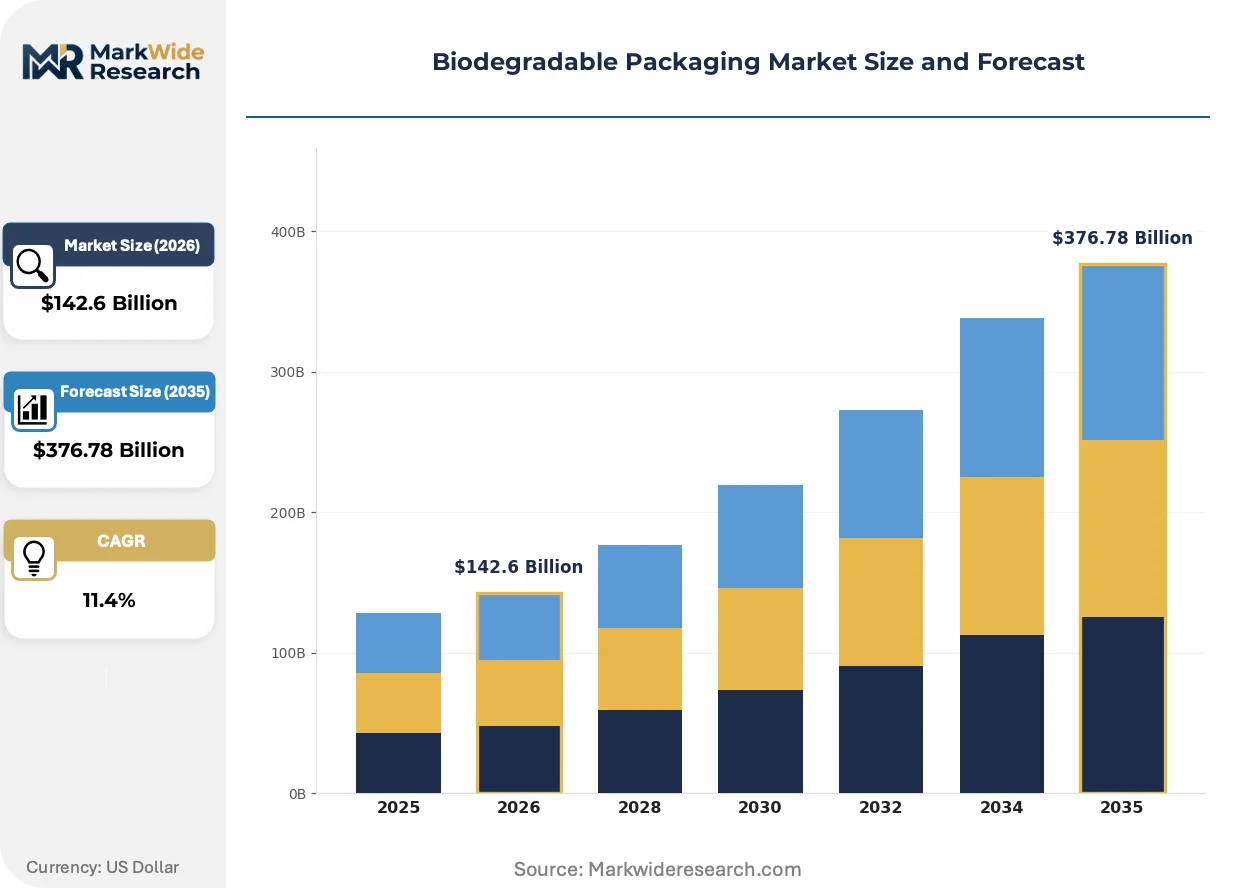
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $376.78 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polylactic Acid, Starch-Based Polymers, Polyhydroxyalkanoates, Cellulose, Chitosan, Lignin Packaging Type: Films, Trays, Pouches, Containers, Cups, Wraps Application: Food Packaging, Personal Care Packaging, Agriculture Packing, Industrial Packaging, E-commerce Packaging, Gift Packaging End User: Food Manufacturers, Cosmetics Producers, Agrochemical Suppliers, E-commerce Retailers, Industrial Enterprises, Event Organizers |
| Companies Covered | Amcor, Mondi, Sealed Air, DS Smith, Tetra Pak, Huhtamaki, Smurfit Westrock, BASF, NatureWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Packaging Market Trends and Innovations
Active barrier technologies and fermentation-derived polymers are compressing the performance gap between biodegradable and conventional packaging, while regulatory fragmentation is forcing modular certification strategies.
Barrier coating technology is converging with nanocellulose deposition systems to create oxygen transmission rates below 1 cc/m²/day. Fresh protein and dairy processors in Denmark and the Netherlands are piloting these structures for modified atmosphere packaging. The convergence is displacing aluminum oxide metallization in premium retail segments where microwaveability and recyclability are specified.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorinated coatings from food contact applications by 2026. European converters are accelerating qualification of bio-wax and chitosan alternatives. Wet-formed fiber tray manufacturers in Germany report 40% longer qualification cycles as they validate new barrier chemistries against legacy performance benchmarks.
Retail procurement consolidation is compressing supplier qualification timelines while expanding sustainability scorecard weighting. French and Belgian supermarket chains now mandate compostability certifications for private-label produce packaging. Category managers are unbundling conventional plastic SKUs in favor of certified biodegradable alternatives with verified end-of-life pathways, particularly in prepared salad and fresh herb segments.
Biodegradable Packaging Market Segmentation
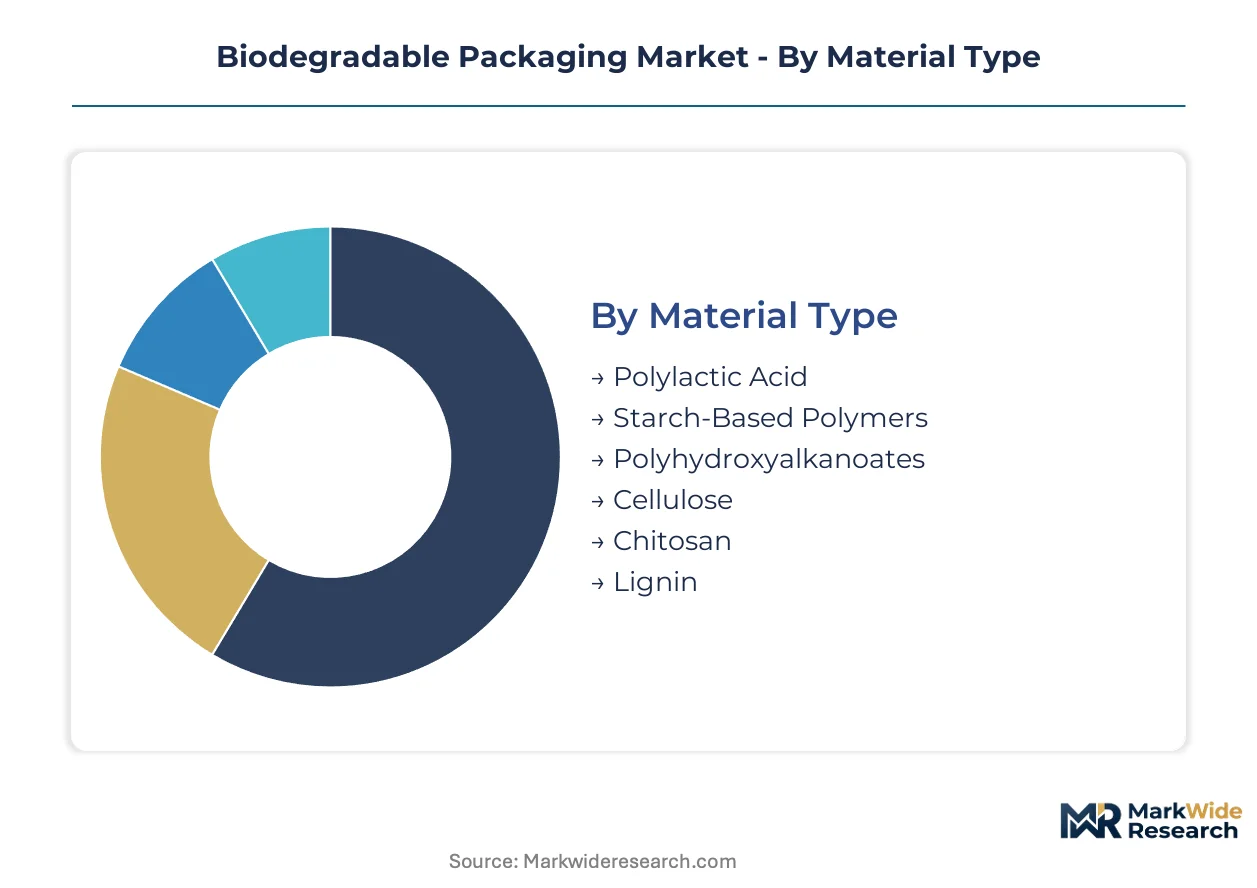
Segmentation in biodegradable packaging tracks how material properties, processing constraints, and end-of-life pathways align with specific customer procurement criteria. Each dimension reveals distinct upgrade cycles and substitution economics that determine supplier positioning.
Material Type:
Equipment retrofit requirements and thermal processing windows are forcing converters to sequence material transitions based on existing extrusion assets and composting certification timelines.
- Polylactic Acid:Thermoplastic aliphatic polyester derived from fermented corn starch or sugarcane, offering optical clarity and heat-sealability comparable to conventional polypropylene. European fresh produce and ready-to-eat meal segments specify PLA films for modified atmosphere applications, though narrow thermal windows demand screw and die modifications on legacy blown film lines.
- Starch-Based Polymers:Blends of native or modified starch with plasticizers and compatibilizers, occupying the economy tier where cost thresholds dominate over moisture resistance. German retail chains under the Packaging Act mandate specify starch trays for short-shelf produce, accepting performance trade-offs in chilled distribution networks where secondary barrier films add cost.
- Polyhydroxyalkanoates:Bacterial fermentation-derived polyesters with marine biodegradability credentials. Agricultural waste feedstock conversion in Brazil and India is narrowing unit economics against polypropylene in bulk packaging applications.
- Cellulose:Regenerated or nanofibrillated cellulose with high oxygen barrier potential. Danish dairy processors pilot nanocellulose laminates for protein packaging to displace aluminum oxide metallization.
- Chitosan:Deacetylated chitin from crustacean shells, applied as antimicrobial coatings on fresh protein wraps. REACH fluorinated coating restrictions accelerate qualification against legacy grease-resistant benchmarks.
- Lignin:Aromatic polymer from wood pulping, used as UV stabilizer and antioxidant in agricultural mulch films. Limited thermoplastic processability confines deployment to extrusion-compounded blends.
Starch-based polymers sit at the top of the volume ranking, with polyhydroxyalkanoates climbing the fastest as fermentation yields improve and agricultural waste feedstocks scale.
Packaging Type:
Customer switching costs vary dramatically by format, with films demanding full extrusion line retooling while trays permit modular thermoforming equipment upgrades.
- Films:Blown or cast structures for primary food contact and overwrap. Barrier-coated kraft paper converges with nanocellulose deposition to achieve oxygen transmission rates below 1 cc/m²/day in Dutch and Danish pilot programs.
- Trays:Thermoformed or pressed fiber structures for produce and protein presentation. French and Belgian supermarket chains mandate compostable tray certifications for private-label prepared salads, unbundling conventional plastic SKUs.
- Pouches:Flexible multilayer structures with zip closures and spouts. Amcor leverages film extrusion footprint to anchor premium pouch supply for regulated European retail chains.
- Containers:Rigid tubs and clamshells for dairy and deli applications. Loop-style reusable platforms in Nordic markets specify durable biodegradable crates with 50+ use cycles before industrial composting.
- Cups:Cold and hot beverage vessels with PLA or coated paper walls. Industrial composting infrastructure expansion in France and the Netherlands creates offtake certainty for certified cup formats.
- Wraps:Primary contact sheets for bakery and confectionery. Bio-wax alternatives to fluorinated coatings extend qualification cycles by 40% as German wet-formed fiber manufacturers validate new barrier chemistries.
Films command the largest installed equipment base, with pouches gaining share fastest as retail procurement consolidates around certified flexible formats.
Application:
Regulatory pressure intensity and end-of-life infrastructure maturity determine which applications convert first, with food contact leading due to direct EU Green Deal exposure.
- Food Packaging:Fresh produce, protein, dairy, and ready-to-eat meals requiring oxygen and moisture barriers. EU Packaging and Packaging Waste Regulation mandates pull starch-based films into German retail supply chains through extended producer responsibility schemes.
- Personal Care Packaging:Cosmetics and toiletries where aesthetic finish and shelf presence matter. EMA food contact guidelines and national composting certifications in France, Italy, and the Netherlands fragment compliance requirements across beauty brand portfolios.
- Agriculture Packing:Mulch films, plant pots, and crop protection with direct soil contact. PHA marine biodegradability credentials address microplastic accumulation concerns in intensive farming regions.
- Industrial Packaging:Bulk bags, dunnage, and protective wraps where performance thresholds dominate. Moisture sensitivity of starch blends limits deployment above 65% relative humidity without secondary barriers.
- E-commerce Packaging:Void fill, mailers, and protective wraps for direct-to-consumer shipment. Home composting standard divergence between France's NF T 51-800 and Italy's UNI 11183 forces SKU duplication for cross-border retail.
- Gift Packaging:Decorative wraps and presentation boxes with lower functional demands. Seasonal volume spikes strain composting facility capacity during holiday periods.
Food packaging anchors current procurement volume, with agriculture packing expanding most quickly as soil microplastic regulations tighten across European member states.
End User:
Procurement sophistication and sustainability scorecard weighting separate early adopters from laggards, with food manufacturers facing the steepest compliance deadlines.
- Food Manufacturers:Processors of fresh, chilled, and ambient goods with direct retail supply relationships. Category managers unbundle conventional plastic SKUs in favor of certified biodegradable alternatives with verified end-of-life pathways.
- Cosmetics Producers:Beauty and personal care brands with premium positioning and packaging-led marketing. EMA guidelines constrain material choices for products with dermal contact claims.
- Agrochemical Suppliers:Seed, fertilizer, and crop protection distributors with agricultural field deployment. Starch-based water-soluble packaging addresses chemical residue concerns in organic farming segments.
- E-commerce Retailers:Direct-to-consumer platforms and marketplace sellers with last-mile packaging decisions. Consolidated procurement compresses supplier qualification timelines while expanding sustainability weighting.
- Industrial Enterprises:Manufacturing and logistics operations with bulk packaging and protective wrap needs. Cost thresholds dominate where end-of-life remains outside direct customer visibility.
- Event Organizers:Catering and hospitality vendors with single-use service requirements. Temporary deployment limits willingness to absorb premium pricing for certified compostable formats.
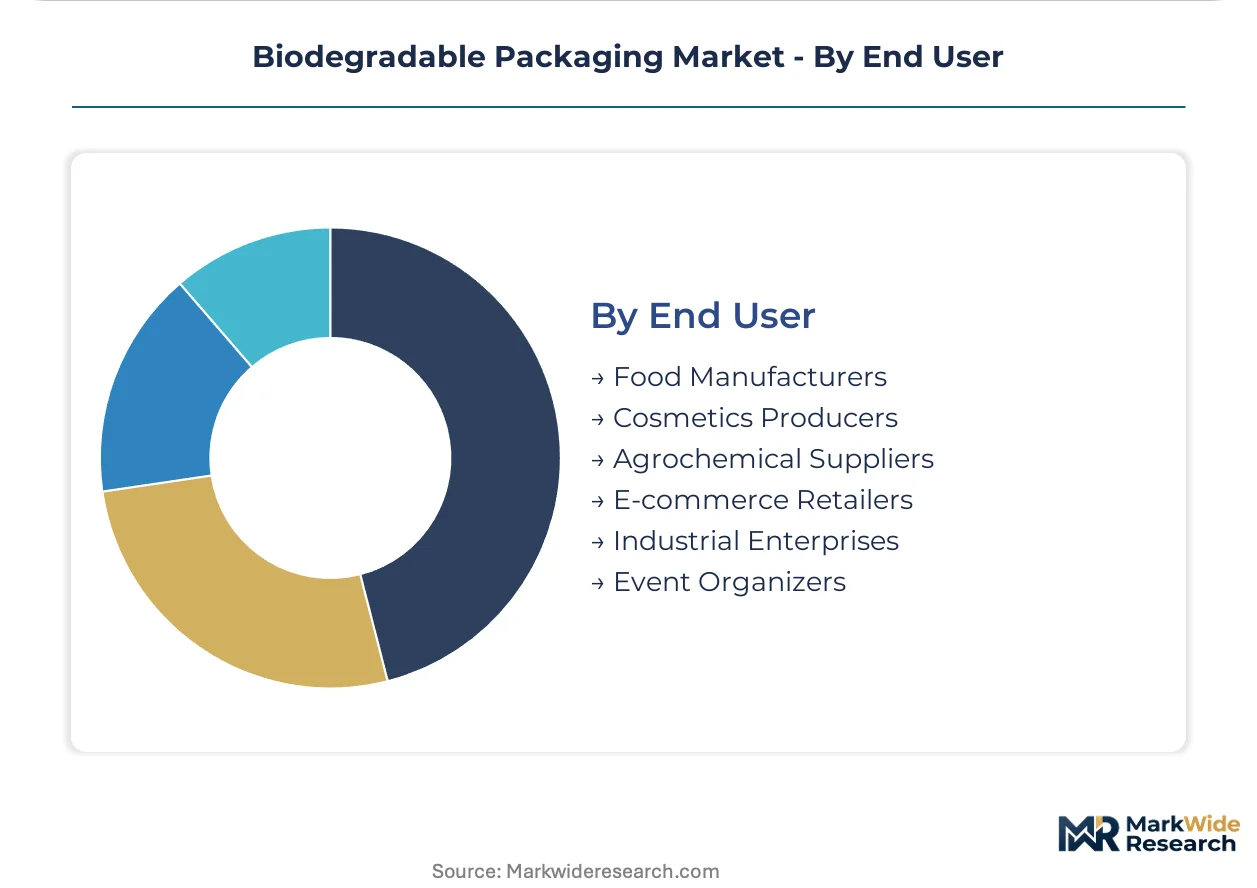
Food manufacturers represent the deepest current customer base, with e-commerce retailers gaining purchasing power fastest as channel consolidation accelerates sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineers and Dutch polymer scientists anchor European biodegradable packaging innovation, clustering around industrial composting infrastructure and regulatory compliance expertise.
Germany
Fresh produce processors and ready-to-eat meal manufacturers drive starch-based film procurement under the Packaging Act's extended producer responsibility framework. The EU Green Deal mandates industrial compostability certification under EN 13432, forcing Hamburg-area converters to retrofit blown film extrusion lines for PLA's narrower thermal processing window.
France
Dairy processors and protein packagers specify barrier-coated kraft paper for modified atmosphere applications as retail chains consolidate private-label procurement. NF T 51-800 home composting standards create compliance complexity alongside industrial certification, with Lyon-based wet-formed fiber tray manufacturers extending qualification cycles for bio-wax barrier alternatives.
Netherlands
Anaerobic digestion facility expansion around Rotterdam and Eindhoven creates offtake certainty for certified biodegradable cup and tray formats. Nanocellulose deposition pilot programs with Danish dairy partners achieve oxygen transmission rates below 1 cc/m²/day, displacing aluminum oxide metallization in premium protein segments.
Italy
UNI 11183 home composting timelines conflict with French standards, forcing SKU duplication for cross-border retail distribution. Emilia-Romagna's agricultural packaging specialists leverage PHA marine biodegradability credentials for intensive farming regions facing soil microplastic accumulation scrutiny.
United States
Nebraska-based lactic acid fermentation capacity supplies PLA resin to Midwest converters, though freight cost volatility and currency exposure complicate procurement planning. FDA food contact guidelines and state-level composting infrastructure gaps create regulatory fragmentation compared to European certification harmonization efforts.
Biodegradable Packaging Market Competitive Landscape
The competitive structure tilts toward integrated material suppliers with captive resin production and certified compostability testing capabilities. Tier-one packaging conglomerates and specialty biopolymer manufacturers divide the landscape, with mid-scale converters occupying equipment-dependent niches. Strategic archetypes include film extrusion specialists with retail chain anchoring, integrated paper-barrier coating operators, and fermentation-derived polymer pioneers. Dominant competitive moves encompass extrusion asset retrofitting for PLA thermal windows and modular certification strategies spanning multiple national composting standards.
Among integrated packaging conglomerates, Amcor and Mondi exemplify contrasting archetype positioning. Amcor represents film extrusion footprint leverage for premium pouch supply in regulated European retail chains. Mondi occupies a position within integrated kraft paper and barrier coating operations that sustain margin capture across tray and wrap segments. Specialty biopolymer positioning is anchored by NatureWorks as a fermentation-capital-intensive archetype, while BASF exemplifies diversified chemical conglomerate participation through material science capabilities rather than packaging-format integration.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| Sealed Air |
| DS Smith |
| Tetra Pak |
| Huhtamaki |
| Smurfit Westrock |
| BASF |
| NatureWorks |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap converters across Germany and the Netherlands anchor supply discipline through generational capital allocation, linking patient balance-sheet management to selective equipment upgrades and pricing power in certified compostable segments. Their ownership structure insulates against quarterly margin pressure while concentrating procurement relationships with retail chains under EU Green Deal mandates.
Pricing Analysis
Certification-bundled versus unbundled service splits dominate pricing architecture, with EN 13432 validation packaged into premium tier quotes while economy starch-based films trade on per-kilogram spot terms. Price differentiation hinges on compostability certification grade and volume scale commitments from German retail chains. Pricing pressure stems from PLA resin freight cost volatility between Thai fermentation hubs and European extrusion plants. Industrial bulk packaging buyers exhibit highest price sensitivity, while fresh protein processors under retailer sustainability scorecards absorb certified premiums.
Supply Chain Analysis
Dual-sourcing requirements from French and Belgian supermarket chains mandate multi-supplier qualification for PLA film and barrier-coated kraft paper, preventing single-source dependency despite NatureWorks' fermentation scale. Supply concentrates in Thailand for lactic acid feedstock, Germany for extrusion and thermoforming equipment, and Brazil for agricultural waste-derived PHA pilot production. Raw material dependencies include corn starch, sugarcane bagasse, and chitosan from crustacean processing. Tariff exposure on Asian resin imports threatens margin stability. Distribution runs through converter-direct relationships with retail chain category managers, bypassing traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biodegradable packaging market functions as a stable compounder, with EU Packaging and Packaging Waste Regulation mandates delivering predictable demand visibility across industrial composting infrastructure buildouts.
For Market Incumbents: Cement certification leadership through captive EN 13432 testing laboratories in Hamburg and Munich industrial clusters, defending against mid-cap converters with faster qualification timelines. Prioritize backward integration into lactic acid fermentation partnerships to offset Thai supply concentration. Channel control through exclusive supply agreements with French retail consolidation groups protects volume commitments. For New Entrants and Emerging Players: PHA fermentation technology from agricultural waste streams offers white-space penetration in Brazilian and Indian bulk packaging where polypropylene substitution economics narrow fastest. Target Italian agricultural packaging specialists facing UNI 11183 compliance complexity alongside industrial certification requirements. Go-to-market leverage rests on marine biodegradability credentials for intensive farming regions under soil microplastic scrutiny. For Investors and Strategic Acquirers: Valuations sit cheapest among wet-formed fiber tray manufacturers with 40% extended qualification cycles for bio-wax barrier alternatives, creating distressed entry points before REACH fluorinated coating phase-down completion. Long-term viability hinges on composting infrastructure density per capita across member states. Watch anaerobic digestion facility permitting velocity in France and the Netherlands as inflection signal for certified format offtake certainty.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Captive lactic acid supply from Nebraska or Thai agricultural networks secures margin against freight volatility. |
| Modular Certification Strategy | Parallel EN 13432 and NF T 51-800 validation prevents SKU duplication for cross-border French retail distribution. |
| Nanocellulose Barrier Deposition Scale-Up | Pilot oxygen transmission rates below 1 cc/m²/day with Danish dairy processors displace aluminum oxide metallization. |
| Reusable Container-as-a-Service Platform | Loop-style Nordic deployments with 50+ use cycles extend asset life before industrial composting end-of-life. |
| Equipment Retrofit Partnership Program | Screw and die modifications for PLA thermal windows lock in converter loyalty amid uncertain volume commitments. |
Research Methodology
Coverage spans Germany, France, the Netherlands, Italy, and the United States, with primary inputs from each market cluster through structured interviews with blown film extrusion plant managers, retail chain category buyers, composting facility operators, and regulatory compliance officers at packaging converters. Secondary validation draws from EU Packaging and Packaging Waste Regulation filings, ECHA REACH restriction updates, national composting certification databases, and SEC disclosures from listed packaging conglomerates. Bottom-up volume modeling triangulates against top-down spending estimates from retail procurement consolidation trends.
Rate-of-change decomposition separates volume growth into substitution-driven displacement of conventional plastics, regulatory mandate timing, and composting infrastructure readiness across the projection horizon. Segmentation dimensions include material type, packaging format, and end-use application with regulatory pressure intensity as a cross-cutting factor. CAGRs derive from fitted adoption curves against historical compliance deadline responses in adjacent packaging categories. Industry-specific inputs capture PLA resin freight cost indices and industrial composting facility permitting queues.
The model holds under sustained EU Green Deal implementation timelines and stable fermentation feedstock pricing; deviation in home composting standard harmonization or Thai lactic acid export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Europe Biodegradable Cups Market