
 Plastic Bags and Sacks Market | 2026-2036
Plastic Bags and Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Bags and Sacks Market Analytics
ASTM D6400 and EN 13432 compostability certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. Berry Global Inc. leverages its North American manufacturing footprint to sustain high-volume supply contracts with major retail chains. Mondi Group differentiates through integrated paper-plastic hybrid solutions that navigate tightening European packaging regulations. Novolex anchors its position in food service applications through specialized film extrusion capabilities.
Plastic bags and sacks are flexible packaging containers manufactured from polyethylene films typically ranging from 0.5 to 6 mils in thickness, formed through blown film extrusion and subsequent heat-sealing or side-weld conversion. These products serve primarily to protect, transport, and merchandise goods across retail, industrial, and institutional supply chains. HDPE dominates grocery and retail carryout applications due to its stiffness-to-cost ratio, while biodegradable plastics represent the fastest-expanding material segment as regulatory bans on conventional polymers proliferate. Stand-up pouches command premium margin pools in food services and healthcare end uses where barrier properties and shelf presence justify higher unit economics.
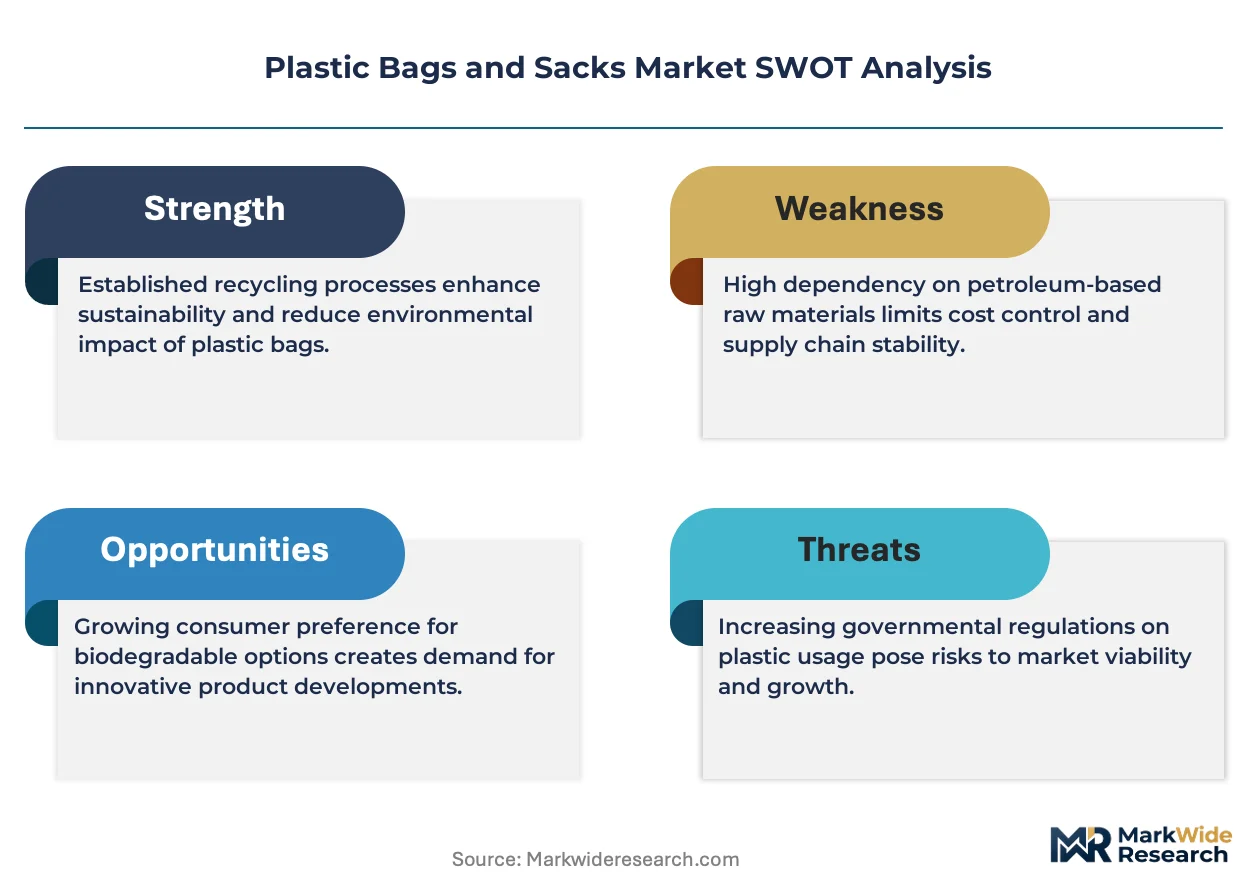
The EPA oversees municipal solid waste frameworks affecting bag disposal pathways in the United States, while the EU Green Deal and F-Gas Regulation indirectly pressure converters toward lower-carbon film production methods. REACH compliance in Europe and evolving state-level plastic bag legislation across the United States create divergent compliance cost structures that reshape sourcing decisions. Stakeholders must monitor certification alignment and regional ban schedules to determine facility investment and material portfolio priorities.
Market Dynamics
Regulatory fragmentation between jurisdictions with outright bans and those with permissive frameworks is forcing converters to maintain dual material portfolios and regional production footprints simultaneously.
Growth Catalysts
- EU Single-Use Plastics Directive:The 2019 framework mandating reduction targets and extended producer responsibility schemes is pulling demand toward certified compostable alternatives across member states.
- Food service expansion:Quick-service restaurant chains and meal-kit delivery platforms are scaling specialized barrier film procurement for temperature-stable packaging.
- Blown film extrusion advances:Down-gauging technologies enabling 0.3-mil thickness without puncture failure are cutting resin input per unit across high-volume grocery applications.
Market Restraints
- Ethylene feedstock volatility:Crude oil and natural gas liquid price swings transmit directly to polyethylene resin contracts, compressing converter margins during upstream spikes.
- Composting infrastructure gaps:ASTM D6400 and EN 13432 certified bags require industrial composting facilities that remain concentrated in Germany, Netherlands, and select US coastal corridors.
- Paper and non-woven substitution:Kraft paper sacks and reusable polypropylene totes are capturing regulatory-compliant share in retail carryout and promotional bag segments.
Strategic Opportunities
- Indian organized retail penetration:Reliance Retail, D-Mart, and BigBasket are formalizing bag procurement standards as modern trade expands beyond tier-one cities into tier-two and tier-three urban centers.
- Pharmaceutical cold-chain packaging:Insulated pouch formats with phase-change material compatibility are opening specialized demand from vaccine distributors and biologics shippers.
- Extended producer responsibility credits:France's CITEO eco-modulation scheme and Italy's CONAI framework reward post-consumer recycled content integration with fee reductions.
Industry Challenges
- Compostability certification timelines:ASTM D6400 and TÜV Austria OK Compost INDUSTRIAL testing cycles extend 6-12 months, delaying product launches and locking working capital in pipeline inventory.
- Multi-layer film recycling complexity:EVOH and nylon barrier layers in food-grade pouches complicate mechanical reprocessing, requiring investment in solvent-based delamination or pyrolysis feedstock preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Bags and Sacks Market |
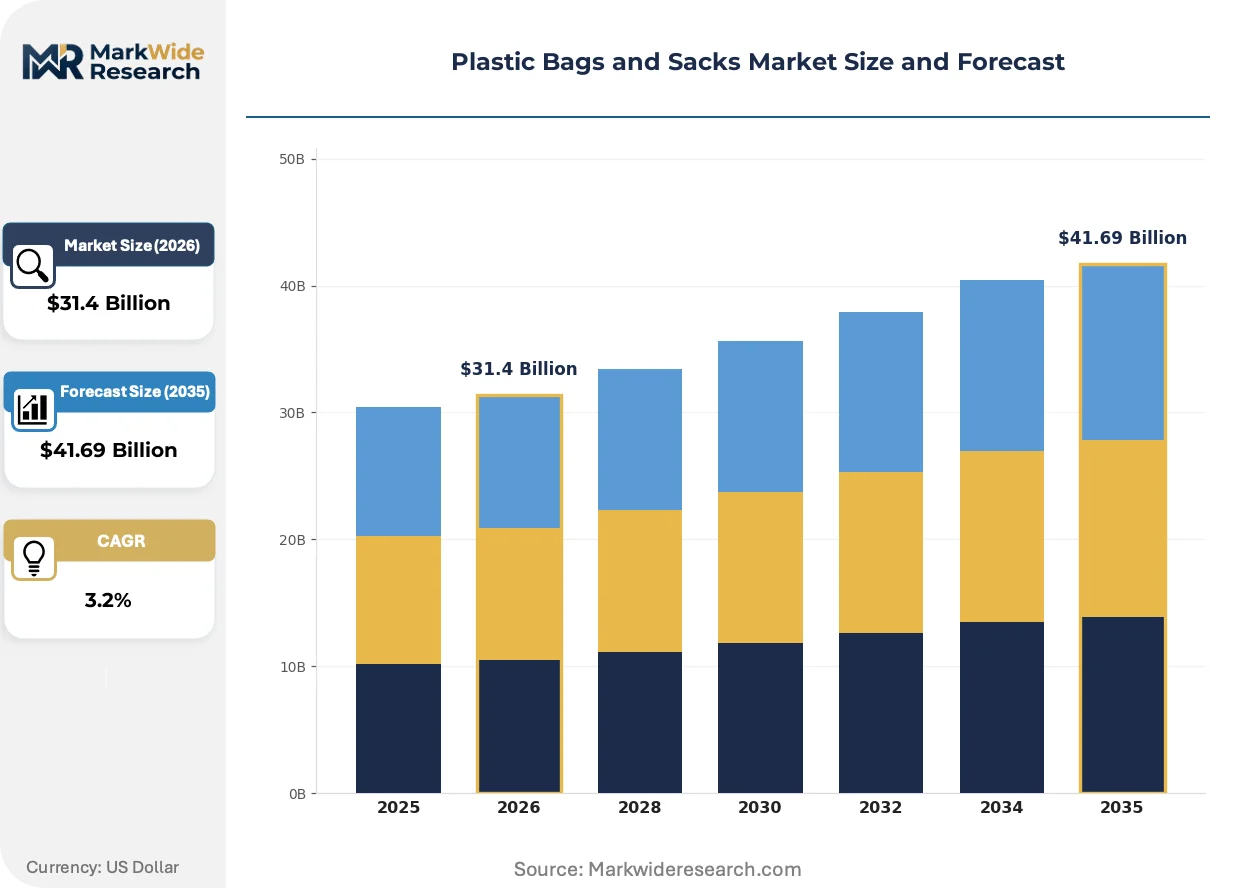
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $41.69 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Stand-up Pouches, Gusseted Bags, Drawstring Bags Material: HDPE, LDPE, Biodegradable Plastics, PP End User: Retail, Food Services, Healthcare, Industrial Packaging Type: Reusable Bags, Single-use Bags, Custom Printed Bags, Bulk Bags |
| Companies Covered | Berry Global Inc., Novolex, Mondi Group, Inteplast Group, Ampac Holdings LLC, Bischof + Klein SE & Co. KG, Starlinger & Co Gesellschaft m.b.H., Amcor plc, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Bags and Sacks Market Evolving Landscape
Material science breakthroughs and regulatory calibration are converging to redefine performance specifications and end-of-life pathways for flexible packaging formats.
Polyhydroxyalkanoate and polylactic acid formulations are displacing conventional LDPE in premium retail and food service applications where municipalities enforce strict contamination limits on organic waste streams. Specialty grocers and institutional food service buyers in California, Washington, and Vermont are specifying certified compostable carryout at 15-25% price premiums. The displacement is compressing virgin resin demand in coastal metropolitan zones while inland markets without composting access remain polyethylene-dependent.
REACH SVHC candidate list expansion and the EU Packaging and Packaging Waste Regulation revision are tightening substance restrictions and recycled content mandates for flexible formats entering European commerce. Converters face reformulation costs to eliminate intentionally added microplastics and meet 2030 recycled content thresholds. Food contact applications are most affected, with migration testing protocols extending development cycles for rPE incorporation.
Centralized procurement through sustainability consortiums is consolidating buyer power and standardizing specification templates across retail and food service networks. The Sustainable Packaging Coalition's How2Recycle labeling program and similar initiatives are displacing fragmented supplier-specific claims with harmonized disposal instructions. This consolidation is most visible in North American grocery retail, where Kroger, Albertsons, and Ahold Delhaize are aligning bag specifications through shared technical committees.
Plastic Bags and Sacks Market Segmentation
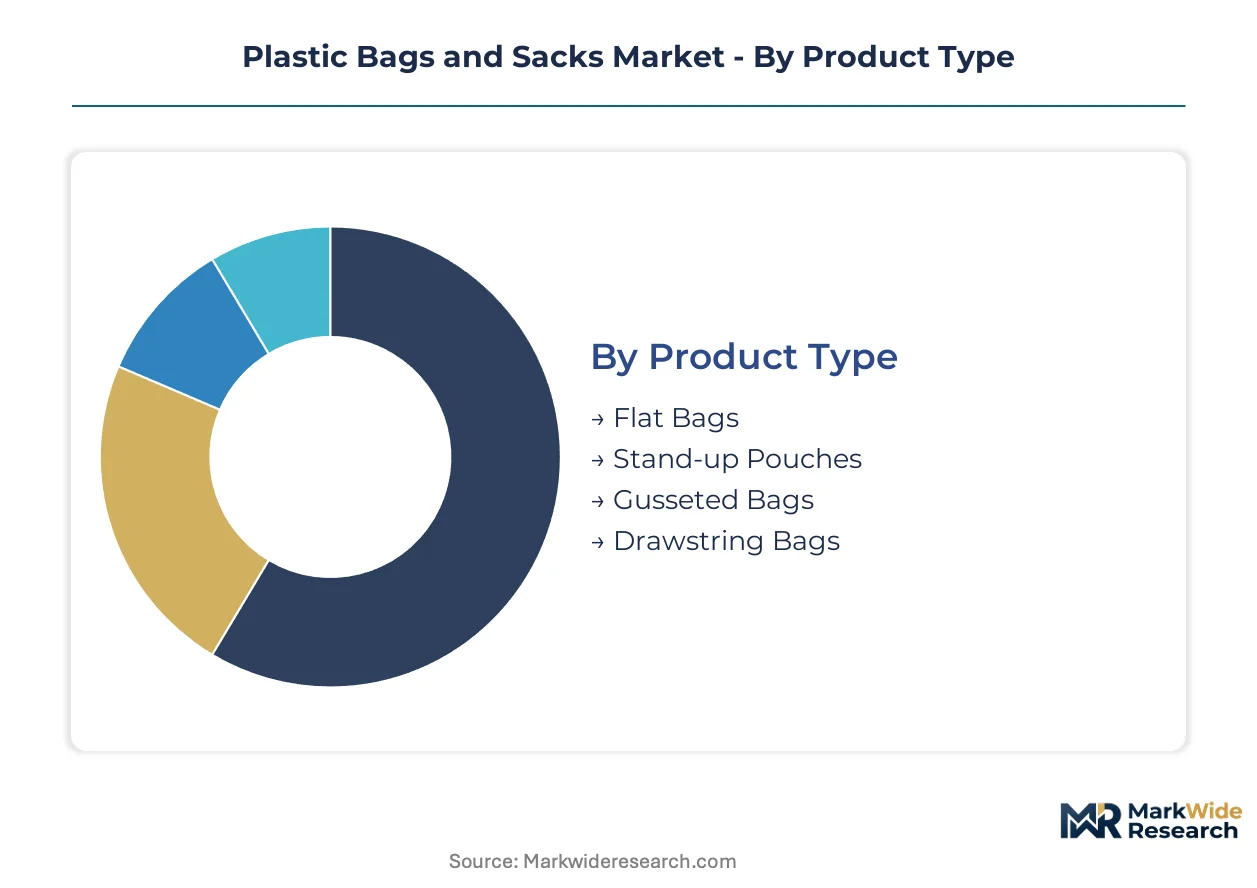
Segmentation in plastic bags and sacks reveals where substitution pressure and regulatory compliance costs concentrate most intensely. Material and end-use boundaries are blurring as converters reformulate portfolios to serve divergent regional ban schedules.
Product Type:
Substitution pressure from paper and non-woven alternatives hits commodity formats hardest while specialized barrier constructions defend margin pools.
- Flat Bags:Conventional LDPE and HDPE constructions dominate grocery carryout and industrial liner applications. Demand concentrates in Indian organized retail and Southeast Asian manufacturing clusters where cost-competitive blown film extrusion scales rapidly. The EU Single-Use Plastics Directive is accelerating displacement toward certified compostable alternatives in member states with industrial composting infrastructure.
- Stand-up Pouches:Multi-layer barrier films incorporating EVOH or nylon layers serve temperature-stable food service and pharmaceutical cold-chain requirements. Quick-service restaurant chains and meal-kit delivery platforms in California and Washington specify these formats despite 15-25% price premiums over conventional structures.
- Gusseted Bags:Side-weld constructions expand capacity for bulk dry goods and institutional food service procurement.
- Drawstring Bags:Convenience closures capture promotional and retail apparel segments where reusability extends product lifecycle.
Flat bags anchor the volume base while stand-up pouches gain share at the steepest rate.
Material:
Cost tier stratification separates virgin polyethylene commodity supply from certified biodegradable alternatives commanding formulation premiums.
- HDPE:High-density polyethylene delivers optimal stiffness-to-cost ratios for grocery carryout and retail merchandise bags. India and Vietnam manufacturing clusters exploit feedstock proximity to serve cost-sensitive procurement from modern trade expanding into tier-two and tier-three urban centers.
- Biodegradable Plastics:Polyhydroxyalkanoate and polylactic acid formulations require ASTM D6400 or EN 13432 certification for municipal organic waste stream acceptance. California, Washington, and Vermont municipalities enforce strict contamination limits that pull specialty grocer procurement toward these alternatives despite limited industrial composting facility coverage.
- LDPE:Low-density polyethylene films dominate bread bags, frozen food overwrap, and general merchandise applications where clarity and sealability matter.
- PP:Polypropylene woven and non-woven constructions serve reusable tote and bulk agricultural packaging segments.
HDPE retains the largest installed production base while biodegradable plastics expand most quickly in coastal metropolitan zones with composting access.
End User:
Application-specific barrier requirements and regulatory exposure vary sharply across customer types, reshaping converter sales force deployment.
- Retail:Supermarket and hypermarket chains specify standardized formats through centralized procurement consortiums. The Sustainable Packaging Coalition's How2Recycle labeling program is harmonizing disposal instruction requirements across Kroger, Albertsons, and Ahold Delhaize networks in North America.
- Food Services:Quick-service restaurants and meal-kit platforms demand temperature-stable barrier films with down-gauged thickness. Blown film extrusion advances enabling 0.3-mil construction without puncture failure are cutting resin input per unit across high-volume contracts.
- Healthcare:Pharmaceutical cold-chain packaging requires insulated pouch formats compatible with phase-change materials for vaccine distributors.
- Industrial:Liners and protective covers for manufacturing and logistics operations prioritize puncture resistance over aesthetic specifications.
Retail commands the broadest format diversity while food services drives the fastest specification evolution.
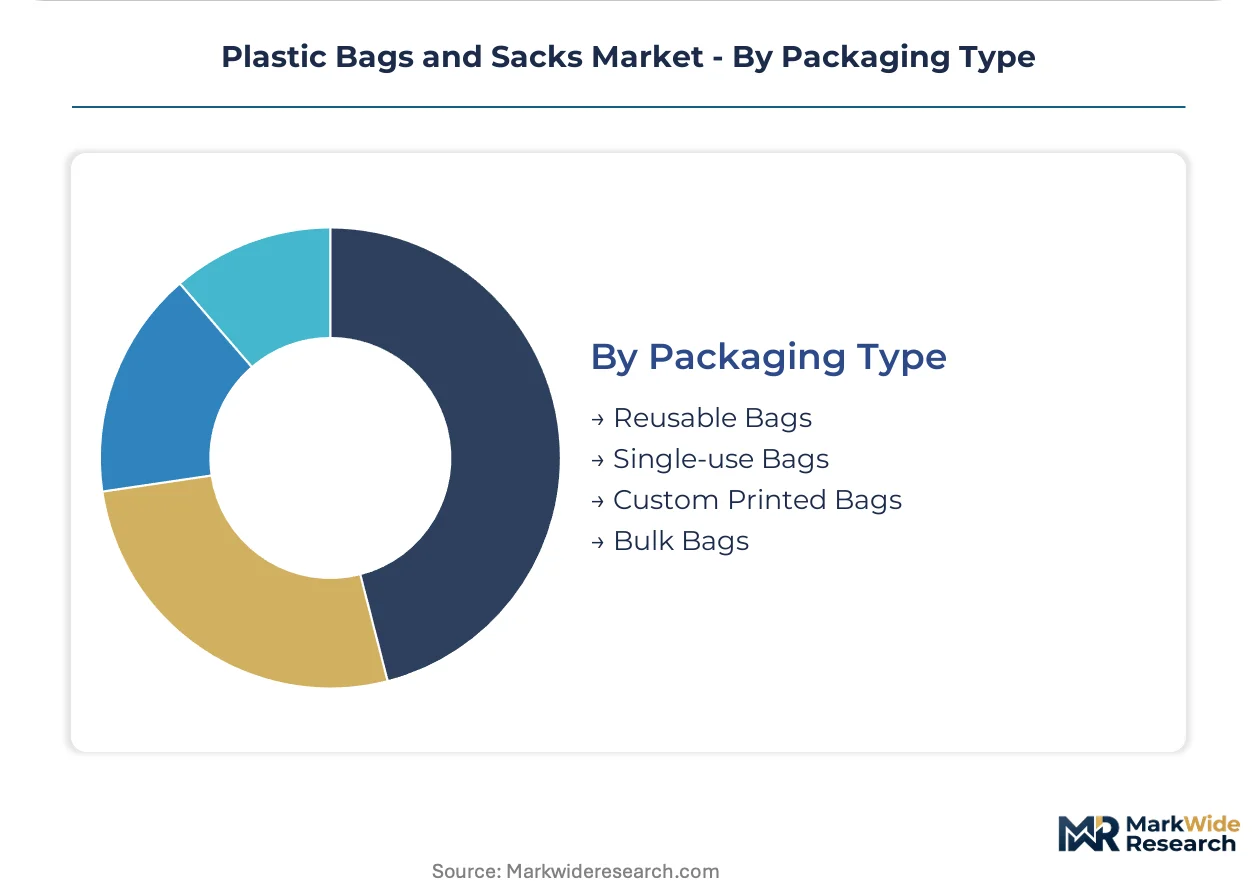
Packaging Type:
Volume scale and margin structure diverge sharply between single-use commodity supply and value-added custom formats.
- Single-use Bags:Virgin and recycled polyethylene formats face outright bans in France, Italy, and select US municipalities while remaining permissible in permissive jurisdictions. Converters maintain dual material portfolios and regional production footprints to navigate this regulatory fragmentation.
- Custom Printed Bags:Rotogravure and flexographic decoration serve brand-owner promotional requirements with higher unit economics and shorter production runs.
- Reusable Bags:Polypropylene totes and heavy-gauge polyethylene constructions capture regulatory-compliant share in retail carryout segments.
- Bulk Bags:Flexible intermediate bulk containers and large-format liners serve agricultural and chemical handling applications.
Single-use bags retain volume dominance while custom printed formats capture the most favorable margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern trade procurement managers in India, quick-service restaurant chains in California, and pharmaceutical distributors in Germany represent three distinct buyer archetypes pulling demand toward divergent material specifications and certification requirements.
United States
Quick-service restaurant chains and meal-kit delivery platforms in California and Washington specify certified compostable carryout formats at price premiums. EPA municipal solid waste frameworks and state-level plastic bag legislation create divergent compliance cost structures across coastal and inland markets. Manufacturing clusters in the Midwest and Southeast maintain dual material portfolios to serve both polyethylene-dependent and compostable-preferring customer segments.
Germany
Industrial composting infrastructure concentration supports certified compostable bag procurement from specialty grocers and institutional food service buyers. The EU Single-Use Plastics Directive and extended producer responsibility schemes under the EU Green Deal accelerate material transitions. Manufacturing facilities in North Rhine-Westphalia and Bavaria leverage proximity to chemical feedstock corridors for cost-competitive blown film extrusion.
India
Organized retail chains including Reliance Retail and BigBasket formalize bag procurement standards as modern trade expands into tier-two and tier-three urban centers. BIS standards and evolving state-level plastic waste management rules reshape converter compliance obligations. Manufacturing clusters in Maharashtra and Gujarat exploit domestic polyethylene resin availability to serve cost-sensitive procurement from rapidly formalizing retail networks.
China
Export-oriented converters supply North American and European retail chains with both conventional and certified compostable formats. GB standards and dual carbon goals pressure domestic producers toward lower-carbon film production methods. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta benefits from integrated resin-to-film supply chains serving global procurement contracts.
Vietnam
Cost-competitive blown film extrusion scales rapidly to serve Southeast Asian retail expansion and export demand from developed markets. The country's national environmental regulator implements plastic waste management frameworks that gradually tighten material specifications. Manufacturing clusters near Ho Chi Minh City and Hanoi attract investment from regional and international converters seeking feedstock proximity to petrochemical complexes.
Plastic Bags and Sacks Market Competitive Landscape
Player mix skews toward integrated multinational converters with captive resin supply agreements and regional specialists serving single-country procurement contracts. The competitive structure bifurcates between scale-driven commodity suppliers and certified-compostable specialists commanding formulation premiums. Two strategic archetypes dominate: vertically integrated resin-to-film producers defending high-volume grocery contracts, and technology-focused specialists capturing barrier-film applications in food service and healthcare. Capacity expansion in Indian and Southeast Asian manufacturing clusters and strategic partnerships for compostability certification represent the dominant competitive moves.
Among North American integrated converters, Berry Global Inc. and Novolex occupy positions exemplifying scale-driven commodity supply archetypes. Mondi Group represents the European paper-plastic hybrid specialist archetype navigating tightening packaging regulations. These three named entities anchor the competitive landscape without exhausting its diversity, as regional specialists in India, China, and Southeast Asia maintain significant share in geographically concentrated procurement contracts.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Novolex |
| Mondi Group |
| Inteplast Group |
| Ampac Holdings LLC |
| Bischof + Klein SE & Co. KG |
| Starlinger & Co Gesellschaft m.b.H. |
| Amcor plc |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
ASTM D6400 and EN 13432 certification regimes bifurcate supplier pools while simultaneously enabling price premiums for qualified converters. This dual-gate mechanism concentrates pricing power among certified producers in coastal metropolitan zones while compressing margins for commodity polyethylene suppliers serving inland markets without composting infrastructure.
Pricing Analysis
Cost-plus contracts with ethylene feedstock indexation dominate resin procurement for high-volume grocery and retail carryout applications. Three-tier pricing structure across certified compostable premium, food-grade barrier standard, and commodity virgin polyethylene economy levels reflects certification investment recovery and barrier performance differentiation. Cost compression in commodity flat bag tiers is intensifying because Indian and Vietnamese manufacturing clusters exploit feedstock proximity to undercut legacy North American converters. Quick-service restaurant chains in California and Washington demonstrate lowest price sensitivity, accepting 15-25% premiums for certified compostable specifications, while tier-two Indian retail procurement remains most cost-driven.
Supply Chain Analysis
Inventory cycles for certified compostable grades extend 6-12 months due to ASTM D6400 testing timelines, constraining working capital velocity for converters pursuing qualification. Manufacturing gravity centers on India, Vietnam, and China where blown film extrusion scales rapidly to serve both domestic retail expansion and export demand from regulated markets. Raw material sourcing draws from polyethylene resin contracts tied to naphtha and natural gas liquid indices, with polylactic acid and polyhydroxyalkanoate formulations increasingly sourced from specialized fermentation and biopolymer producers. Tariff exposure on Chinese film imports into North American markets represents the dominant structural supply risk. Distribution runs through centralized procurement consortiums including the Sustainable Packaging Coalition's harmonized specification networks, consolidating buyer power across Kroger, Albertsons, and Ahold Delhaize retail systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive and parallel state-level mandates across California, Washington, and Vermont constitute a regulatory inflection accelerating material transitions and compressing timelines for certification investment recovery.
For Market Incumbents: Shield high-volume grocery contracts through backward integration into resin supply agreements and captive blown film extrusion capacity in Midwest and Southeast manufacturing clusters. Prioritize ASTM D6400 and EN 13432 certification pipeline investment to defend margin position against emerging biodegradable specialists. Channel control through exclusive supply arrangements with quick-service restaurant chains provides defensive moats as regulatory bans proliferate. For New Entrants and Emerging Players: Composting infrastructure gaps in tier-two US markets and inland European corridors represent service-layer white-space where incumbents under-serve. Target pharmaceutical cold-chain packaging segments requiring phase-change material compatibility, where barrier film expertise commands premium economics and incumbent concentration remains lowest. Pursue white-label manufacturing partnerships with Indian organized retail chains formalizing procurement standards as modern trade expands beyond tier-one cities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across certified compostable production lines due to fermentation-based biopolymer feedstock requirements and extended qualification timelines. Five-to-ten year viability hinges on regulatory ban schedule acceleration rather than organic demand growth. Acquisition target archetype: regional specialists in India and Southeast Asia with established BIS or GB standard compliance and relationships with rapidly formalizing retail networks. Monitor industrial composting facility build-out announcements in US inland corridors as inflection indicator for certified compostable addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Investment | ASTM D6400 qualification opens California and Washington municipal procurement to premium pricing. |
| Backward Integration into Resin Supply | Captive polyethylene feedstock agreements insulate Midwest converters from ethylene price volatility. |
| Indian Manufacturing Footprint Expansion | Maharashtra and Gujarat clusters exploit domestic resin availability for cost-competitive export supply. |
| Pharmaceutical Cold-Chain Format Development | Phase-change material compatibility captures vaccine distributor demand from specialized biologics shippers. |
| Extended Producer Responsibility Credit Optimization | France's CITEO eco-modulation scheme rewards post-consumer recycled content with fee reductions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association disclosures. Conversations with blown film extrusion plant managers, retail procurement leads at organized chains, distribution channel partners, and technical R&D directors at biopolymer suppliers informed demand-side and supply-side calibration. Secondary validation drew from EPA municipal solid waste reports, EU Single-Use Plastics Directive implementation trackers, BIS standard publications, and SEC filings from listed packaging converters. Bottom-up volume builds from individual facility capacity and utilization estimates triangulated against top-down demand segmentation from end-use consumption patterns.
Segmentation dimensions modeled include material type, product format, end-use application, and regional regulatory cluster across the projection horizon. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for regulatory inflection impacts and material substitution elasticities. Industry-specific forecast inputs incorporated blown film extrusion down-gauging adoption curves, industrial composting facility build-out pipelines, and organized retail penetration rates in Indian tier-two and tier-three urban centers.
Underlying assumptions cover regulatory ban schedule adherence, ethylene feedstock price band stability, and certification timeline normalization, with deviation risk concentrated in municipal composting infrastructure deployment delays and biopolymer fermentation scale-up bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Breather Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Net Bags Market
Bags and Containers
Portion Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Flat Bottom Bags Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Bulk Tote Dumpers Market