
 Industrial Plastic Bags Market | 2026-2036
Industrial Plastic Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Plastic Bags Market Foresight
Subscription-based liner programs for bulk chemical transport is pivoting how industrial buyers procure containment solutions. Dow Chemical leverages captive polyethylene supply chains to dominate resin-grade bag production. Berry Global sustains leadership through multi-layer coextrusion technology for barrier-sensitive applications. Inteplast Group anchors North American distribution with vertically integrated film-to-bag manufacturing.
Industrial plastic bags are engineered film containers, typically 1-8 mil in thickness, manufactured through blown film extrusion or cast film processes using polyethylene resins to protect, store, and transport bulk solids and liquids. Gusseted bags accommodate irregular geometries in chemical and agricultural handling, while ziplock configurations command premium positioning in electronics and pharmaceutical sampling. Heavy duty and extra heavy duty thickness grades capture disproportionate margin pools due to specialized resin formulations and certification requirements for hazardous material containment.
EPA hazardous waste manifest rules, OSHA workplace chemical exposure limits, and EU REACH substance restrictions collectively elevate compliance costs and favor certified suppliers with documented chain-of-custody protocols. BIS certification requirements in India and FDA food contact regulations in the United States create divergent testing burdens that regional specialists navigate more efficiently than global generalists. Stakeholders must monitor how extended producer responsibility frameworks in Europe and state-level plastic bans in the United States reshape specifications for virgin versus recycled content ratios.
Market Dynamics
Recycled content mandates from the EU Green Deal are forcing resin-grade suppliers to reconfigure virgin-to-reblend ratios across entire production networks. This regulatory pressure cascades through specification sheets, procurement contracts, and certification documentation faster than capacity retooling permits.
Growth Catalysts
- E-commerce fulfillment scale:Food packaging demand from automated distribution centers drives heavy-duty gusseted specifications for bulk dry goods handling.
- India PLI scheme:Domestic manufacturing incentives accelerate blown film extrusion capacity additions for export-grade chemical containment applications.
- REACH substance restrictions:EU hazardous material documentation requirements favor certified suppliers with chain-of-custody protocols over uncertified competitors.
Market Restraints
- Polyethylene resin volatility:Naphtha-derived feedstock costs swing with crude oil benchmarks, compressing margin predictability for converters.
- Single-supplier concentration:Captive ethylene supply chains at integrated petrochemical majors limit independent access to virgin resin grades.
- Mechanical recycling contamination:Post-consumer film feedstock carries adhesive and ink residues that degrade reprocessed mechanical properties.
Strategic Opportunities
- Chemical subscription liner programs:Bulk transport buyers are pivoting from spot purchases to recurring containment service agreements.
- India BIS certification gap:Domestic testing infrastructure lags demand, creating first-mover advantage for laboratories with accredited film-testing capability.
- Multi-layer coextrusion convergence:Barrier film technology from pharmaceutical packaging migrates into agricultural chemical containment with oxygen and moisture specifications.
Industry Challenges
- Blown film technician scarcity:Die gap calibration and bubble stability expertise concentrates among aging workforces in mature manufacturing regions.
- Extended producer responsibility integration:EU packaging waste directives require traceability systems that legacy ERP platforms cannot support without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Plastic Bags Market |
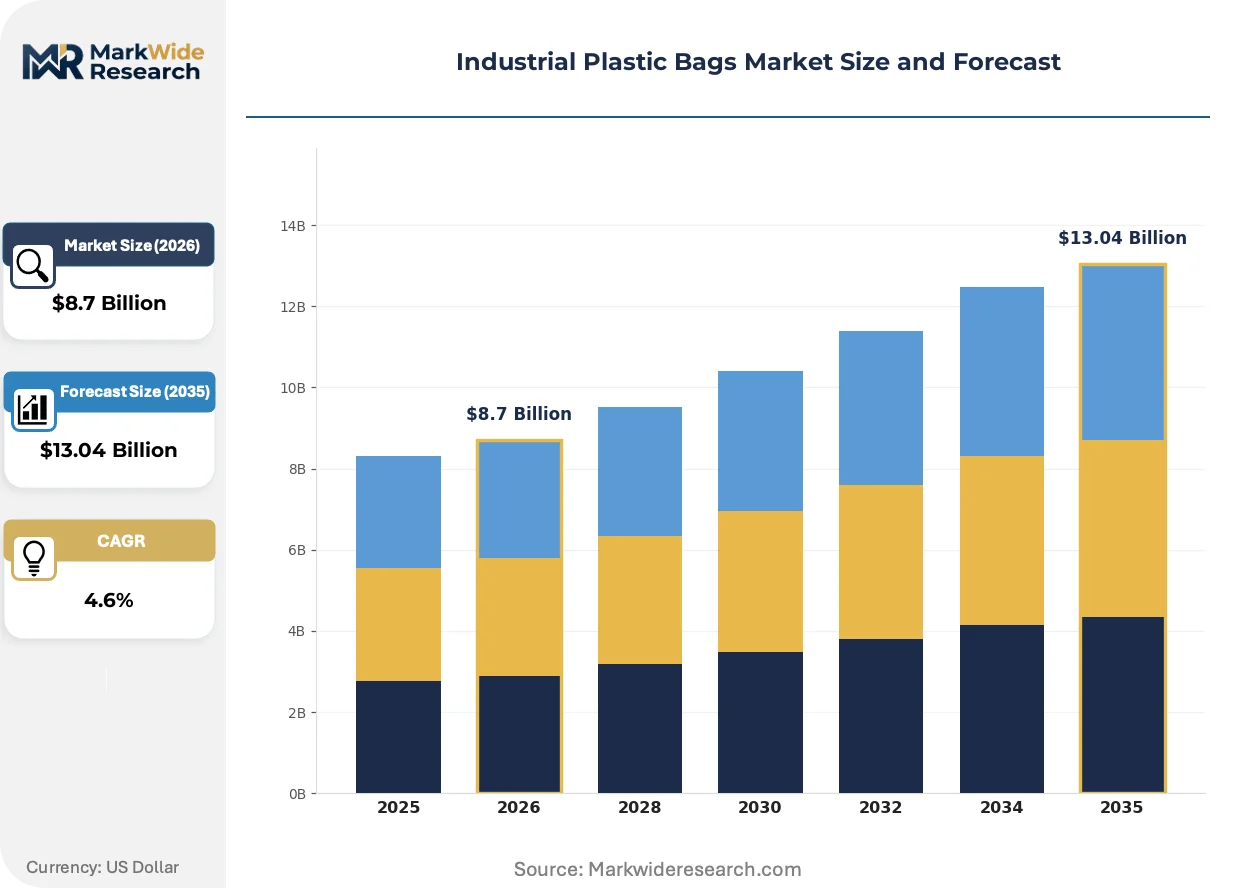
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, T-Shirt Bags, Ziplock Bags Material: HDPE, LDPE, LLDPE, Recycled Plastic End User: Food Packaging, Chemical Industry, Retail, Electronics Thickness: Lightweight, Medium, Heavy Duty, Extra Heavy Duty |
| Companies Covered | Dow Chemical, SABIC, Amcor, Inteplast Group, Uflex, Berry Global, LyondellBasell, ProAmpac, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Plastic Bags Market Shifts & Advancements
Material science advances and procurement model experimentation are compressing traditional specification boundaries between commodity and performance-grade films. Buyers now evaluate total cost of containment rather than unit bag economics.
Post-industrial recycled polyethylene is decentralizing supply chain geography for non-food contact applications. Agricultural chemical distributors in the US Midwest are adopting 30% reblend content for non-hazardous fertilizer handling. This shift reduces resin transportation miles and enables regional compounding operations to compete with Gulf Coast virgin resin suppliers.
EU Green Deal recycled content mandates are rewriting procurement specifications for virgin versus reblend ratios. Brand owners now require mass-balance documentation through entire converter networks. Food contact applications face the strictest verification burdens, pushing technical development investment toward chemical and agricultural segments where regulatory tolerance for reprocessed content remains higher.
Buyer concentration among third-party logistics providers is consolidating specification authority away from end-users. Amazon Fulfillment and similar operators now dictate mil thickness, print registration, and pallet configuration standards that converters must meet for network eligibility. This standardization reduces SKU complexity but compresses margin for customized short-run production.
Industrial Plastic Bags Market Segmentation
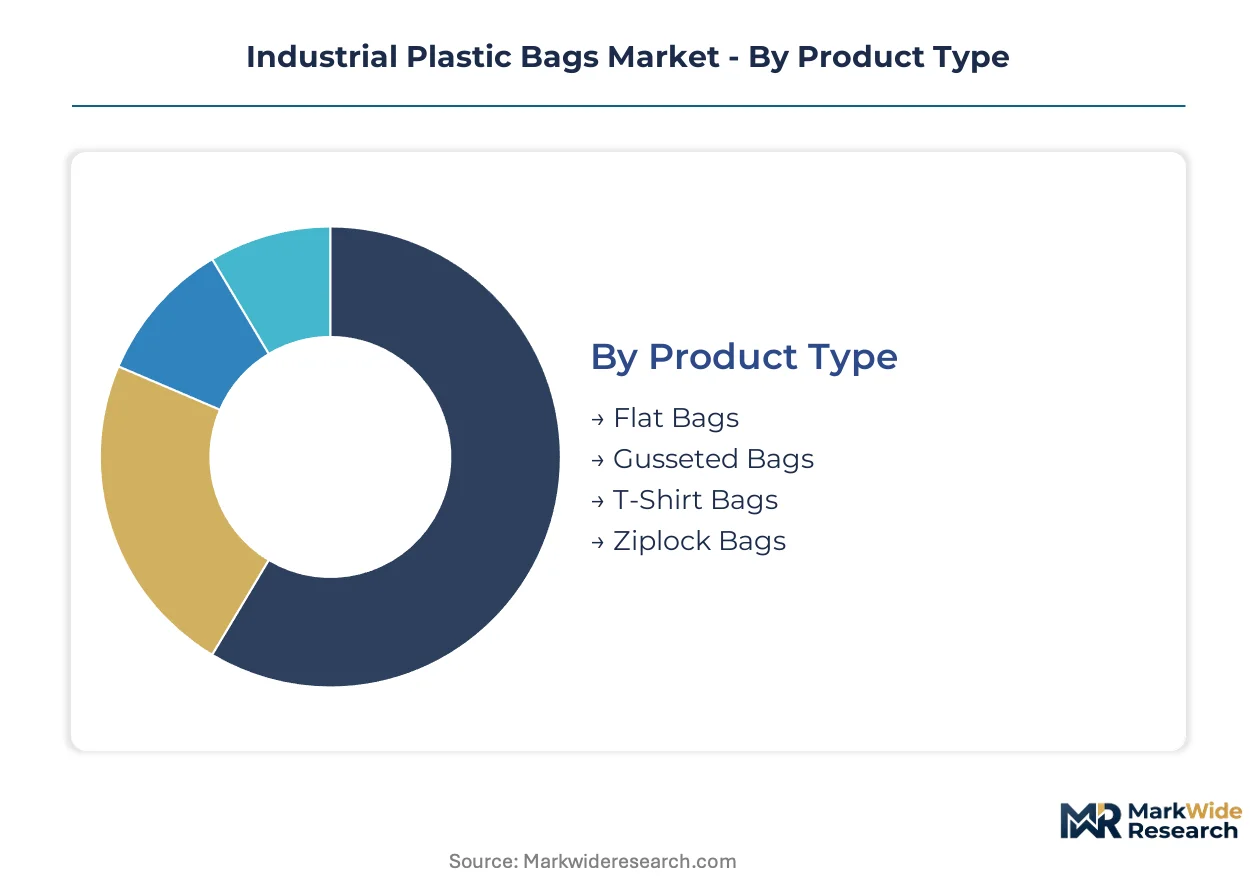
Industrial plastic bag procurement operates across incompatible specification regimes. Food contact mandates, hazardous material containment standards, and automated handling requirements create divergent technical baselines that reshape converter specialization and margin structure.
Product Type:
Buyers select configurations based on load geometry, handling automation, and reseal requirements rather than commodity price alone.
- Gusseted Bags:Side and bottom folds expand cubic capacity for irregular bulk solids. Chemical distributors in India specify these for fertilizer and pesticide handling under BIS certification requirements.
- Ziplock Bags:Interlocking closure strips enable repeated access without contamination. Electronics manufacturers in South Korea and pharmaceutical samplers in Switzerland pay premium positioning for moisture-barrier coextruded variants.
- Flat Bags:Two-dimensional sealing suits automated filling lines for dry goods.
- T-Shirt Bags:Die-cut handles accommodate manual carrying in retail and last-mile distribution.
Volume sits with Gusseted Bags for bulk industrial handling; growth tilts toward Ziplock Bags as barrier specifications migrate from pharmaceutical into electronics sampling.
Material:
Resin selection traces regulatory tolerance for recycled content against performance requirements.
- LLDPE:Linear low-density polyethylene delivers puncture resistance and seal strength for automated packaging lines. EU Green Deal mass-balance documentation requirements now complicate procurement of virgin grades for food contact.
- Recycled Plastic:Post-industrial regrind and post-consumer flake feedstocks carry adhesive and ink contamination that limits mechanical property retention. Agricultural chemical distributors in the US Midwest accept 30% reblend for non-hazardous fertilizer handling where FDA food contact rules do not apply.
- HDPE:High-density formulation provides stiffness for stack stability in palletized chemical transport.
- LDPE:Low-density grades offer clarity and flexibility for retail display applications.
Supply concentrates with LLDPE for performance-critical specifications; regulatory pressure is accelerating recycled plastic adoption fastest in non-food segments.
End User:
End-use determines certification burden, thickness grade, and barrier layer complexity.
- Food Packaging:FDA and EFSA compliance mandates migration testing for additives and residual monomers. Automated fulfillment centers operated by third-party logistics providers now dictate mil thickness and pallet configuration standards.
- Chemical Industry:EPA hazardous waste manifest rules and OSHA exposure limits require documented chain-of-custody protocols. Heavy duty and extra heavy duty thickness grades capture disproportionate margins due to specialized resin formulations.
- Retail:Thin-gauge configurations compete on unit economics for high-volume checkout and promotional applications.
- Electronics:Static-dissipative and moisture-barrier specifications protect sensitive components during global supply chain transit.
Revenue concentrates with Food Packaging for volume scale; margin expansion tilts toward Chemical Industry as containment certification requirements intensify.
Thickness:
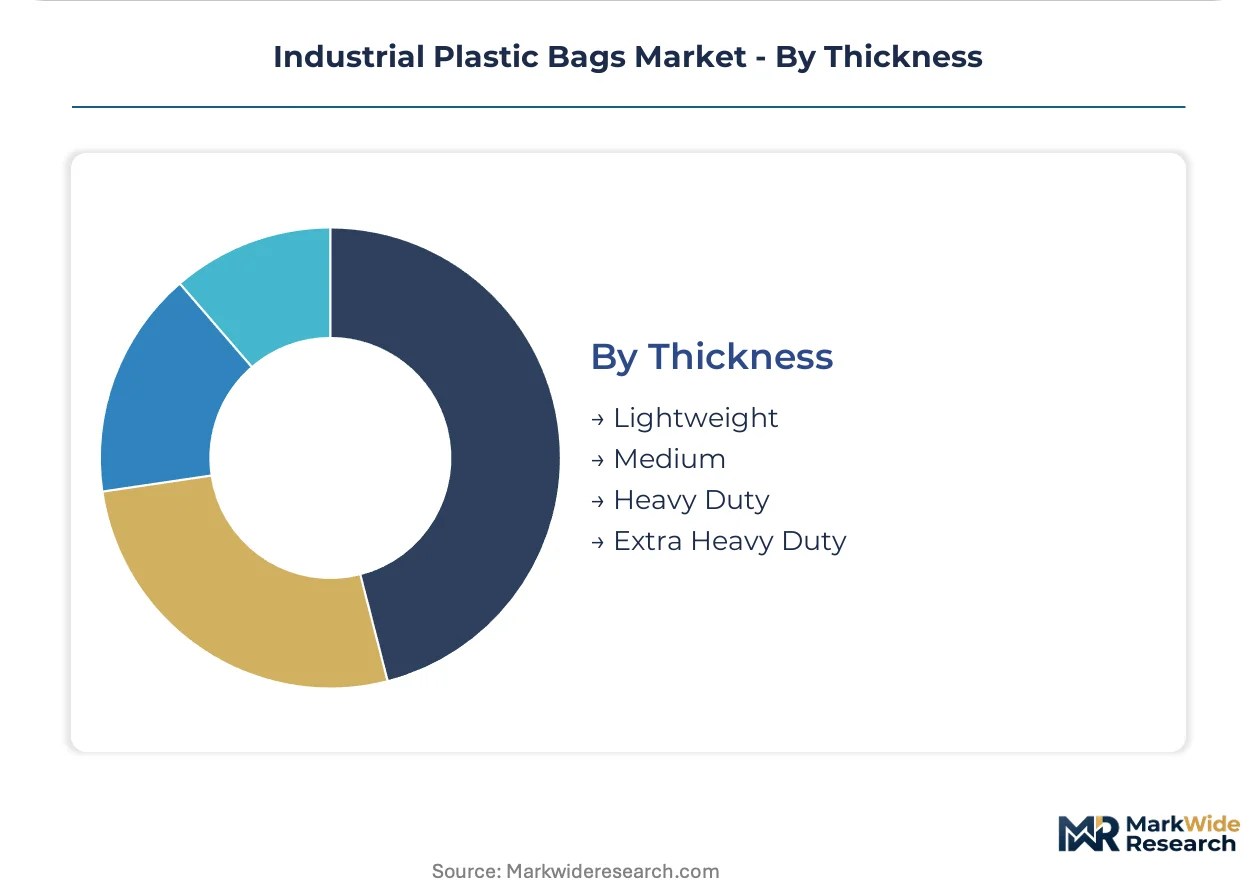
Thickness grade selection maps directly to load weight, puncture risk, and regulatory containment obligations.
- Heavy Duty:4-6 mil construction handles abrasive mineral and construction materials. REACH substance restrictions in Europe favor certified suppliers with documented resin sourcing over uncertified competitors.
- Extra Heavy Duty:6-8 mil and above specifications meet UN-certified hazardous material transport requirements. The India PLI scheme accelerates domestic blown film capacity for export-grade chemical containment at this thickness tier.
- Lightweight:1-2 mil suits single-use retail and promotional applications.
- Medium:2-4 mil balances cost and durability for general industrial handling.
Unit economics favor Medium thickness for commodity applications; specification authority concentrates with Extra Heavy Duty as hazardous material compliance costs reshape procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in petrochemical corridors while consumption spreads across manufacturing belts and agricultural zones. The mismatch between resin supply and bag fabrication creates freight arbitrage opportunities for regional converters.
United States
Gulf Coast ethylene crackers feed blown film extrusion clusters along the Houston Ship Channel. EPA hazardous waste manifest rules elevate compliance costs for chemical containment specifications. Midwest agricultural distributors in Iowa and Illinois adopt 30% recycled content blends for fertilizer handling.
Germany
Automotive component suppliers in Baden-Württemberg demand static-dissipative specifications for electronics transit packaging. EU Green Deal mass-balance documentation requirements complicate virgin resin procurement for food contact applications. The Ruhr industrial corridor hosts specialized converters serving REACH-compliant chemical containment.
China
E-commerce fulfillment centers in Yangtze River Delta cities drive heavy-duty gusseted bag consumption for bulk dry goods. GB standards for food contact migration testing diverge from FDA protocols, creating specification friction for export-oriented fabricators. Zhejiang province concentrates cast film capacity for retail display applications.
India
BIS certification requirements accelerate domestic blown film capacity additions under the PLI scheme. Agricultural chemical distributors in Maharashtra and Gujarat specify extra heavy duty grades for pesticide handling. Gujarat's petrochemical belt integrates forward into bag fabrication for export-grade chemical containment.
South Korea
Electronics manufacturers in Gyeonggi-do province procure moisture-barrier ziplock configurations for semiconductor component sampling. MFDS food contact regulations align with EFSA standards, easing specification overlap for converters serving both markets. Busan-Ulsan corridor combines resin production with specialized film extrusion for barrier-sensitive applications.
Industrial Plastic Bags Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Integrated petrochemical majors with captive ethylene supply chains dominate virgin resin-grade production. Independent converters rely on spot resin markets and recycled feedstock arbitrage. Three archetypes define competitive positioning: resin-integrated volume players, technology-specialized barrier film houses, and regionally anchored distribution specialists. Capacity expansion and backward integration into resin sourcing represent the dominant competitive moves.
Among resin-integrated majors, Dow Chemical and LyondellBasell exemplify the scale-driven archetype through Gulf Coast ethylene infrastructure. Berry Global occupies a position within the technology-specialized tier, representing multi-layer coextrusion capability for barrier-sensitive end uses. Inteplast Group anchors the North American distribution-focused archetype with film-to-bag manufacturing integration. These three patterns illustrate how supply chain configuration determines specification authority and margin capture across thickness grades and certification tiers.
| Leading Market Players |
|---|
| Dow Chemical |
| SABIC |
| Amcor |
| Inteplast Group |
| Uflex |
| Berry Global |
| LyondellBasell |
| ProAmpac |
| Huhtamaki |
| Others |
Supply & Pricing Matrix
EU Green Deal recycled content mandates gate qualified supply access and premium-tier pricing authorization across converter networks. Buyers lacking mass-balance documentation face exclusion from food-contact procurement pools, while certified suppliers command margin premiums for documented chain-of-custody protocols.
Pricing Analysis
Margin tightening in extra heavy duty grades reflects specialized resin formulations and UN certification burdens. Three-tier pricing structure across premium certified, standard industrial, and economy retail levels separates buyers by compliance tier and volume commitment. Price differentiation traces to REACH documentation depth and BIS certification status. Spot resin volatility compresses converter margins most acutely for non-integrated players lacking captive ethylene supply.
Supply Chain Analysis
Polyethylene resin supply rests on Gulf Coast ethylene crackers, Saudi petrochemical complexes, and Indian naphtha-based production. Blown film extrusion draws from linear low-density pellets, high-density grades for stack stability, and post-industrial regrind for non-food applications. Single-source concentration at integrated majors creates vulnerability for independent converters. Distribution runs through regional fabricators serving agricultural chemical distributors and third-party logistics fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive resin supply and accredited testing infrastructure determine specification authority. Players lacking upstream control or certification capability face margin compression and network exclusion.
For Market Incumbents: Anticipate mechanical recycling contamination limits by securing post-industrial regrind contracts before feedstock competition intensifies. Deepen backward integration into regional compounding operations to offset virgin resin volatility. Defend position through BIS-accredited laboratory investment in India, where testing infrastructure lags PLI-scheme capacity expansion.
For New Entrants and Emerging Players: E-commerce fulfillment procurement portals offer direct channel access bypassing established distributor relationships. Target agricultural chemical segments in the US Midwest, where 30% reblend tolerance and non-food regulatory exposure lower certification barriers. Pursue subscription-based liner service models that convert spot buyers to recurring revenue relationships.
For Investors and Strategic Acquirers: First-mover BIS laboratory accreditation in India is the leading indicator that domestic certification capacity will consolidate around early entrants. Position for five-to-ten year horizon through specialized barrier film converters with multi-layer coextrusion capability. Monitor extended producer responsibility implementation timelines as the inflection signal for traceability system investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Gulf Coast ethylene infrastructure secures margin predictability against naphtha volatility. |
| Multi-Layer Coextrusion Capacity Expansion | Berry Global's barrier technology migration opens pharmaceutical and electronics containment pools. |
| BIS Certification Laboratory Investment | India's PLI-scheme capacity additions outpace accredited testing infrastructure availability. |
| Subscription Liner Program Launch | Dow Chemical's captive supply chains support recurring containment service agreements for chemical transport. |
| Post-Industrial Recycled Feedstock Contracts | Midwest agricultural distributors adopt 30% reblend specifications ahead of food-contact mandates. |
Research Methodology
Independent corroboration across blown film plant managers, procurement leads at agricultural chemical distributors, third-party logistics specification directors, and resin trading desk analysts underwrites the qualitative findings. Secondary validation draws from customs trade data, ACC resin production reports, SEC 10-K filings of integrated petrochemical majors, and BIS certification registry records. Bottom-up capacity tallies triangulate against top-down consumption estimates from end-use industry associations.
Rate-of-change decomposition separates volume growth across thickness grades, material types, end-use industries, and regional production hubs. The analytical framework models penetration trajectories for recycled content adoption against regulatory enforcement timelines. CAGRs derive from elasticity-adjusted demand projections and capacity expansion schedules. Key inputs include EU Green Deal implementation pacing, India PLI scheme disbursement velocity, and polyethylene resin price correlation coefficients with crude benchmarks.
The model holds under stable regulatory enforcement and resin supply continuity; deviation in mechanical recycling feedstock quality standards or extended producer responsibility acceleration would shift converter margin structures. Forecasts reflect documented assumptions about certification timeline adherence and petrochemical capacity utilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Dunnage Racks Market