
 North America Biodegradable Paper and Plastic Packaging Market | 2026-2036
North America Biodegradable Paper and Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biodegradable Paper and Plastic Packaging Market Analytics
Buyer concentration in North American food service and quick-service restaurant chains is shifting toward centralized sustainable procurement mandates that favor certified compostable packaging. Smurfit WestRock leverages its integrated pulp-to-box infrastructure to dominate corrugated biodegradable formats for perishable goods. Mondi competes through specialized kraft paper and flexible film solutions engineered for high-moisture food applications. Packaging Corporation of America anchors its position with containerboard assets strategically located near Midwest agricultural processing hubs.
Biodegradable paper and plastic packaging comprises fiber-based substrates, polylactic acid films, and starch-derived polymers engineered to decompose under industrial composting or marine biodegradation conditions per ASTM D6400 and D6866 specifications. Flexible packaging leads volume adoption due to its compatibility with existing form-fill-seal equipment across food packaging lines, while rigid containers command premium positioning in personal care and electronics applications where dimensional stability protects high-value goods. PLA and pulp materials capture the fastest growth trajectory as brand owners eliminate petroleum-based barriers from primary packaging layers.
The U.S. EPA, California's Department of Resources Recycling and Recovery, and Canada's Competition Bureau collectively shape demand through compostability labeling standards, extended producer responsibility frameworks, and greenwashing enforcement actions that disqualify non-certified environmental claims. ASTM International and the Biodegradable Products Institute certification programs function as de facto market access gates for suppliers seeking national distribution through major retail and food service channels. Stakeholders must monitor pending state-level packaging reduction mandates and federal procurement preference rules that will restructure supplier qualification criteria without warning.
Market Dynamics
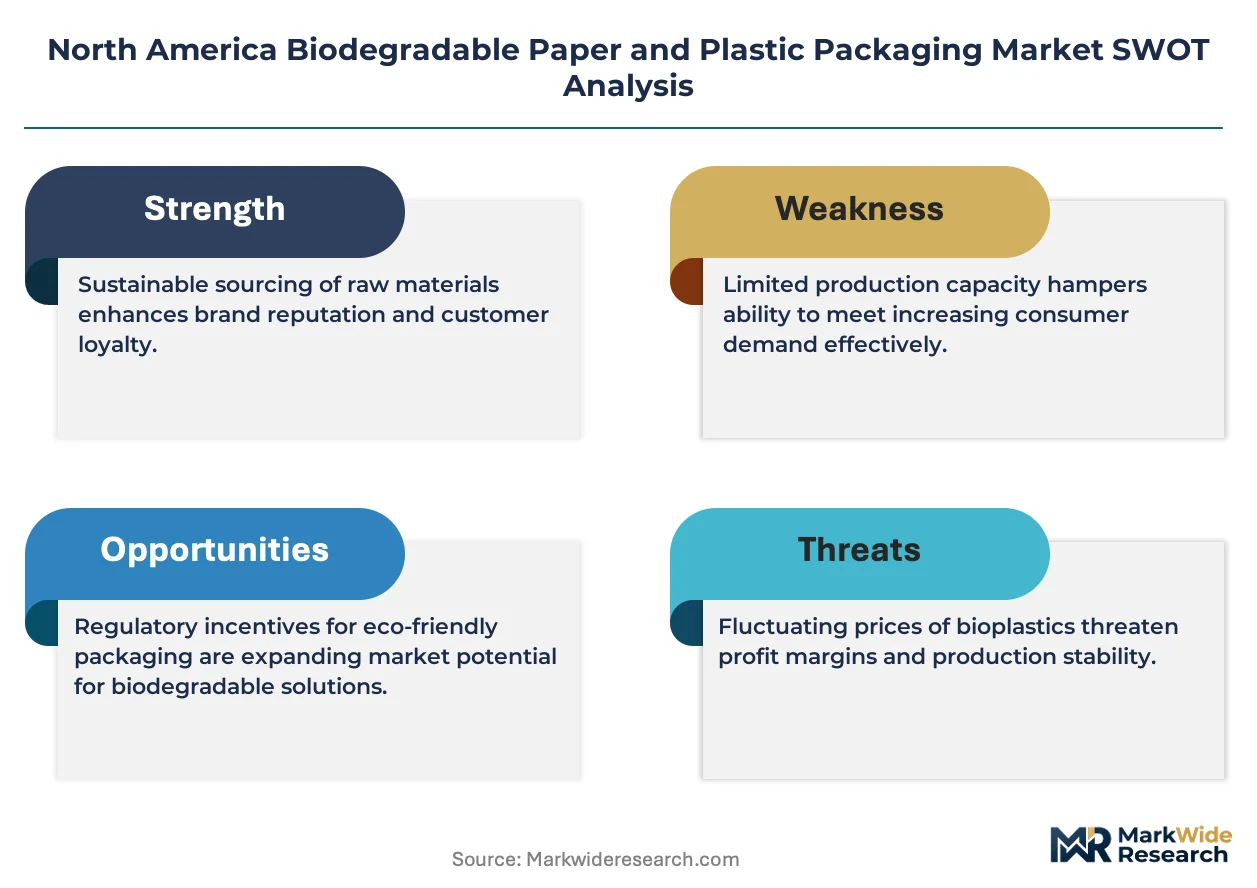
California's extended producer responsibility laws are forcing rapid material substitution across food service supply chains, compressing the timeline for petroleum-based packaging phase-out and creating certification bottlenecks at industrial composting facilities.
Growth Catalysts
- State-level packaging mandates:California's SB 54 and New York's extended producer responsibility frameworks mandate post-consumer recycled content thresholds that accelerate compostable material procurement.
- Quick-service restaurant chains:Centralized sustainable sourcing mandates at major food service operators favor ASTM D6400-certified suppliers with national distribution capacity.
- Industrial composting infrastructure:Facility expansion in the Great Lakes corridor and Pacific Northwest creates geographic coverage for certified biodegradable waste streams.
Market Restraints
- PLA resin supply concentration:Polylactic acid feedstock relies on corn starch from Midwest agricultural processors, exposing pricing to commodity crop volatility and ethanol market competition.
- Composting facility access gaps:Industrial composting capacity concentrates in coastal states, leaving interior markets without end-of-life infrastructure for certified materials.
- Performance limitations in high-moisture applications:Fiber-based barriers exhibit shortened shelf-life stability compared to conventional polyethylene in refrigerated protein packaging.
Strategic Opportunities
- Mexico manufacturing integration:Cross-border supply chain reconfiguration near Mexico City's food processing corridor reduces landed costs for US Southwest distribution.
- E-commerce protective packaging:Void-fill and cushioning applications for electronics and personal care represent underpenetrated demand outside food service.
- Federal procurement preference rules:Pending updates to EPA sustainable materials management guidelines would mandate compostable packaging for government food service contracts.
Industry Challenges
- BPI certification backlog:Third-party verification timelines stretch six to nine months, delaying product launches and locking out suppliers without pre-certified material libraries.
- Legacy equipment retrofit costs:Form-fill-seal lines engineered for petroleum-based films require temperature and tension recalibration to run PLA without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biodegradable Paper and Plastic Packaging Market |
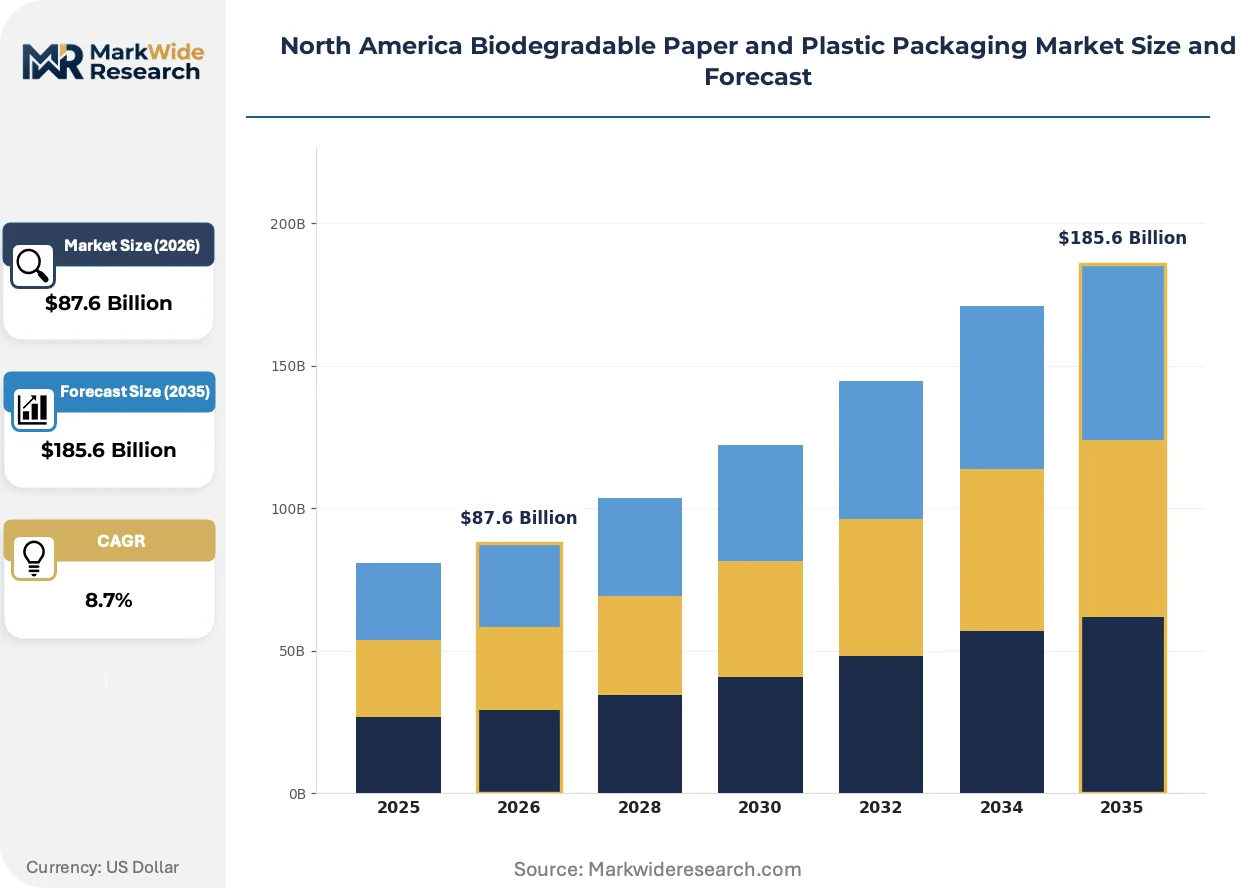
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Pouches, Containers Material: Pulp, PLA, Starch, Mica Application: Food Packaging, Consumer Goods, Personal Care, Electronics End User: Retail, Food Service, E-Commerce, Healthcare |
| Companies Covered | Smurfit WestRock, Mondi, Amcor PLC, Tetra Pak International SA, Kruger Inc., International Paper Company, Packaging Corporation of America, Graphic Packaging International Inc., Cascades Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biodegradable Paper and Plastic Packaging Market Evolving Landscape
Material science advances and regulatory compression are collapsing the performance gap between biodegradable and conventional packaging, while procurement centralization at food service chains favors suppliers with integrated certification and geographic coverage.
Barrier-coated molded fiber technology is modularizing the protective packaging category by replacing expanded polystyrene in electronics and appliance applications. Major e-commerce fulfillment operators in the Pacific Northwest and Texas are piloting these formats for damage-prone shipments. The technology is modularizing what had been a petroleum-dependent supply base into regionally sourced pulp networks with composting partnerships.
The EPA's evolving sustainable materials management priorities and state-level truth-in-labeling enforcement are disqualifying non-certified environmental claims from national retail distribution. Industrial composting operators now reject loads with contamination rates above specified thresholds, forcing packaging engineers to eliminate conventional adhesive and ink systems. Food service chains operating across multiple states face the strictest compliance burden as they harmonize specifications to the most restrictive jurisdiction.
Centralized procurement at quick-service restaurant chains is consolidating supplier relationships around vendors with multi-format certification and coast-to-coast logistics. Regional distributors that previously stocked multiple material grades are narrowing portfolios to pre-qualified national suppliers. This consolidation is most visible in the California Central Valley packaging cluster, where three buyers now represent the majority of compostable container volume and dictate specification standards upstream.
North America Biodegradable Paper and Plastic Packaging Market Segmentation
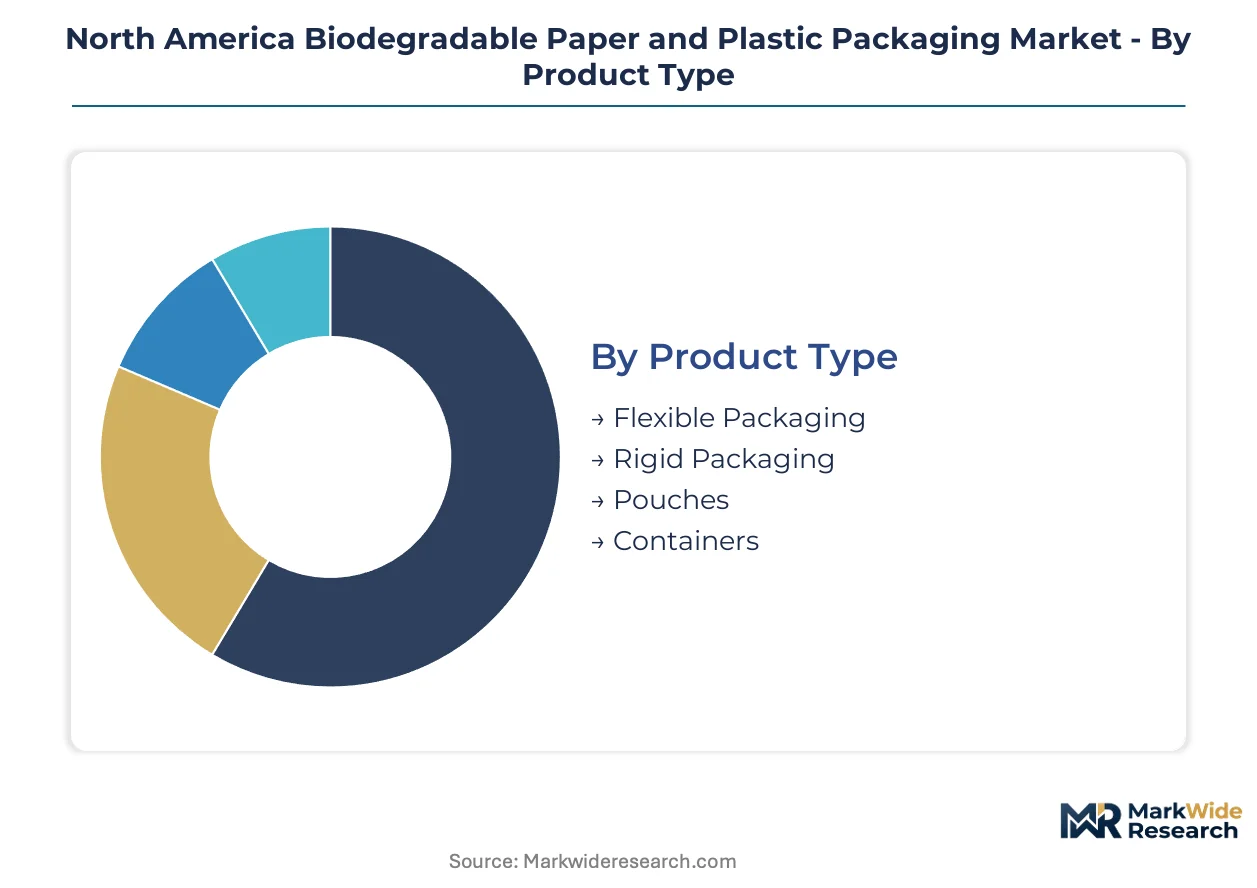
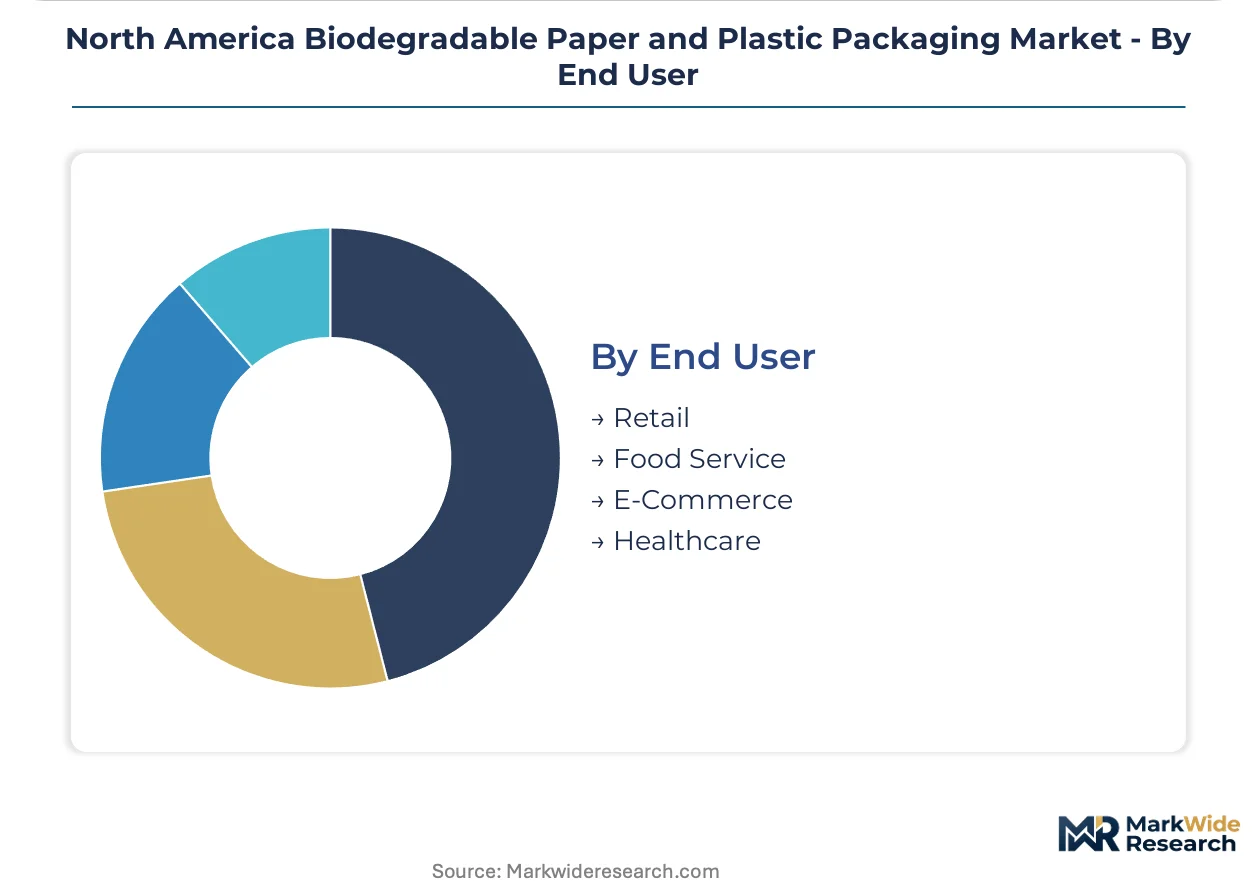
Segmentation in the North America biodegradable packaging market reveals how procurement mandates, composting infrastructure gaps, and performance requirements reshape supplier priorities. Buyers prioritize ASTM D6400-certified formats compatible with existing food service equipment and regional composting access.
Product Type:
Buyers differentiate by equipment compatibility and shelf-life performance demands across temperature-sensitive supply chains.
- Flexible Packaging:Roll-stock films and bags engineered from PLA and kraft-laminate structures run on standard form-fill-seal lines. Quick-service restaurant chains in California's Central Valley procurement cluster specify flexible formats for grab-and-go items, though high-moisture protein applications face barrier limitations.
- Rigid Packaging:Thermoformed trays, clamshells, and injection-molded containers deliver dimensional stability for fragile goods. Electronics fulfillment operators in the Pacific Northwest pilot molded fiber rigid formats to replace expanded polystyrene in damage-prone shipments.
- Pouches:Stand-up and flat pouches with compostable zipper closures serve dry goods and shelf-stable snacks. The format requires specialized sealing equipment calibration.
- Containers:Deli bowls, hinged-lid boxes, and portion cups address food service takeaway demand. Midwest agricultural processing hubs supply molded fiber feedstock for regional container manufacturing.
Volume sits with Flexible Packaging; growth tilts toward Rigid Packaging.
Material:
Cost tier and certification timeline separate buyers, with national food service chains demanding pre-certified material libraries.
- Pulp:Molded fiber from agricultural residues and recycled paperboard offers the broadest industrial composting acceptance. Barrier-coated pulp formats are displacing polystyrene in electronics protective packaging across Texas and Pacific Northwest distribution centers.
- PLA:Polylactic acid derived from Midwest corn starch provides clarity and heat resistance for cold beverage cups and deli containers. Corn crop volatility and ethanol market competition expose pricing to commodity swings.
- Starch:Thermoplastic starch blends offer lower cost positioning for short-shelf-life applications. The material exhibits moisture sensitivity limiting use in refrigerated distribution.
- Mica:Mineral-reinforced biocomposites provide gas barrier properties for oxygen-sensitive goods. Commercial scale-up remains constrained by processing equipment compatibility.
Pulp commands current volume leadership; PLA climbs the fastest on food service chain procurement mandates.
Application:
Regulatory pressure intensity varies by application, with food packaging facing the strictest state-level extended producer responsibility compliance.
- Food Packaging:Primary and secondary packaging for fresh, prepared, and shelf-stable foods drives certification demand. California's SB 54 mandates accelerate compostable substitution in quick-service and grocery retail channels.
- Consumer Goods:Household products and dry goods packaging favors fiber-based formats with lower barrier requirements. E-commerce protective applications for non-food consumer goods remain underpenetrated relative to food service.
- Personal Care:Rigid containers for cosmetics and personal hygiene products command premium positioning where dimensional stability protects high-value formulations.
- Electronics:Void-fill, cushioning, and molded fiber protective formats replace petroleum-based alternatives in fulfillment operations. Barrier-coated molded fiber technology is modularizing this historically petroleum-dependent supply base.
Food Packaging anchors volume concentration; Electronics protective applications expand most quickly on e-commerce fulfillment pilot programs.
End User:
Procurement centralization and sustainability mandate stringency separate buyer categories.
- Retail:Grocery chains and mass merchandisers specify certified compostable formats for private-label and fresh departments. Truth-in-labeling enforcement by the EPA and state attorneys general disqualifies non-certified environmental claims from national distribution.
- Food Service:Quick-service restaurant chains and institutional food operators drive centralized sustainable sourcing mandates. Three buyers in the California Central Valley packaging cluster now represent the majority of compostable container volume.
- E-Commerce:Fulfillment operators pilot biodegradable void-fill and protective formats for damage reduction. The Great Lakes corridor and Pacific Northwest industrial composting infrastructure supports end-of-life processing for certified materials.
- Healthcare:Medical device and pharmaceutical packaging faces sterility and barrier performance requirements that biodegradable formats have not yet satisfied at commercial scale.
Food Service concentrates procurement volume; E-Commerce gains share fastest on protective packaging substitution pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and centralized food service procurement concentrate biodegradable packaging demand in California's Central Valley and the Greater Toronto Area, with industrial composting infrastructure expansion reshaping geographic supply priorities.
United States
California's SB 54 mandates drive compostable container substitution across quick-service supply chains. The EPA's sustainable materials management guidelines and state-level extended producer responsibility laws accelerate material phase-out timelines. The Central Valley packaging cluster near Fresno anchors national procurement volume for certified formats.
Canada
Extended producer responsibility frameworks in Ontario and British Columbia mandate post-consumer recycled content thresholds for food service packaging. Health Canada's compostability labeling standards and Competition Bureau greenwashing enforcement disqualify non-certified environmental claims. The Greater Toronto Area food processing corridor concentrates demand for molded fiber containers and PLA films.
Mexico
Cross-border manufacturing integration near Mexico City's food processing corridor reduces landed costs for US Southwest distribution. Federal environmental standards and emerging state-level waste management regulations create compliance frameworks for biodegradable material adoption. The Bajío Region's agricultural processing base supplies feedstock for regional pulp-based packaging production.
North America Biodegradable Paper and Plastic Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue barrier-coated molded fiber and mineral-reinforced biocomposite specializations. The market structure consolidates around integrated pulp-to-box operators with coast-to-coast logistics capacity and certified material libraries. Three strategic archetypes dominate: vertically integrated fiber processors, specialized flexible film engineers, and regional containerboard specialists with agricultural hub proximity. Competitive moves center on certification pre-qualification at BPI and ASTM International, plus industrial composting partnership networks that secure end-of-life infrastructure access.
Within the integrated fiber processor tier, Smurfit WestRock and International Paper Company exemplify scale-driven positioning through captive pulp supply and national distribution infrastructure. Mondi occupies a specialization-focused position among European-originated flexible packaging engineers with kraft paper and high-moisture film expertise. Packaging Corporation of America anchors the regional specialist archetype through containerboard assets strategically positioned near Midwest agricultural processing hubs.
| Leading Market Players |
|---|
| Smurfit WestRock |
| Mondi |
| Amcor PLC |
| Tetra Pak International SA |
| Kruger Inc. |
| International Paper Company |
| Packaging Corporation of America |
| Graphic Packaging International Inc. |
| Cascades Inc. |
| Others |
Value Network & Pricing Analysis
Corn starch feedstock from Midwest agricultural processors flows through polylactic acid resin production into three distinct pricing tiers for biodegradable packaging, with certified formats commanding premiums over uncertified alternatives and commodity pulp grades anchoring the economy segment.
Pricing Analysis
Volume concentrates in commodity-grade pulp containers while margins accrue to barrier-coated molded fiber and BPI-certified flexible films. Price differentiation separates ASTM D6400-certified suppliers with pre-qualified material libraries from uncertified regional competitors. Cost compression in standard-grade PLA films is intensifying because corn starch pricing competes with ethanol market demand. Quick-service restaurant chains exhibit lowest price sensitivity due to centralized sustainable procurement mandates, while independent food service distributors face acute margin pressure.
Supply Chain Analysis
Workforce availability constraints in Mexico City's food processing corridor and the California Central Valley packaging cluster are reshaping manufacturing location decisions for biodegradable container production. Supply concentrates in the United States, Canada, and Mexico, with pulp feedstock drawing from Midwest agricultural residues and Great Lakes recycled fiber networks. Raw material dependencies center on corn starch for PLA, softwood pulp for molded fiber, and mineral additives for barrier coatings. Single-source vulnerability runs through concentrated PLA resin production. Distribution runs through national food service distributors with coast-to-coast logistics capacity and direct procurement relationships with quick-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers with integrated certification and geographic coverage, as BPI verification backlogs and centralized procurement mandates force weaker regional players toward exit or acquisition.
For Market Incumbents: Deepen backward integration into captive pulp supply near Midwest agricultural hubs to secure feedstock cost advantages against commodity volatility. Expand BPI-certified material libraries ahead of pending state-level packaging reduction mandates. Barrier-coated molded fiber specialization offers defensive positioning against emerging mineral-reinforced biocomposite entrants in electronics protective packaging. For New Entrants and Emerging Players: E-commerce fulfillment operators represent the most penetrable buyer archetype for biodegradable void-fill and cushioning applications outside food service concentration. Electronics protective packaging in Texas and Pacific Northwest distribution centers offers white-space expansion with lower certification barriers than quick-service procurement. A direct-to-fulfillment-operator sales model bypasses entrenched national distributor relationships. For Investors and Strategic Acquirers: Federal procurement preference rule updates are the leading indicator that government food service contract mandates will restructure supplier qualification criteria and accelerate consolidation. The five-to-ten-year viability window favors vertically integrated fiber processors with industrial composting partnership networks. Acquisition targets should demonstrate pre-certified material libraries and geographic coverage across multiple state regulatory jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| BPI Certification Pre-Qualification | ASTM D6400 verification unlocks national distribution through major quick-service restaurant chains. |
| Backward Integration into Pulp Supply | Captive agricultural residue processing insulates margin from corn starch commodity volatility. |
| Industrial Composting Partnership Network | End-of-life infrastructure access secures buyer confidence in certified material performance claims. |
| Barrier-Coated Molded Fiber Scale-Up | Expanded polystyrene replacement in electronics protective packaging opens e-commerce demand outside food service. |
| Cross-Border Manufacturing Integration | Mexico City corridor production reduces landed costs for US Southwest distribution against coastal competitors. |
Research Methodology
Document review covered EPA sustainable materials management guidelines, state-level extended producer responsibility legislation, ASTM International certification standards, and industrial composting facility databases, complemented by interviews with sustainability procurement directors at quick-service restaurant chains, packaging engineers at food processing companies, plant managers at molded fiber manufacturing facilities, and commercial officers at industrial composting operators. Secondary validation drew from BPI certification records, USDA agricultural commodity reports, and customs trade data for pulp and PLA resin flows. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, application, and end-user segments.
Segment-level outputs across the projection horizon reflect equipment compatibility constraints, composting infrastructure access gaps, and procurement mandate implementation timelines. The analytical framework modeled flexible packaging, rigid containers, pouches, and deli formats separately by pulp, PLA, starch, and mineral-reinforced material grades. CAGRs derived from regression analysis of historical substitution rates against regulatory compression indicators and food service chain procurement velocity. Forecast inputs incorporated California SB 54 compliance deadlines, Great Lakes corridor composting capacity expansion schedules, and corn starch pricing correlation with ethanol market dynamics.
Revisions become necessary when federal procurement preference rules materialize ahead of schedule, industrial composting contamination thresholds tighten beyond current ASTM specifications, or PLA resin supply concentration shifts through merger or facility closure. Material deviation in these named triggers warrants pause and re-evaluation of supplier qualification criteria and geographic demand distribution assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Lidding Films Market