
 Beverage Cartons Market | 2026-2036
Beverage Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Cartons Market Intelligence
The capital-intensity divergence between integrated fiber producers and pure-play converters is unwinding competitive stability in beverage carton supply. Tetra Pak leverages captive pulp sourcing and aseptic filling equipment ecosystems to sustain margin control across dairy and juice value chains. SIG Combibloc competes through modular filling technology that reduces customer switching costs in emerging markets. Elopak anchors its position via gable-top specialization and regional dairy partnerships in Europe.
Beverage cartons are multi-layer liquid packaging containers constructed from paperboard substrates laminated with polyethylene barriers and aluminum foil oxygen shields, engineered for shelf-stable distribution without refrigeration. The form dimension segments across brick, gable top, aseptic, spout, sleeve, and Tetra Pak configurations, with aseptic and spout formats capturing expanding share in functional drinks and plant-based milks due to extended shelf life and convenience premiums. Application demand concentrates in dairy beverages and juices where cold-chain limitations favor ambient distribution, while plant-based milks represent the fastest-growing application pool as oat and almond alternatives displace conventional dairy in retail and food service channels.
The EU Green Deal and F-Gas Regulation are reshaping material specifications by restricting fluorinated barriers and mandating recyclability thresholds, while the FDA maintains aseptic processing standards that govern food contact safety and validation protocols in North America. China's GB standards and SAMR oversight impose compositional limits on imported packaging materials that affect multinational supplier access. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D pipelines with diverging compliance timelines rather than unified global specifications.
Market Dynamics
EU Green Deal packaging waste directives are forcing fiber-based material transitions across the beverage carton supply chain, rewiring converter procurement patterns and pulp sourcing strategies in real time.
Growth Catalysts
- Aseptic filling infrastructure:Dairy processors in Brazil's São Paulo state manufacturing corridor are installing ambient distribution lines to bypass cold-chain limitations. This equipment deployment pulls laminated carton demand.
- F-Gas Regulation phaseout:The EU restriction on fluorinated barriers accelerates aluminum-foil oxygen shield adoption. Converters must reformulate multilayer structures to maintain shelf-stable performance.
- Plant-based milk proliferation:Oat and almond alternatives displace conventional dairy in retail and food service channels. These products favor brick and spout formats for extended shelf life and convenience premiums.
Market Restraints
- Polyethylene barrier cost volatility:Crude-linked resin prices swing converter margins. Integrated fiber producers with captive pulp sourcing withstand input spikes better than pure-play converters.
- Pulp supply concentration:Nordic and Brazilian pulp mills control hardwood fiber flows. Geographic clustering creates bottleneck risk for non-integrated carton manufacturers.
- Aluminum foil technical floor:Sub-micron foil layers cannot thin further without oxygen permeability breaches. Material science limits constrain lightweighting programs.
Strategic Opportunities
- China GB standards compliance:SAMR oversight of imported packaging materials blocks some multinationals. Localized production and compositional alignment unlock access.
- Spout format functional drinks:Energy and wellness beverages adopt resealable convenience. This application segment captures premium positioning versus standard brick configurations.
- Recyclability mandate tailwinds:EU Green Deal recyclability thresholds favor fiber-based substrates. Early alignment with fiber recovery infrastructure yields channel access.
Industry Challenges
- Aseptic validation timelines:FDA food contact safety protocols require extended equipment qualification cycles. New filling line deployment stretches 18-24 months.
- Multilayer delamination expertise:Separating polyethylene barriers from paperboard cores in recycling streams demands specialized reprocessing chemistry. Talent scarcity constrains circular economy scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Cartons Market |
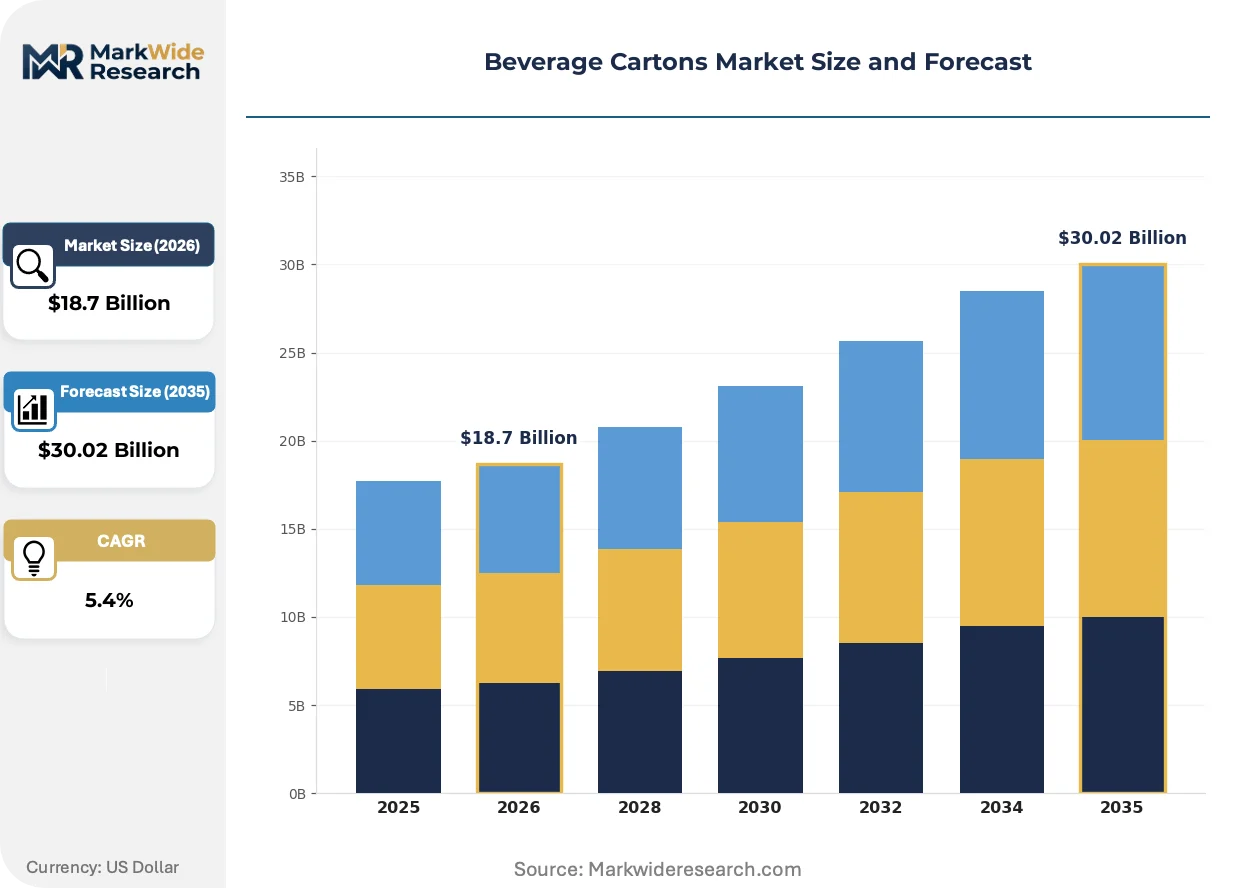
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paperboard, Polyethylene, Aluminum Foil, Biodegradable Films, Composite Laminates Form: Brick, Gable Top, Aseptic, Spout, Sleeve, Tetra Pak Application: Juices, Dairy Beverages, Functional Drinks, Plant-Based Milks, Alcoholic Beverages End User: Food & Beverage Producers, Contract Packers, Retail Chains, Food Service Providers, Hospitality Sector |
| Companies Covered | Tetra Pak, SIG Combibloc, Elopak, Greatview Aseptic Packaging, Mondi Group, WestRock Company, Stora Enso, Pactiv Evergreen, Visy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Cartons Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are actively fragmenting the traditional polyethylene-aluminum-paperboard laminate stack, opening substitution pathways across barrier technologies.
Barrier material innovation is decomposing the standard three-layer laminate architecture. Mono-material polyethylene alternatives and bio-based coatings gain traction among juice processors seeking design-for-recycling credentials. The structural consequence is compressing aluminum foil demand in ambient-stable applications where oxygen sensitivity permits.
REACH and F-Gas Regulation restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier chemistries from EU-sourced cartons. Industrial consequence falls heaviest on long-life dairy and functional drink segments requiring extended shelf stability. Manufacturers respond with aluminum foil thickness optimization and polymer crystallinity engineering.
Food service channel consolidation is compressing buyer negotiation cycles. National restaurant chains and contract catering operators now specify packaging formats at procurement headquarters rather than regional distribution centers. This concentration is most visible in North American and Western European plant-based milk contracts, where volume commitments drive exclusive format standardization.
Beverage Cartons Market Segmentation
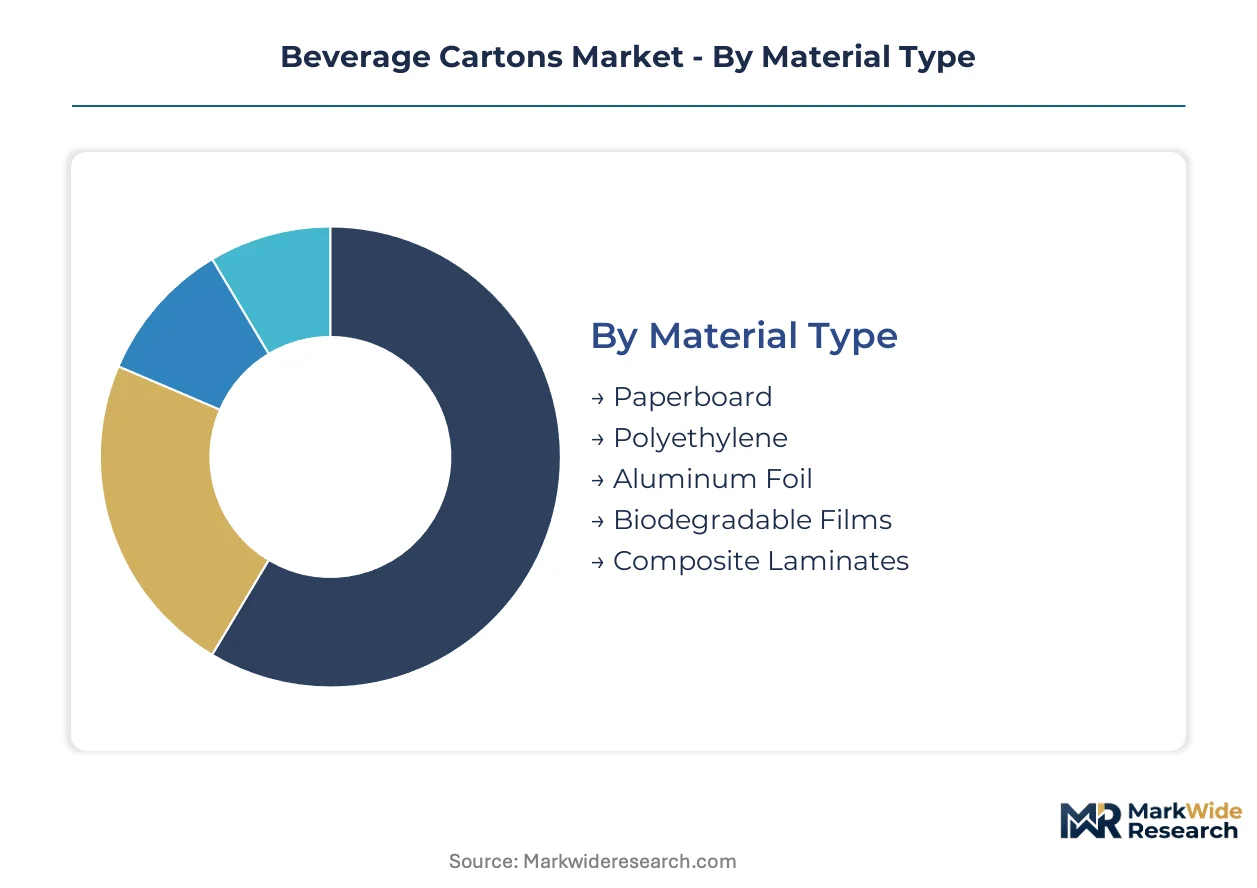
Material composition and form geometry determine shelf-life performance and recyclability credentials across beverage carton procurement decisions. End-user concentration in dairy and plant-based segments is rewiring converter capacity allocation toward aseptic and spout configurations.
Material Type:
Domestic pulp integration favors paperboard and aluminum foil sourcing in Nordic and Brazilian manufacturing corridors, while polyethylene and biodegradable films track import-dependent supply chains.
- Paperboard:Hardwood fiber substrates provide structural rigidity and printability for retail-facing surfaces. Dairy processors in Brazil's São Paulo corridor specify high-grammage boards for ambient distribution lines. Pulp supply concentration in Nordic mills creates procurement leverage for integrated converters.
- Polyethylene:Extruded resin layers seal liquid contents and enable heat-seal closure during filling operations. Cost volatility in crude-linked inputs squeezes pure-play converter margins disproportionately. Brazilian and Nordic integrated producers withstand price spikes through captive pulp offsets.
- Aluminum Foil:Sub-micron oxygen barriers extend shelf stability in long-life dairy applications. EU F-Gas Regulation phaseout is accelerating foil adoption as fluorinated alternatives face restriction.
- Biodegradable Films:Bio-based coatings gain traction among juice processors seeking design-for-recycling compliance under EU Green Deal thresholds.
- Composite Laminates:Multi-layer structures combining fiber, polymer, and metal barriers dominate functional drinks requiring extended ambient stability.
Paperboard commands the established base. The steepest expansion runs through biodegradable films.
Form:
Cost tiering separates premium spout configurations from economy sleeve formats, with aseptic and brick geometries occupying mid-tier positioning across dairy and juice value chains.
- Brick:Rectangular prism geometry maximizes pallet density and retail shelf efficiency. Plant-based milk producers in North American food service channels favor brick for logistics optimization and extended shelf-life claims.
- Gable Top:Sloped roof design enables pour-spout functionality without secondary fitments. Regional dairy partnerships across Europe anchor demand for this format in fresh milk distribution where cold-chain infrastructure exists.
- Aseptic:Sterilized filling environments enable shelf-stable distribution without refrigeration. Brazil's São Paulo manufacturing corridor is installing ambient lines that pull laminated carton demand for dairy export markets.
- Spout:Resealable convenience commands premium positioning in energy and wellness beverages. Functional drink adoption is climbing fastest in North American and Western European retail channels.
- Sleeve:Wraparound labeling format reduces material intensity for short-shelf-life applications. Contract packers specify sleeves for seasonal juice promotions requiring rapid format changeovers.
- Tetra Pak:Proprietary geometry with integrated straw or cap options dominates emerging market dairy penetration. Modular filling ecosystems lock in converter relationships across Latin American and Asian markets.
Aseptic formats hold the volume core. Spout configurations are gaining share fastest in premium functional drink segments.
Application:
Customer type concentration splits procurement between multinational dairy processors seeking scale efficiencies and specialty beverage startups prioritizing format differentiation.
- Juices:Acidic content demands oxygen barrier performance and light protection. Design-for-recycling pressures from EU Green Deal are shifting juice processors toward mono-material alternatives and bio-based coatings.
- Dairy Beverages:Cold-chain limitations in emerging markets favor aseptic carton adoption. Brazil's processors are expanding ambient distribution lines that specify multilayer laminated structures.
- Functional Drinks:Energy and wellness formulations require extended shelf stability and resealable convenience. Spout format penetration is deepest in this segment across North American retail.
- Plant-Based Milks:Oat and almond alternatives displace conventional dairy in food service and retail channels. Brick and spout formats capture this expansion due to ambient distribution requirements and convenience premiums.
- Alcoholic Beverages:Wine and ready-to-drink cocktails adopt cartons for outdoor and festival consumption occasions. Regulatory alcohol packaging restrictions limit penetration in certain jurisdictions.
Dairy beverages anchor the installed base. Plant-based milks are expanding most quickly as oat and almond alternatives displace conventional dairy.
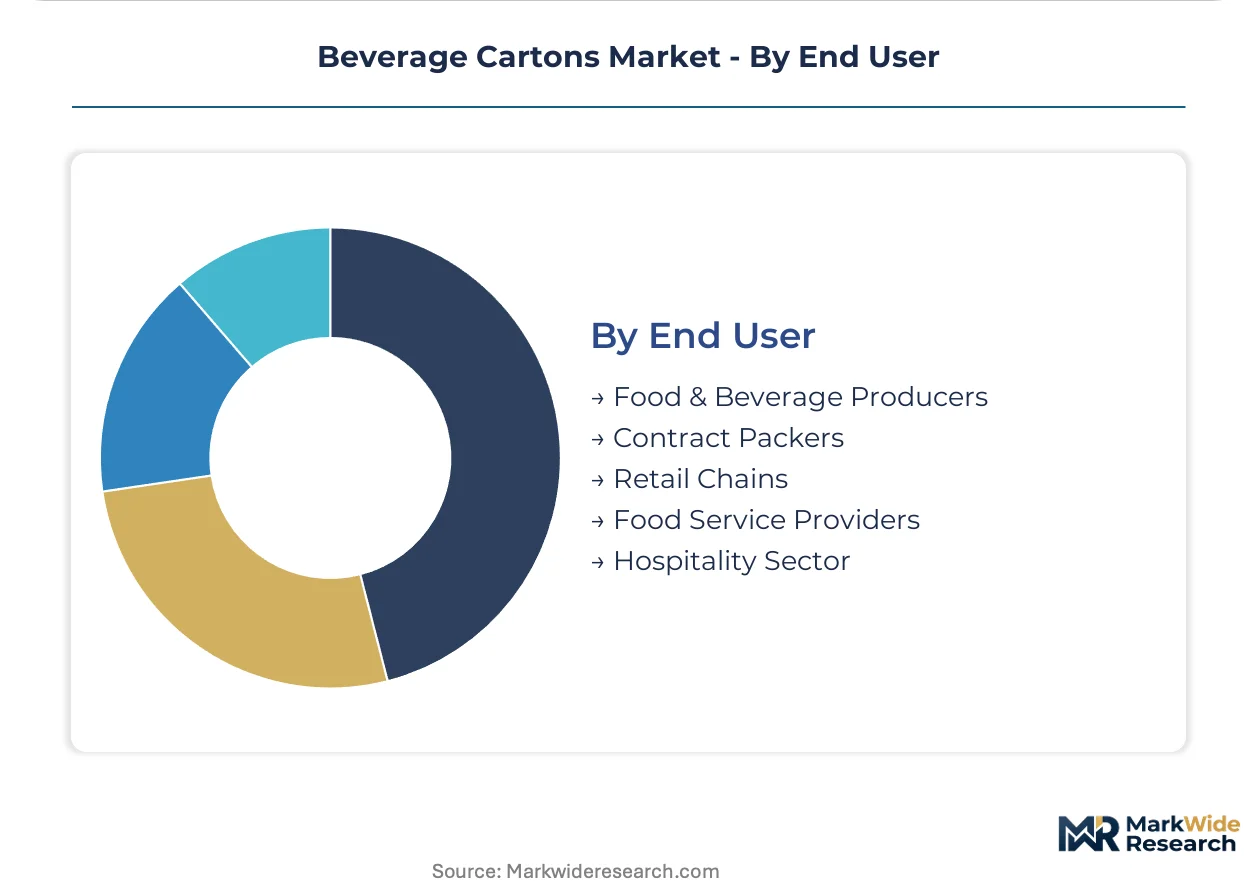
End User:
Supply concentration among national restaurant chains and contract catering operators is compressing buyer negotiation cycles and driving format standardization.
- Food & Beverage Producers:Integrated dairy and juice manufacturers specify carton formats at corporate procurement headquarters. Volume commitments drive exclusive supplier relationships and long-term filling equipment contracts.
- Contract Packers:Third-party filling operations serve multiple brands with rapid changeover capabilities. Sleeve and gable-top formats dominate this channel due to lower equipment capital requirements.
- Retail Chains:Private-label beverage programs specify carton formats to differentiate shelf presence. Spout and aseptic configurations capture premium positioning in organic and functional drink aisles.
- Food Service Providers:National restaurant chains and contract catering operators now centralize packaging procurement decisions. Plant-based milk contracts in North America and Western Europe exhibit this concentration most visibly.
- Hospitality Sector:Hotels and institutional catering favor portion-controlled and ambient-stable formats for minibars and breakfast service. Brick and aseptic geometries align with storage constraints and shelf-life requirements.
Food and beverage producers command the established base. Food service providers are climbing fastest as channel consolidation centralizes procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil deploys aseptic cartons for ambient dairy distribution while Germany drives fiber-based transitions under EU packaging mandates. China restricts imported multilayer structures through compositional standards. The United States maintains FDA-validated filling protocols for extended shelf-life applications. India scales gable-top capacity for regional fresh milk networks.
Brazil
Dairy processors in São Paulo state are installing ambient distribution lines to bypass cold-chain gaps in interior regions. ANVISA aligns food contact safety protocols with Mercosur standards to facilitate cross-border carton trade. The São Paulo manufacturing corridor concentrates converter capacity for export-oriented aseptic filling operations.
Germany
EU Green Deal recyclability thresholds are accelerating paperboard substrate transitions among juice and dairy packagers. ECHA REACH restrictions on fluorinated barriers force aluminum-foil oxygen shield reformulation. Bavarian and North Rhine-Westphalian converter clusters specialize in multilayer delamination chemistry for circular economy compliance.
China
SAMR oversight of imported packaging materials blocks multinationals lacking localized production or GB standards alignment. MIIT promotes domestic aseptic filling equipment to reduce technology import dependence. Yangtze River Delta converters expand capacity for plant-based milk cartons targeting food service channels.
United States
FDA aseptic processing validation protocols govern 18-24 month equipment qualification cycles for extended shelf-life dairy and juice lines. Midwest dairy cooperatives specify gable-top formats for regional fresh milk distribution. Pacific Northwest pulp integration supports fiber-based barrier innovation for design-for-recycling claims.
India
FSSAI food safety standards govern multilayer laminate approvals for ambient dairy and flavored milk distribution. Gujarat and Maharashtra dairy federations scale gable-top capacity for regional cold-chain networks. Karnataka-based contract packers serve juice processors with rapid format changeover capabilities for seasonal promotions.
Beverage Cartons Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in beverage carton supply. Captive pulp sourcing and filling equipment ecosystems distinguish the upper tier from pure-play converters exposed to resin price volatility. Three archetypes dominate: Nordic-Brazilian integrated fiber producers, European modular filling technology suppliers, and Asia-Pacific regional specialists. Competitive moves concentrate on backward integration into hardwood fiber supply and strategic partnerships with dairy processors for long-term equipment contracts.
Among Nordic integrated producers, Tetra Pak and Stora Enso exemplify the captive pulp sourcing archetype that withstands input cost spikes. SIG Combibloc occupies a position within the modular filling technology tier that reduces customer switching costs in emerging markets. Elopak anchors the gable-top specialization segment through regional dairy partnerships across European markets.
| Leading Market Players |
|---|
| Tetra Pak |
| SIG Combibloc |
| Elopak |
| Greatview Aseptic Packaging |
| Mondi Group |
| WestRock Company |
| Stora Enso |
| Pactiv Evergreen |
| Visy Industries |
| Others |
Cost & Logistics Intelligence
Aluminum-foil oxygen shield substitution for fluorinated barriers is simultaneously relocating converter procurement toward Nordic and Brazilian pulp-integrated corridors while compressing margin structures for resin-dependent pure-plays. This material transition rewires cost allocation across multilayer laminate stacks as EU F-Gas Regulation phaseout accelerates.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated fiber producers and multinational dairy processors, locking in volume commitments across 18-24 month filling equipment deployment cycles. Price differentiation rests on captive pulp sourcing versus import-dependent resin exposure, with Brazilian and Nordic integrated converters commanding stability while pure-plays absorb polyethylene volatility. Cost compression in standard brick formats is intensifying because crude-linked resin inputs swing disproportionately. Contract packers and seasonal juice processors exhibit highest price sensitivity due to rapid format changeover requirements and low volume commitments.
Supply Chain Analysis
Brazil and Sweden anchor hardwood fiber supply through São Paulo state and Nordic pulp mill corridors that feed captive paperboard production for aseptic carton converters. Raw material flows draw from Brazilian eucalyptus plantations and Scandinavian birch forests, with polyethylene resin and sub-micron aluminum foil as critical import dependencies. Single-source vulnerability concentrates in Nordic pulp mill geographic clustering that creates bottleneck risk for non-integrated manufacturers. Distribution runs through converter co-location with dairy processor filling lines in regional manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage cartons sit in early-cycle expansion as plant-based milk proliferation and aseptic infrastructure deployment in Brazil's interior create penetration tailwinds beyond traditional dairy strongholds.
For Market Incumbents: Shield margin position through backward integration into São Paulo state pulp assets and Nordic hardwood fiber supply to offset resin price volatility. Prioritize aseptic filling equipment ecosystem lock-in across Brazil's expanding ambient distribution corridor to defend against modular technology competitors reducing customer switching costs.
For New Entrants and Emerging Players: EU Green Deal recyclability certification fast-track unlocks channel access as juice processors abandon fluorinated barriers and seek design-for-recycling credentials. Target North American functional drink spout format penetration where resealable convenience commands premium positioning and incumbent equipment ecosystems remain underdeployed. Pursue co-manufacturing partnerships with contract packers to bypass 18-24 month FDA validation timelines.
For Investors and Strategic Acquirers: The market sits at an infrastructure-deployment phase that favors integrated fiber producers with captive pulp sourcing and regional dairy partnerships. Long-term viability centers on backward integration depth and circular economy reprocessing chemistry capabilities rather than pure-play conversion scale. Monitor aluminum-foil thickness optimization breakthroughs as inflection signals for material science disruption of standard laminate architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic and Brazilian captive fiber sourcing insulates margins from resin volatility. |
| Aseptic Filling Equipment Ecosystem Lock-in | Long-term dairy processor contracts in São Paulo state secure volume commitments. |
| Multilayer Delamination Chemistry Investment | Bavarian and North Rhine-Westphalian clusters specialize in circular economy compliance. |
| Spout Format Premium Positioning | North American functional drink adoption captures convenience premiums beyond brick configurations. |
| GB Standards Localized Production | SAMR oversight compliance unlocks access to Yangtze River Delta plant-based milk channels. |
Research Approach
The analysis maps paperboard substrate tiers, polyethylene barrier specifications, aluminum-foil oxygen shield grades, and biodegradable film alternatives, each validated through converter procurement directors, dairy processor filling line engineers, pulp mill supply managers, and EU regulatory affairs specialists. Primary interview intelligence triangulates against secondary sources including FDA aseptic processing guidance documents, ECHA REACH restriction filings, Brazilian ANVISA food contact safety protocols, Chinese SAMR packaging material standards, and customs trade flow data for hardwood fiber and resin imports. Bottom-up capacity modeling and top-down demand aggregation cross-validate volume estimates.
Consistency checks against external benchmarks confirm projection outputs across the modeling period. Segmentation dimensions include material composition, form geometry, application category, and end-user procurement concentration. CAGRs derive from installed base erosion rates and new capacity absorption curves. Industry-specific inputs capture aseptic filling line deployment timelines, F-Gas Regulation compliance phaseout schedules, and plant-based milk format conversion rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and Brazilian cold-chain infrastructure gaps; material deviation in regulatory timelines or resin price regimes would warrant model refresh. Recalibration cycles align with material shifts in barrier material substitution rates and recyclability mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Twist Opening Cartons Market
Cartons
Pizza Cartons Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Metallized Folding Cartons Market
Cartons
Folding Carton in Healthcare Market
Cartons
Carton Liners Market
Cartons
Carton Serialization Machine Market
Cartons
XXL Packaging Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Africa Folding Carton Market
Cartons
Global Folding Carton Packaging Market
Cartons
Wax Boxes Market
Cartons
Tablet Cartons Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Cartoning Machines Market
Cartons
Brick Carton Packaging Market