
 Folding Carton in Healthcare Market | 2026-2036
Folding Carton in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Folding Carton in Healthcare Market Foresight
Pharmaceutical packaging is consolidating its share within the healthcare folding carton mix as biologics and specialty drug portfolios expand. DS Smith leverages its European manufacturing footprint to serve multinational pharmaceutical clients with serialized carton lines. WestRock anchors North American supply through integrated paperboard-to-carton operations that control substrate costs. Edelmann Group differentiates via high-value finishing capabilities for oncology and rare-disease therapies.
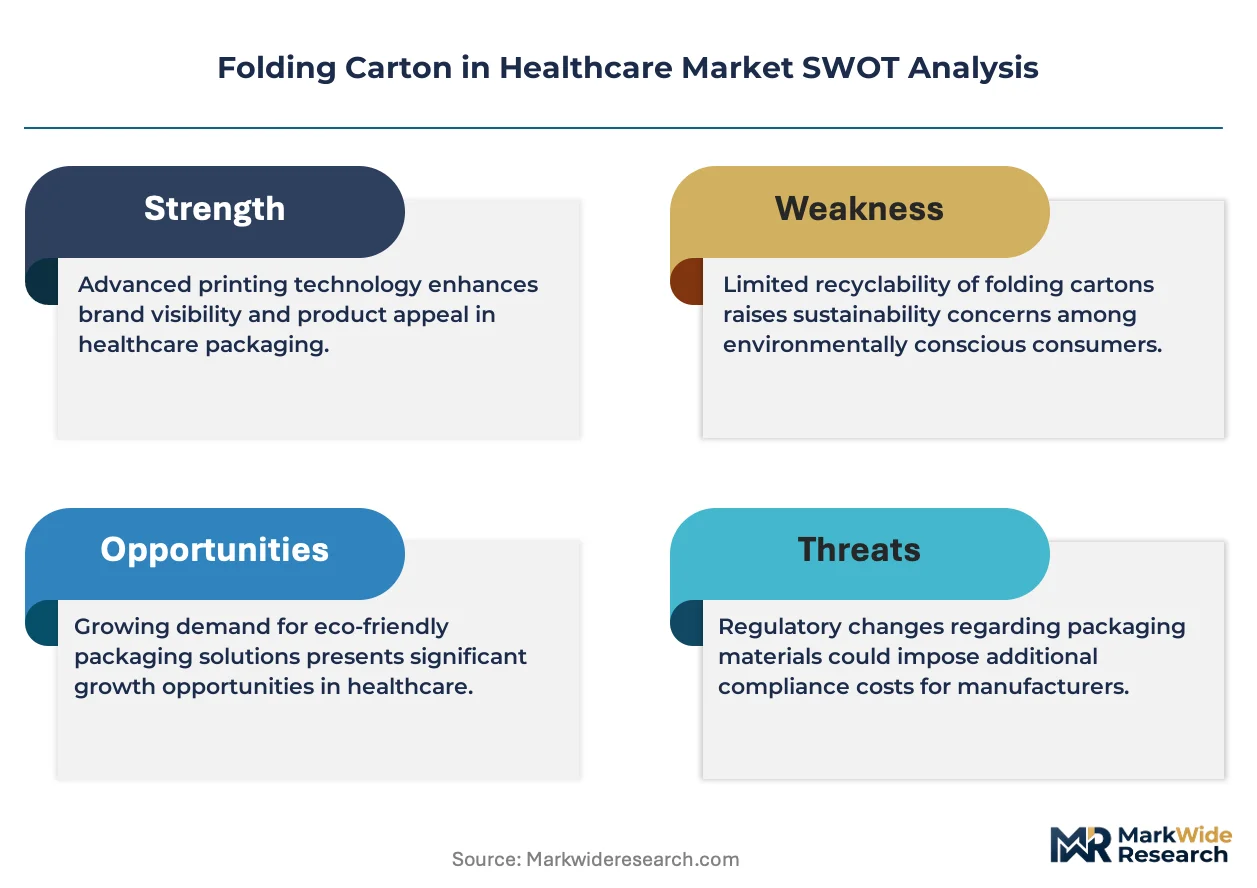
Folding carton in healthcare denotes paperboard-based secondary packaging, typically 12-24 pt solid bleached sulfate or folding boxboard, die-cut and glued to form protective enclosures for pharmaceuticals, devices, and diagnostics. The substrate accepts variable-data printing, tamper-evident features, and child-resistant closures required for regulated distribution. Pharmaceutical packaging dominates value contribution due to serialization investments and anti-counterfeiting mandates, while diagnostic kit packaging represents the fastest-expanding application as point-of-care testing proliferates. Barrier laminates command premium positioning where moisture and oxygen protection extend shelf stability for sensitive formulations.
FDA drug supply chain security requirements and EU MDR traceability provisions compel carton converters to integrate aggregation codes and verification infrastructure. The EPA and ECHA jointly influence substrate chemistry through restrictions on mineral oil saturated hydrocarbons in recycled fiber food-contact and healthcare applications. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables that could disqualify certain coated boards from primary-contact roles.
Market Dynamics
Serialization mandates from the FDA and EU MDR are forcing carton converters to rebuild production lines around aggregation infrastructure, collapsing the distinction between packaging and data management.
Growth Catalysts
- EU MDR traceability provisions:Secondary packaging must now carry unique device identifiers, pulling investment into high-speed printing and verification systems.
- Biologics portfolio expansion:Temperature-sensitive monoclonal antibodies require barrier laminates and moisture-resistant board grades that command premium positioning.
- German contract packaging concentration:Rhine-Ruhr and Bavarian clusters aggregate demand from both domestic pharmaceutical manufacturers and export-oriented multinationals.
Market Restraints
- Pulp and coated board cost volatility:Solid bleached sulfate prices fluctuate with energy-intensive bleaching operations, compressing converter margins without pass-through mechanisms.
- Recycled fiber regulatory friction:ECHA restrictions on mineral oil saturated hydrocarbons in food-contact and healthcare applications limit secondary fiber substitution.
- Digital printing substitution threat:Direct-to-blister label technologies and smart packaging interfaces reduce reliance on printed cartons for patient information.
Strategic Opportunities
- Point-of-care diagnostic kit expansion:Lateral flow and molecular test cartridges require compact, instruction-integrated cartons with tamper-evident closures.
- India CDSCO packaging localization:Domestic production incentives and import substitution policies create openings for regional substrate-to-carton operations.
- Pharmacopeial extractables standards:Evolving USP and EP chapters on coated board leachables favor converters with validated barrier coating chemistries.
Industry Challenges
- Serialization engineering talent scarcity:Integration of camera-based verification, aggregation software, and line control systems demands cross-functional automation specialists in short supply.
- Legacy ERP integration friction:Track-and-trace data must flow from carton lines into pharmaceutical manufacturer systems, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding Carton in Healthcare Market |
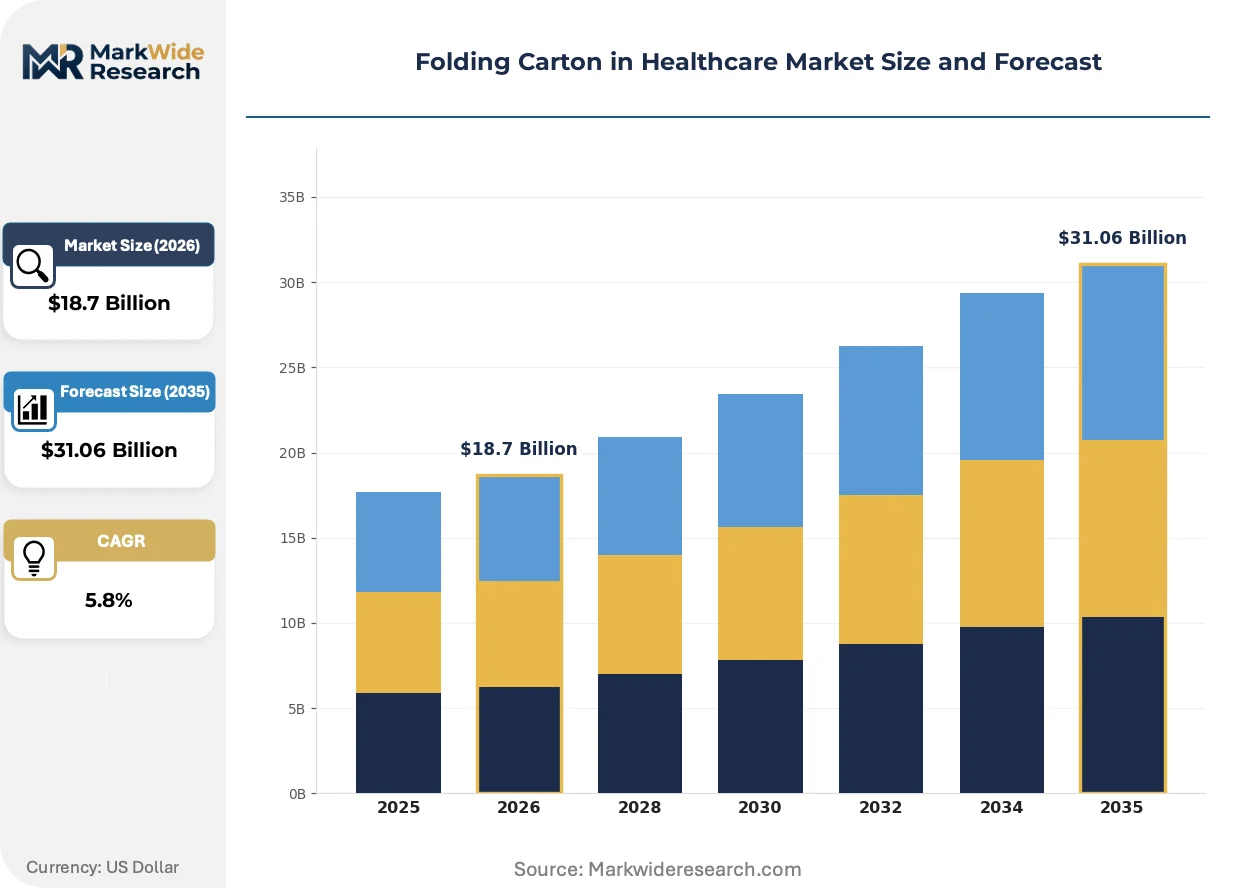
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Device Packaging, Pharmaceutical Packaging, Diagnostic Kit Packaging, Surgical Instrument Packaging, Supplement Packaging Application: Drug Delivery, Wound Care, Diagnostic Testing, Surgical Procedures, Nutritional Support End User: Hospitals, Ambulatory Care Centers, Laboratories, Specialty Clinics, Pharmacies Material Technology: Paperboard, Recycled Fiber, Coated Board, Barrier Laminates, Embossed Sheets |
| Companies Covered | DS Smith, Edelmann Group, CCL Industries, Jones Healthcare Group, Unipak Inc, WestRock, August Faller GmbH & Co. KG, Nosco, Inc, LGR Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding Carton in Healthcare Market Shifts & Advancements
Active and intelligent packaging functions are migrating from premium niches into standard pharmaceutical specifications, blurring the boundary between container and communication device.
Near-field communication (NFC) tags and printed electronics are expanding into folding cartons for medication adherence monitoring. Oncology and rare-disease therapy packagers in Switzerland and the Netherlands are adopting these features to support patient support programs. The technology is expanding into mid-volume generic portfolios as tag costs fall below the threshold where brand owners can justify adherence data collection against rebate negotiations.
EPA restrictions on per- and polyfluoroalkyl substances (PFAS) in food-contact and healthcare paperboard are accelerating fluorochemical-free barrier coating development. Coating suppliers and carton converters must validate alternative grease and moisture barriers without the performance degradation that previously blocked PFAS substitution. Solid oral dose manufacturers with US distribution face reformulation timelines that compress qualification windows for new board grades.
Hospital and pharmacy procurement consolidation is compressing supplier rosters and extending contract durations. Large health systems in the US and integrated hospital networks in Germany are bundling pharmaceutical packaging contracts across multiple therapy areas. This behavior concentrates volume with converters capable of serving diverse regulatory requirements and geographic footprints from unified quality systems.
Folding Carton in Healthcare Market Segmentation
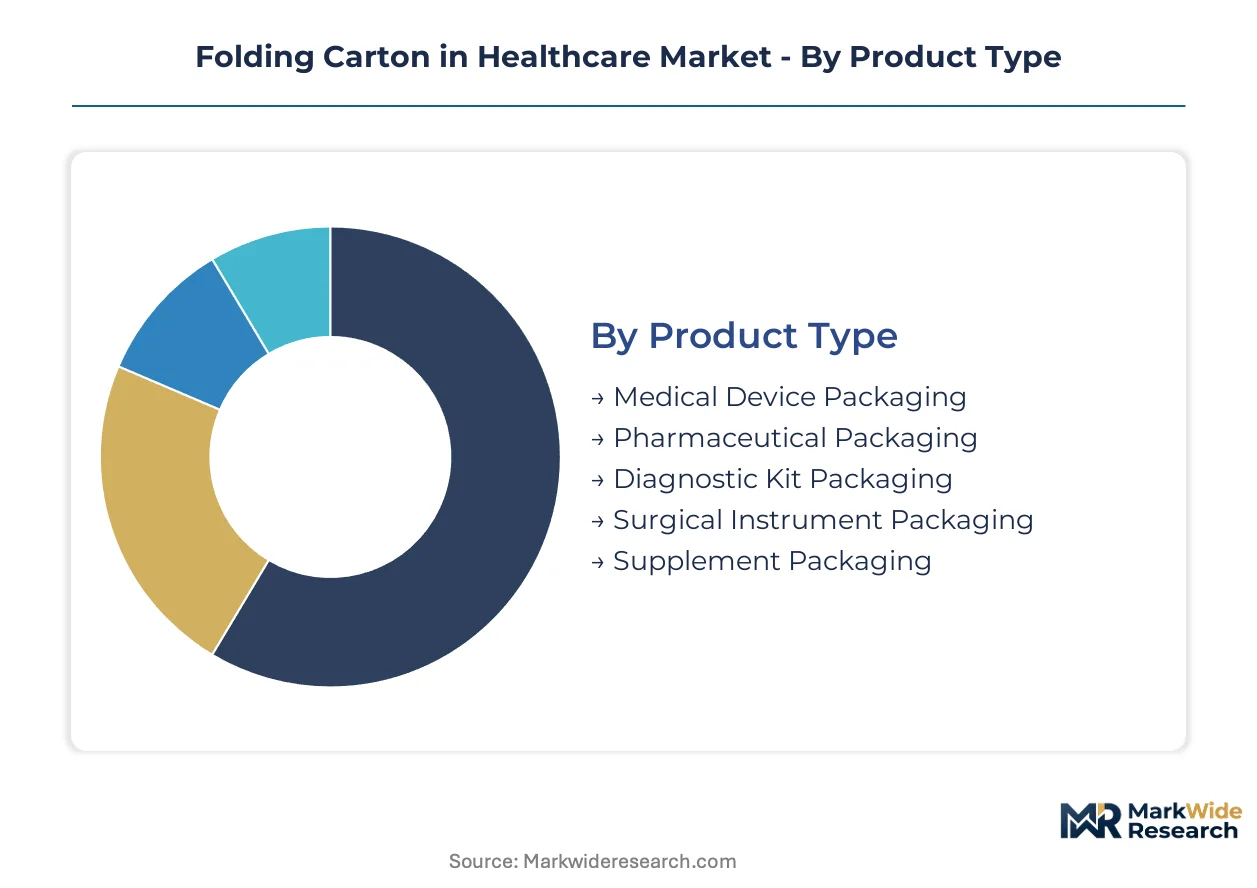
Healthcare folding cartons serve divergent performance requirements across therapy areas, substrate specifications, and regulatory jurisdictions. Segmentation reveals where serialization investments concentrate versus where commoditization pressures dominate.
Product Type:
Customization intensity spans from standard pharmaceutical formats requiring only variable-data printing to engineered medical device cartons with multi-point verification systems.
- Medical Device Packaging:Rigid 18-24 pt solid bleached sulfate constructions accommodate EU MDR unique device identifiers and sterilization barrier integration. German and Swiss contract manufacturers drive specification complexity for export-class devices.
- Pharmaceutical Packaging:Dominates value contribution through FDA Drug Supply Chain Security Act aggregation infrastructure, anti-counterfeiting holograms, and child-resistant closure compatibility. Temperature-sensitive biologics demand moisture-barrier laminates that command premium substrate positioning.
- Diagnostic Kit Packaging:Compact formats integrate lateral flow test instructions with tamper-evident closures for point-of-care deployment.
- Surgical Instrument Packaging:Sterilization-grade boards with validated seal integrity for autoclave and gamma sterilization protocols.
- Supplement Packaging:Lower regulatory burden permits recycled fiber substitution where mineral oil saturated hydrocarbon restrictions permit.
Leading the category by volume: Pharmaceutical Packaging. Growing fastest: Diagnostic Kit Packaging.
Application:
Volume scale concentrates in chronic disease administration, while procedural applications demand specialized sterile presentation formats.
- Drug Delivery:Oral solid dose cartons represent the baseline specification for serialization infrastructure investment. Aggregation codes and verification cameras dominate line engineering priorities for high-volume solid oral portfolios.
- Diagnostic Testing:Molecular and antigen test formats require instruction-integrated designs with humidity indicators for shelf-life verification. COVID-19 test deployment established manufacturing templates now extending to influenza and RSV multiplex panels.
- Wound Care:Advanced dressing cartons prioritize sterile field presentation with peel-open aseptic access features.
- Surgical Procedures:Custom kit configurations bundle multiple instruments with procedure-specific labeling for operating room efficiency.
- Nutritional Support:Enteral feeding and parenteral nutrition packaging emphasizes tamper evidence and batch traceability for home care settings.
Drug Delivery commands installed capacity. Diagnostic Testing climbs fastest on point-of-care expansion.
End User:
Procurement consolidation patterns split between centralized hospital purchasing and fragmented pharmacy dispensing networks.
- Hospitals:Integrated delivery networks in the US and German hospital groups bundle multi-therapy contracts, demanding unified quality systems across cardiovascular, oncology, and orthopedic portfolios.
- Ambulatory Care Centers:Outpatient surgical and infusion facilities require compact carton formats optimized for inventory velocity and space constraints.
- Laboratories:Reference and hospital lab networks prioritize batch-level traceability for reagent and control material packaging.
- Specialty Clinics:Dialysis, ophthalmology, and fertility clinics drive small-lot customization for patient-specific therapy regimens.
- Pharmacies:Retail and mail-order dispensing channels emphasize patient adherence features including calendarized blister integration.
Hospitals concentrate contract value. Specialty Clinics fragment demand across niche indications.
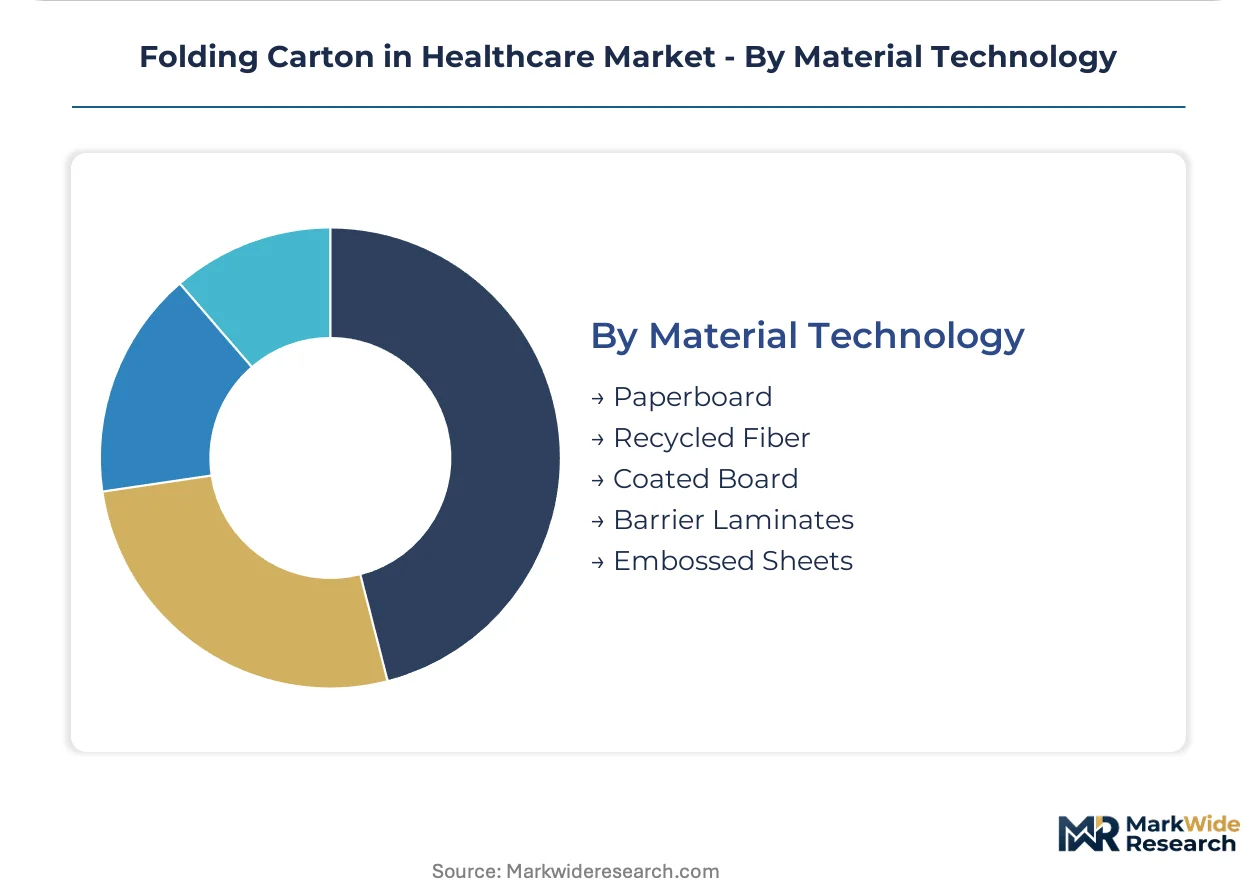
Material Technology:
Performance tiering separates validated barrier systems from commodity board grades subject to pulp cost volatility.
- Paperboard:Solid bleached sulfate remains the workhorse substrate for pharmaceutical serialization, accepting thermal transfer and inkjet variable-data printing with verified grade-A barcode readability.
- Barrier Laminates:Aluminum oxide and ethylene vinyl alcohol coatings extend shelf stability for moisture-sensitive biologics. FDA and EMA extractables validation requirements favor converters with established coating chemistry dossiers.
- Recycled Fiber:ECHA restrictions on mineral oil saturated hydrocarbons limit deployment in food-contact and primary healthcare applications despite sustainability procurement preferences.
- Coated Board:Clay and polymer coatings enable high-definition graphics for patient-facing oncology and rare-disease therapies.
- Embossed Sheets:Tactile finishing differentiates premium therapeutic categories while supporting accessibility compliance for vision-impaired patients.
Paperboard dominates tonnage. Barrier Laminates expand most quickly on biologics portfolio growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Telangana and Gujarat concentrate contract packaging demand for export-class folding cartons. These zones attract multinational pharmaceutical manufacturers seeking cost-competitive serialization infrastructure.
Germany
Rhine-Ruhr and Bavarian industrial corridors aggregate folding carton demand from both domestic pharmaceutical manufacturers and export-oriented multinationals. The EU MDR traceability provisions compel local converters to integrate unique device identifier printing and verification systems. Stuttgart-based contract packaging specialists serve Swiss and Austrian pharmaceutical clients with high-value finishing capabilities.
United States
Integrated delivery networks in the Northeast and Midwest bundle multi-therapy pharmaceutical packaging contracts across cardiovascular and oncology portfolios. The FDA Drug Supply Chain Security Act mandates aggregation infrastructure that collapses traditional boundaries between packaging and data management. Chicago-area converters anchor North American supply through integrated paperboard-to-carton operations controlling substrate input costs.
Switzerland
Oncology and rare-disease therapy packagers in Basel and Zurich drive adoption of near-field communication tags for patient adherence monitoring. Swissmedic pharmacovigilance requirements favor converters with validated extractables dossiers for barrier-coated boards. The Lake Geneva corridor concentrates precision finishing specialists serving global biologics portfolios.
India
CDSCO packaging localization policies and domestic production incentives create openings for regional substrate-to-carton operations in Maharashtra and Gujarat. Import substitution mandates for pharmaceutical secondary packaging pull investment into high-speed serialization lines. Hyderabad's pharmaceutical special economic zone clusters demand for compact diagnostic kit cartons with integrated tamper-evident closures.
China
NMPA traceability requirements for domestic pharmaceutical distribution reshape converter investment priorities in Jiangsu and Zhejiang provinces. Dual carbon goals accelerate fluorochemical-free barrier coating development for moisture-sensitive biologics. Shanghai-area packaging parks concentrate capacity serving both multinational joint ventures and domestic generic manufacturers.
Folding Carton in Healthcare Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical serialization consolidating around integrated converters while diagnostic kits fragment across regional players. The vendor base organizes into three tiers: multinational integrated paperboard suppliers, European contract packaging specialists, and regional substrate converters. Tier-one players defend position through captive fiber supply and aggregation software partnerships. Mid-tier specialists compete on pharmacopeial validation capabilities and therapy-area expertise.
Within the European specialist tier, DS Smith and WestRock exemplify divergent scale strategies. DS Smith leverages its manufacturing footprint across multiple countries to serve multinational pharmaceutical clients with serialized carton infrastructure. WestRock anchors North American supply through integrated operations spanning paperboard production to finished cartons. Edelmann Group occupies a position among high-value finishing specialists targeting oncology and rare-disease therapy packaging requirements.
| Leading Market Players |
|---|
| DS Smith |
| Edelmann Group |
| CCL Industries |
| Jones Healthcare Group |
| Unipak Inc |
| WestRock |
| August Faller GmbH & Co. KG |
| Nosco, Inc |
| LGR Packaging |
| Others |
Supply & Pricing Matrix
High-speed serialization line retrofitting simultaneously compresses converter margins and consolidates supply among capital-rich operators capable of absorbing FDA and EU MDR compliance costs. This technology transition concentrates pricing power with integrated paperboard producers while squeezing regional converters dependent on spot substrate purchases.
Pricing Analysis
Lead-time-based pricing stratification separates urgent serialized carton orders commanding premium positioning from standard-schedule production absorbing commodity board volatility. Three-tier pricing structure across premium barrier-laminate, standard solid bleached sulfate, and economy recycled-fiber grades reflects certification investment and pharmacopeial validation tiers. Cost compression in standard pharmaceutical cartons is intensifying because pulp and energy-intensive bleaching operations lack full pass-through mechanisms. Contract packaging specialists in Germany exhibit lowest price sensitivity due to bundled multi-therapy contracts, while generic solid oral dose manufacturers in India face acute margin pressure.
Supply Chain Analysis
Solid bleached sulfate supply rests on Nordic and North American pulp producers with energy-intensive bleaching infrastructure vulnerable to natural gas volatility. Folding carton production draws from German and Swiss precision finishing clusters, Indian contract packaging zones in Telangana and Gujarat, and integrated North American paperboard-to-carton operations. Single-source vulnerability concentrates in specialized barrier coating chemistries where fluorochemical-free alternatives remain under validation. Distribution runs through pharmaceutical manufacturer direct procurement for high-volume portfolios and contract packaging intermediaries for specialty therapy areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive fiber supply and in-house aggregation software development separate viable competitors from margin-squeezed converters. Players are pursuing upstream control over solid bleached sulfate substrate production to defend position against pulp cost volatility.
For Market Incumbents: Hedge against digital printing substitution by acquiring NFC tag integration capabilities and printed electronics partnerships for adherence monitoring applications. Lock in long-term fiber supply agreements with Nordic pulp producers before energy cost volatility accelerates. Defend margin position through pharmacopeial validation dossiers for barrier coating chemistries that qualify for biologics portfolios. For New Entrants and Emerging Players: Direct-to-pharmaceutical-manufacturer digital procurement platforms offer the lowest-friction entry path for spot carton orders bypassing contract packaging intermediaries. Target diagnostic kit packaging in Indian special economic zones where CDSCO localization mandates create demand for regional substrate-to-carton operations. Pursue point-of-care test cartridge formats with integrated tamper-evident closures as the most penetrable white-space segment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated paperboard conglomerates seeking pharmacopeial validation capabilities and therapy-area expertise. Long-term viability favors converters with validated barrier coating dossiers and established serialization infrastructure partnerships. Watch FDA enforcement discretion on aggregation timeline extensions as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Partnership | Aggregation software integration with pharmaceutical manufacturer ERP systems locks in multi-year contract value. |
| Fluorochemical-Free Barrier Coating Development | EPA restrictions on PFAS in healthcare paperboard accelerate validation timelines for alternative moisture barriers. |
| Contract Packaging Specialist Acquisition | German and Swiss precision finishing capabilities command premium positioning in oncology and rare-disease therapies. |
| Indian Substrate-to-Carton Capacity Buildout | CDSCO localization policies and import substitution mandates pull investment into domestic serialization lines. |
| NFC Tag Integration for Adherence Monitoring | Swissmedic pharmacovigilance requirements favor patient support programs with connected packaging data streams. |
Research Methodology
Document review covered FDA Drug Supply Chain Security Act guidance documents, EU MDR technical documentation requirements, and ECHA restriction proposals on mineral oil saturated hydrocarbons, complemented by interviews with pharmaceutical packaging procurement directors, folding carton operations managers, barrier coating R&D specialists, and serialization systems integrators. Secondary validation drew from pharmaceutical manufacturer annual reports, CDSCO import substitution policy circulars, and trade data on solid bleached sulfate pricing. Bottom-up demand modeling across therapy areas and substrate grades triangulated against top-down pulp industry capacity forecasts.
Market sizing outputs reflect installed serialization line capacity, biologics portfolio expansion trajectories, and point-of-care diagnostic test deployment rates across the projection horizon. Segmentation modeling incorporated product type, application, end user, and material technology dimensions with regional regulatory cluster overlays. CAGRs were derived from pharmaceutical packaging volume growth correlated to prescription drug spending and serialization mandate compliance deadlines. Forecast inputs included EU MDR unique device identifier adoption curves and NMPA traceability requirement implementation timelines.
The model holds under stable pulp pricing and regulatory deadline adherence; deviation in energy cost spikes or aggregation timeline extensions would shift converter margin recovery trajectories. A small set of named triggers warrants ongoing watch: ECHA mineral oil restriction enforcement, FDA DSCSA aggregation waiver decisions, and fluorochemical-free barrier coating qualification rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Fully Enclosed Cartons Market
Cartons
Carton Liners Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Beverage Cartoners Market
Cartons
Global Open Top Cartons Market
Cartons
Interlocking Boxes Market
Cartons
Twist Opening Cartons Market
Cartons
Japan Corrugated Boxes Market
Cartons
Folding Cartons Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Wax Boxes Market
Cartons
Africa Folding Carton Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Carton Serialization Machine Market
Cartons
Litho Laminated Cartons Market
Cartons
Liquid Packaging Cartons Market