
 US Soft Drinks Packaging Market | 2026-2036
US Soft Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Soft Drinks Packaging Market Analytics
US aluminum can sheet producers is rebalancing capacity toward beverage-grade substrate after years of prioritizing automotive alloys. Ball Corporation leverages its integrated metal supply chain to sustain domestic canbody production at scale. Crown Holdings anchors its position through specialized ends and tabs manufacturing. Amcor competes across multiple material platforms, extending its reach into both rigid and flexible formats for carbonated and non-carbonated soft drinks.
US Soft Drinks Packaging encompasses the engineered containment systems—ranging from two-piece aluminum cans with internal lacquer coatings to polyethylene terephthalate bottles with multilayer barrier structures—designed to preserve carbonation, prevent flavor scalping, and withstand internal pressures of 90-100 psi during distribution. Aluminum cans command the largest volume position due to their infinite recyclability loop and lightweight logistics profile, while paperboard cartons with aseptic laminates represent the fastest-expanding niche as brands pursue shelf-stable, refrigeration-free distribution. Glass bottles retain premium positioning in specialty and craft segments where tactile differentiation supports higher price realization.
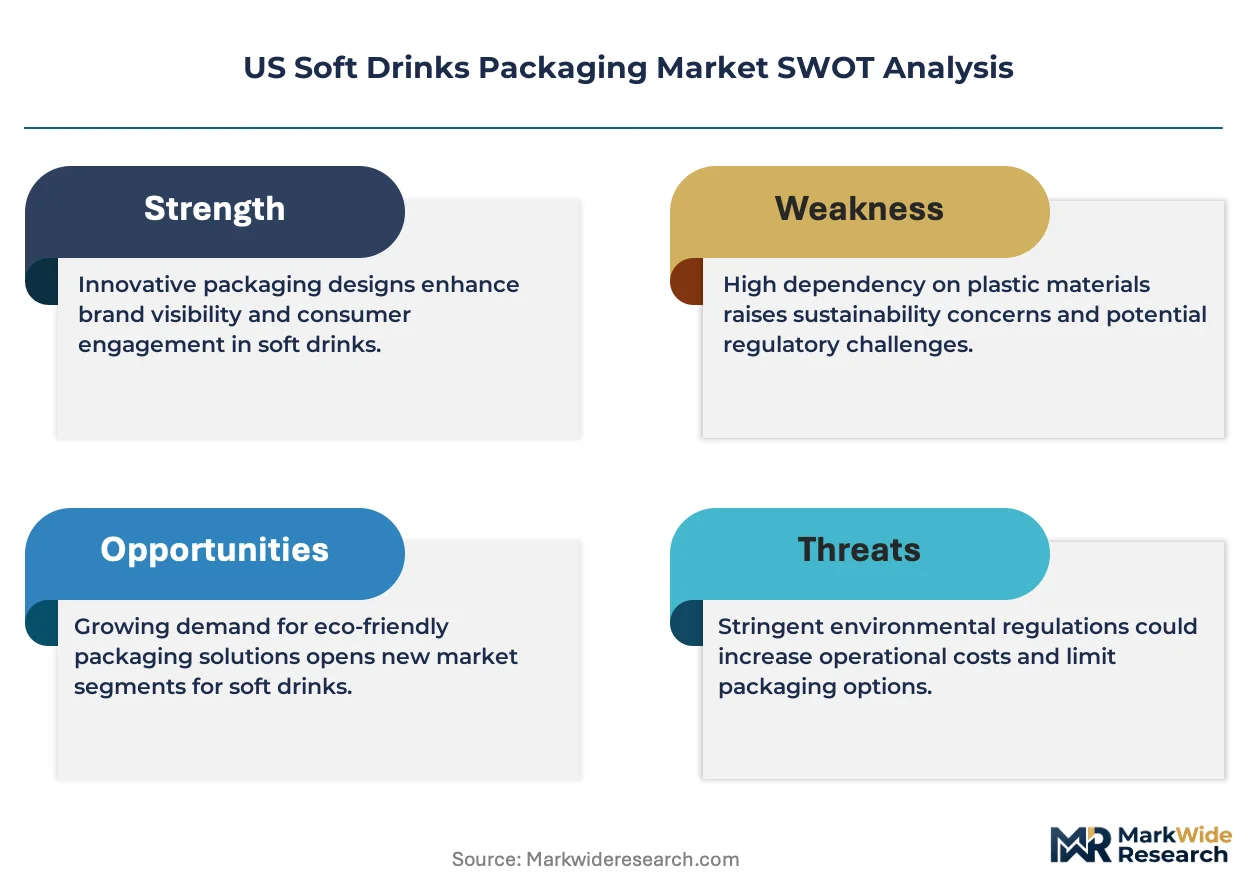
The FDA governs food contact substances through its FCN program, while California's CalRecycle administers SB 54 compliance timelines that mandate recycled content thresholds and producer-funded collection infrastructure. OSHA standards for pressurized filling operations and EPA emissions rules for coating and printing processes add layered compliance costs that favor capital-intensive operators with established environmental management systems. Stakeholders must monitor how state-level extended producer responsibility frameworks diverge from federal baseline requirements and whether recycled aluminum and PET flake supplies tighten as multiple beverage categories compete for finite reprocessed material streams.
Market Dynamics
Aluminum sheet capacity rebalancing toward beverage-grade substrate is compressing resin-dependent formats as brands accelerate can adoption for sparkling water and carbonated soft drinks. This supply-side pivot intersects with California's SB 54 mandates to reshape material procurement priorities across the value chain.
Growth Catalysts
- Extended Producer Responsibility Mandates:California's SB 54 establishes recycled content thresholds and producer-funded collection infrastructure, compelling format shifts toward infinitely recyclable aluminum and driving investment in domestic reprocessing capacity.
- Beverage Manufacturing Cluster Expansion:Southwest and Southeast states concentrate new production facilities proximate to Gulf Coast resin plants and Southeast aluminum rolling mills, reducing inbound logistics costs for high-volume converters.
- Sparkling Water Format Migration:Flavored sparkling water brands are abandoning PET bottles for aluminum cans to leverage curbside recycling acceptance rates and meet retailer sustainability scorecard requirements.
Market Restraints
- Aluminum Sheet Supply Concentration:Domestic beverage-grade substrate production remains concentrated among integrated metal producers, creating allocation risk during automotive alloy demand spikes.
- Resin Price Volatility:PET and HDPE pellet costs fluctuate with natural gas liquids feedstock pricing, compressing margins for bottle converters locked into annual supply agreements.
- Multilayer Barrier Technical Limitations:Aseptic carton structures incorporating aluminum foil and polyethylene laminates face mechanical recycling incompatibility, constraining circularity claims under FTC Green Guides scrutiny.
Strategic Opportunities
- Underpenetrated Aseptic Carton Segment:Shelf-stable, refrigeration-free distribution formats remain underdeveloped in mainstream carbonated categories, offering white space for ambient supply chain optimization.
- Regulatory Tailwind from FDA FCN Streamlining:Updated food contact notification requirements for recycled content are accelerating approval timelines for post-consumer PET applications in beverage bottles.
- Direct-to-Store Distribution Innovation:E-commerce beverage subscription models and micro-fulfillment centers are bypassing traditional warehouse club and grocery distributor markups.
Industry Challenges
- Coating Formulation Skill Gap:Internal lacquer chemistry expertise for two-piece aluminum cans has atrophied as veteran technical talent retires from domestic can manufacturing.
- Capex Intensity for Aseptic Filling Lines:Hydrogen peroxide sterilization and dry-aseptic packaging equipment requires capital deployment that mid-tier bottlers struggle to finance.
- OSHA Pressurized Operation Compliance:Carbonated filling at 90-100 psi demands specialized safety training and equipment certification timelines that extend facility commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Soft Drinks Packaging Market |
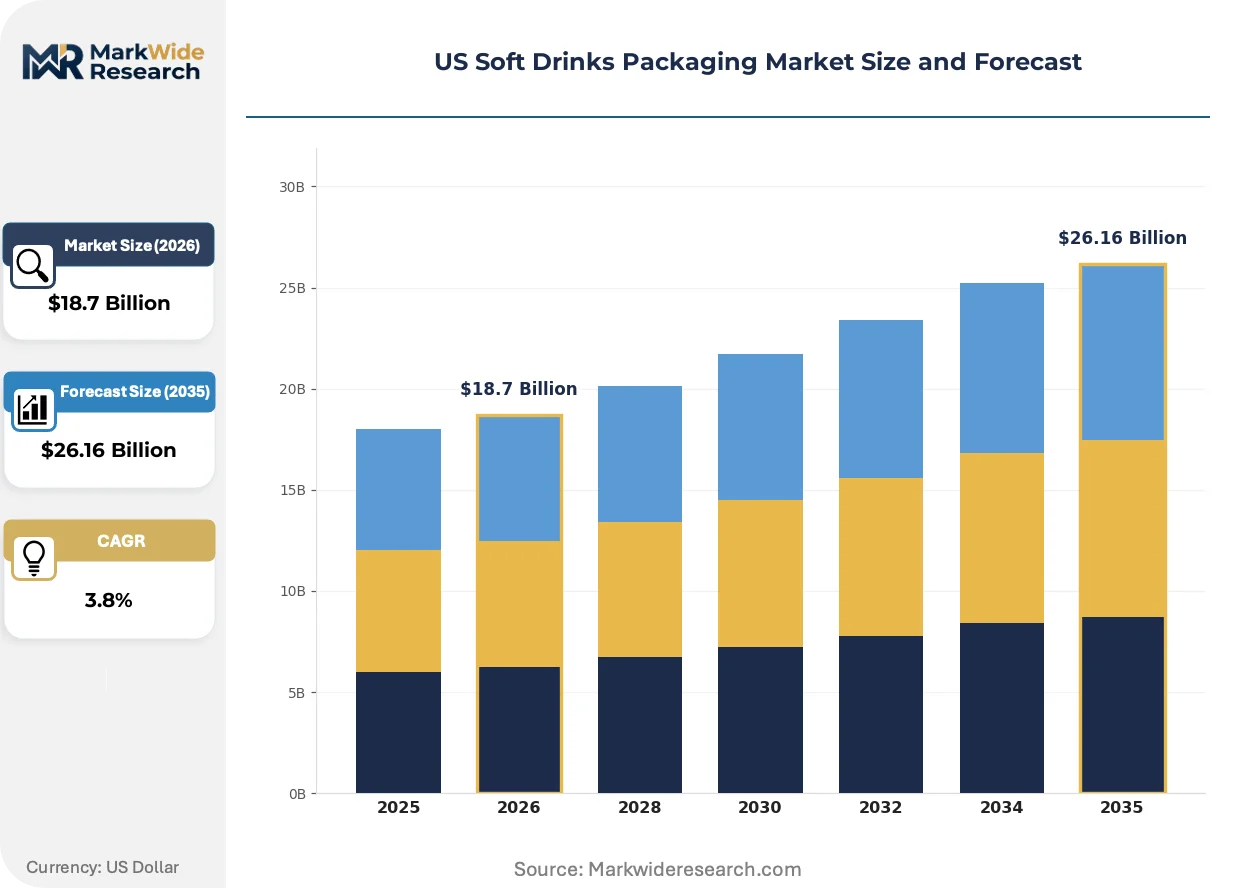
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Bottles, Pouches, Cartons Material: Glass, Plastic, Aluminum, Paperboard Size: Single-Serve, Two-Liter, Family Pack, Bulk Closure Type: Screw Cap, Snap Cap, Crown Cap, Flip Top |
| Companies Covered | Ball Corporation, Crown Holdings, Amcor, Tetra Pak, Owens-Illinois, Ardagh Group, Berry Global, WestRock Company, Sealed Air Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Soft Drinks Packaging Market Evolving Landscape
Digital printing and smart packaging integration are collapsing minimum order quantities and enabling hyper-localized SKU proliferation, while regulatory pressure on recycled content ratchets up material traceability requirements across the value chain.
Digital can printing technology is decentralizing decoration workflows by eliminating mechanical plate changes and enabling lot sizes below 5,000 units. Regional craft beverage producers are adopting this capability to support seasonal and collaborative limited releases. The technology is decentralizing geographic concentration of label manufacturing and collapsing lead times from weeks to days.
California's SB 54 implementation timeline is mandating 30% recycled content thresholds by 2028 and establishing producer responsibility organization governance structures. Brand owners must fund and operate collection infrastructure or pay penalty fees to CalRecycle. PET bottle formats face the steepest compliance cost escalation given competing demand for recycled flake from textile and sheet applications.
Retailers are consolidating supplier bases around vendors with verified mass balance certification for recycled content, displacing fragmented procurement across multiple converters. Walmart and Target sustainability scorecards now weight packaging circularity metrics in shelf placement algorithms. This preference shift is most visible in the Northeast and West Coast markets where municipal recycling infrastructure supports higher diversion rates.
US Soft Drinks Packaging Market Segmentation
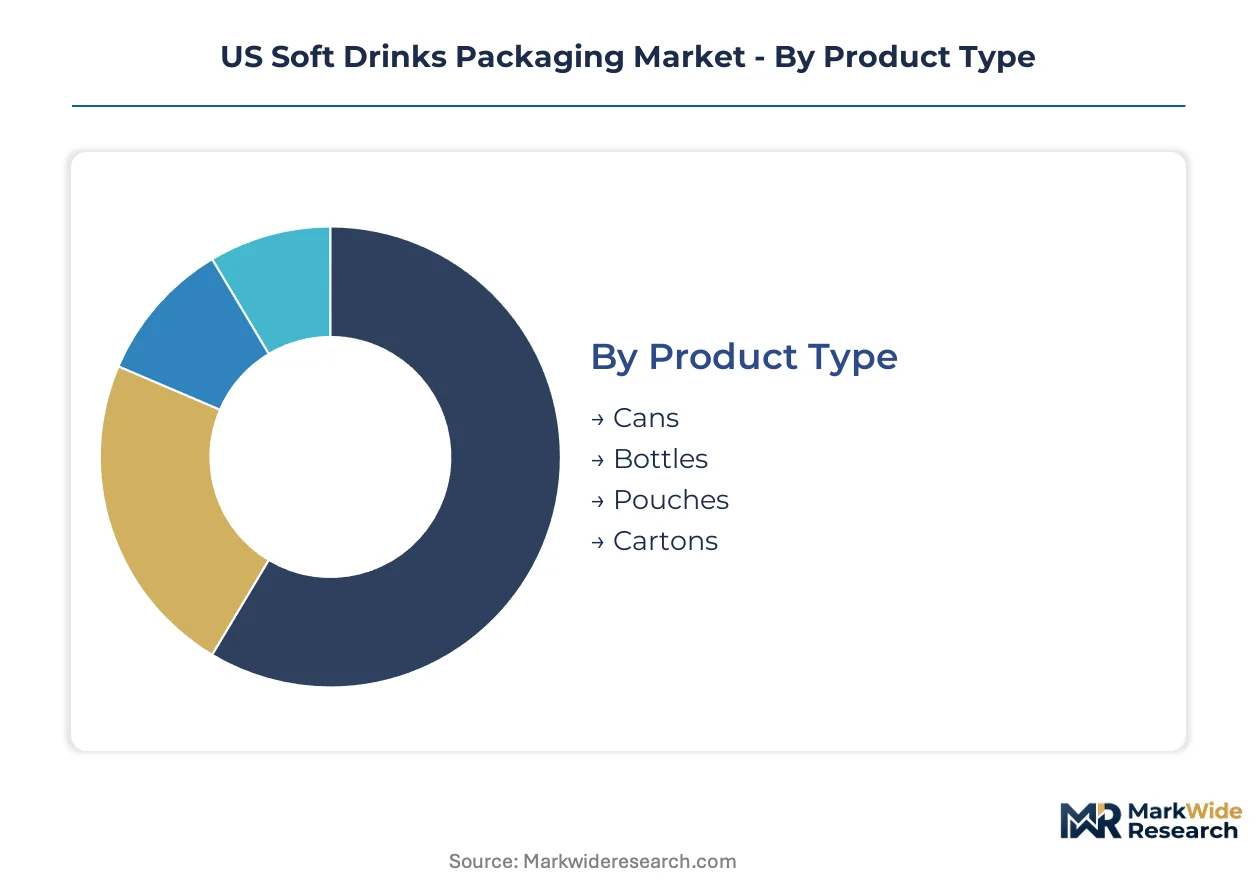
Packaging format selection in the US soft drinks sector follows beverage carbonation levels, shelf-life requirements, and retail channel specifications. Material and closure combinations determine filling line compatibility, distribution durability, and end-consumer convenience expectations.
Product Type:
Upgrade cycles in filling equipment and retailer sustainability mandates are accelerating format transitions away from legacy packaging toward higher-recyclability alternatives.
- Cans:Two-piece aluminum construction with internal epoxy-phenolic lacquer coatings withstands internal pressures of 90-100 psi during carbonated filling. Demand concentrates in Southwest and Southeast states where beverage manufacturing clusters have expanded near aluminum rolling mills, driven by sparkling water brands abandoning PET for curbside recycling acceptance rates.
- Bottles:PET multilayer barrier structures with oxygen-scavenging additives preserve carbonation and prevent flavor scalping in non-alcoholic beverages. The segment faces margin pressure from California's SB 54 recycled content mandates and competing demand for post-consumer flake from textile applications.
- Pouches:Flexible laminated films with spouted fitments serve niche energy drink and children's beverage segments requiring lightweight logistics.
- Cartons:Aseptic brick structures with aluminum foil and polyethylene laminates enable shelf-stable distribution without refrigeration infrastructure.
Volume placements concentrate in Cans; the faster expansion belongs to Cartons as ambient supply chain optimization gains traction.
Material:
Procurement priorities are diverging based on CalRecycle compliance timelines and domestic reprocessing capacity availability.
- Aluminum:Beverage-grade sheet with magnesium-silicon alloying delivers infinite recyclability through the used beverage can loop. US rolling mills are rebalancing capacity from automotive alloys toward canbody substrate as sparkling water adoption accelerates.
- Plastic:PET homopolymer and copolymer resins face recycled content threshold requirements under California SB 54 implementation. The segment encounters flake supply constraints from competing textile and thermoform demand.
- Glass:Amber and flint soda-lime compositions retain premium positioning in craft and specialty segments where tactile differentiation supports price realization.
- Paperboard:Liquid packaging board with polyethylene extrusion coatings serves aseptic carton applications requiring mechanical rigidity and moisture resistance.
Aluminum commands the largest volume position; paperboard is climbing the fastest as brands pursue refrigeration-free distribution formats.
Size:
Format sizing follows channel-specific consumption occasions and retail shelf-space economics rather than manufacturing scale efficiencies.
- Single-Serve:12-ounce and 16-ounce aluminum cans and PET bottles dominate convenience store and vending machine channels. This segment aligns with on-the-go consumption patterns and impulse purchase behavior.
- Two-Liter:PET bottles with HDPE screw closures anchor supermarket and mass merchant home consumption occasions. The format faces volume erosion from declining carbonated soft drink per-capita consumption.
- Family Pack:Multi-can fridge packs and 1.5-liter bottle configurations serve household stock-up shopping missions.
- Bulk:5-gallon bag-in-box and 2.5-gallon pouches supply foodservice fountain systems and office beverage dispensers.
Single-Serve formats generate the highest unit volumes; Family Pack configurations are gaining share fastest through warehouse club channel expansion.
Closure Type:
Closure selection intersects with carbonation retention engineering, child-safety requirements, and opening torque specifications for demographic accessibility.
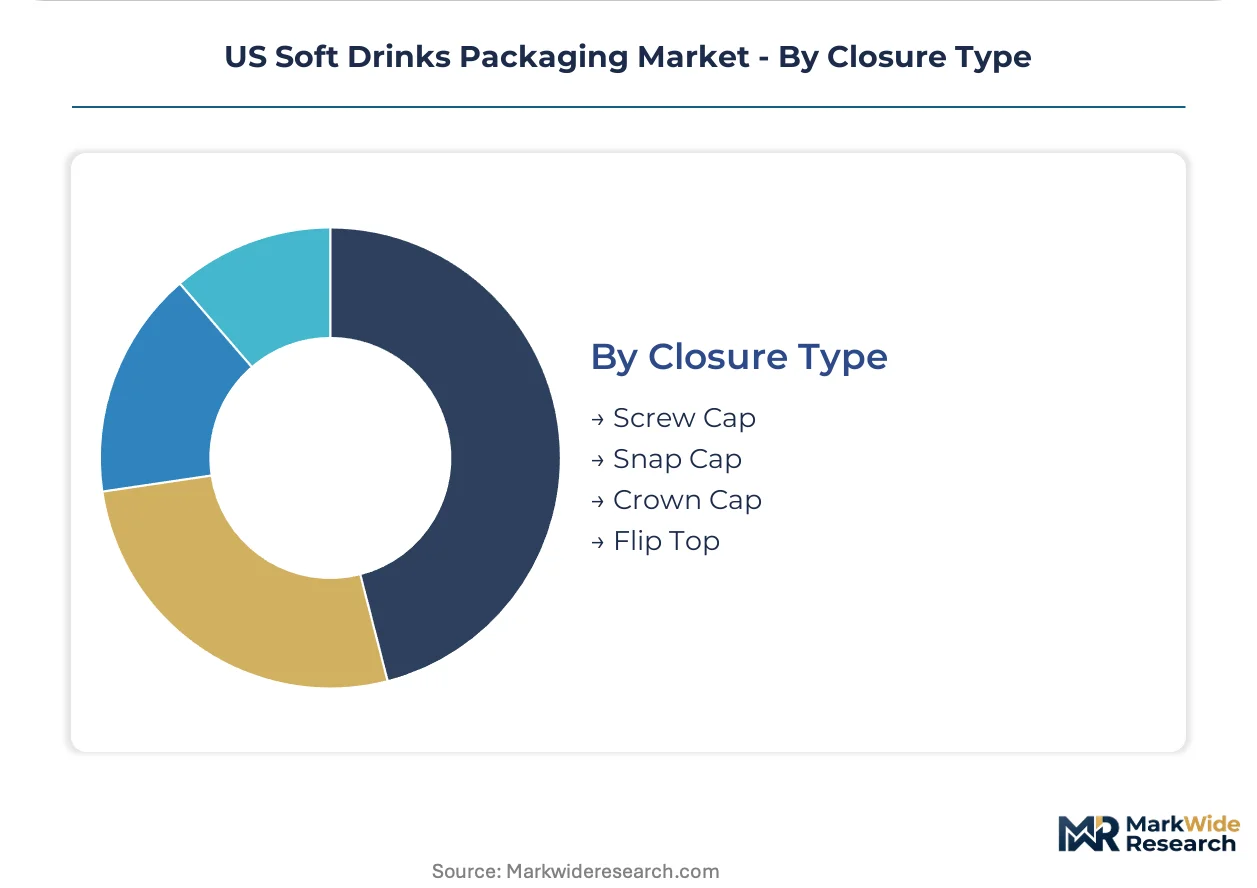
- Screw Cap:HDPE and PP continuous-thread designs with induction foil seals provide resealability for multi-serve PET bottles. This closure type dominates still and lightly carbonated beverage applications.
- Snap Cap:Integral hinge designs with audible engagement feedback serve sports drink and enhanced water segments requiring one-handed operation.
- Crown Cap:Lined metal shells crimped onto glass bottle finishes retain premium authenticity cues for craft soda and heritage brands.
- Flip Top:Stay-on-tab aluminum ends with optimized aperture geometry enable controlled pouring from two-piece beverage cans.
Screw Cap installations lead in absolute units; Flip Top configurations are expanding most quickly as can adoption displaces bottle formats across sparkling categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast resin corridors and Southeast aluminum rolling capacity anchor US soft drinks packaging supply chains. Beverage manufacturing clusters concentrate near these feedstock localities to compress inbound logistics costs. State-level extended producer responsibility mandates create divergent compliance burdens across sub-regional markets.
Southwest
Texas and Arizona concentrate PET bottle manufacturing proximate to Gulf Coast resin plants and Mexico-border maquiladora networks. California's SB 54 recycled content mandates spill over into supplier procurement decisions across the broader region. Phoenix and Dallas-Fort Worth metro areas host expanding contract filling operations for sparkling water brands migrating to aluminum formats.
Southeast
Georgia, Florida, and the Carolinas anchor aluminum can demand growth near Novelis and Ball Corporation rolling mill investments. Florida's beverage excise tax structure favors single-serve can formats in convenience retail channels. Atlanta and Charlotte logistics hubs enable rapid distribution to expanding warehouse club footprints throughout the Sun Belt.
Midwest
Ohio and Illinois retain legacy glass bottle production for craft soda and premium heritage brands despite broader format decline. Indiana's regulatory environment for pressurized filling operations supports carbonated beverage concentration near Chicago distribution networks. Detroit and Cleveland industrial corridors maintain specialized coating and printing capabilities for seasonal promotional packaging.
Northeast
New York and Pennsylvania municipal recycling infrastructure supports higher PET diversion rates, attracting brands with California-style circularity commitments. Massachusetts and Connecticut extended producer responsibility legislation tracks California SB 54 implementation timelines. Philadelphia and Boston metro areas concentrate aseptic carton demand for shelf-stable, refrigeration-free distribution in urban convenience retail.
Pacific Northwest
Washington and Oregon aluminum smelting history underpins regional expertise in beverage-grade substrate specification and quality assurance. Seattle and Portland sustainability-forward consumer bases drive early adoption of refillable bottle pilot programs and packaging-free retail formats. Regional grocers weight circularity metrics heavily in supplier scorecards, accelerating format transitions ahead of national trends.
US Soft Drinks Packaging Market Competitive Landscape
Global majors compete with regional champions across material platforms and filling-line integration depth. The vendor base organizes around three tiers: integrated metal producers with captive aluminum supply, diversified packaging conglomerates spanning rigid and flexible formats, and specialized converters focused on single material categories. Strategic moves concentrate on M&A for recycling infrastructure control and capacity expansion near beverage manufacturing clusters.
Within the integrated metal tier, Ball Corporation and Crown Holdings exemplify supply chain architectures that combine upstream aluminum rolling with downstream canbody and end manufacturing. Amcor occupies a diversified position across PET, flexible films, and pharmaceutical-grade barrier structures. These three anchors represent distinct competitive vectors: captive metal integration, specialized closure engineering, and multi-material platform breadth.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Amcor |
| Tetra Pak |
| Owens-Illinois |
| Ardagh Group |
| Berry Global |
| WestRock Company |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
Warehouse club and mass merchant procurement concentration anchors contract-based long-term offtake agreements across aluminum can and PET bottle supply tiers. Pricing stratifies across premium certified-sustainable, standard food-grade, and economy non-certified material tiers, with California SB 54 compliance costs compressing margins at the economy end.
Pricing Analysis
Service-bundling separates technical support and coating formulation expertise from base material supply in aluminum can contracts. Three-tier pricing structure across premium certified-sustainable, standard food-grade, and economy non-certified tiers reflects mass balance certification and recycled content verification levels. Cost compression in economy PET bottle grades is intensifying because competing textile demand tightens post-consumer flake availability. Small regional craft beverage producers exhibit highest price sensitivity, while multinational sparkling water brands with sustainability scorecard commitments absorb premium tier pricing.
Supply Chain Analysis
Direct-to-beverage-manufacturer channels handle high-volume demand from Southwest and Southeast production clusters, bypassing distributor markups for annual volume commitments. Domestic supply draws from Gulf Coast resin corridors, Southeast aluminum rolling mills, and Mexico-border maquiladora networks for component assembly. Raw material dependencies center on beverage-grade aluminum sheet, PET homopolymer resin, and epoxy-phenolic can coatings. Single-source vulnerability in domestic beverage-grade aluminum substrate creates allocation risk during automotive alloy demand spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing technology is displacing mechanical plate-based decoration workflows, collapsing minimum order quantities and enabling hyper-localized SKU proliferation that legacy converters struggle to match.
For Market Incumbents: Cement captive aluminum supply through backward integration into Southeast rolling mill capacity or long-term offtake agreements with Novelis and Ball Corporation. Defend against digital printing entrants by acquiring specialized coating formulation talent pools before veteran technical expertise fully attrites. Prioritize FDA FCN approval investments for post-consumer PET applications to lock in recycled content compliance ahead of California SB 54 enforcement timelines. For New Entrants and Emerging Players: Digital can printing capability offers entry into seasonal craft beverage segments requiring lot sizes below 5,000 units with lead times compressed to days. Target underpenetrated aseptic carton applications in mainstream carbonated categories where ambient supply chain optimization remains undeveloped. Pursue direct-to-store distribution partnerships with micro-fulfillment centers and e-commerce subscription platforms bypassing traditional grocery distributor networks. For Investors and Strategic Acquirers: The window for entry favors specialized converters with verified mass balance certification and established retailer sustainability scorecard relationships. Long-term viability hinges on control over domestic reprocessing infrastructure for used beverage can loops and post-consumer PET flake supply. Monitor CalRecycle penalty fee structures and producer responsibility organization governance formation as inflection indicators for compliance cost escalation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captive beverage-grade substrate supply secures allocation priority during automotive demand spikes. |
| Digital Printing Technology Deployment | Decentralized decoration workflows collapse minimum order quantities for regional craft brands. |
| FDA FCN Approval Investment | Accelerated food contact notification timelines unlock post-consumer PET bottle applications. |
| Aseptic Filling Line Expansion | Hydrogen peroxide sterilization capacity captures shelf-stable carbonated beverage white space. |
| Producer Responsibility Organization Participation | CalRecycle compliance governance structures mandate brand-funded collection infrastructure. |
Research Methodology
SEC 10-K filings, EPA emissions disclosures, and CalRecycle regulatory databases formed the secondary backbone for supply chain and compliance cost quantification. Primary interviews with beverage packaging procurement directors, aluminum rolling mill operations managers, FDA regulatory affairs specialists, and retail category buyers combined with secondary validation through bottom-up facility capacity analysis and top-down market sizing triangulation.
Historical trendline analysis of aluminum can and PET bottle shipment volumes established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated packaging format, material substrate, closure type, and geographic production cluster dimensions. CAGRs were derived from regression analysis against carbonated soft drink and sparkling water consumption patterns, with specific inputs from filling line capacity expansion announcements and retailer sustainability scorecard weighting shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under California SB 54 enforcement acceleration or automotive alloy demand spikes diverting aluminum sheet capacity. Forecasts reflect assumptions regarding recycled content threshold compliance timelines and domestic reprocessing capacity buildout rates. Periodic stress-testing of base assumptions is recommended against EPA coating emissions rule amendments and OSHA pressurized operation certification timeline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
French Square Bottle Market