
 Twist Opening Cartons Market | 2026-2036
Twist Opening Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Opening Cartons Market Analytics
Pharmaceutical manufacturers is bifurcating twist opening carton demand away from traditional food and beverage buyers as compliance requirements intensify. Tetra Pak dominates aseptic carton technology for liquid dairy and juice applications across Nordic and Latin American markets. Amcor Limited leverages its global film and carton integration capabilities to serve multinational pharmaceutical clients with tamper-evident twist formats. Mondi Group anchors European supply through its recycled fiberboard operations in Slovakia and Poland, competing on sustainability credentials against virgin-material rivals.
Twist opening cartons are rigid paper-based containers featuring helical-thread closures that permit resealing without separate caps, typically constructed from liquid packaging board with polyethylene barrier layers and aluminum foil for oxygen protection. The primary commercial purpose centers on extending product freshness for liquid and semi-liquid goods while eliminating loose components that complicate recycling streams. Premium Twist formats command disproportionate margin pools in cosmetics and specialty beverages where unboxing experience drives brand differentiation. Eco-Friendly Twist segments are gaining fastest in European markets where Extended Producer Responsibility schemes penalize non-recyclable multi-material construction. Composite material substrates remain structurally dominant despite recycling complexity, though Recycled Material grades are narrowing the performance gap through improved fiber processing.
FDA child-resistant packaging standards under 16 CFR 1700 shape pharmaceutical twist-carton specifications in the United States, while the EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that reshape material sourcing across European supply chains. Germany's national packaging registry, LUCID, enforces strict producer participation rules that filter market access for non-compliant carton suppliers. Stakeholders must monitor evolving state-level extended producer responsibility legislation in the United States, where fragmented regulatory development threatens to replicate the European compliance burden without harmonized federal standards.
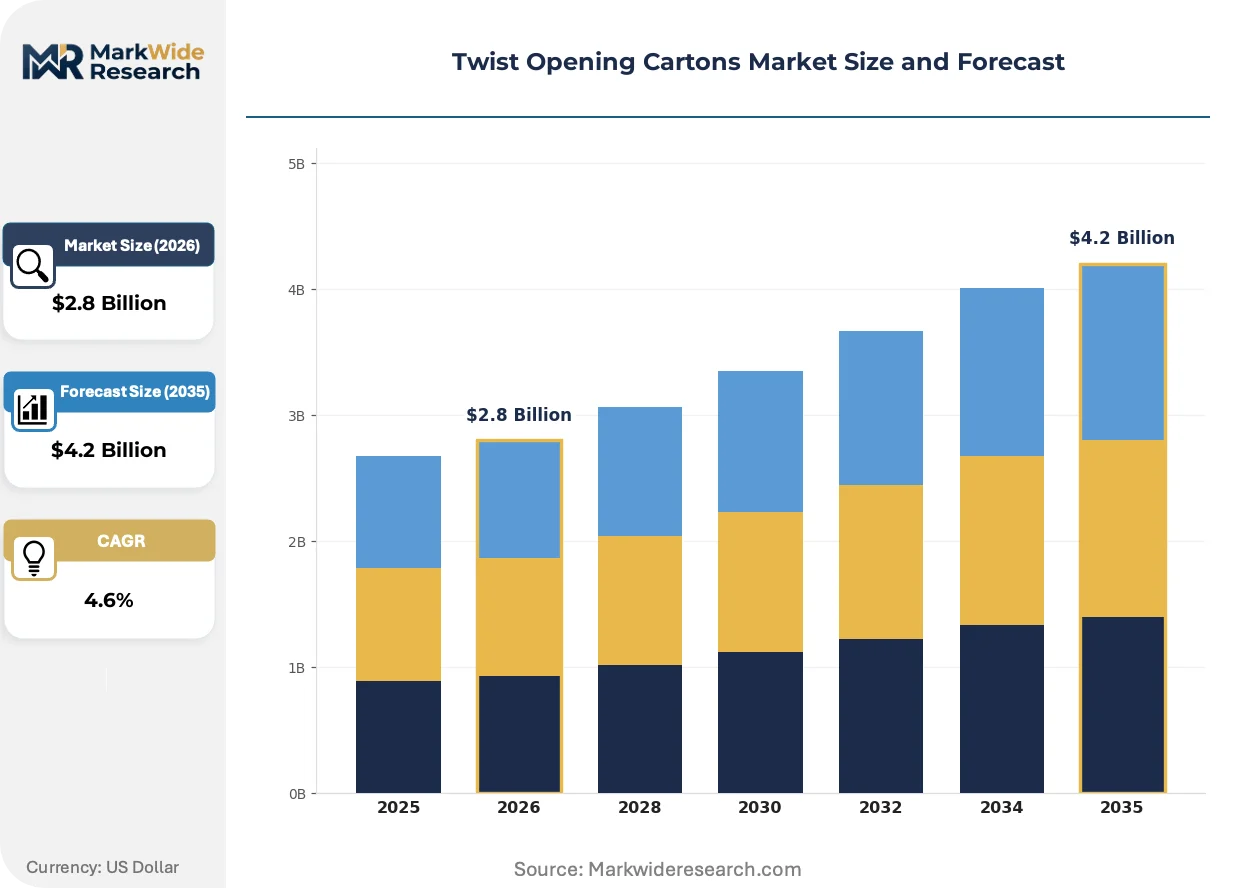
Market Dynamics
Pharmaceutical compliance mandates and circular economy packaging rules are restructuring procurement priorities, pulling investment toward child-resistant formats and recyclable substrates while squeezing multi-material legacy designs.
Growth Catalysts
- Child-resistant closure mandates:FDA 16 CFR 1700 standards and EU safety directives are expanding pharmaceutical uptake of twist-seal cartons for pediatric medication protection.
- Extended Producer Responsibility schemes:Germany's LUCID registry and similar frameworks in France and Italy penalize non-recyclable packaging, accelerating mono-material twist carton adoption.
- Barrier coating advances:Water-based and bio-derived oxygen barriers are displacing aluminum foil laminates in liquid dairy applications, improving end-of-life recyclability without shelf-life sacrifice.
Market Restraints
- Recycled fiber quality inconsistency:Post-consumer pulp variability limits high-speed forming line throughput, constraining output at converted board mills in Poland and Slovakia.
- Helical thread tooling concentration:Precision mold fabrication for twist closures clusters in southern Germany and northern Italy, creating single-source vulnerability for carton assemblers.
- Polyethylene barrier dependency:Fossil-derived sealant layers remain essential for liquid tightness, exposing converters to resin price volatility and regulatory pressure under EU Green Deal targets.
Strategic Opportunities
- Cosmetics unboxing premiumization:Skincare brands in South Korea and Japan are adopting twist-opening gift cartons with tactile finishes, opening margin pools above commodity food packaging.
- Refill system integration:Concentrate-and-dilute household products are pairing with reusable twist-carton dispensers, creating recurring revenue attachments for CPG manufacturers.
- Digital printing convergence:Inline inkjet decoration enables lot-level traceability and regional customization without plate changeover, compressing minimum order quantities for niche beverage launches.
Industry Challenges
- Pharmaceutical validation timelines:Child-resistant certification through FDA or EMA pathways requires 18-24 month stability testing, delaying revenue recognition for new carton formats.
- Legacy line retrofit costs:Converting existing straight-line carton equipment to handle helical-thread closures demands mechanical and controls investment that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Opening Cartons Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Standard Twist, Premium Twist, Eco-Friendly Twist, Custom Twist Material: Cardboard, Plastic, Composite, Recycled Material End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Size: Small, Medium, Large, Extra Large |
| Companies Covered | Tetra Pak, Amcor Limited, Mondi Group, SIG Combibloc, Elopak, WestRock Company, International Paper Company, Greatview, Ecolean, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Opening Cartons Market Evolving Landscape
Material science breakthroughs and regulatory tightening are fragmenting the competitive landscape into sustainability-certified premium tiers and cost-optimized conventional supply, with technology choices increasingly locking in strategic positioning.
Barrier-coated paperboard without aluminum lamination is bifurcating liquid packaging into recyclable and legacy streams. Dairy processors in Nordic markets are adopting these substrates for ambient milk cartons with six-month shelf life. The technology is compressing demand for conventional foil-barrier twist formats in regions with strict sorting infrastructure.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from food-contact cartons. European converters are migrating to clay-based and bio-wax alternatives for semi-liquid product protection. Bakery and ready-meal segments in Germany and France face the steepest compliance deadlines and are accelerating supplier qualification for PFAS-free alternatives.
Direct-to-retail e-commerce fulfillment is reshaping secondary packaging requirements for twist cartons. Fragile liquid products previously shipped in corrugated shippers now travel in primary cartons with integrated cushioning, eliminating one packaging layer. German and Dutch online grocery platforms are driving specification changes that prioritize drop-test performance over traditional shelf-display aesthetics.
Twist Opening Cartons Market Segmentation
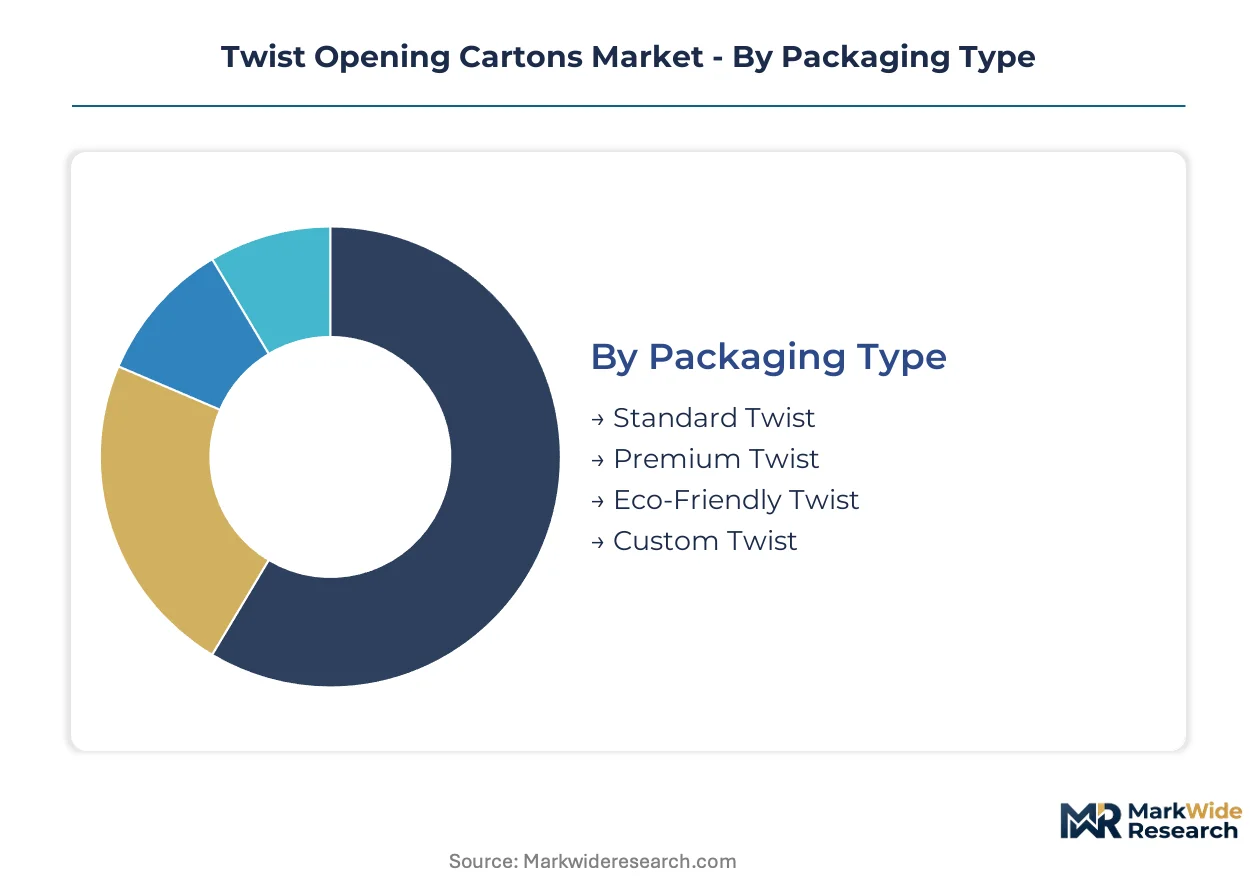
Twist opening carton configurations fragment across four distinct dimensions, each mapping to divergent margin structures and technical requirements. Packaging type and material substrate together determine recyclability credentials and barrier performance, while end-use verticals impose divergent regulatory validation burdens.
Packaging Type:
Premium Twist formats capture the widest margin spreads through tactile finishes and unboxing-driven brand differentiation in cosmetics and specialty beverages.
- Premium Twist:High-grammage liquid packaging board with embossed helical threads and soft-touch coatings commands price premiums in South Korean skincare and Japanese gift confectionery. Demand concentrates where unboxing experience drives repeat purchase intent.
- Eco-Friendly Twist:Mono-material constructions with water-based oxygen barriers and aluminum-free substrates target German and French Extended Producer Responsibility compliance. Nordic dairy processors are adopting these formats for ambient milk with six-month shelf life.
- Standard Twist:Conventional polyethylene-barrier cartons serve commodity liquid dairy and juice applications across Latin American markets.
- Custom Twist:Bespoke thread geometries and branded closure colors support limited-edition beverage launches and pharmaceutical differentiation.
Premium Twist holds installed capacity. Eco-Friendly Twist is rotating up the share rankings.
Material:
Composite substrates dominate unit economics through established supply chains, though recycled fiber grades are narrowing performance gaps.
- Composite:Multi-layer liquid packaging board with aluminum foil and polyethylene laminates delivers superior oxygen barrier for ambient shelf-stable products. Pharmaceutical manufacturers in Germany's Heidelberg-Mannheim corridor specify these substrates for child-resistant medication packaging under EU safety directives.
- Recycled Material:Post-consumer fiberboard with enhanced pulp processing achieves forming line speeds approaching virgin grades. Polish and Slovak mills are expanding output despite quality variability constraints.
- Cardboard:Uncoated or clay-coated solid bleached sulfate serves dry goods and short-shelf-life applications with minimal barrier demands.
- Plastic:Polypropylene and polyethylene twist cartons occupy niche pharmaceutical and laboratory supply segments requiring chemical resistance.
Composite maintains production gravity. Recycled Material is climbing the fastest.
End User:
Pharmaceutical compliance mandates are restructuring procurement priorities away from traditional food and beverage volume buyers.
- Pharmaceuticals:Child-resistant twist closures for over-the-counter medications require FDA 16 CFR 1700 certification and EMA stability validation. German manufacturers face 18-24 month testing timelines that delay revenue recognition for new formats.
- Cosmetics:Skincare and fragrance brands adopt twist-opening gift cartons with magnetic closures and foil stamping for premium unboxing rituals in Tokyo and Seoul.
- Food & Beverage:Liquid dairy and juice processors represent legacy volume demand, though Nordic markets are shifting toward recyclable barrier-coated alternatives.
- Household Products:Concentrate-and-dilute cleaners pair with reusable twist-carton dispensers, creating recurring revenue attachments for CPG manufacturers.
Food & Beverage anchors shipment volumes. Pharmaceuticals is gaining share fastest.
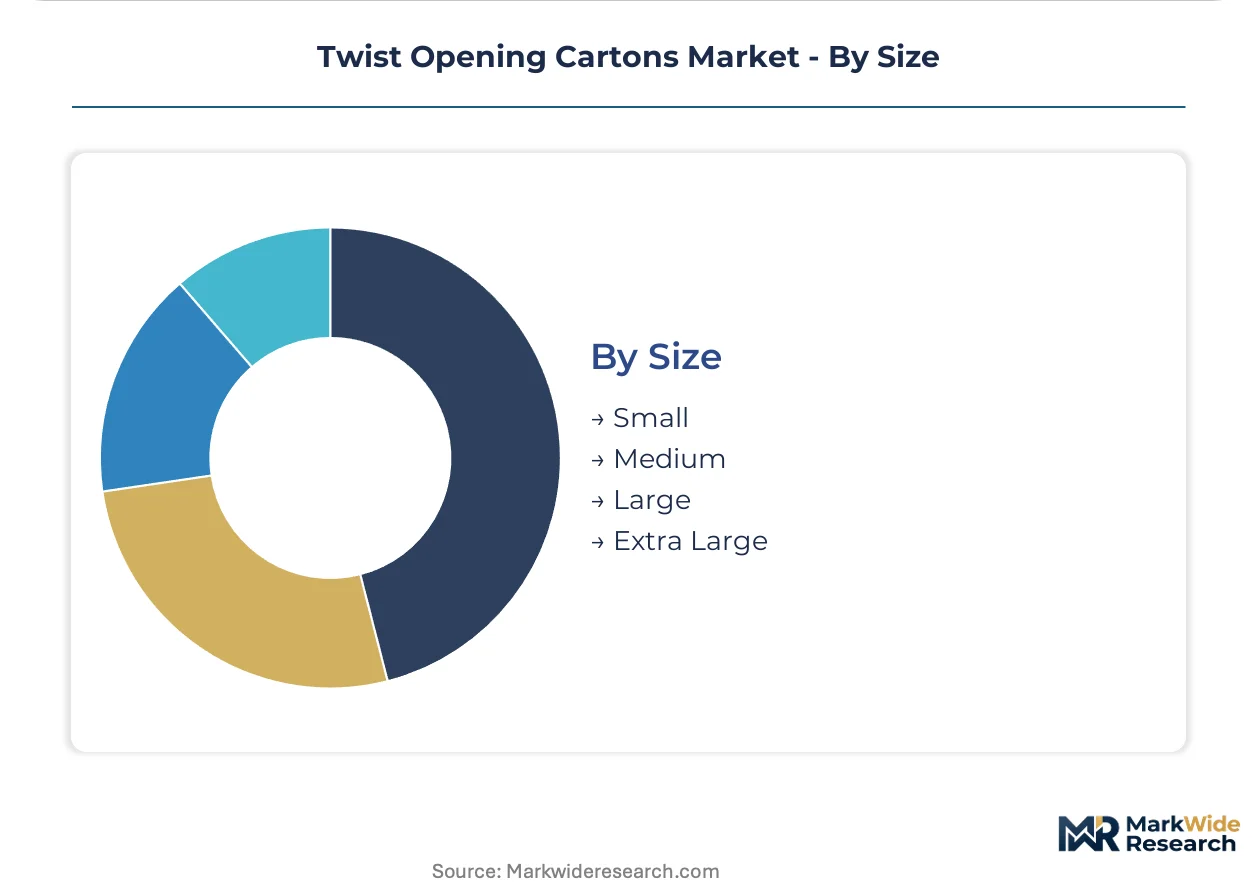
Size:
Medium formats concentrate manufacturing efficiency, while small sizes capture pharmaceutical unit-dose premiums.
- Medium:250-500 milliliter capacities optimize filling line throughput for ambient milk and juice across Nordic and Latin American dairy operations.
- Small:Unit-dose pharmaceutical cartons for pediatric medications command per-unit premiums through precise child-resistant thread engineering.
- Large:Family-size beverage and household product formats serve German and Dutch online grocery platforms with integrated cushioning for drop-test compliance.
- Extra Large:Bulk concentrate dispensers and institutional food service cartons occupy limited niche demand.
Medium holds line utilization. Small is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical buyers cluster in Germany's Heidelberg-Mannheim corridor, while Nordic dairy processors and South Korean cosmetics brands concentrate demand for premium formats. Regulatory divergence between FDA child-resistant mandates and EU circular economy rules splits procurement specifications across Atlantic markets.
Germany
Heidelberg-Mannheim pharmaceutical packaging corridor drives child-resistant twist carton specifications for over-the-counter medications. Germany's LUCID packaging registry enforces strict producer participation rules that filter market access for non-compliant suppliers. Bavarian and Baden-Württemberg converters retrofit legacy filling lines to handle helical-thread closures amid 18-24 month pharmaceutical validation timelines.
United States
FDA 16 CFR 1700 standards expand pharmaceutical uptake of twist-seal cartons for pediatric medication protection. Fragmented state-level extended producer responsibility legislation threatens to replicate European compliance burdens without harmonized federal standards. Midwestern dairy processors and Southeast pharmaceutical contract manufacturers anchor domestic capacity expansion.
France
ANSM safety directives and REACH restrictions on PFAS chemicals accelerate migration to clay-based grease-resistant coatings for food-contact cartons. Île-de-France cosmetics houses and Lyon-based dairy cooperatives specify mono-material recyclable formats under Extended Producer Responsibility penalties. Northern French converters qualify PFAS-free alternatives ahead of steep compliance deadlines.
South Korea
Seoul skincare brands adopt twist-opening gift cartons with tactile finishes and magnetic closures for premium unboxing rituals. MFDS pharmaceutical regulations shape domestic medication packaging specifications alongside export-oriented FDA compliance. Gyeonggi-do converters serve Japanese and domestic cosmetics demand through high-grammage embossed formats.
Sweden
Nordic dairy processors pioneer barrier-coated paperboard without aluminum lamination for ambient milk cartons with six-month shelf life. Swedish sorting infrastructure supports recyclable mono-material adoption that compresses demand for conventional foil-barrier formats. Stockholm and Gothenburg packaging clusters integrate water-based oxygen barriers at commercial scale.
Twist Opening Cartons Market Competitive Landscape
Player mix skews toward integrated packaging conglomerates with captive board supply and specialized carton technology licensors. Tetra Pak and SIG Combibloc anchor aseptic liquid packaging through proprietary filling equipment ecosystems. Three archetypes dominate: diversified materials conglomerates with film-carton integration, pure-play carton specialists with regional board mills, and equipment-integrated technology licensors. Competitive moves concentrate on barrier coating R&D partnerships and pharmaceutical certification capacity expansion.
Among diversified packaging conglomerates, Tetra Pak and Amcor Limited exemplify scale-driven archetypes with global pharmaceutical client coverage. Mondi Group anchors European supply through recycled fiberboard operations in Slovakia and Poland, competing on sustainability credentials. These three occupy positions spanning equipment-integrated technology licensing, materials integration, and regional sustainability-focused supply respectively.
| Leading Market Players |
|---|
| Tetra Pak |
| Amcor Limited |
| Mondi Group |
| SIG Combibloc |
| Elopak |
| WestRock Company |
| International Paper Company |
| Greatview |
| Ecolean |
| Others |
Value Network & Pricing Analysis
Water-based oxygen barrier coatings replacing aluminum foil laminates are simultaneously shifting supply geography toward Nordic coating specialists and compressing margin structures for legacy foil converters. This substitution dynamic redirects procurement flows away from southern European aluminum laminators toward Swedish and Finnish barrier technology developers, while pricing power concentrates with converters mastering mono-material recyclability credentials under Germany's LUCID registry.
Pricing Analysis
Cost-plus contracts indexed to liquid packaging board futures dominate pharmaceutical and dairy procurement, with price differentiation across FDA-certified, EMA-validated, and commodity tiers. Premium-mid-economy pricing differentiation reflects child-resistant certification status and recycled content thresholds. Pricing pressure stems from post-consumer pulp quality variability constraining high-speed line throughput. Food and beverage buyers exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premiums for compliance-certain supply.
Supply Chain Analysis
Germany and Poland anchor liquid packaging board production, with Heidelberg-Mannheim converters specializing in child-resistant helical-thread formats. Southern Germany and northern Italy concentrate precision mold fabrication for twist closures. Raw material dependencies center on polyethylene sealant resins, aluminum foil laminates, and post-consumer fiber pulp. Single-source vulnerability clusters in helical-thread tooling. Distribution runs through converter-direct relationships with pharmaceutical contract manufacturers and dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between FDA child-resistant mandates and EU circular economy rules fragments procurement specifications, creating specialist niches for compliance-certified converters and barrier-coating innovators.
For Market Incumbents: Fortify pharmaceutical certification capacity through EMA stability testing infrastructure in Germany's Heidelberg-Mannheim corridor. Deepen backward integration into water-based barrier coating R&D partnerships with Nordic chemical specialists. Defend against emerging mono-material specialists by locking multi-year offtake agreements with dairy processors ahead of EU Packaging and Packaging Waste Regulation tightening.
For New Entrants and Emerging Players: Anchor in South Korean cosmetics packaging demand for tactile-finish gift cartons with magnetic closures. Target German mid-tier pharmaceutical contract manufacturers underserved by Tetra Pak and SIG Combibloc equipment ecosystems. Pursue digital printing convergence for lot-level traceability as entry wedge against plate-based legacy converters.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European carton specialists holding pharmaceutical validation pipelines but limited barrier-coating R&D. Five-to-ten year viability hinges on mono-material transition execution. Monitor FDA 16 CFR 1700 certification backlog duration as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Partnership | Water-based oxygen barriers displace aluminum foil in Nordic dairy applications under EU Green Deal targets. |
| Pharmaceutical Certification Capacity Expansion | EMA stability testing infrastructure captures 18-24 month validation timelines for child-resistant formats. |
| Mono-Material Line Retrofit | Helical-thread equipment conversion enables LUCID registry compliance for German pharmaceutical suppliers. |
| Digital Printing Integration | Inkjet decoration compresses minimum order quantities for South Korean cosmetics limited-edition launches. |
| Recycled Fiberboard Mill Acquisition | Polish and Slovak post-consumer pulp operations secure sustainability credentials against virgin-material rivals. |
Research Methodology
Cross-validation between converter production data and pharmaceutical procurement records anchors the qualitative findings. Primary interviews with carton equipment engineers, pharmaceutical packaging managers, dairy procurement leads, and barrier coating R&D directors combined with secondary validation from FDA 510(k) filings, EMA marketing authorization databases, EU Packaging and Packaging Waste Regulation impact assessments, and German LUCID registry participation records. Bottom-up capacity utilization models and top-down end-use demand estimates triangulate volume outputs.
Sensitivity analysis across barrier coating adoption curves and pharmaceutical validation timeline scenarios shapes the analytical framework. Segmentation dimensions include packaging type, material substrate, end-use vertical, and geographic regulatory cluster. CAGRs derive from installed base growth rates and replacement cycle dynamics. Forecast inputs incorporate EU Green Deal recycled content mandates and FDA child-resistant packaging enforcement patterns.
Material uncertainties — regulatory timeline delays, post-consumer pulp quality breakthroughs, helical-thread tooling supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about barrier coating shelf-life parity and pharmaceutical certification throughput. Recalibration cycles align with material shifts in EU Packaging and Packaging Waste Regulation implementation and FDA enforcement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Tuck Top Box Market
Cartons
Folding Cartons Market
Cartons
Carton Serialization Machine Market
Cartons
Global Open Top Cartons Market
Cartons
Wax Boxes Market
Cartons
Pizza Cartons Market
Cartons
Japan Corrugated Boxes Market
Cartons
Carton Liners Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Africa Folding Carton Market
Cartons
Braille Cartons Packaging Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Global Hand Carton Sealers Market