
 Metallized Folding Cartons Market | 2026-2036
Metallized Folding Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Metallized Folding Cartons Market Foresight
EU Packaging and Packaging Waste Regulation is hardening the cost-of-entry calculus for converters serving European personal care and food brands. Mayr-Melnhof Karton AG leverages integrated pulp-to-carton operations across Central Europe to sustain margin resilience under compliance pressure. Graphic Packaging International anchors North American beverage and food accounts with high-speed metallized line capacity. Mondi Group competes through specialty kraft and paperboard substrates engineered for thin-gauge metallization.
Metallized folding cartons are paperboard or composite structures laminated with vacuum-deposited aluminum or metallized PET films, typically achieving barrier values below 0.1 g/m²/day moisture vapor transmission to protect oxygen- and light-sensitive contents. Their primary purpose spans premium shelf presence, extended product stability, and tamper-evident closure integration for cosmetics, pharmaceuticals, and confectionery. Aluminum foil material type occupies the dominant share due to established barrier performance and converter familiarity, though PET metallization is gaining traction in fragrance and electronics packaging where dimensional stability matters. Food packaging end use leads volume absorption, while cosmetic packaging commands the widest coating-type experimentation with matte and soft-touch UV finishes.
EMA packaging guidelines, REACH substance restrictions, and EU Green Deal circularity targets collectively shape material selection, adhesive chemistry, and end-of-life labeling obligations across the value chain. FDA food-contact regulations and state-level extended producer responsibility laws in California and New York add compliance layers for exporters targeting North American premium segments. Stakeholders must monitor how deposit-return schemes and recyclability auditing protocols redefine acceptable metallized laminate constructions before committing capital to substrate or coating lines.
Market Dynamics
EU Green Deal circularity targets are forcing metallized carton converters to redesign multi-material laminates for recyclability, compressing profit margins while accelerating R&D spend on mono-material alternatives.
Growth Catalysts
- Premium cosmetic shelf differentiation:Western European fragrance and skincare brands are accelerating metallized carton procurement to secure visual impact in duty-free retail and department store environments.
- REACH substance restrictions:Tighter adhesive chemistry standards are advantaging converters with in-house formulation labs capable of rapid compliance adaptation.
- Rhine-Ruhr packaging belt concentration:Germany's dense cluster of folding carton converters enables just-in-time metallization services that reduce logistics costs for personal care brands.
Market Restraints
- Aluminum foil input volatility:Primary aluminum price swings driven by energy costs in smelting regions transmit directly into metallized laminate production economics.
- Multi-material recyclability barriers:Current PET-aluminum-paperboard laminates face rejection from European paper recycling streams due to contamination thresholds.
- Substitution by rigid metallized plastics:Premium cosmetics brands in Asia-Pacific are piloting metallized injection-molded containers that bypass folding carton converters entirely.
Strategic Opportunities
- Underpenetrated Indian personal care market:Domestic Ayurvedic and natural cosmetics brands remain largely unserved by metallized carton specialists despite rising premiumization.
- Deposit-return scheme alignment:EU member states implementing DRS for packaging create first-mover advantage for converters certifying metallized cartons as returnable.
- Digital printing convergence with metallization:Hybrid inkjet-vacuum deposition lines enable short-run customization for limited-edition cosmetic releases.
Industry Challenges
- Vacuum deposition technician scarcity:Specialized metallization line operators require 18-24 month training curves that outpace converter hiring pipelines.
- Extended producer responsibility compliance timelines:Individual EU member state implementations of packaging fee structures create fragmented reporting obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallized Folding Cartons Market |
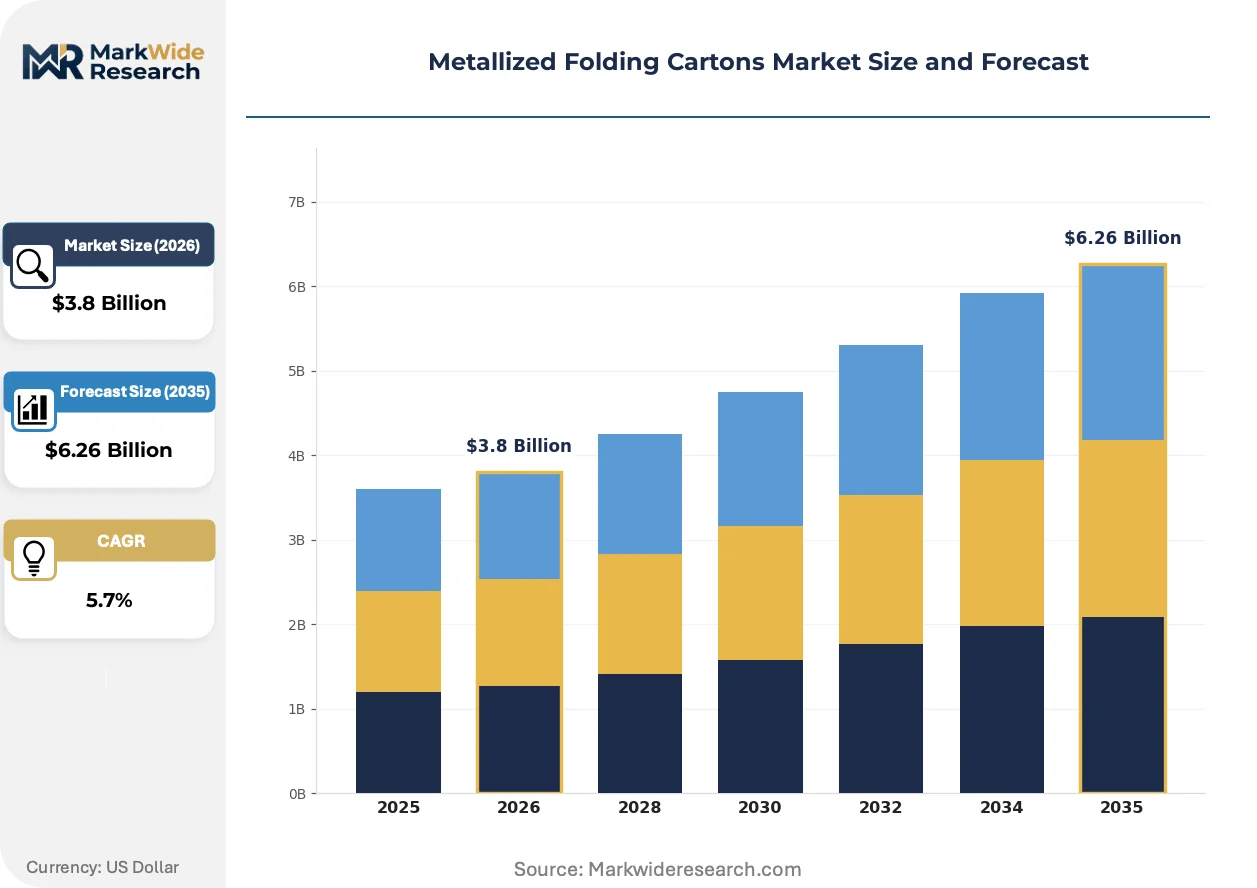
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum Foil, PET, Paperboard, Composite End Use: Food Packaging, Cosmetic Packaging, Pharmaceutical Packaging, Electronics Packaging Coating Type: Glossy Finish, Matte Finish, Heat Seal Coating, UV Coating Design Type: Windowed Cartons, Regular Slotted Cartons, Auto-Lock Bottom, Tuck Top Cartons |
| Companies Covered | Mayr-Melnhof Karton AG, Graphic Packaging International, GMS Industries, DS Smith, Mondi Group, WestRock Company, Smurfit Kappa Group, Sonoco Products, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallized Folding Cartons Market Shifts & Advancements
Metallized folding carton production is pivoting from commodity barrier packaging toward engineered surface solutions that integrate authentication, sustainability credentials, and digital connectivity.
Water-based barrier coatings are rewriting the technical specifications for oxygen-sensitive food and pharmaceutical applications. Swiss chocolate and supplement brands are piloting these aluminum-free laminates to preempt ECHA scrutiny on metal content. The technology is compressing the addressable market for traditional vacuum-deposited aluminum in segments where barrier performance requirements sit below 0.5 g/m²/day.
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing substrate re-engineering across the value chain. Converters must now demonstrate that metallized cartons separate cleanly in standard pulping operations or face exclusion from member state packaging schemes. German and French personal care brands are responding by specifying mono-material paperboard with thin-gauge metallization rather than multi-layer laminates.
Brand procurement teams are consolidating supplier relationships around converters offering integrated design-to-recyclability services. Direct-to-retail cosmetic brands are bypassing traditional packaging distributors to contract directly with Rhine-Ruhr metallization specialists capable of rapid prototyping. This disintermediation is most pronounced in Germany, where converter concentration enables same-day design iteration for limited-edition launches.
Metallized Folding Cartons Market Segmentation
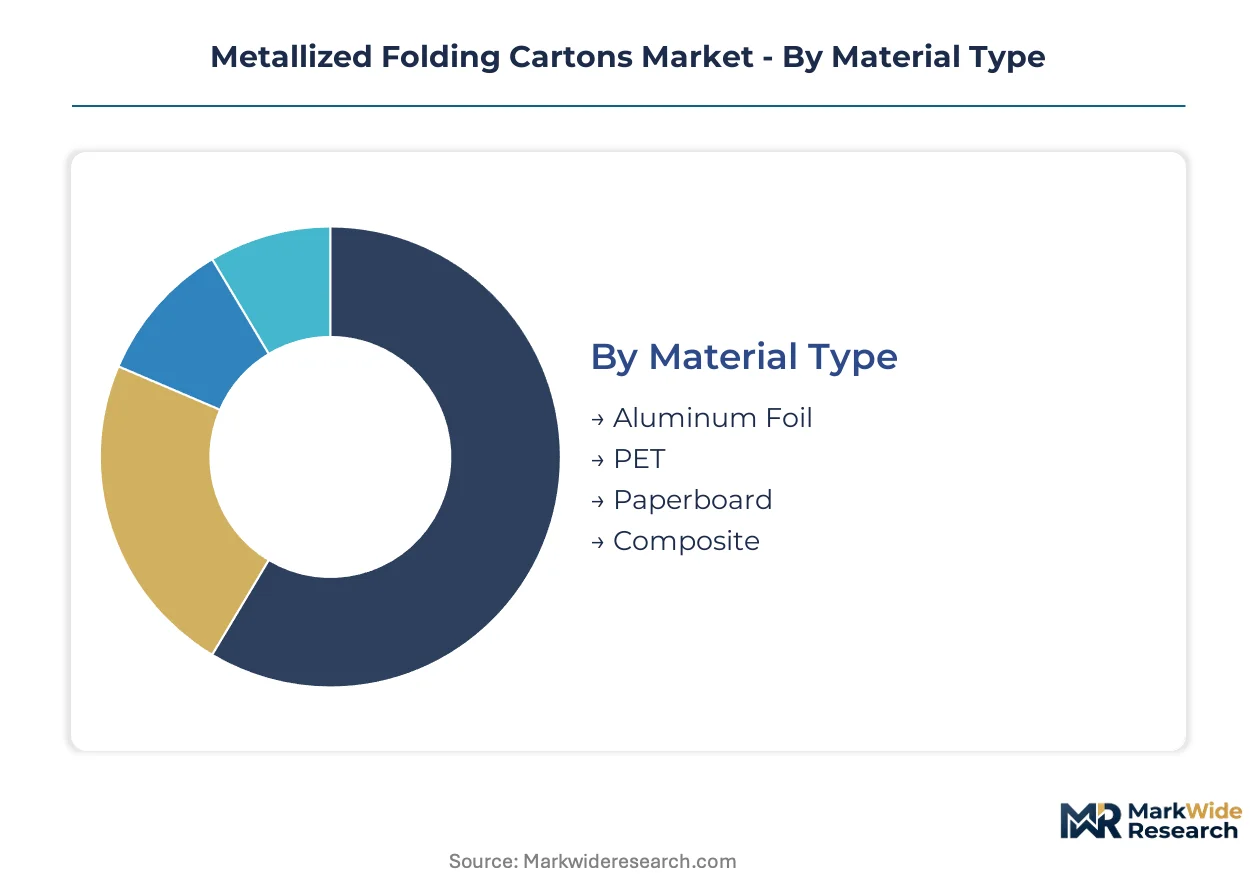
Material selection and coating technology determine barrier performance and recyclability pathways for metallized cartons. End-use specifications drive divergent requirements for moisture resistance, dimensional stability, and shelf presence across cosmetics, food, and pharmaceutical applications.
Material Type:
Aluminum foil dominates standalone barrier applications, while PET and composite structures serve embedded multi-layer systems requiring substrate flexibility.
- Aluminum Foil:Vacuum-deposited aluminum layers achieve moisture vapor transmission rates below 0.1 g/m²/day, making this the default specification for oxygen-sensitive pharmaceuticals and high-fat confectionery. German chocolate brands along the Rhine-Ruhr corridor specify this material type for extended shelf stability under EFSA food-contact compliance.
- PET:Metallized polyethylene terephthalate films provide superior dimensional stability and crease recovery for complex carton geometries. Demand concentrates in fragrance packaging where French and Italian cosmetic houses require tight registration for embossed detailing and soft-touch finishes.
- Paperboard:Uncoated or pre-coated paperboard substrates serve as the structural foundation for thin-gauge metallization, enabling mono-material recyclability under EU Packaging and Packaging Waste Regulation mandates.
- Composite:Multi-layer aluminum-paperboard-PET laminates deliver maximum barrier performance but face mounting rejection from European paper recycling streams due to separation failures in standard pulping operations.
Volume placements concentrate in aluminum foil; the faster expansion belongs to paperboard as mono-material designs gain regulatory preference.
End Use:
Cosmetic applications command premium coating experimentation, while food packaging absorbs the highest absolute tonnage of metallized substrate.
- Food Packaging:Chocolate, nutritional supplements, and premium snacks require metallized barriers to prevent lipid oxidation and moisture ingress. Swiss and Belgian confectionery brands drive specification tightening for odor barrier performance.
- Cosmetic Packaging:Skincare and fragrance cartons prioritize visual differentiation through mirror-finish metallization and tactile coatings. Duty-free retail channels in Germany and France accelerate procurement for limited-edition launches requiring rapid design iteration.
- Pharmaceutical Packaging:Blister pack backers and unit-dose cartons leverage metallized structures for light-blocking and child-resistance compliance under EMA packaging guidelines.
- Electronics Packaging:Anti-static metallized cartons protect sensitive components during distribution, with demand emerging from German automotive electronics suppliers requiring ESD-safe presentation packaging.
Food packaging claims the largest installed base; cosmetic packaging is climbing the fastest as premiumization accelerates across Western European personal care markets.
Coating Type:
Glossy and matte finishes split the premium cosmetic segment, while functional coatings address heat-seal and UV-cure requirements for high-speed converting lines.
- Glossy Finish:High-reflectivity mirror surfaces maximize shelf impact in competitive retail environments. French fragrance houses specify this coating for department store displays where light capture drives consumer attention.
- Matte Finish:Soft-touch and satin metallization conveys understated luxury for skincare and men's grooming brands. German natural cosmetics producers favor this aesthetic to align with sustainability messaging while maintaining premium positioning.
- Heat Seal Coating:Thermally activated adhesive layers enable tamper-evident closure integration for pharmaceutical and food applications requiring hermetic seals.
- UV Coating:Ultraviolet-cured protective layers enhance scuff resistance and chemical durability for cartons exposed to handling in high-traffic retail environments.
Glossy finish retains the highest shipment volumes; matte finish is gaining share fastest as soft-touch aesthetics displace mirror metallization in premium skincare.
Design Type:
Structural complexity correlates with automation compatibility and unboxing experience requirements across e-commerce and retail channels.
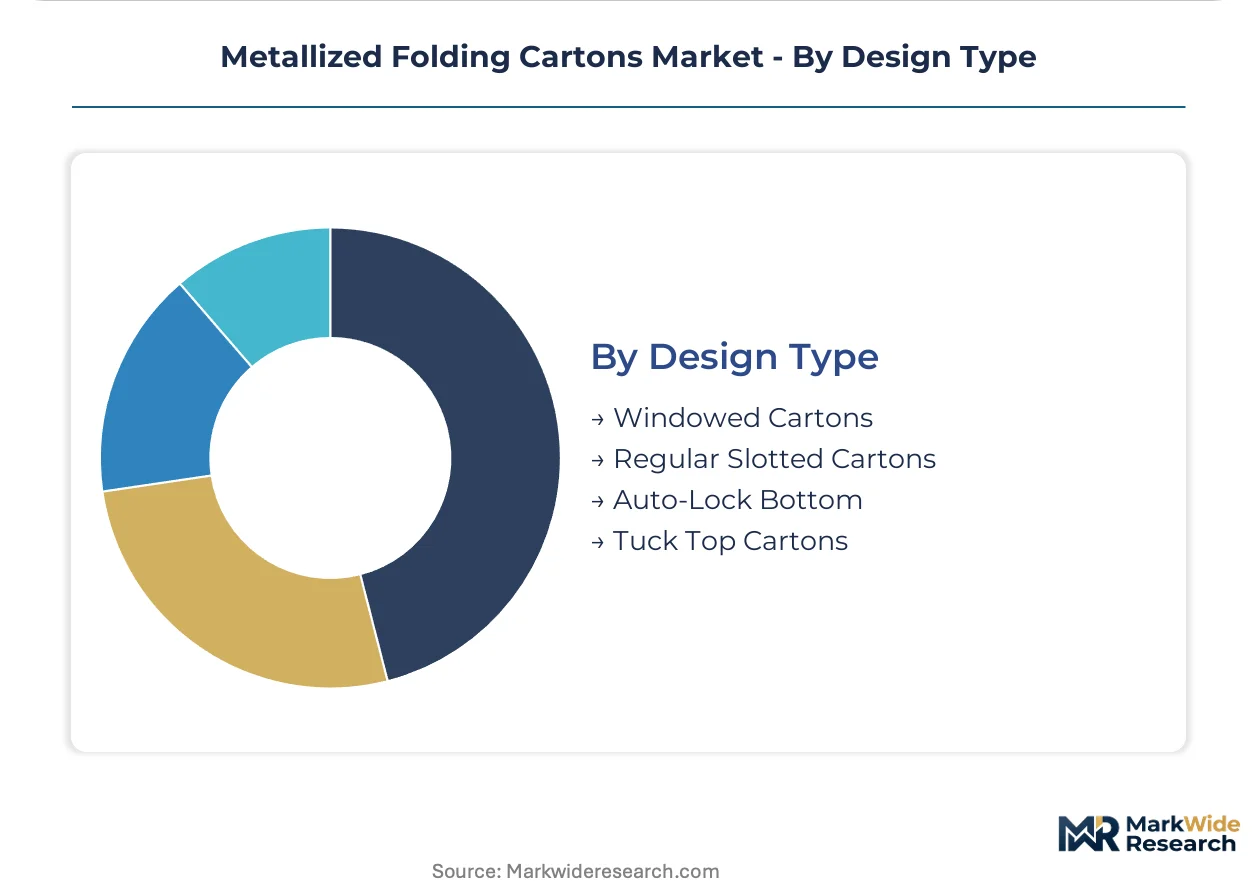
- Windowed Cartons:Die-cut apertures with transparent film windows combine metallized borders with product visibility for confectionery and cosmetics. Belgian praline brands use this design to showcase color differentiation while maintaining barrier protection.
- Regular Slotted Cartons:Standard RSC formats dominate high-volume food applications where shipping efficiency outweighs shelf presentation requirements.
- Auto-Lock Bottom:Pre-glued base structures enable rapid assembly without tape or adhesive, preferred by German e-commerce cosmetics brands for unboxing experience optimization.
- Tuck Top Cartons:Friction-fit closure systems provide resealability for multi-use pharmaceutical and supplement packaging.
Regular slotted cartons handle the greatest throughput; windowed cartons show the steepest expansion trajectory as visual merchandising intensifies in premium retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Rhine-Ruhr corridor concentrate metallized carton production capacity near German personal care brand headquarters. Tax-advantaged manufacturing parks in India's western states attract converters serving domestic cosmetics markets. Special economic zones in China's Yangtze River Delta host integrated substrate-metallization facilities for export-oriented electronics packaging.
Germany
Fragrance and skincare brands along the Rhine-Ruhr packaging belt accelerate metallized carton procurement for duty-free retail channels. ECHA substance restrictions under REACH tighten adhesive chemistry standards, advantaging converters with in-house formulation capabilities. The Cologne-Düsseldorf corridor hosts dense clusters of folding carton specialists offering same-day prototyping for limited-edition cosmetic launches.
France
Paris-based luxury houses specify mirror-finish metallization for department store displays where light capture drives consumer attention. ANSM packaging guidelines impose child-resistance and tamper-evidence requirements that favor converters integrating metallized barriers with functional closures. The Île-de-France region concentrates design-to-recyclability service providers serving direct-to-retail cosmetic brands.
India
Domestic Ayurvedic and natural cosmetics brands in Maharashtra and Gujarat remain largely unserved by metallized carton specialists despite accelerating premiumization. BIS packaging standards and FSSAI food-contact regulations create compliance thresholds that favor organized converters over fragmented local suppliers. The Mumbai-Pune industrial corridor attracts substrate manufacturers expanding thin-gauge metallization capacity for pharmaceutical applications.
United States
California and New York state-level extended producer responsibility laws add compliance layers for metallized carton exporters targeting premium North American segments. FDA food-contact regulations govern barrier specifications for nutritional supplement packaging. The Midwest packaging belt around Chicago anchors high-volume beverage and confectionery accounts requiring metallized barrier performance.
China
Automotive electronics suppliers in the Yangtze River Delta specify anti-static metallized cartons for ESD-sensitive component distribution. MIIT industrial standards and dual carbon goals pressure converters toward mono-material substrate designs compatible with domestic recycling infrastructure. The Shanghai-Suzhou corridor integrates vacuum deposition capacity with digital printing lines for short-run customization.
Metallized Folding Cartons Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated pulp-to-carton operators controlling substrate supply, high-speed converting specialists anchoring beverage and food accounts, and substrate engineers competing through specialty kraft and paperboard formulations. Dominant competitive moves include backward integration into metallization equipment operation and geographic expansion into underpenetrated personal care markets through certified recyclability offerings.
Within the integrated operator tier, Mayr-Melnhof Karton AG exemplifies margin resilience through captive pulp supply and Central European production density. Among North American converters, Graphic Packaging International occupies a position defined by high-throughput metallized line capacity serving anchored beverage accounts. Mondi Group represents the substrate engineering archetype, competing through specialty kraft and paperboard substrates purpose-built for thin-gauge metallization processes.
| Leading Market Players |
|---|
| Mayr-Melnhof Karton AG |
| Graphic Packaging International |
| GMS Industries |
| DS Smith |
| Mondi Group |
| WestRock Company |
| Smurfit Kappa Group |
| Sonoco Products |
| Huhtamaki |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EU Green Deal-compliant mono-material designs and legacy multi-layer laminates manifests in both pricing premiums and sourcing configurations. Rhine-Ruhr converters command lead-time premiums for rapid-turnaround cosmetic prototyping while spot-market aluminum foil purchases compress margins at commodity-tier operations.
Pricing Analysis
Lead-time-driven pricing stratification rewards converters offering same-day metallization iteration for limited-edition fragrance launches with 15-20% premiums over standard-batch contracts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified mono-material specialists from commodity aluminum-laminate producers. Cost compression in the standard tier is intensifying because ECHA substance restrictions force adhesive reformulation R&D. Mass-market food brands exhibit highest price sensitivity; luxury cosmetic houses show lowest, prioritizing shelf differentiation over unit economics.
Supply Chain Analysis
Domestic-content mandates under EU Packaging and Packaging Waste Regulation are reshaping sourcing toward certified European paperboard mills. Production gravity centers on Germany, France, and Austria for high-barrier cosmetic applications, with China and India supplying substrate for electronics packaging. Raw material dependencies include primary aluminum from smelters in Norway and Iceland, metallized PET films from German coating specialists, and specialty kraft pulp from Nordic integrated operators. Single-source vulnerability concentrates in vacuum deposition equipment, where two German engineering firms dominate global installation bases. Distribution runs through converter-direct relationships with personal care brand procurement teams, bypassing traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Captive pulp supply and in-house metallization equipment operation represent the decisive upstream levers separating margin-resilient operators from price-takers.
For Market Incumbents: Anchor high-volume beverage and food accounts through long-term offtake agreements that commit dedicated metallization line capacity. Defend against substitution by rigid metallized plastics through rapid prototyping services that injection-molding cannot match. Deepen backward integration into specialty paperboard substrate engineering to preempt REACH compliance costs at supplier tier. For New Entrants and Emerging Players: Domestic Ayurvedic cosmetics brands in Maharashtra and Gujarat remain largely unserved by metallized carton specialists despite accelerating premiumization. Target pharmaceutical blister-pack backers in India where BIS standards favor organized converters over fragmented local suppliers. Lead with certified mono-material recyclability to differentiate from legacy multi-layer laminate incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified packaging conglomerates seeking European personal care exposure. Long-term viability hinges on converters achieving integrated pulp-to-carton economics within a decade. Target mid-cap Rhine-Ruhr specialists with captive metallization capacity and established brand-direct relationships. Watch ECHA substance restriction implementation timelines as inflection indicator for compliance-cost winners and losers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Paperboard | Captive kraft supply insulates Mayr-Melnhof Karton AG from EEA pulp price volatility. |
| Mono-Material Recyclability Certification | EU Green Deal alignment opens German deposit-return scheme participation for certified converters. |
| Hybrid Digital-Metallization Line Investment | Inkjet-vacuum deposition convergence enables short-run customization for limited-edition cosmetic releases. |
| Direct-to-Brand Procurement Bypass | Same-day prototyping contracts with Düsseldorf fragrance houses disintermediate traditional packaging distributors. |
| Anti-Static Electronics Packaging Capacity | ESD-safe carton production for Yangtze River Delta automotive suppliers diversifies beyond personal care exposure. |
Research Methodology
Document review covered trade customs data, EU regulatory filings, and SEC disclosures from publicly listed packaging conglomerates, complemented by interviews with folding carton plant managers, cosmetic brand procurement directors, metallization equipment engineers, and REACH compliance specialists at ECHA-registered adhesive formulators. Secondary validation drew from EMA packaging guidelines, BIS standards documentation, and FSSAI food-contact regulations. Bottom-up volume modeling triangulated against top-down industry association aggregates.
Cross-referencing historical shipment patterns with expert panel input anchored the projection framework across material type, end-use application, coating technology, and regional regulatory cluster dimensions. CAGRs derived from segmented growth rate application to baseline volumes, with specific adjustment for EU Packaging and Packaging Waste Regulation implementation pacing and aluminum smelter energy cost trajectories.
Revisions become necessary when ECHA substance restriction timelines accelerate, deposit-return scheme adoption diverges across member states, or water-based barrier coating performance thresholds breach commercial viability. Forecasts reflect documented assumptions on regulatory enforcement intensity and brand sustainability commitment durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Europe Corrugated Box Market
Cartons
Beverage Cartoners Market
Cartons
Tetrahedron Carton Market
Cartons
Fully Enclosed Cartons Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
North America Corrugated Boxes Market
Cartons
Brick Carton Packaging Market
Cartons
Digital Printed Cartons Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Child-Resistant Carton Box Market
Cartons
Braille Cartons Packaging Market
Cartons
Africa Folding Carton Market
Cartons
Carton Sealer Machine Market
Cartons
Brick Liquid Carton Market
Cartons
Metallized PET Cartons Market
Cartons
Cupcake Box Market