
 Global Folding Carton Packaging Market | 2026-2036
Global Folding Carton Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Folding Carton Packaging Market Analysis
Plastic-to-paper substitution in food service and retail-ready packaging is recalibrating cost structures and volume forecasts across the industry. Smurfit Westrock leverages its integrated containerboard and converting footprint to capture margin at multiple production stages. International Paper Company anchors North American supply through extensive kraft linerboard and recycled fiber operations. Mayr-Melnhof Karton AG specializes in coated recycled board for premium consumer goods, competing on print surface quality and consistency.
Folding carton packaging consists of paperboard substrates—typically 200–400 gsm—scored, folded, and glued into rigid containers that protect, display, and facilitate distribution of consumer products. The material segment shows coated paperboard commanding premium positioning in cosmetics and pharmaceutical applications where print fidelity and barrier properties justify higher unit economics, while recycled paperboard expands fastest in grocery and foodservice as EPR frameworks tighten virgin fiber thresholds. Digital printing within print technology is displacing offset for short-run, SKU-proliferated orders in e-commerce and seasonal promotional packs.
REACH and the EU Green Deal shape material compliance and chemical safety across European supply chains, while FDA food contact regulations govern substrate and coating formulations in US markets. India's BIS packaging standards and EPR draft rules are forcing domestic converters toward certified recycled content and standardized labeling. Stakeholders must monitor how divergent extended producer responsibility timelines across the EU, US, and India reshape capital allocation for recycling infrastructure and board specification.
Market Dynamics
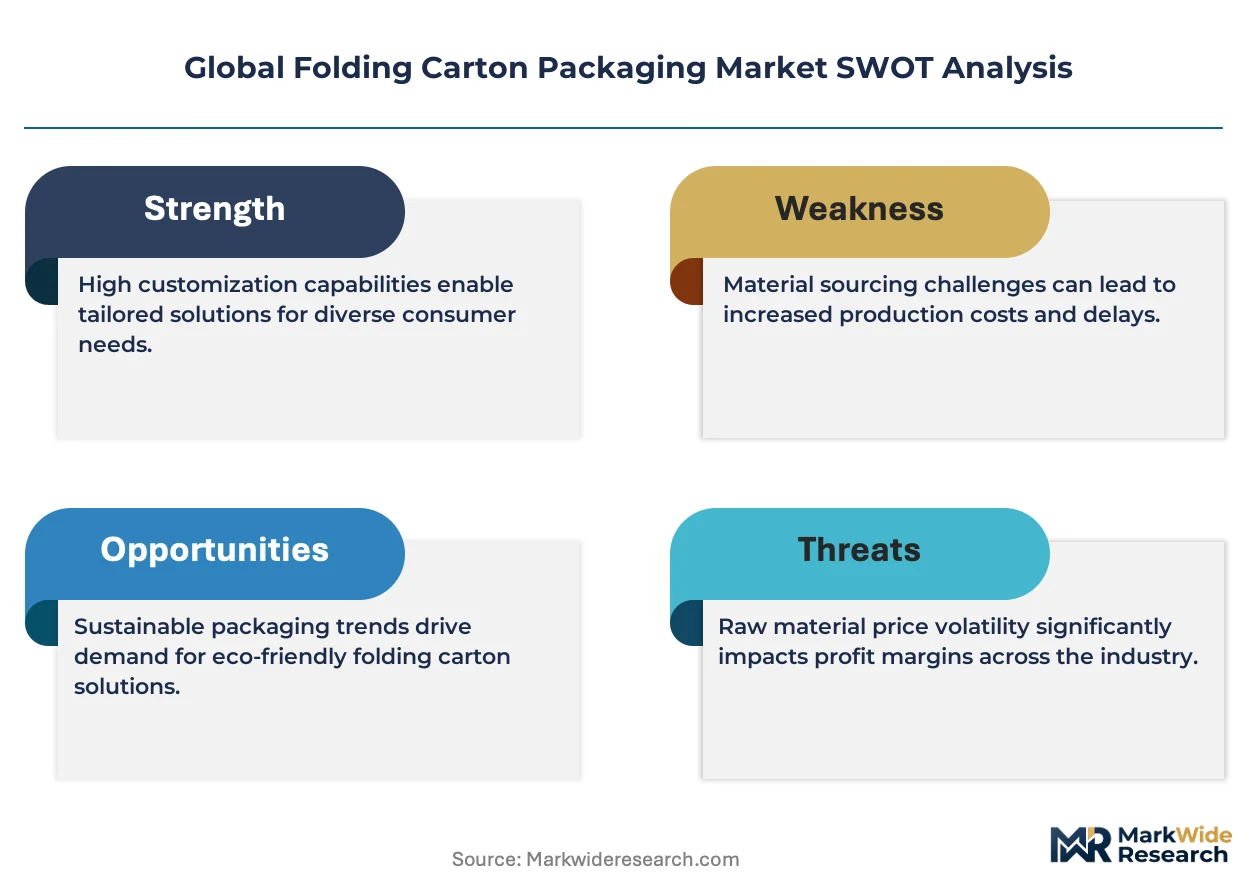
Plastic-to-paper substitution across food service and retail-ready formats is compressing legacy substrate economics while expanding addressable volume for fiber-based converters. This structural pivot forces simultaneous retooling of coating chemistry, barrier performance, and line speed compatibility.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recycled content mandates across member states pull virgin-dependent converters toward certified fiber sourcing and closed-loop collection partnerships.
- India FMCG production scaling:Domestic modern retail penetration and chilled dairy expansion generate sustained carton demand from local and multinational brand owners.
- Digital print adoption:Short-run SKU proliferation in e-commerce and seasonal promotional packs reduces minimum order thresholds and inventory carrying costs for brand managers.
Market Restraints
- Pulp price volatility:Kraft linerboard and recycled fiber input swings compress converter margins when pass-through clauses lag quarterly resets by contract buyers.
- Barrier coating technical limitation:Current water-based and bio-based formulations fail to match polyethylene lamination for extended shelf-life chilled meat and ready-meal applications.
- REACH compliance friction:ECHA substance restrictions on certain mineral oil saturated hydrocarbons force reformulation of recycled board grades used in food contact.
Strategic Opportunities
- India regulatory tailwind:BIS packaging standards and draft EPR rules position early certified-recycled entrants for preferential supplier status with domestic FMCG majors.
- Pharmaceutical serialization convergence:Integration of digital printing with track-and-trace authentication creates premium service tiers for contract packaging organizations serving EU and US markets.
- Direct-to-retail channel innovation:Shelf-ready and retail-optimized carton formats bypass traditional case-packing tiers, capturing margin from eliminated secondary packaging steps.
Industry Challenges
- Prepress-to-press skill compression:Convergence of digital file preparation with inline finishing collapses traditional operator specializations, requiring cross-functional training programs most mid-size converters lack.
- Recycling infrastructure capex intensity:EU Green Deal timelines demand fiber recovery and deinking investments that strain balance sheets before volume premiums materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Folding Carton Packaging Market |
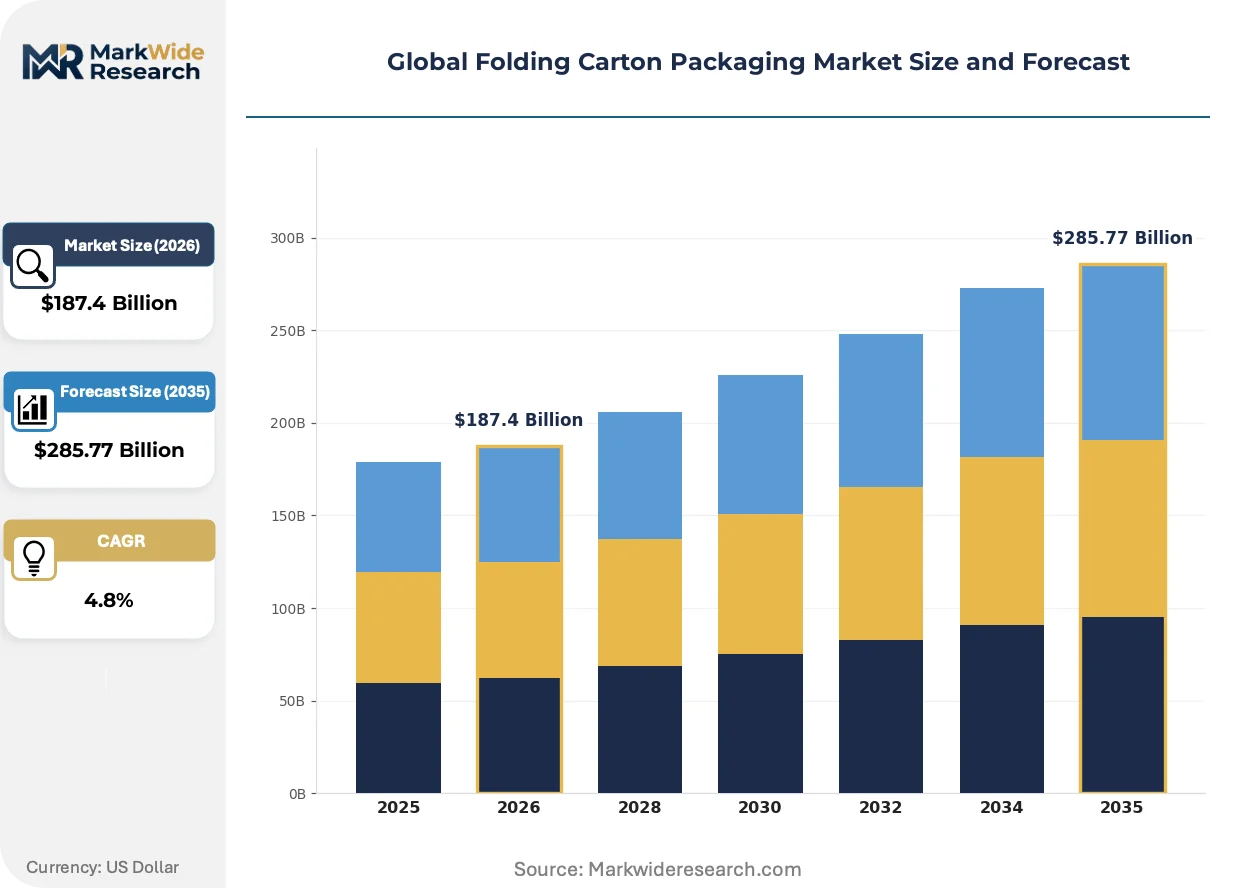
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cartons, Die-Cut Boxes, Multi-Depth Boxes, Sleeve Boxes Material: Recycled Paperboard, Coated Paperboard, Uncoated Paperboard, Specialty Paperboard End User: Food & Beverage, Personal Care, Pharmaceutical, Consumer Electronics Print Technology: Flexographic Printing, Digital Printing, Offset Printing, Gravure Printing |
| Companies Covered | International Paper Company, Huhtamaki, Smurfit Westrock, Amcor, DS Smith Plc, Graphic Packaging International, Stora Enso, Rengo Co., Ltd., Mayr-Melnhof Karton AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Folding Carton Packaging Market Emerging Trajectories
Active transformation in this market centers on manufacturing velocity, regulatory chemistry, and procurement compression. These forces operate simultaneously across substrate, print, and fulfillment layers.
Robotic case packing and palletizing systems are automating post-press handling in folding carton plants serving high-SKU pharmaceutical and cosmetics accounts. Contract manufacturers in Germany and the United States deploy these systems to compress changeover intervals below 15 minutes. This automation is enabling same-day turnaround on promotional runs previously scheduled across multi-day windows.
REACH substance restrictions and the EU Green Deal packaging rules are mandating elimination of per- and polyfluoroalkyl substances from grease-resistant coatings by 2026. Board mills must qualify alternative barrier chemistries without sacrificing heat-seal performance on high-speed forming lines. Premium chocolate and bakery brands in France and Belgium face the tightest compliance windows and are pre-qualifying suppliers 18 months ahead of enforcement.
Brand procurement teams are consolidating carton suppliers to capture scale pricing while demanding regional redundancy against single-source risk. This concentration compresses the viable vendor base for mid-size converters in North America and Western Europe. Pharmaceutical and personal care multinationals in Switzerland and the United Kingdom are driving this consolidation most aggressively, reducing qualified supplier lists by 40 percent across primary and secondary packaging categories.
Global Folding Carton Packaging Market Segmentation
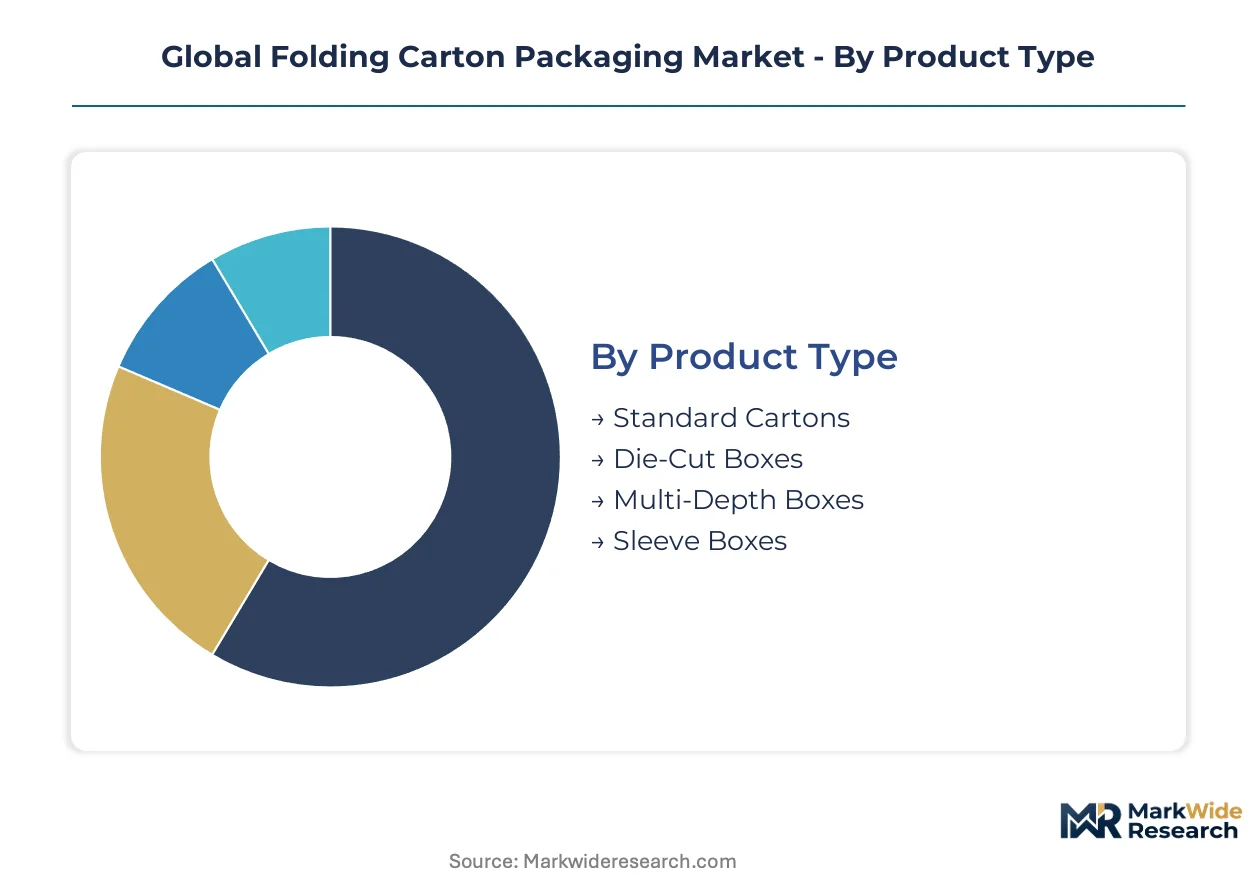
Folding carton segmentation reveals how substrate specification, forming geometry, and print fidelity align with distinct value chains. Each axis carries different margin profiles, capital intensity, and regulatory exposure that reshape converter strategy.
Product Type:
Structural geometry determines line speed compatibility, tooling amortization, and downstream handling efficiency across fulfillment networks.
- Standard Cartons:Rectangular prism designs with standard scores and tuck flaps dominate high-volume CPG applications. Pharmaceutical blister packs and dry grocery segments in Germany and the United States concentrate demand here, though margin compression from procurement consolidation forces converters toward 50-million-unit annual minimums.
- Die-Cut Boxes:Complex geometries with window apertures, hanging tabs, and curved edges require steel-rule die tooling and slower press speeds. Premium chocolate and cosmetics brands in Belgium and Switzerland absorb the 15-20% unit cost premium for shelf differentiation and unboxing experience.
- Multi-Depth Boxes:Adjustable height designs with scored depth tiers accommodate variable product counts without SKU proliferation. E-commerce fulfillment centers in India and the Netherlands deploy these for subscription box and seasonal gift sets.
- Sleeve Boxes:Open-ended wraps that slide over rigid trays or containers. Ready-meal and frozen dessert applications in France and Japan favor this format for microwave venting and visible product presentation.
Mature deployment sits with Standard Cartons. Newer deployment is concentrated in Die-Cut Boxes.
Material:
Substrate chemistry governs barrier performance, print receptivity, and compliance with evolving extended producer responsibility frameworks.
- Recycled Paperboard:Post-consumer fiber content ranging from 80-100% qualifies for EU Green Deal recycled content mandates. Grocery private-label converters in the United Kingdom and Italy are shifting volume here ahead of enforcement deadlines, though mineral oil saturated hydrocarbon limits under REACH complicate food contact certification.
- Coated Paperboard:Clay or polymer surface treatments deliver 175+ line screen print fidelity and moisture resistance. Cosmetic and pharmaceutical folding cartons in the United States and Switzerland command 30-40% price premiums over uncoated alternatives for brand asset protection.
- Uncoated Paperboard:Natural fiber appearance with direct food contact compliance for dry goods. Organic and clean-label brands in Germany and Australia specify this for sustainability signaling despite inferior scuff resistance.
- Specialty Paperboard:Metallized substrates, textured embossing stocks, and fragrance-release coatings. Ultra-premium spirits and limited-edition confectionery in Japan and the United Arab Emirates absorb substantial unit premiums for tactile differentiation.
Volume leadership belongs to Coated Paperboard. Regulatory tailwinds are accelerating Recycled Paperboard fastest.
End User:
Downstream sector requirements dictate barrier specifications, serialization mandates, and supply chain service levels.
- Food & Beverage:The largest addressable volume spanning ambient shelf-stable, chilled dairy, and frozen applications. India's domestic FMCG expansion and modern retail penetration are generating carton demand from local dairy cooperatives and multinational beverage bottlers.
- Personal Care:Skincare and haircare cartons require grease-resistant coatings and precise registration for metallic accents. Brands in France and South Korea are consolidating suppliers to capture scale pricing while demanding regional redundancy.
- Pharmaceutical:Child-resistant features, tamper-evident closures, and EU Falsified Medicines Directive serialization compliance. Contract packagers in Germany and Switzerland integrate digital printing with track-and-trace authentication.
- Consumer Electronics:Anti-static coatings and structural protection for high-value devices. Premium smartphone and accessory brands in the United States and China specify rigid board grades with foam inserts.
Established demand concentrates in Food & Beverage. Pharmaceutical serialization requirements are driving technology investment fastest.
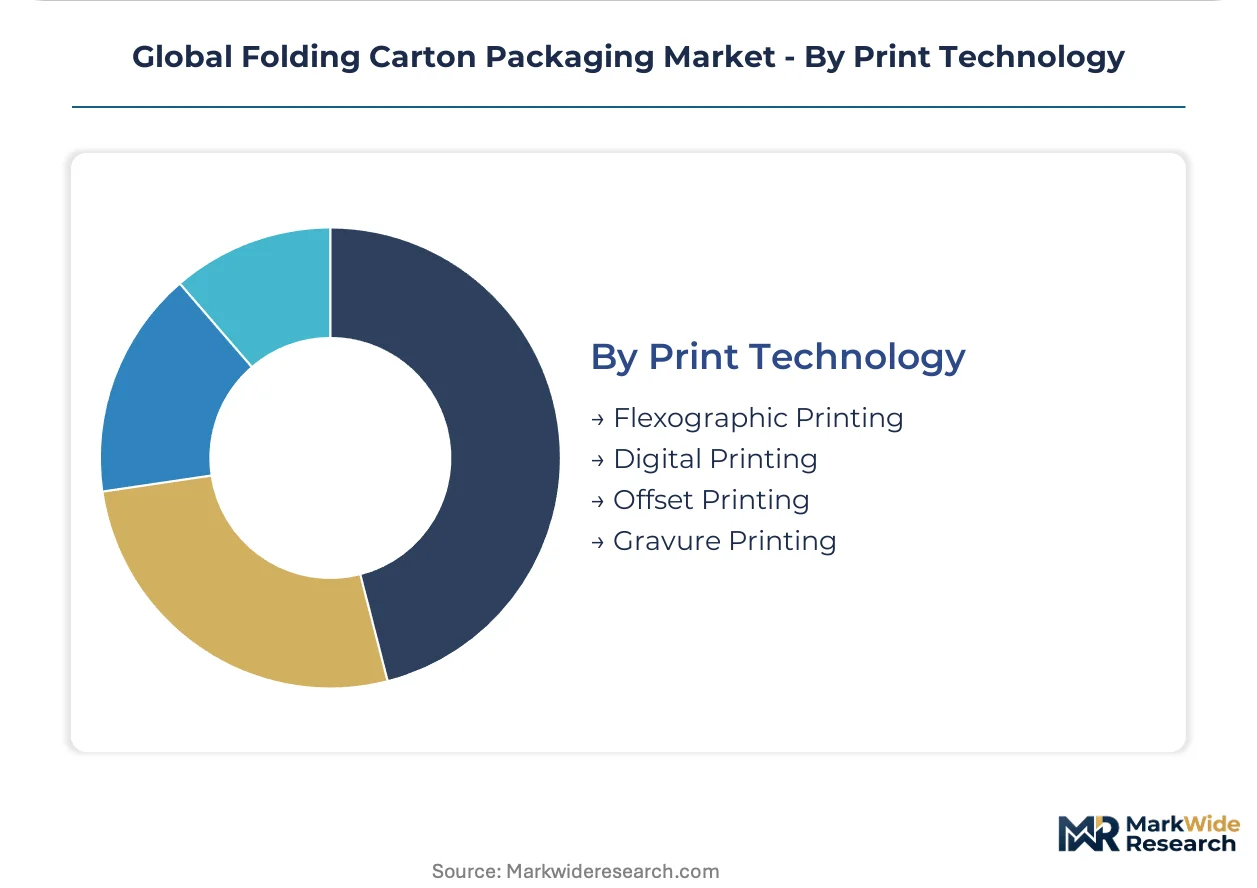
Print Technology:
Imaging method determines run-length economics, color consistency, and variable data capabilities.
- Flexographic Printing:Rotary relief plates with water-based or UV-curable inks deliver 300+ meters per minute on long-run grocery and beverage cartons. High-volume converters in Brazil and Poland maintain competitive positioning through anilox inventory depth.
- Digital Printing:Inkjet and electrophotographic systems eliminate plate costs and enable lot-size-one production. E-commerce promotional packs and pharmaceutical serialization in the United States and the Netherlands are climbing the fastest as run lengths fragment.
- Offset Printing:Lithographic transfer with 200+ line screen quality for premium cosmetic and pharmaceutical applications. Swiss and German converters defend this installed base through color management certification.
- Gravure Printing:Engraved cylinder imaging for ultra-long runs with consistent ink density. Cigarette and confectionery cartons in China and Indonesia retain this method for 50-million-unit annual campaigns.
Capital deployment favors Offset Printing. Digital Printing is gaining share fastest among technology transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand acceleration as domestic FMCG production scales and modern retail penetration deepens. Carton consumption from dairy cooperatives and multinational beverage bottlers is expanding fastest in this market. Regulatory tightening across the EU, US, and India is simultaneously reshaping fiber sourcing requirements and compliance costs.
United States
Food and beverage brands are expanding carton-based packaging for shelf-stable and chilled products across domestic supply chains. FDA food contact regulations govern substrate and coating formulations, forcing reformulation of barrier chemistries. Converters in the Midwest and Southeast maintain extensive kraft linerboard operations to anchor North American supply security.
Germany
Pharmaceutical serialization convergence and EU Falsified Medicines Directive compliance are driving technology investment in folding carton plants. REACH substance restrictions on mineral oil saturated hydrocarbons force reformulation of recycled board grades used in food contact. Industrial clusters around Düsseldorf and Hamburg deploy robotic case packing systems to compress changeover intervals below 15 minutes.
India
Domestic FMCG production scaling and chilled dairy expansion generate sustained carton demand from local cooperatives and multinational bottlers. BIS packaging standards and draft EPR rules are forcing domestic converters toward certified recycled content and standardized labeling. Manufacturing concentration in Maharashtra and Gujarat positions early certified-recycled entrants for preferential supplier status.
France
Premium chocolate and bakery brands face the tightest compliance windows for PFAS elimination from grease-resistant coatings by 2026. EU Packaging and Packaging Waste Regulation recycled content mandates pull converters toward certified fiber sourcing. Converters in the Île-de-France and Auvergne-Rhône-Alpes regions are pre-qualifying alternative barrier chemistries 18 months ahead of enforcement.
Japan
Sleeve box formats for ready-meal and frozen dessert applications favor microwave venting and visible product presentation in convenience retail. METI guidance on sustainable packaging aligns with corporate carbon reduction commitments. Industrial concentration in the Kanto region around Tokyo supports high-volume output for domestic and export confectionery brands.
Global Folding Carton Packaging Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated producers add converting lines to capture margin at multiple production stages. The vendor base stratifies across three tiers: multinational integrated paperboard-to-carton operators, regional specialists in coated recycled board, and mid-size contract converters serving pharmaceutical and cosmetics accounts. Two strategic archetypes predominate: fiber-integrated players controlling pulp through finished carton supply, and technology-differentiated specialists leveraging digital printing for short-run pharmaceutical serialization. Competitive intensity centers on M&A consolidation of regional converters and vertical integration into captive recycled fiber recovery.
Within the integrated multinational tier, Smurfit Westrock and International Paper Company exemplify scale-driven positioning across containerboard and converting operations. Mayr-Melnhof Karton AG occupies a specialist position in coated recycled board for premium consumer goods applications. These three entities represent divergent strategic bets on fiber integration depth versus premium surface quality specialization.
| Leading Market Players |
|---|
| International Paper Company |
| Huhtamaki |
| Smurfit Westrock |
| Amcor |
| DS Smith Plc |
| Graphic Packaging International |
| Stora Enso |
| Rengo Co., Ltd. |
| Mayr-Melnhof Karton AG |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between virgin fiber and recycled content tiers splits the folding carton market into parallel supply chains with divergent margin structures. EU Green Deal mandates and BIS standards in India force converters to source certified recycled fiber at premiums that do not fully pass through to contract buyers, while coated paperboard for pharmaceutical and cosmetic applications retains pricing power through print fidelity guarantees and barrier performance specifications.
Pricing Analysis
Volume-driven grocery and beverage segments trade at compressed margins where 50-million-unit annual minimums dominate procurement negotiations, while premium die-cut formats for chocolate and cosmetics in Belgium and Switzerland absorb 15-20% unit cost premiums for structural differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies around certification grade and volume scale, with EU recycled content mandates intensifying cost compression in the standard tier. Brand procurement consolidation in pharmaceutical and personal care segments has reduced qualified supplier lists by 40%, shifting leverage toward multinational buyers with regional redundancy demands. Price sensitivity concentrates in grocery private-label converters ahead of enforcement deadlines, while premium cosmetic brands exhibit lowest sensitivity due to brand asset protection requirements.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and India form hub-and-spoke patterns that position finished cartons within 48-hour delivery windows of major FMCG manufacturing clusters. Kraft linerboard production anchors in the United States and Brazil, while coated recycled board specialization concentrates in Austria and Germany, creating geographic interdependence for barrier-coated substrates. Raw material dependencies on bleached hardwood pulp, post-consumer fiber streams, and water-based barrier chemistries expose converters to ECHA substance restriction compliance costs and mineral oil saturated hydrocarbon reformulation timelines. Single-source vulnerability runs through integrated containerboard producers controlling pulp through finished carton supply. Distribution runs through contract packaging organizations and direct-to-brand fulfillment networks with serialized track-and-trace integration requirements in pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deinking and fiber recovery capacity bottlenecks across EU member states prop pricing for certified recycled content, constraining volume expansion until capital-intensive infrastructure investments mature. Supply constraints in compliant substrate grades create asymmetric pricing power for early-certified entrants.
For Market Incumbents: Lock in long-term offtake agreements with dairy cooperatives and beverage bottlers in Maharashtra and Gujarat ahead of BIS enforcement, while accelerating backward integration into captive fiber recovery to offset pulp price volatility. Smurfit Westrock and International Paper Company exemplify scale positioning through containerboard-to-carton control. Digital print serialization capabilities for pharmaceutical contract packaging defend margin against mid-size converter consolidation. For New Entrants and Emerging Players: Digital printing infrastructure for short-run SKU proliferation presents the most penetrable wedge, targeting e-commerce promotional packs and seasonal gift sets in the Netherlands and India where run-length fragmentation outpaces incumbent retooling speed. Multi-depth box formats for subscription fulfillment offer white-space expansion with lower barrier coating compliance burdens than chilled meat applications. Go-to-market positioning through direct-to-retail shelf-ready formats bypasses traditional case-packing tiers and captures eliminated secondary packaging value. For Investors and Strategic Acquirers: Exit pathways concentrate in fiber-integrated mid-cap specialists with certified recycled content pipelines and pharmaceutical serialization capabilities. Five-to-ten year viability favors converters with upstream pulp control and downstream digital print integration rather than commodity standard carton producers facing procurement consolidation. Watch for EU Packaging and Packaging Waste Regulation enforcement timelines as inflection indicators for recycled content premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Recovery | Captures margin from deinking operations while securing EU Green Deal compliance feedstock. |
| Digital Print Serialization Deployment | Enables track-and-trace authentication for EU Falsified Medicines Directive contract packaging. |
| Barrier Chemistry Reformulation | Qualifies PFAS-free coatings for French chocolate and bakery brands ahead of REACH deadlines. |
| Regional Distribution Center Expansion | Positions inventory within same-day turnaround windows for German pharmaceutical promotional runs. |
| Certified Recycled Content Pre-Qualification | Secures preferential supplier status with Indian FMCG majors under draft BIS EPR rules. |
Methodological Framework
Document review covered trade association filings, customs records, and regulatory submissions to ECHA and FDA, complemented by interviews with plant managers at integrated containerboard mills, procurement leads at multinational beverage bottlers, and technical R&D directors at barrier coating suppliers. Secondary validation drew from SEC 10-K disclosures, EU Packaging and Packaging Waste Regulation impact assessments, and Indian BIS standard drafts. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical capacity expansion patterns against converter panel input informed the projection framework. Segmentation dimensions spanned structural geometry, substrate chemistry, end-use sector requirements, and print technology adoption curves. CAGRs derived from elasticity-adjusted demand functions incorporating pulp price volatility and regulatory compliance cost trajectories. Industry-specific inputs included pharmaceutical serialization penetration rates and Indian modern retail square footage expansion.
Several conditions sit outside the modeled scope, including sudden tariff disruptions on kraft linerboard trade flows, breakthrough barrier coating technologies displacing polyethylene lamination, and accelerated EU enforcement timelines. Forecasts reflect documented assumptions around fiber recovery infrastructure buildout schedules and brand procurement consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Digital Printed Cartons Market
Cartons
Africa Folding Carton Market
Cartons
North America Corrugated Boxes Market
Cartons
Digital Folding Cartons Market
Cartons
Litho Laminated Cartons Market
Cartons
Shaped Liquid Cartons Market
Cartons
Global Hand Carton Sealers Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Carton Serialization Machine Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Microwaveable Carton Market
Cartons
Round Corrugated Box Market
Cartons
Carton Bottle Market
Cartons
Metallized Folding Cartons Market
Cartons
Folding Cartons Market