
 Packaging Design Services Market | 2026-2036
Packaging Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Design Services Market Analytics
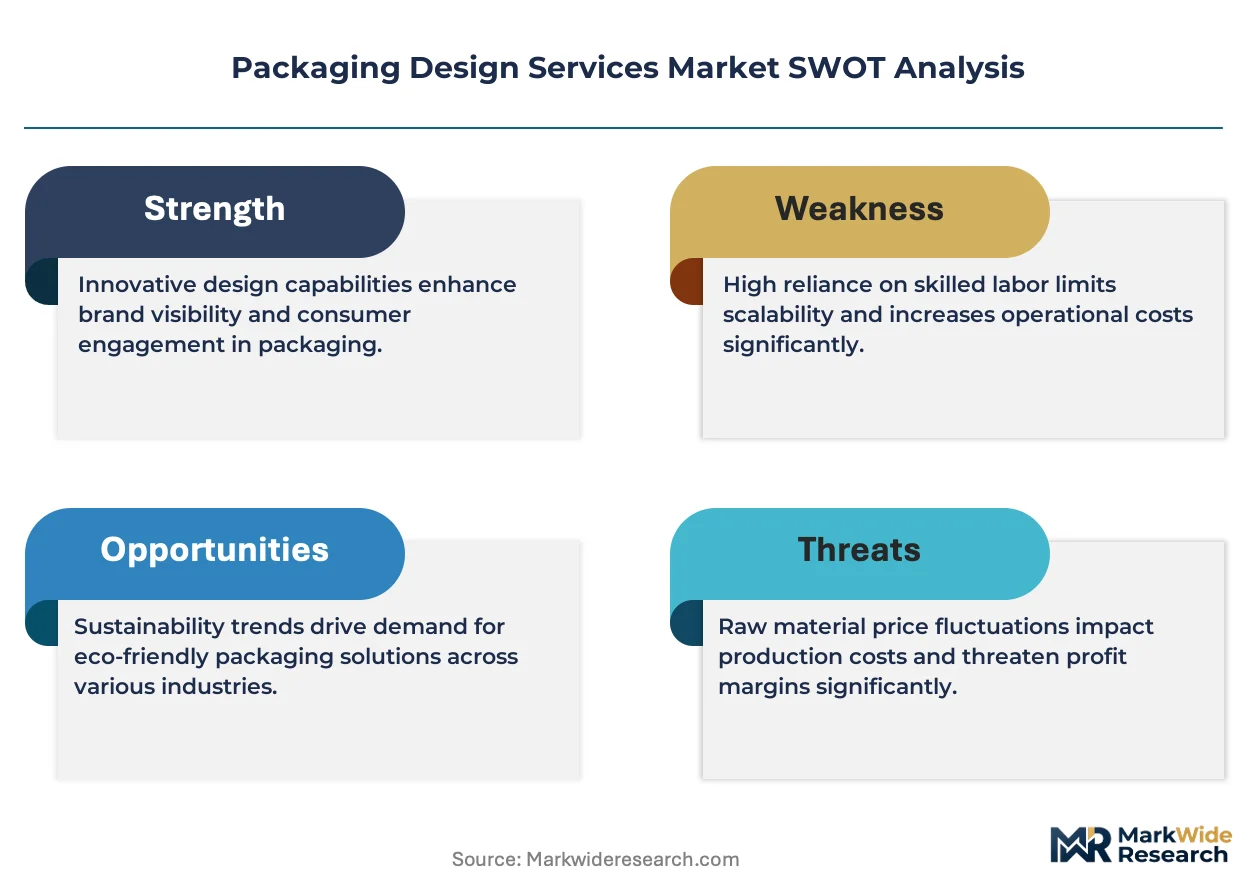
Mid-market consumer brands is rotating toward advanced structural and graphic design services as premium positioning replaces cost-driven procurement. Turner Duckworth anchors high-profile beverage and technology accounts with distinctive visual identity systems. Pearlfisher specializes in luxury and wellness packaging, leveraging deep material expertise across glass and paperboard substrates. Jones Knowles Ritchie competes through bold typographic and color-forward approaches that command shelf differentiation in crowded retail environments.
Packaging design services encompass the engineering, aesthetic development, and prototyping of protective and promotional containers, integrating structural specifications such as burst strength, barrier properties, and dimensional tolerance with brand communication objectives. The discipline serves industrial and commercial purposes by ensuring product integrity through distribution while converting consumer attention at the point of purchase. Structural design and graphic design command the largest service-type revenue pools, though prototyping is gaining share as brands accelerate go-to-market timelines and reduce physical sampling waste. Paperboard dominates material-type engagement due to recyclability alignment and printability, while plastic faces selective displacement as EPR regulations tighten across multiple jurisdictions.
The U.S. Federal Trade Commission's Green Guides and the EU Green Deal shape permissible environmental claims and material sourcing disclosures, directly influencing design brief specifications and supplier qualification criteria. REACH and FDA food-contact regulations further constrain substrate selection and ink chemistry for cosmetics and food end users. Stakeholders must monitor evolving EPR fee structures and recycled-content mandates to preempt compliance-driven redesign cycles and capture first-mover positioning in compliant material innovation.
Market Dynamics
EPR fee escalation and recycled-content mandates are compressing design iteration cycles as brands race to lock compliant material specifications ahead of regulatory deadlines.
Growth Catalysts
- EU Green Deal packaging requirements:The framework's 2030 recyclability targets are forcing reformulation of multilayer structures, expanding design service scope for compliance-driven redesigns.
- Beauty and personal care verticals:Premium skincare brands are commissioning refillable glass and aluminum formats that require specialized structural engineering and closure system innovation.
- Digital printing integration:Short-run personalization capabilities are collapsing minimum order thresholds, enabling microbrand access to professional packaging design previously reserved for volume players.
Market Restraints
- Pigment and ink chemistry constraints:REACH Annex XVII restrictions on heavy metals and phthalates are eliminating certain color ranges, constraining brand palette options.
- Recycled fiber supply concentration:European containerboard mills control high-purity post-consumer pulp availability, creating input cost volatility for paperboard-heavy design portfolios.
- Barrier coating technical limitations:Current bio-based alternatives to polyethylene laminates fail moisture and oxygen specifications for shelf-stable food applications.
Strategic Opportunities
- India's organized retail expansion:Modern trade growth in Tier-2 cities is creating first-mover positioning for design studios establishing local prototyping capabilities.
- Reusable packaging system design:Return-loop logistics integration represents uncaptured white space as CPG brands pilot refill infrastructure.
- US FDA food-contact notification pathways:Streamlined approval for post-consumer recycled content in food packaging is accelerating compliant material adoption.
Industry Challenges
- Structural engineer talent scarcity:Cross-disciplinary expertise combining CAD modeling with material science commands premium compensation, inflating project delivery costs.
- Physical prototyping capex intensity:High-fidelity color-accurate mockup production requires investment in UV-cured inkjet systems and die-cutting automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Design Services Market |
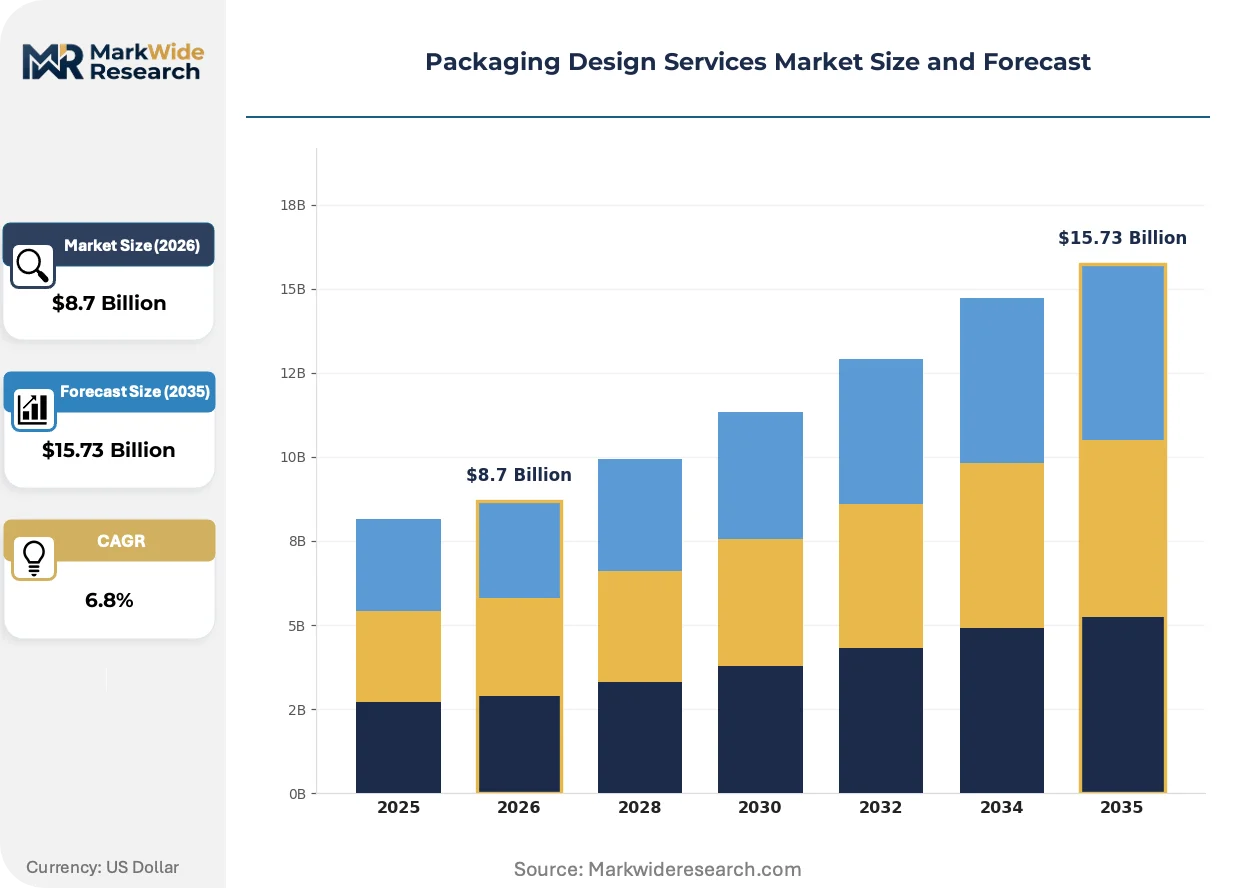
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Structural Design, Graphic Design, Prototyping, Consultation Material Type: Paperboard, Plastic, Glass, Metal End User: Food & Beverage, Cosmetics, Pharmaceuticals, Electronics Design Complexity: Basic, Intermediate, Advanced, Custom |
| Companies Covered | Chase Design Group, Turner Duckworth, SmashBrand, Robot Food, Jones Knowles Ritchie, Pearlfisher, Bulletproof, BrandOpus, Landor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Design Services Market Evolving Landscape
Generative design algorithms and substrate digitization are compressing the traditional concept-to-tooling timeline from months to weeks, redefining competitive advantage around velocity rather than scale.
AI-powered structural optimization software is decomposing conventional box-design heuristics by simulating load distribution across thousands of geometric permutations. Electronics and appliance brands are adopting these tools for protective packaging, cutting material usage by double-digit percentages without compromising drop-test performance. The technology is decomposing the legacy advantage of incumbent studios with decades of accumulated empirical knowledge.
REACH authorization requirements for SVHCs in packaging adhesives and coatings are tightening substance disclosure obligations across EU supply chains. Cosmetic and food-contact applications face the steepest compliance burdens, with brands now requiring full material passports from design partners. German and French regulators are enforcing these provisions most aggressively, driving consolidation toward design firms with in-house toxicology assessment capabilities.
Brand procurement functions are consolidating design spend under fewer retained relationships, replacing project-by-project bidding with annual agency-of-record structures. Mid-market CPG companies are centralizing packaging decisions at headquarters, eliminating regional design autonomy that previously supported local studio ecosystems. This concentration is most visible in North American beverage and snack categories, where procurement teams now mandate global design consistency across market tiers.
Packaging Design Services Market Segmentation
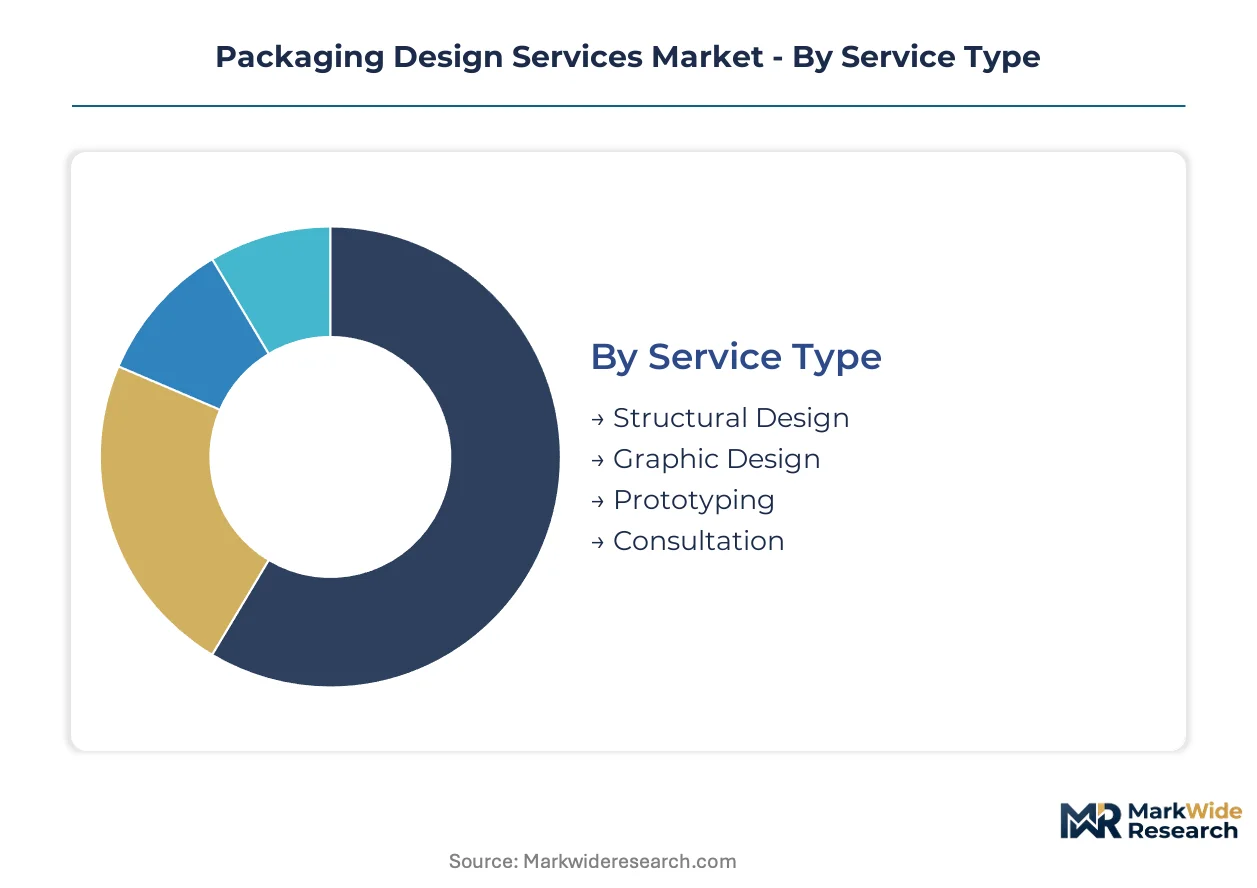
Packaging design services fragment across four dimensions that determine project economics and capability requirements. Service type dictates talent composition, material type governs regulatory exposure, end user sets performance specifications, and design complexity controls margin structure.
Service Type:
Structural design and graphic design flow through retained agency relationships, while prototyping and consultation increasingly route through digital platforms and specialized boutiques.
- Structural Design:Engineering of dimensional tolerances, load distribution, and barrier specifications for protective performance. Food and beverage brands in Germany and the United States commission complex folding carton geometries to meet EU Green Deal recyclability targets while maintaining shelf presence.
- Graphic Design:Visual identity systems integrating typography, color palettes, and surface graphics for brand communication. Premium cosmetics brands concentrate demand here, driven by unboxing experience requirements and social media shareability.
- Prototyping:Physical mockup production using UV-cured inkjet and die-cutting automation.
- Consultation:Regulatory navigation and material passport development for REACH and FDA compliance.
By volume, graphic design leads. By growth pace, prototyping is climbing the fastest.
Material Type:
Cost tiers separate premium substrate portfolios from commodity engagements, with paperboard commanding premium positioning due to compliance complexity.
- Paperboard:Recyclable fiber-based substrates with high printability and structural versatility. European containerboard mill concentration creates input cost volatility, yet beauty and personal care brands absorb premiums for FSC-certified grades.
- Plastic:Thermoformed and injection-molded formats facing selective displacement. EPR fee escalation across multiple jurisdictions compresses design iteration cycles as brands race for compliant alternatives.
- Glass:Refillable and premium formats requiring specialized closure engineering.
- Metal:Aluminum and tinplate for barrier-critical applications.
By revenue concentration, paperboard dominates. By regulatory pressure exposure, plastic faces the steepest headwinds.
End User:
Application requirements diverge sharply across verticals, with food-contact regulations imposing the strictest material qualification protocols.
- Food & Beverage:Packaging requiring FDA food-contact notification and barrier performance for shelf stability. US brands pilot post-consumer recycled content adoption through streamlined approval pathways, though bio-based barrier coatings still fail moisture and oxygen specifications for extended shelf life.
- Cosmetics:Luxury formats emphasizing tactile experience and sustainability credentials. French and German regulators enforce REACH SVHC disclosure most aggressively, driving demand for design partners with in-house toxicology assessment.
- Pharmaceuticals:Child-resistant and compliance-focused formats with serialization requirements.
- Electronics:Protective packaging optimized for drop-test performance and material minimization.
By project volume, food and beverage leads. By fee intensity, cosmetics generates the highest per-project margins.
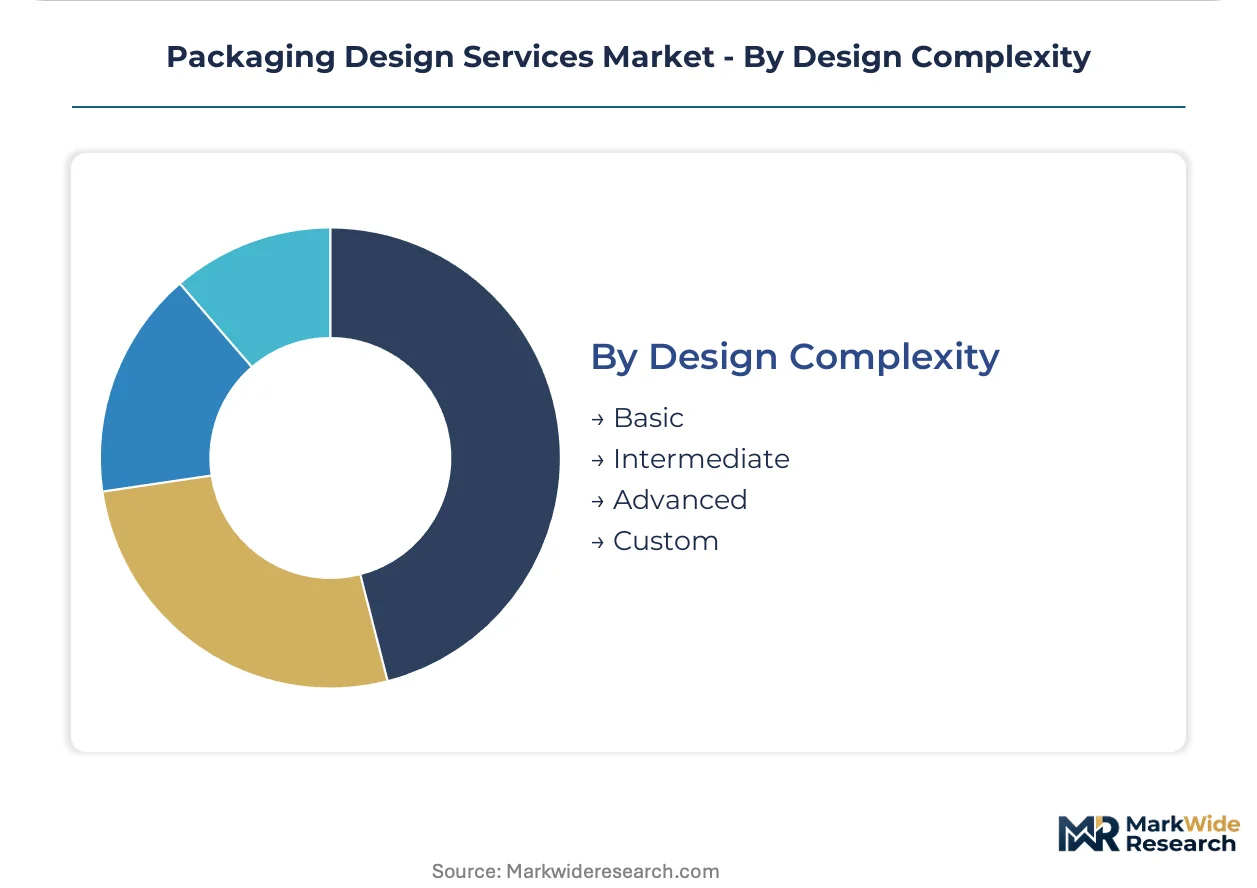
Design Complexity:
Customer type stratification separates enterprise retained relationships from mid-market project engagements, with complexity tier determining studio qualification requirements.
- Advanced:Generative algorithms and AI-powered structural optimization for geometric permutation testing. Electronics brands adopt these tools for protective packaging, cutting material usage without compromising performance while collapsing concept-to-tooling timelines.
- Custom:Bespoke formats integrating return-loop logistics for reusable systems. CPG pilot programs in North America create uncaptured white space as refill infrastructure scales.
- Intermediate:Standardized templates with moderate customization for regional adaptation.
- Basic:Template-driven execution for cost-constrained microbrands accessing digital printing short runs.
By adoption velocity, advanced complexity is gaining share fastest. By absolute project count, intermediate remains the workhorse tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market consumer brands concentrate procurement decisions in Germany, the United States, and China, with design execution localizing to these hubs as EPR frameworks tighten material compliance requirements.
Germany
Beauty and personal care brands commission refillable glass formats requiring specialized closure engineering. The EU Green Deal's 2030 recyclability targets force reformulation of multilayer structures, expanding service scope for compliance-driven redesigns. Hamburg and Berlin host dense clusters of design studios with in-house toxicology assessment capabilities serving REACH authorization requirements.
United States
Beverage and snack categories mandate global design consistency across market tiers, eliminating regional design autonomy. The FTC Green Guides shape permissible environmental claims and material sourcing disclosures, directly influencing design brief specifications. New York and San Francisco anchor high-profile technology and beverage accounts with distinctive visual identity systems.
China
Electronics brands adopt AI-powered structural optimization tools for protective packaging, cutting material usage without compromising drop-test performance. SAMR and evolving GB standards constrain substrate selection for food-contact applications. Shenzhen and Shanghai concentrate digital printing integration capabilities enabling short-run personalization for microbrand access.
France
Luxury cosmetics brands emphasize tactile experience and sustainability credentials, generating the highest per-project margins. ANSM enforces REACH SVHC disclosure most aggressively alongside German regulators, driving demand for material passport development. Paris hosts specialists in luxury and wellness packaging leveraging deep material expertise across glass and paperboard substrates.
India
Modern trade growth in Tier-2 cities creates first-mover positioning for design studios establishing local prototyping capabilities. BIS standards and FSSAI regulations govern food-contact material qualification as organized retail expands. Mumbai and Bangalore concentrate emerging design execution capabilities serving domestic CPG brand localization needs.
Packaging Design Services Market Competitive Landscape
Player mix skews toward boutique studios with deep substrate expertise rather than diversified advertising conglomerates. The vendor base concentrates in London, New York, and San Francisco, with tiered differentiation separating retained agency relationships from project-based engagements. Two strategic archetypes dominate: specialists in luxury verticals commanding premium fees, and scale-oriented studios serving mid-market CPG through templated execution. Competitive moves center on M&A to acquire toxicology assessment capabilities and strategic partnerships with European containerboard mills to secure fiber supply.
Within the premium-tier specialist archetype, Turner Duckworth and Pearlfisher occupy anchor positions representing distinctive visual identity capabilities and luxury substrate expertise respectively. Jones Knowles Ritchie exemplifies the bold typographic differentiation vector competing for shelf presence in crowded retail environments. These three London-based and San Francisco-rooted studios sit within the retained-agency tier where procurement consolidation is concentrating design spend under fewer relationships.
| Leading Market Players |
|---|
| Chase Design Group |
| Turner Duckworth |
| SmashBrand |
| Robot Food |
| Jones Knowles Ritchie |
| Pearlfisher |
| Bulletproof |
| BrandOpus |
| Landor |
| Others |
Value Network & Pricing Analysis
Containerboard mill utilization rates in Germany and the United States anchor cost structures for paperboard-heavy design portfolios, compressing margin buffers as European fiber supply concentrates among a handful of integrated producers. Scale advantages at these mills translate directly into input cost volatility for design studios, forcing project-based pricing models to absorb or pass through pulp index movements.
Pricing Analysis
Cost-plus contracts with European containerboard mills index to NBSK pulp benchmarks, transmitting fiber cost swings directly into design studio operating margins. Three-tier pricing structure across premium, standard, and economy levels separates retained agency relationships from project-based engagements and digital platform access. Pricing pressure stems from recycled fiber supply concentration as mills consolidate post-consumer pulp availability. Mid-market CPG brands exhibit highest price sensitivity, while luxury cosmetics brands absorb premiums for FSC-certified grades and toxicology assessment capabilities.
Supply Chain Analysis
Just-in-time fiber sourcing dominates European containerboard procurement, though design studios are building strategic stockpiles of FSC-certified paperboard grades to hedge against mill allocation constraints. Supply concentrates in Germany, the United States, and China as brands localize design execution alongside EPR compliance requirements. Raw material dependencies center on high-purity post-consumer pulp, UV-cured ink chemistries, and bio-based barrier coatings. Single-source vulnerability runs through European containerboard mill concentration. Distribution runs through retained agency relationships for structural and graphic design, with prototyping increasingly routing through digital platforms and specialized boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service types, material expertise, and geographic execution creates niche positioning opportunities as procurement consolidation simultaneously concentrates spend under fewer relationships. Digital printing integration and AI-powered structural optimization are spawning specialist boutiques that bypass traditional agency retainers.
For Market Incumbents: Fortify toxicology assessment capabilities through in-house hiring or targeted acquisition as REACH SVHC disclosure obligations intensify across EU supply chains. Secure backward integration into European containerboard mill relationships to lock fiber supply and dampen input cost volatility. The priority lever sits with material passport development services that command premium fees from cosmetics and food-contact brands facing steepest compliance burdens.
For New Entrants and Emerging Players: FDA food-contact notification fast-track expertise represents a penetrable white space as US brands pilot post-consumer recycled content adoption through streamlined approval pathways. Target India's Tier-2 city modern trade expansion by establishing local prototyping capabilities ahead of organized retail growth. Go-to-market angle centers on digital platform models collapsing minimum order thresholds for microbrand access to professional packaging design.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors design studios with generative algorithm capabilities and AI-powered structural optimization tools that compress concept-to-tooling timelines. Long-term viability hinges on regulatory compliance depth rather than creative scale, with 5-10 year windows favoring specialists over generalists. Acquisition target archetype: boutique studios with in-house toxicology assessment and deep substrate expertise across glass and paperboard. Signal to watch: EPR fee escalation velocity crossing thresholds that trigger mandatory redesign cycles across brand portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Toxicology Capability Acquisition | REACH SVHC enforcement by German and French regulators mandates in-house substance assessment. |
| European Fiber Supply Partnership | Containerboard mill concentration creates allocation risk for paperboard-heavy design portfolios. |
| Generative Design Platform Launch | AI-powered structural optimization decomposes legacy advantage of incumbent studios with empirical knowledge. |
| India Prototyping Footprint Expansion | Tier-2 city modern trade growth creates first-mover positioning for localized execution capabilities. |
| Reusable Packaging System Design | Return-loop logistics integration represents uncaptured white space as CPG brands pilot refill infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from packaging design studio principals, brand procurement directors, containerboard mill sales executives, and regulatory affairs specialists at cosmetics and food companies, then refined through secondary validation. Primary fieldwork combined structured interviews with stakeholder decision-makers and project-level data collection. Secondary sources encompassed EU ECHA substance databases, FDA food-contact notification filings, FSC chain-of-custody certification records, and trade customs data for paperboard substrate flows. Bottom-up project pipeline analysis triangulated against top-down market sizing from service-type revenue pools.
Variance decomposition across service type, material type, end user, and design complexity dimensions structured the analytical framework over the projection horizon. Segmentation modeling captured structural design, graphic design, prototyping, and consultation revenue flows alongside paperboard, plastic, glass, and metal substrate exposures. CAGRs derived from regression against macroeconomic indicators and regulatory timeline assumptions. Industry-specific forecast inputs included EPR fee escalation schedules and recycled-content mandate phase-ins across EU member states.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation or abrupt pulp supply disruptions would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement velocity and brand compliance spending elasticity. Revision becomes warranted when EPR fee structures or REACH authorization timelines cross thresholds that accelerate redesign cycle frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Returnable Transport Packaging (RTP) Market
Packaging
Canada Foodservice Packaging Market
Packaging
Slide Tray Box Market
Packaging
Plastic Lab Totes Market
Packaging
Fresh Food Packaging Market
Packaging
Flowpack Paper Packaging Market
Packaging
United States Retort Pouches Market
Packaging
High Performance Barrier Films Market
Packaging
Freezer Paper Market
Packaging
Global Anti-Static Films Market
Packaging
Glass Frosting for Packaging Market
Packaging
Pack Testing Machines Market
Packaging
Water Bottle Racks Market
Packaging
Cement Packaging Market
Packaging
Printed Plastic Films Market
Packaging
Food and Beverages Metal Can Market