
 Global Aseptic Paper Packaging for Flat Top Carton Market | 2026-2036
Global Aseptic Paper Packaging for Flat Top Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aseptic Paper Packaging for Flat Top Carton Market Intelligence
The direct-to-consumer shift via e-commerce platforms is reshaping distribution strategies for beverage and dairy manufacturers. This creates new opportunities for packaging formats that ensure product integrity through complex logistics chains. Tetra Pak International S.A. leverages its dominant position in integrated processing and packaging solutions. In contrast, Greatview Aseptic Packaging Co., Ltd. competes by offering cost-effective alternatives and flexible supply agreements to regional brands.
Aseptic paper packaging for flat top cartons is a multi-layer composite, typically combining paperboard, polyethylene, and an aluminum or polymer barrier. Its design allows for the separate sterilization of the package and its contents, enabling shelf-stable storage of liquid foods without refrigeration. Aluminum foil laminated paperboard continues to lead in performance, especially for sensitive products. Dairy products and juices represent the core application segments, with demand for long-life formats being a primary driver.
Food safety standards from bodies like the US FDA and China's NMPA govern material composition and market access. Concurrently, environmental regulations, including the EU's directives on packaging waste, are pushing for designs that enhance recyclability. Manufacturers must therefore balance high-barrier performance with the imperative to develop more circular and sustainable packaging solutions.
Market Dynamics
The central dynamic shaping the market is the structural tension between sustainability mandates and the technical necessity for high-performance barrier materials. Regulatory frameworks like the EU Green Deal are compelling a shift toward circularity, while food safety and shelf-life requirements continue to depend on complex, multi-layer composites.
Growth Catalysts
- UHT Product Expansion:The proliferation of UHT milk, creams, and plant-based dairy alternatives, particularly in Asia-Pacific, requires long-shelf-life packaging formats that do not need a cold chain, directly stimulating carton demand.
- Food Safety Imperatives:In markets like China, heightened consumer and regulatory focus on food safety and traceability, governed by bodies like the NMPA, favors the sealed, sterile environment provided by aseptic packaging.
- Sustainable Material Innovation:European Union policies promoting a circular economy are accelerating investment in renewable and recyclable barrier technologies, such as polymer-based films, as alternatives to aluminum foil.
Market Restraints
- Raw Material Price Volatility:The market is exposed to fluctuating prices of essential inputs, including paperboard pulp, polyethylene resins, and aluminum, which can compress manufacturer margins and create pricing instability. li>Recycling Infrastructure Deficiencies: The multi-layer composite nature of the cartons makes them difficult to process in standard paper recycling streams, and the lack of widespread, specialized collection and sorting systems remains a structural barrier.
- Threat from Alternative Formats:For certain product categories like single-serve juices and nectars, aseptic cartons face substitution pressure from formats like flexible aseptic pouches and multi-layer PET bottles, which offer different form factors.
Strategic Opportunities
- Aluminum-Free Barrier Layers:Developing and commercializing high-performance, non-aluminum barrier solutions presents a significant opportunity to improve the recyclability profile of cartons and meet sustainability goals set by brand owners.
- Expansion into New Food Categories:There is untapped potential in liquid food segments beyond dairy and juice, including ready-to-drink soups, broths, culinary sauces, and even wine, which could benefit from shelf-stable carton formats.
- Geographic Penetration in Latin America:Markets such as Brazil and Mexico show strong potential for growth, driven by an expanding middle class, urbanization, and a rising preference for conveniently packaged, long-life liquid food products.
Industry Challenges
- High Capital Investment:The acquisition and installation of aseptic filling and packaging lines represent a substantial capital expenditure, posing a significant hurdle for small and medium-sized enterprises seeking to enter the market.
- Complex Recycling Logistics:Establishing and managing effective take-back and recycling programs for post-consumer cartons requires complex coordination between manufacturers, municipalities, waste management companies, and recyclers.
- Harmonizing Global Standards:Manufacturers face the challenge of navigating a fragmented landscape of food safety and packaging waste regulations, such as those from the US FDA and the EU, which can complicate product design and market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aseptic Paper Packaging for Flat Top Carton Market |
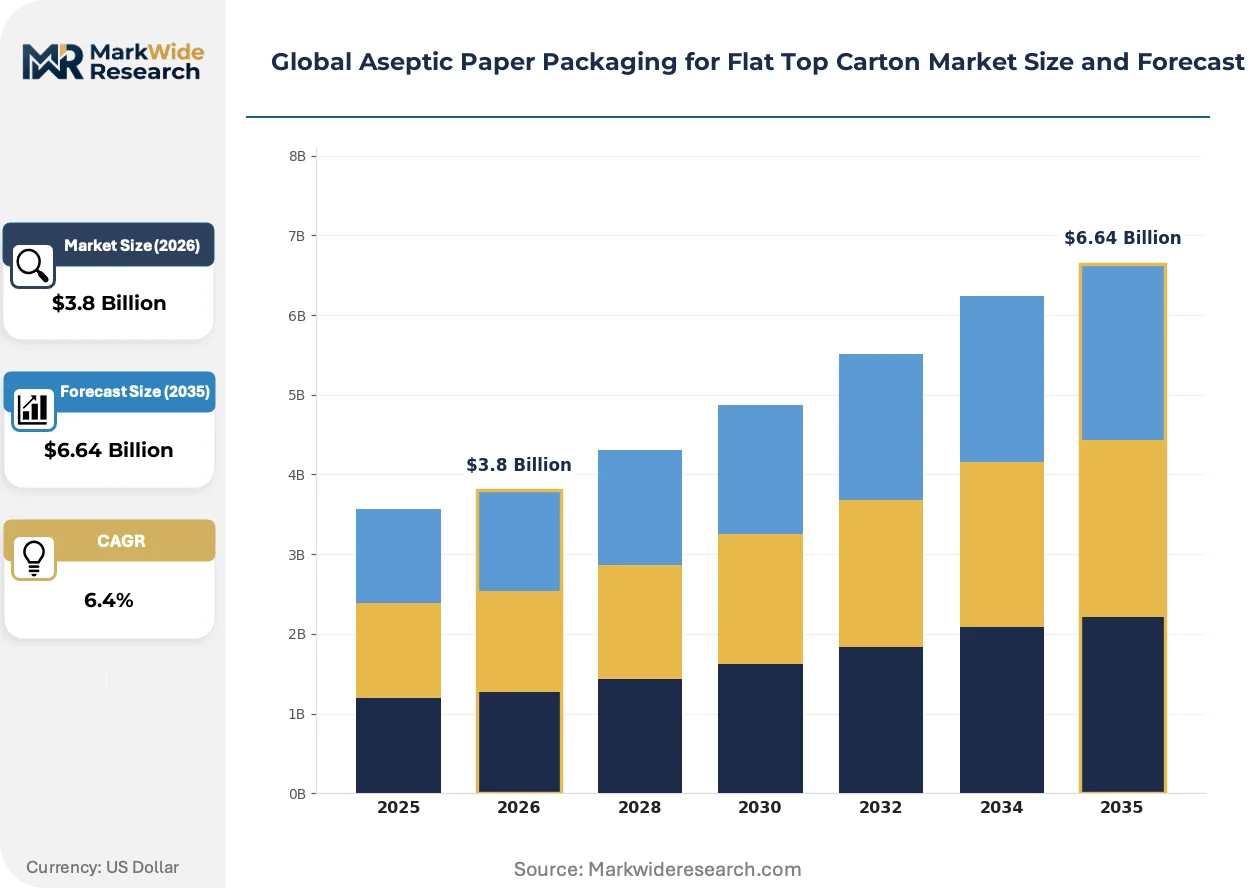
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Laminated Paperboard, Aluminum Foil Laminated Paperboard, Barrier Treated Paperboard, Coated Paperboard Application: Dairy Products, Juice & Beverages, Liquid Food, Pharmaceuticals End User: Food & Beverage Manufacturers, Beverage Processing Units, Pharmaceutical Companies, Catering Services Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Retail Chains |
| Companies Covered | Stora Enso, Amcor Limited, Tetra Pak International S.A., Nippon Paper Industries Co., Ltd., Greatview Aseptic Packaging Co., Ltd., SIG Combibloc Obeikan (Pty) Ltd., Mondi Ltd., TidePak Aseptic Packaging Material Co. Ltd., Elopak SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aseptic Paper Packaging for Flat Top Carton Market Strategic Shifts & Innovations
Material science advancements are running parallel to supply chain digitalization. These forces are pushing manufacturers to develop packaging that is not only more sustainable and compliant with evolving regulations but also more intelligent and capable of navigating complex, direct-to-consumer logistics channels.
Intelligent packaging features, such as printed QR codes and embedded Near Field Communication (NFC) tags, are being integrated into flat top cartons. Dairy and premium juice brands are adopting this technology to offer consumers detailed information on product provenance, ingredients, and recycling. This capability is digitizing the connection between the physical product and a brand's online platform, enabling direct consumer engagement and data collection.
Regulatory frameworks focused on circularity, notably the EU's Packaging and Packaging Waste Regulation (PPWR), are directly influencing package design. This legislation sets stringent targets for recyclability and the use of recycled content, compelling a move away from traditional multi-material constructions. European beverage companies are consequently leading the investment into mono-material structures and coatings that are easier to separate and recycle, ensuring continued market compliance.
A notable behavioral shift is the rise of direct-to-consumer (D2C) sales models facilitated by e-commerce. This trend allows liquid food producers to bypass traditional retail channels, creating a direct relationship with the end customer. This shift is most visible in the North American and Chinese markets for specialty products like cold-brew coffee and plant-based milks, demanding packaging robust enough for the rigors of the individual parcel delivery network.
Global Aseptic Paper Packaging for Flat Top Carton Market Segmentation
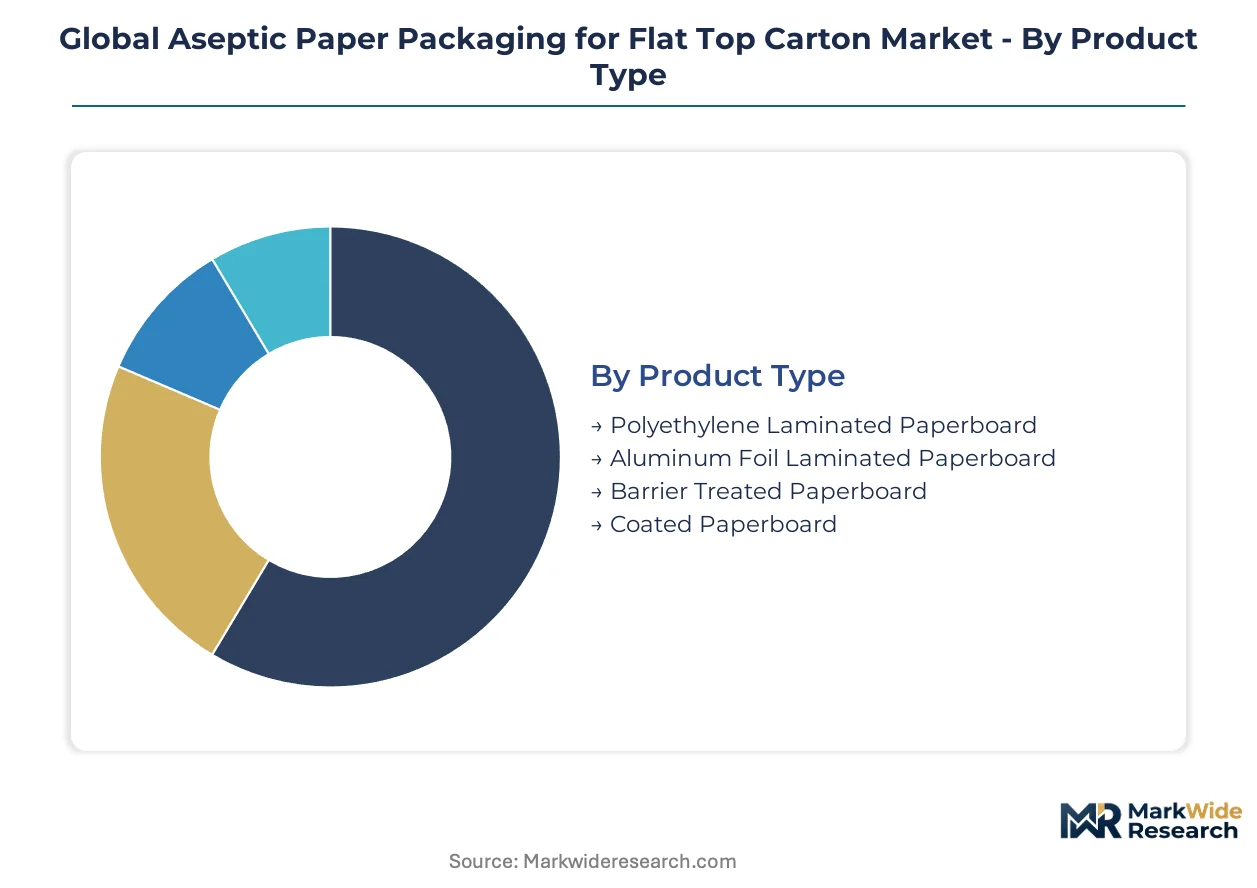
The aseptic paper packaging market for flat top cartons is characterized by distinct segments reflecting diverse material compositions, application requirements, end-user profiles, and distribution strategies. Understanding these differentiations is crucial for manufacturers to align product development with evolving consumer needs and regulatory mandates.
Product Type:
The product type spectrum for aseptic flat top cartons addresses varying barrier requirements and cost sensitivities across diverse liquid food applications.
- Aluminum Foil Laminated Paperboard:This multi-layer composite integrates aluminum foil to provide an exceptional oxygen and light barrier, crucial for sensitive products. Demand concentrates in UHT milk and premium juices, particularly in markets like China, driven by extended shelf-life requirements without refrigeration.
- Polyethylene Laminated Paperboard:This basic construction utilizes polyethylene layers to provide moisture resistance and sealability, often used for products requiring less stringent barrier properties. Its demand is significant in cost-conscious segments and for liquids with shorter shelf stability, offering a balance of protection and economy.
- Barrier Treated Paperboard:This segment includes paperboard treated with advanced polymer-based films or coatings to enhance barrier properties, often as an aluminum-free alternative. These solutions target sustainability goals, aligning with EU Green Deal directives for improved recyclability.
- Coated Paperboard:Standard paperboard with a protective coating, primarily offering liquid resistance for products with shorter shelf lives or those stored under refrigeration. This type supports basic packaging needs for various dairy and beverage items.
Established volume favors Aluminum Foil Laminated Paperboard; emerging adoption favors Barrier Treated Paperboard.
Application:
Segmentation by application highlights the diverse categories benefiting from shelf-stable packaging solutions.
- Dairy Products:This category encompasses UHT milk, flavored milk, creams, and plant-based dairy alternatives, which require sterile, long-life packaging. Demand is particularly strong in Asia-Pacific, driven by convenience and food safety imperatives from regulators like China's NMPA.
- Juice & Beverages:This segment includes fruit juices, nectars, iced tea, and ready-to-drink coffee, all benefiting from extended shelf life and protection against spoilage. The growth of D2C e-commerce platforms in North America necessitates robust packaging for complex logistics.
- Liquid Food:This segment extends beyond traditional beverages to include products such as soups, broths, culinary sauces, and purees. These applications leverage aseptic packaging for convenience and reduced need for refrigeration in retail and food service.
- Pharmaceuticals:This niche application involves sterile packaging for liquid medications, nutritional supplements, and medical food products. Aseptic cartons ensure product integrity and safety for sensitive pharmaceutical formulations.
Dairy Products continue to dominate volume, while Liquid Food applications are expanding most quickly.
End User:
Customer type differentiation reveals the primary commercial entities driving packaging demand.
- Food & Beverage Manufacturers:These are large-scale producers of dairy, juice, and other liquid food products, requiring high-volume, efficient aseptic packaging solutions. They prioritize cost-effectiveness, supply chain reliability, and packaging innovation to meet diverse market needs.
- Beverage Processing Units:Specialized facilities focused on processing and packaging various liquid beverages, including UHT milk and non-carbonated drinks. These units integrate aseptic filling lines to ensure product sterility and extend shelf life.
- Pharmaceutical Companies:Manufacturers of liquid medicines and health supplements that demand sterile, tamper-evident, and compliant packaging solutions. Their requirements are stringent, adhering to regulations from bodies like the US FDA.
- Catering Services:Businesses providing food and beverage services to institutions, events, or transport, utilizing aseptic cartons for bulk storage, portion control, and convenient serving of liquids. This segment values efficiency and hygiene.
Food & Beverage Manufacturers represent the largest consumer segment, with Pharmaceutical Companies demonstrating the steepest expansion trajectory.
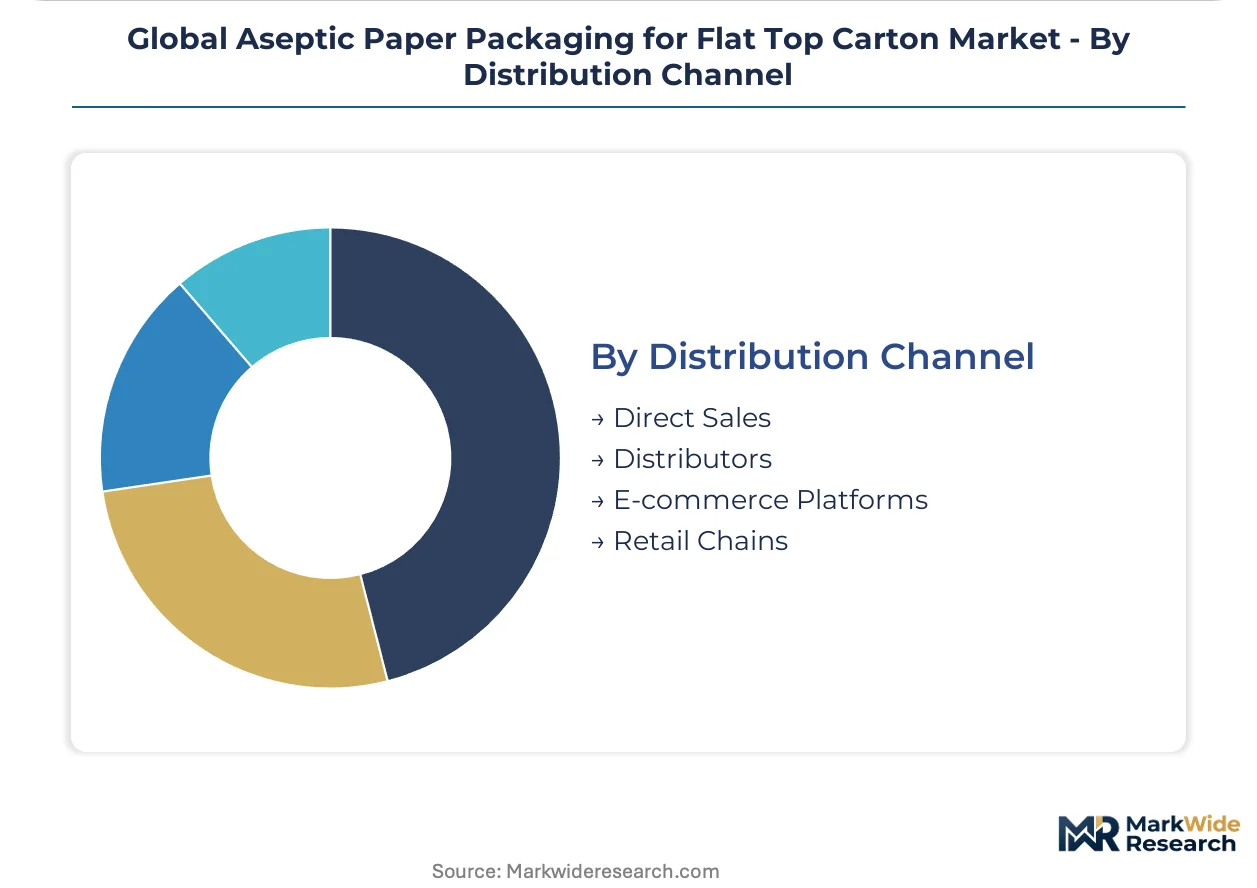
Distribution Channel:
The market's distribution channels delineate how aseptic cartons reach end consumers and industrial clients.
- Direct Sales:Manufacturers sell directly to large industrial clients, often for bulk orders or specialized applications, fostering direct relationships and customized supply agreements. This channel is common for high-volume processors.
- Distributors:Intermediary companies manage logistics and sales to a broader network of smaller manufacturers, retailers, and food service providers. Distributors offer regional reach and inventory management services.
- E-commerce Platforms:Online retail channels facilitate direct-to-consumer (D2C) sales for beverage and dairy products, particularly specialty items. This channel demands packaging robust enough for individual parcel delivery and complex logistics.
- Retail Chains:Traditional supermarkets, hypermarkets, and convenience stores serve as the primary point of sale for consumer-packaged goods. Retail chains require packaging that is shelf-stable, visually appealing, and optimized for display.
Retail Chains maintain significant market share, while E-commerce Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for aseptic paper packaging solutions exhibits significant regional asymmetry, with established markets like Germany commanding premium rates while emerging economies such as China prioritize cost-effectiveness. This disparity reflects varied consumer purchasing power, regulatory landscapes, and the maturity of local supply chains for packaging materials.
China
Demand for UHT milk and plant-based dairy alternatives drives significant growth in China's aseptic packaging market. The NMPA (National Medical Products Administration) mandates stringent food safety standards, favoring sterile packaging solutions. The Yangtze River Delta region, particularly around Shanghai, sees high investment in advanced aseptic filling and packaging lines.
United States
The United States market experiences strong demand from specialty beverages and the expanding direct-to-consumer e-commerce channels. US FDA regulations govern food contact materials and packaging safety, influencing design choices. In California, the vibrant beverage industry drives innovation in sustainable and robust aseptic carton formats suitable for complex logistics.
Germany
German manufacturers prioritize sustainable packaging solutions for premium dairy and export-oriented food products. The EU Green Deal directives on packaging waste are compelling a shift towards enhanced recyclability and bio-based materials. Bavaria's dairy sector is a hub for implementing advanced barrier-treated paperboard solutions to meet these environmental goals.
Brazil
Brazil's expanding middle class and increasing urbanization fuel demand for conveniently packaged, long-life liquid foods. ANVISA (National Health Surveillance Agency) establishes food packaging standards, ensuring product safety and quality. The São Paulo region experiences significant growth in aseptic carton adoption, especially for juices and UHT milk products.
India
India's large consumer base and extensive distribution challenges necessitate shelf-stable packaging for dairy products and juices. The FSSAI (Food Safety and Standards Authority of India) mandates specific requirements for food packaging materials. The Delhi-NCR region shows increasing demand for cost-effective aseptic solutions, supporting wider market penetration.
Global Aseptic Paper Packaging for Flat Top Carton Market Key Industry Players
Integrated solution providers and cost-effective alternative suppliers split the market for aseptic paper packaging. The industry exhibits a moderately consolidated top tier dominated by a few global players, while a fragmented base of regional specialists competes on price and localized service. Competitive moves often involve capacity expansion, strategic partnerships for material innovation, and geographic market penetration.
Within the integrated solutions tier, Tetra Pak International S.A. exemplifies a global leader, offering comprehensive processing and packaging technologies. Greatview Aseptic Packaging Co., Ltd. represents a strong challenger, particularly in Asian markets, by providing cost-effective alternatives and flexible supply agreements. SIG Combibloc Obeikan (Pty) Ltd. also occupies a significant position, known for its advanced filling technology and regional market presence, particularly in the Middle East and Africa.
| Leading Market Players |
|---|
| Stora Enso |
| Amcor Limited |
| Tetra Pak International S.A. |
| Nippon Paper Industries Co., Ltd. |
| Greatview Aseptic Packaging Co., Ltd. |
| SIG Combibloc Obeikan (Pty) Ltd. |
| Mondi Ltd. |
| TidePak Aseptic Packaging Material Co. Ltd. |
| Elopak SA |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping corridor's fluctuating freight costs directly influence the pricing power of large-volume suppliers and create distinct price differentiation across regional markets. These cost dynamics shape how raw material inputs are sourced and impact final product pricing.
Pricing Analysis
Configured-to-order aseptic packaging solutions command a premium over standard, high-volume offerings. Pricing stratifies across premium, standard, and economy tiers, driven by customization levels for barrier properties and the volume scale of orders. Pricing pressure stems from the volatility of paperboard pulp and polyethylene resins, impacting manufacturer margins. Regional brands and emerging market players exhibit higher price sensitivity compared to global premium beverage brands.
Supply Chain Analysis
Upstream feedstock for aseptic packaging heavily relies on pulp from Nordic countries like Finland and Sweden, alongside polyethylene resins primarily sourced from the Middle East. China also plays a significant role in paperboard and aluminum foil production. The supply chain faces structural risk from commodity price volatility for these essential inputs. Downstream distribution typically runs through direct sales channels to major food and beverage manufacturers, complemented by distributors serving smaller regional brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a cyclical recovery, driven by renewed consumer spending on convenience-focused liquid food products. Investment in sustainable packaging innovations further accelerates this upward trend.
For Market Incumbents: Insulate core market share by investing heavily in advanced, aluminum-free barrier technologies to counter sustainability-driven substitution pressure from flexible pouches. Expand integrated processing and packaging solutions into high-growth Asia-Pacific markets, leveraging existing supply chain control. This R&D focus on circular materials enhances brand owner loyalty and regulatory compliance. Consolidate regional supply agreements to optimize input costs.
For New Entrants and Emerging Players: Pursue underpenetrated liquid food segments like ready-to-drink soups, broths, and culinary sauces, where aseptic packaging offers clear shelf-stability advantages. Target specialty plant-based milk brands in North American e-commerce channels with robust, individual parcel-ready carton formats. Offer cost-effective, flexible supply agreements to regional brands seeking alternatives to dominant players. This strategy allows market entry without direct competition in established dairy or juice volumes.
For Investors and Strategic Acquirers: Carve-out targets emerge from large, diversified packaging conglomerates seeking to divest non-core aseptic operations. The market offers strong long-term viability over the next 5-10 years, driven by sustained demand for shelf-stable convenience and sustainability mandates. Focus on acquiring vertically integrated mid-cap specialists with proprietary barrier innovation capabilities. The signal to watch is the successful commercialization and widespread adoption of fully recyclable, aluminum-free carton solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-based Polymer Development | Reduces reliance on fossil-based plastics, aligning with EU Green Deal objectives and brand owner sustainability goals. |
| Expand Aseptic Filling Line Capacity | Captures growing demand for UHT milk and plant-based alternatives in Asia-Pacific markets. |
| Regional Supply Chain Optimization | Mitigates raw material price volatility and enhances delivery reliability for key food and beverage manufacturers. |
| Develop E-commerce Robust Packaging | Addresses the specific logistics challenges and product integrity requirements of direct-to-consumer delivery channels. |
| Strategic Partnerships for Recycling Infrastructure | Improves post-consumer carton collection and processing, supporting circular economy mandates and corporate responsibility. |
Research Approach
Desk research of regulatory filings, industry association reports, and company annual reports preceded structured interviews with packaging engineers, procurement managers, brand managers, and waste management specialists. This primary data collection validated and refined insights from secondary sources, ensuring a comprehensive market view. The analysis employed both bottom-up and top-down triangulation to establish market size and growth projections across various segments.
The forecast assumed stable macroeconomic conditions and consistent regulatory enforcement across the analysis window, varying input costs and consumer demand patterns. Segmentation dimensions modeled included product type, application, end-user, distribution channel, and geographic region. Compound Annual Growth Rates were derived from historical trends and future projections. UHT milk consumption and plant-based dairy adoption provided critical industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by material science startups would shift outcomes. Forecasts reflect assumptions; rapid material breakthroughs or regulatory shifts pose risks. Cross-checking industry consumption reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Carton Sealer Market
Cartons
Braille Cartons Packaging Market
Cartons
Mailers Market
Cartons
Europe Corrugated Box Market
Cartons
XXL Packaging Market
Cartons
Cupcake Box Market
Cartons
Interlocking Boxes Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Cartoning Machines Market
Cartons
Carton Liners Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Pulp Roll Cradles Market
Cartons
Wax Boxes Market
Cartons
Metallized PET Cartons Market