
 Tablet Cartons Market | 2026-2036
Tablet Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Cartons Market Analytics
Software-defined serialization and track-and-trace subscription layers is rebalancing how carton value gets captured, shifting margins from physical substrate to compliance-enabled service bundles. WestRock leverages its integrated paperboard-to-converting footprint to anchor large pharmaceutical contracts across North American manufacturing hubs. Amcor sustains global reach through multi-material platforms that span folding cartons, flexibles, and rigid plastics for tablet packaging. DS Smith specializes in circular-fiber solutions, competing on recycled-content specifications that meet tightening EU pharma sustainability criteria.
Tablet cartons are paperboard-based secondary packaging structures, typically 250–400 gsm folding carton grades with clay-coated or barrier-treated surfaces, designed to enclose primary blister packs or bottles while carrying regulatory labeling, barcoding, and patient information. Their commercial purpose centers on product protection, brand differentiation, and supply-chain traceability for oral solid-dose pharmaceuticals. Blister pack and carton product-type pairings dominate volume, as unit-dose compliance packaging expands in geriatric and polypharmacy populations. Cardboard material segments lead on sustainability credentials, though polypropylene closures are gaining in moisture-sensitive formulations where resealable push-through designs command premium positioning.
FDA serialization mandates under DSCSA and EU MDR unique device identifier requirements shape carton design, forcing investments in print verification and aggregation infrastructure. EMA and national competent authorities enforce tamper-evident and child-resistant standards that directly influence closure-type selection across European supply chains. Stakeholders must monitor evolving EPA and REACH restrictions on coatings and adhesives, as chemical compliance becomes inseparable from substrate qualification timelines for new drug launches.
Market Dynamics
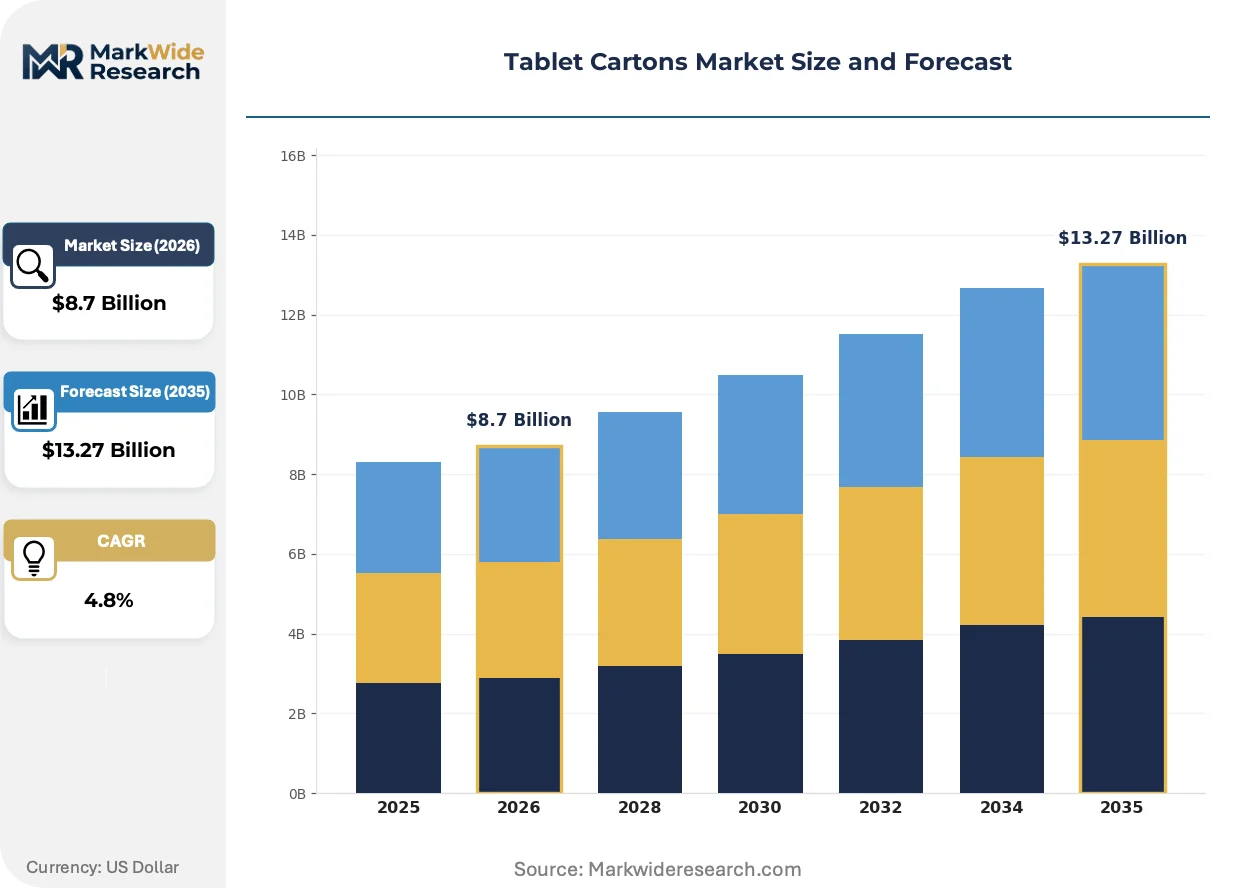
Serialization mandates and carbon-accounting pressures are restructuring how pharmaceutical converters capture value, shifting margin pools from substrate supply toward compliance-enabled service architectures and certified circular-fiber sourcing.
Growth Catalysts
- DSCSA compliance deadlines:FDA track-and-trace mandates force investments in aggregation-ready carton designs, expanding demand for print-verification infrastructure across US distribution networks.
- Geriatric polypharmacy expansion:Unit-dose blister-carton pairings accelerate as aging populations in Germany and Japan require adherence packaging for chronic disease management.
- EU Green Deal procurement rules:Public tender specifications now weight recycled-content thresholds, directing contract packagers toward circular-fiber carton specifications.
Market Restraints
- Coated paperboard cost volatility:Clay-coated folding carton grades face input pressure from pulp futures and energy-intensive drying processes, compressing converter margins.
- Specialty adhesive supply concentration:Moisture-barrier and tamper-evident adhesive formulations rely on concentrated German and Swiss chemical suppliers, creating qualification bottlenecks.
- Substitute flexible formats:High-barrier pouches and stick packs capture share in OTC and nutraceutical segments where portability outweighs carton stackability.
Strategic Opportunities
- Indian CDSCO serialization readiness:Domestic pharma manufacturers preparing for mandatory track-and-trace implementation create demand for aggregation-capable carton lines.
- Brazil ANVISA temperature-indicator integration:Cold-chain pharmaceuticals in Latin America open demand for smart-carton formats with embedded sensor compatibility.
- Digital watermarking convergence:Combination of invisible ink printing and blockchain verification enables premium authentication services for high-value biologics.
Industry Challenges
- Serialization engineering talent scarcity:Shortage of professionals fluent in both pharmaceutical packaging workflows and IT system integration slows line-deployment timelines.
- Multi-site certification synchronization:Global pharma customers require identical validation protocols across converting facilities, complicating capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Cartons Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Pack, Bottle, Tube, Carton Material: Cardboard, Plastic, Aluminum, Polypropylene Closure Type: Snap-Fit, Screw Cap, Push-Through, Resealable End User: Pharmacies, Hospitals, Clinics, Home Care |
| Companies Covered | WestRock, Amcor, Berry Global, DS Smith, Constantia Flexibles, Huhtamaki, Sonoco, Edelmann Group, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Cartons Market Evolving Landscape
Active and intelligent packaging technologies are penetrating pharmaceutical secondary packaging, while regulatory tightening on chemical constituents accelerates substrate reformulation cycles.
Laser-etched serialization is rewriting how carton converters deploy capital, replacing mechanical embossing and inkjet stations with fiber-ablation systems that embed unique identifiers directly into paperboard structure. Large North American contract packagers are retrofitting lines at pace, compressing equipment replacement cycles from seven-year horizons toward three-year refresh mandates.
EU F-Gas Regulation phase-down schedules are forcing substrate suppliers to eliminate fluorinated barrier coatings from pharmaceutical carton specifications. Converters serving EMA-regulated products must qualify alternative grease-resistant and moisture-barrier treatments, with Germany's Rhineland cluster experiencing the most intensive reformulation activity.
Hospital and pharmacy buying consortia are consolidating procurement of compliance-ready carton formats, displacing fragmented spot purchasing with multi-year framework agreements tied to serialization capability and carbon-disclosure scoring. This concentration is most visible in NHS England tendering and German hospital purchasing alliances.
Tablet Cartons Market Segmentation
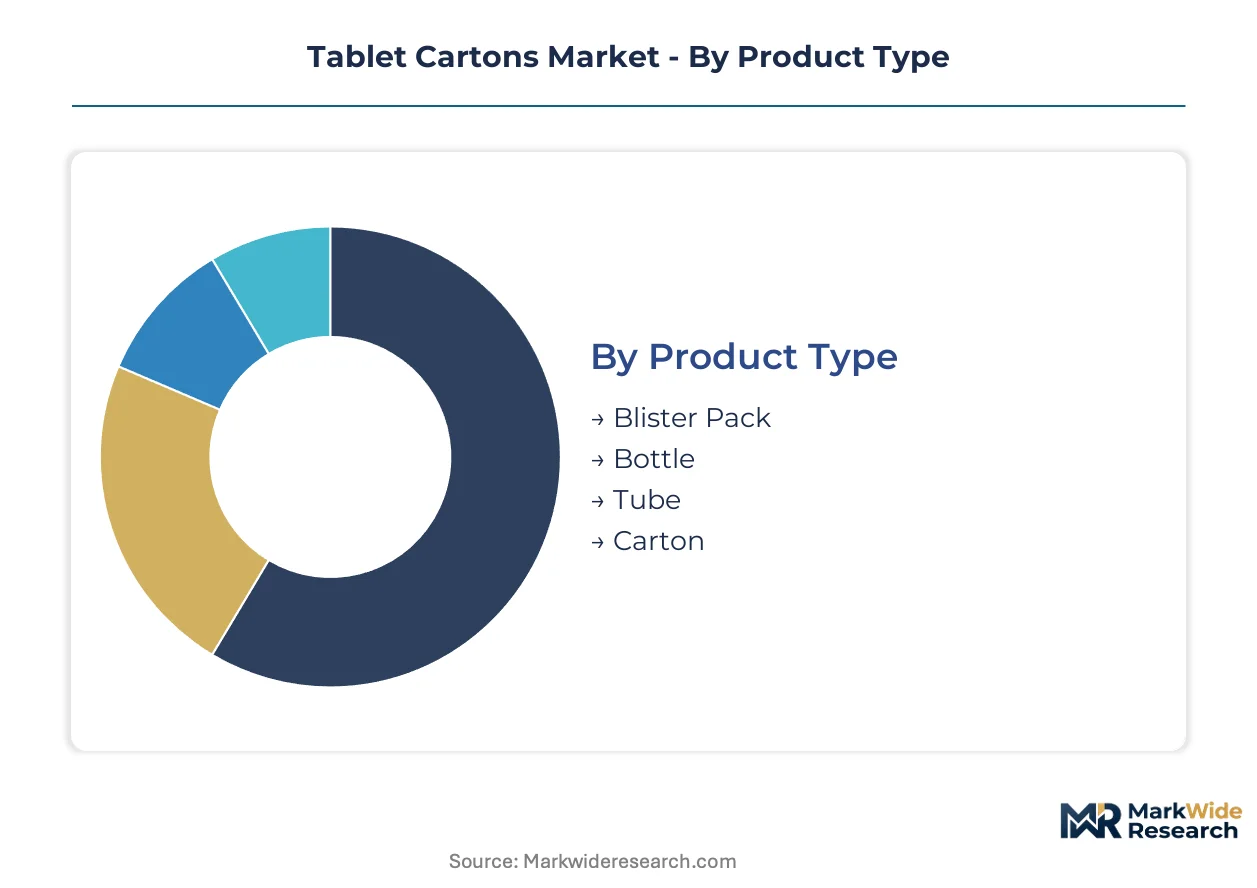
Tablet carton segmentation reveals how regulatory certification burdens concentrate across packaging architectures. Each dimension carries distinct EMA, FDA, or national pharmacy authority requirements that shape converter qualification timelines and margin structures.
Product Type:
Blister pack pairings demand DSCSA aggregation-ready serialization infrastructure, while bottle and tube formats trigger divergent child-resistance testing protocols under USP <671> and ISO 8319 standards.
- Blister Pack:Folding carton structures engineered to enclose thermoformed PVC or aluminum lidding assemblies, typically 300-400 gsm with clay-coated print surfaces. Demand concentrates in Germany's Rhineland pharmaceutical cluster, where contract packagers serve export markets requiring EMA-compliant tamper-evident features. FDA track-and-trace mandates force investments in aggregation-ready line configurations.
- Bottle:Secondary carton sleeves and boxes designed for HDPE or glass primary containers, emphasizing stackability for pharmacy inventory density. Japanese polypharmacy populations drive unit-of-use formats with integrated patient information leaflets. PMDA serialization readiness requirements shape converter selection criteria.
- Tube:Carton enclosures for aluminum or laminate squeeze tubes, common in topical and effervescent tablet presentations. The format faces pressure from flexible pouch substitutes in OTC segments.
- Carton:Stand-alone folding carton primary packaging for bulk tablet presentations, requiring enhanced moisture-barrier specifications. Hospital purchasing consortia favor this format for inventory efficiency.
Leading the category by volume: Blister Pack. Growing fastest: Bottle formats for geriatric adherence packaging.
Material:
Raw material selection determines REACH compliance pathways and carbon-accounting eligibility under EU Green Deal procurement weightings.
- Cardboard:Recycled-content folding carton grades from 250-350 gsm, competing on circular-fiber certifications that satisfy NHS England tender specifications. Clay-coated surfaces face EU F-Gas Regulation pressure to eliminate fluorinated barrier treatments.
- Plastic:PET or PVC windowed cartons for product visibility in retail pharmacy environments. ANVISA temperature-indicator compatibility drives smart-packaging integration in Brazilian cold-chain applications.
- Aluminum:Laminated foil-board constructions for high-barrier moisture protection in tropical climates. The material commands premium positioning but faces recycling infrastructure constraints.
- Polypropylene:Injection-molded or thermoformed rigid components for resealable push-through designs. Swissmedic-registered moisture-sensitive formulations favor this substrate for stability assurance.
Cardboard dominates procurement volumes. Polypropylene exhibits the steepest expansion trajectory as moisture-barrier specifications tighten.
Closure Type:
Child-resistance and senior-friendly testing under 16 CFR 1700 and ISO 8317 creates segmentation between compliance-heavy and convenience-oriented designs.
- Snap-Fit:Friction-lock carton closures for low-risk OTC presentations, minimizing material cost and assembly complexity. German pharmacy chains specify this format for generic substitution packaging.
- Screw Cap:Threaded polyethylene or polypropylene closures for bottle-carton combinations requiring repeated access. CDSCO-mandated serialization in India favors this format for aggregation line compatibility.
- Push-Through:Integrated foil or film lidding for unit-dose blister extraction, balancing child-resistance with geriatric accessibility. EMA tamper-evident guidelines directly influence design specifications.
- Resealable:Adhesive strip or zipper mechanisms for multi-dose compliance packaging. Japan's aging population drives demand for arthritis-friendly opening features.
Push-Through leads pharmacy dispensing volumes. Resealable formats gain share fastest in home care and long-term adherence programs.
End User:
Procurement concentration varies sharply across channel types, with hospital buying consortia exercising greater serialization and carbon-disclosure leverage than fragmented retail pharmacy networks.
- Pharmacies:Community and retail dispensaries requiring stackable, shelf-ready carton formats with barcode verification compatibility. German pharmacy purchasing alliances consolidate tender specifications around circular-fiber thresholds.
- Hospitals:Institutional buyers operating under NHS England and German hospital alliance framework agreements that mandate DSCSA-equivalent traceability and carbon-accounting transparency.
- Clinics:Outpatient and specialist settings favoring compact carton dimensions for limited storage space. Brazilian clinic networks drive temperature-indicator integration for cold-chain biologics.
- Home Care:Direct-to-patient and long-term care packaging emphasizing senior-friendly opening and adherence support features. Japan's home nursing expansion supports this segment.
Pharmacies represent the largest volume channel. Home Care expands most quickly as chronic disease management decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Germany's Rhineland cluster supply export markets across three continents, while US contract packagers absorb domestic serialization infrastructure costs. India's CDSCO mandates and Brazil's ANVISA temperature-indicator rules are redirecting procurement toward compliance-ready carton specifications in emerging pharmaceutical manufacturing hubs.
United States
FDA DSCSA aggregation deadlines force pharmaceutical distributors to verify carton-level traceability before November 2024. EPA restrictions on perfluorinated coatings intersect with state-level extended producer responsibility laws in California and New York. New Jersey and Pennsylvania host the densest contract packaging corridors serving branded and generic drug manufacturers.
Germany
EMA tamper-evident guidelines and EU F-Gas Regulation phase-downs are eliminating fluorinated barrier treatments from pharmaceutical carton specifications. The country's hospital purchasing alliances now weight circular-fiber thresholds above unit price in tender evaluations. North Rhine-Westphalia's Rhineland cluster concentrates Europe's largest blister-carton converting capacity for export to Middle Eastern and African markets.
India
CDSCO mandatory track-and-trace implementation for domestic pharmaceutical exports creates demand for aggregation-capable carton lines. The PLI scheme for active pharmaceutical ingredients indirectly supports secondary packaging investment through integrated manufacturing parks. Maharashtra and Gujarat house the majority of contract packagers preparing serialization-ready infrastructure for regulated markets.
Japan
PMDA serialization readiness requirements and aging demographics drive unit-of-use bottle-carton formats with integrated patient information leaflets. METI circular economy roadmaps pressure converters toward recycled-content specifications for hospital procurement. The Kansai region around Osaka maintains specialized capacity for moisture-sensitive formulations requiring premium barrier substrates.
Brazil
ANVISA temperature-indicator integration mandates for cold-chain biologics open demand for smart-carton formats with embedded sensor compatibility. The country's national pharmaceutical regulator enforces serialization timelines that lag US and EU implementation by 18-24 months. São Paulo state anchors Latin America's largest contract packaging cluster serving regional export markets.
Tablet Cartons Market Competitive Landscape
Top-tier vendors anchor multi-year pharmaceutical contracts, while mid-scale converters compete on regional certification speed and carbon-disclosure scoring. The vendor base stratifies across integrated paperboard-to-converting platforms, multi-material packaging conglomerates, and circular-fiber specialists. Three archetypes dominate: North American integrated converters with captive substrate supply, European sustainability-focused specialists, and Asia-Pacific multi-material platforms. Competitive moves center on serialization infrastructure partnerships and recycled-content qualification programs.
Within the integrated converter tier, WestRock exemplifies the paperboard-to-converting footprint model, while Amcor occupies a position spanning folding cartons, flexibles, and rigid plastics across global pharmaceutical accounts. DS Smith represents the circular-fiber specialist archetype competing on EU Green Deal procurement compliance.
| Leading Market Players |
|---|
| WestRock |
| Amcor |
| Berry Global |
| DS Smith |
| Constantia Flexibles |
| Huhtamaki |
| Sonoco |
| Edelmann Group |
| CCL Industries |
| Others |
Value Network & Pricing Analysis
Captive paperboard-to-converting integration anchors pricing power for North American pharmaceutical contract packagers serving FDA-mandated serialization contracts, while European converters absorb premium circular-fiber qualification costs under NHS England tender specifications. This integration choice separates margin capture between substrate suppliers and compliance-enabled service providers.
Pricing Analysis
Margin tightening in standard-grade folding cartons traces to clay-coated paperboard input volatility and energy-intensive drying processes. Three-tier pricing structure across premium serialization-ready, standard certified-circular, and economy generic-OTC levels stratifies by DSCSA aggregation capability and recycled-content thresholds. Pricing pressure accelerates in cardboard segments as EU F-Gas Regulation reformulation costs transfer downstream. Hospital buying consortia exhibit lowest price sensitivity, prioritizing carbon-disclosure scoring and traceability infrastructure over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss specialty adhesive suppliers for moisture-barrier and tamper-evident formulations, creating qualification bottlenecks for EMA-regulated products. Raw material dependencies center on Nordic pulp for folding carton grades, kaolin clay for coated surfaces, and fluorochemical alternatives for barrier treatments. Supply chain risk concentrates in regulatory restriction exposure as REACH and EPA coatings restrictions compress substrate approval timelines. Distribution runs through pharmaceutical contract packagers in Germany's Rhineland cluster and New Jersey-Pennsylvania corridors, with hospital purchasing consortia consolidating procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Serialization engineering talent scarcity props pricing for compliance-capable carton converters, constraining capacity expansion timelines across pharmaceutical packaging networks.
For Market Incumbents: Anchor multi-year pharmaceutical contracts through integrated paperboard supply and aggregation-ready line infrastructure. Defend position by accelerating laser-etched serialization retrofit cycles before CDSCO mandates activate in India. Prioritize circular-fiber certification investment to meet EU Green Deal procurement weightings in NHS England and German hospital alliance tenders. For New Entrants and Emerging Players: EU F-Gas Regulation phase-downs in Germany open a window for alternative barrier-coating specialists to qualify fluorine-free substrates with Rhineland contract packagers. Target Brazilian ANVISA temperature-indicator integration requirements for cold-chain biologics as the most penetrable smart-packaging segment. Pursue digital watermarking partnerships with blockchain verification platforms as the go-to-market angle for high-value biologics authentication services. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale regional converters with multi-site certification synchronization capabilities and established pharmaceutical validation protocols. Long-term viability favors platforms with captive substrate supply and compliance-enabled service architectures over pure-play converters. Watch Indian CDSCO serialization implementation timelines as the inflection signal for aggregation-capable carton line demand.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Partnership | Aggregation-ready line configurations secure FDA DSCSA-compliant pharmaceutical contracts. |
| Circular-Fiber Certification Program | Recycled-content specifications satisfy NHS England tender weightings and EU Green Deal procurement rules. |
| Alternative Barrier Coating Qualification | Fluorine-free substrates meet EMA tamper-evident guidelines under EU F-Gas Regulation phase-downs. |
| Smart-Carton Sensor Integration | Temperature-indicator compatibility addresses ANVISA mandates for Brazilian cold-chain biologics. |
| Digital Watermarking Platform Development | Invisible ink printing with blockchain verification enables premium authentication for high-value biologics. |
Research Methodology
Multi-period observation of pharmaceutical packaging capacity expansion, regulatory submission timelines, and hospital procurement contract awards anchored the trend analysis, supplemented by interviews with contract packaging operations directors, serialization engineering leads, pharmaceutical regulatory affairs managers, and hospital GPO contracts specialists. Secondary validation drew from FDA DSCSA guidance documents, EMA quality defect records, NHS England tender specifications, and CDSCO track-and-trace notifications. Bottom-up facility-level capacity estimates and top-down pharmaceutical production forecasts were triangulated to constrain volume projections.
Segment-weighting across product type, material grade, closure mechanism, and end-user channel shaped the analytical framework over the projection horizon. Treatment line, dosage form, and regional regulatory cluster dimensions were modeled for pharmaceutical specificity. CAGRs were derived from fitted growth curves calibrated to observed capacity deployment and procurement contract durations. Forecast inputs incorporated serialization mandate compliance deadlines and circular-fiber certification adoption rates.
The model assumes a particular technology adoption path; alternative pathways for laser-etched serialization or digital watermarking convergence would alter the outlook. Forecasts reflect assumptions regarding regulatory implementation timelines and hospital purchasing consortia consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Pizza Cartons Market
Cartons
Mailers Market
Cartons
Printed Folding Cartons Market
Cartons
Global Folding Carton Packaging Market
Cartons
Carton Sealer Machine Market
Cartons
Mono Carton Market
Cartons
Interlocking Boxes Market
Cartons
Fluted Carton Trays Market
Cartons
Folding Carton in Healthcare Market
Cartons
Metallized PET Cartons Market
Cartons
Carton Liners Market
Cartons
Carton Bottle Market
Cartons
Carton Display Market
Cartons
Microwaveable Carton Market
Cartons
Metallized Folding Cartons Market
Cartons
Twist Opening Cartons Market