
 Aluminum Foil Packaging Market | 2026-2036
Aluminum Foil Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Foil Packaging Market Intelligence
ISO 22000 certification is bifurcating the supplier base into food-grade qualified converters and generalist rollers. Novelis Inc. leverages its closed-loop recycling network to secure beverage and food OEM contracts. Hindalco Industries Limited anchors South Asian supply through integrated alumina-to-foil capacity. Constantia Flexibles specializes in pharmaceutical blister lidding and cold-form laminates across European health authorities.
Aluminum foil packaging comprises rolled aluminum alloy sheets between 0.006 mm and 0.2 mm thickness, manufactured through continuous casting or direct chill ingot reduction, engineered to provide moisture, oxygen, and light barriers for perishable and sensitive goods. The end use industry dimension shows food processing occupying the volume base while pharmaceuticals commands premium margin pools due to child-resistance and shelf-life requirements. Pouches and stick packs within product type are gaining share against rigid containers in single-serve and on-the-go consumption formats.
The US FDA governs indirect food contact substances through 21 CFR while the EU REACH framework restricts Substances of Very High Concern in laminated foil constructions, compelling reformulation of adhesives and coatings. China's SAMR enforces GB standards for food contact metals that exporters must meet for market access. Stakeholders must monitor regulatory divergence on chemical migration limits as a determinant of which foil constructions qualify for cross-border pharmaceutical and food contracts.
Market Dynamics
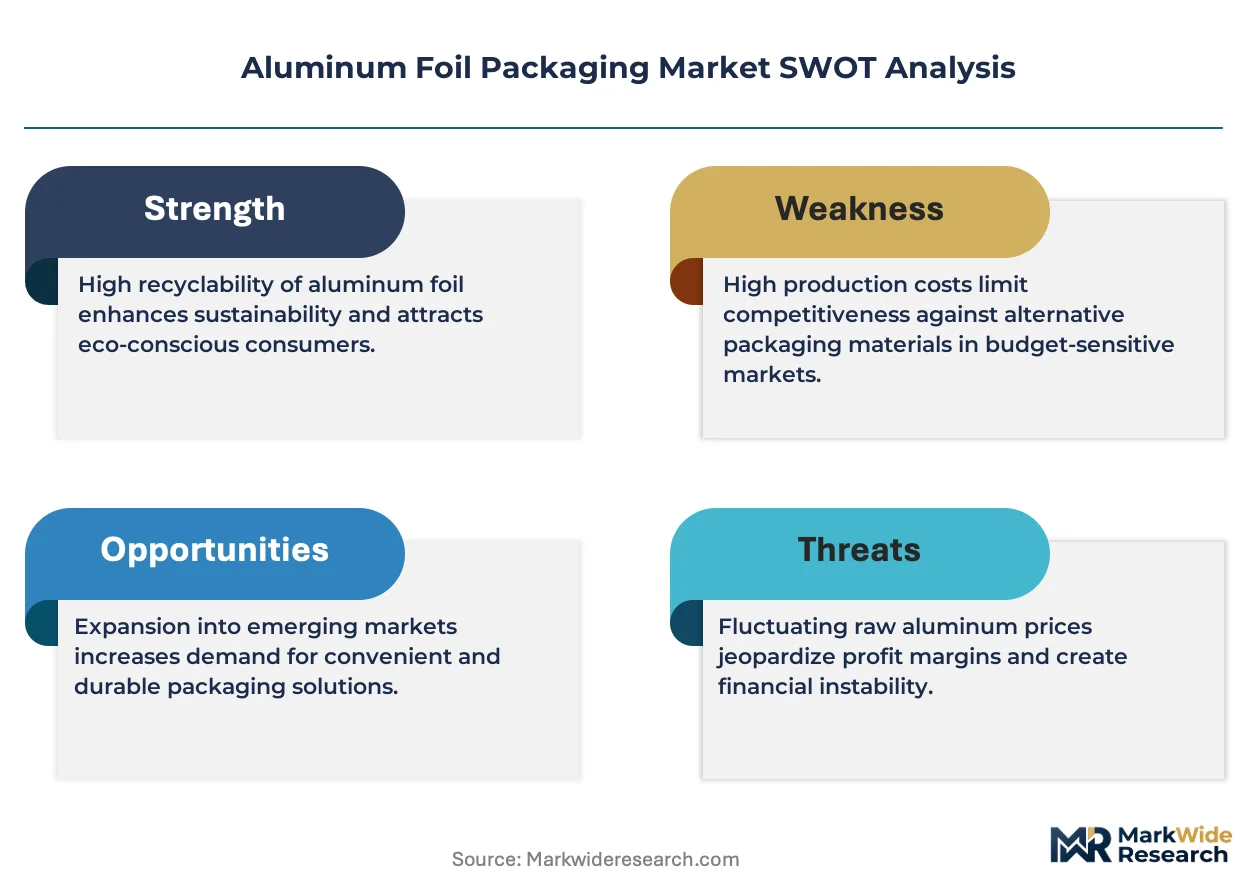
REACH compliance and the EU Packaging and Packaging Waste Regulation are forcing converters to abandon multi-layer laminates in favor of recyclable mono-material aluminum structures, fundamentally restructuring capital allocation across the supply base.
Growth Catalysts
- EU regulatory mandates:The Packaging and Packaging Waste Regulation compels brands to eliminate non-recyclable multi-material constructions, creating pull-through demand for pure aluminum foil formats in food and pharmaceutical applications.
- India food manufacturing expansion:Domestic ready-to-eat and convenience food output is scaling rapidly, requiring barrier-sensitive foil for retort pouches and lidding applications across the subcontinent.
- Pharmaceutical shelf-life extension:Cold-form blister foils with enhanced moisture and oxygen barriers are displacing conventional PVC alternatives in chronic medication packaging.
Market Restraints
- Alumina and energy input volatility:Smelter power costs and bauxite supply disruptions in Guinea and Australia transmit directly to foil rolling margins, compressing converter profitability during price spikes.
- China supply concentration:Over half of global primary aluminum capacity sits within Chinese state-controlled enterprises, creating geopolitical exposure for European and North American foil buyers.
- Technical thickness floor:Conventional rolling mills cannot economically produce below 6 micron gauges demanded by ultralight flexible packaging, ceding share to cast film alternatives in weight-sensitive applications.
Strategic Opportunities
- Brazil domestic pharmaceutical growth:ANVISA regulatory alignment with ICH standards is enabling local blister foil production for export to Latin American markets previously served by European converters.
- Digital printing convergence:Hybrid flexo-digital presses on foil substrates allow SKU proliferation without cylinder changeover costs, opening short-run premium cosmetic and nutraceutical segments.
- EU Green Deal circularity incentives:Member state extended producer responsibility schemes now credit mono-aluminum packaging with higher recyclability scores, tilting brand procurement toward foil-dominant structures.
Industry Challenges
- ISO 22000 auditor scarcity:Qualified food safety certification bodies are backlogged 6-12 months in South Asia, delaying converter qualification for multinational FMCG contracts.
- Laminate adhesive reformulation:Solvent-based polyurethane chemistries face REACH Substances of Very High Concern scrutiny, requiring R&D investment in waterborne or UV-curable alternatives with unproven line speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Foil Packaging Market |
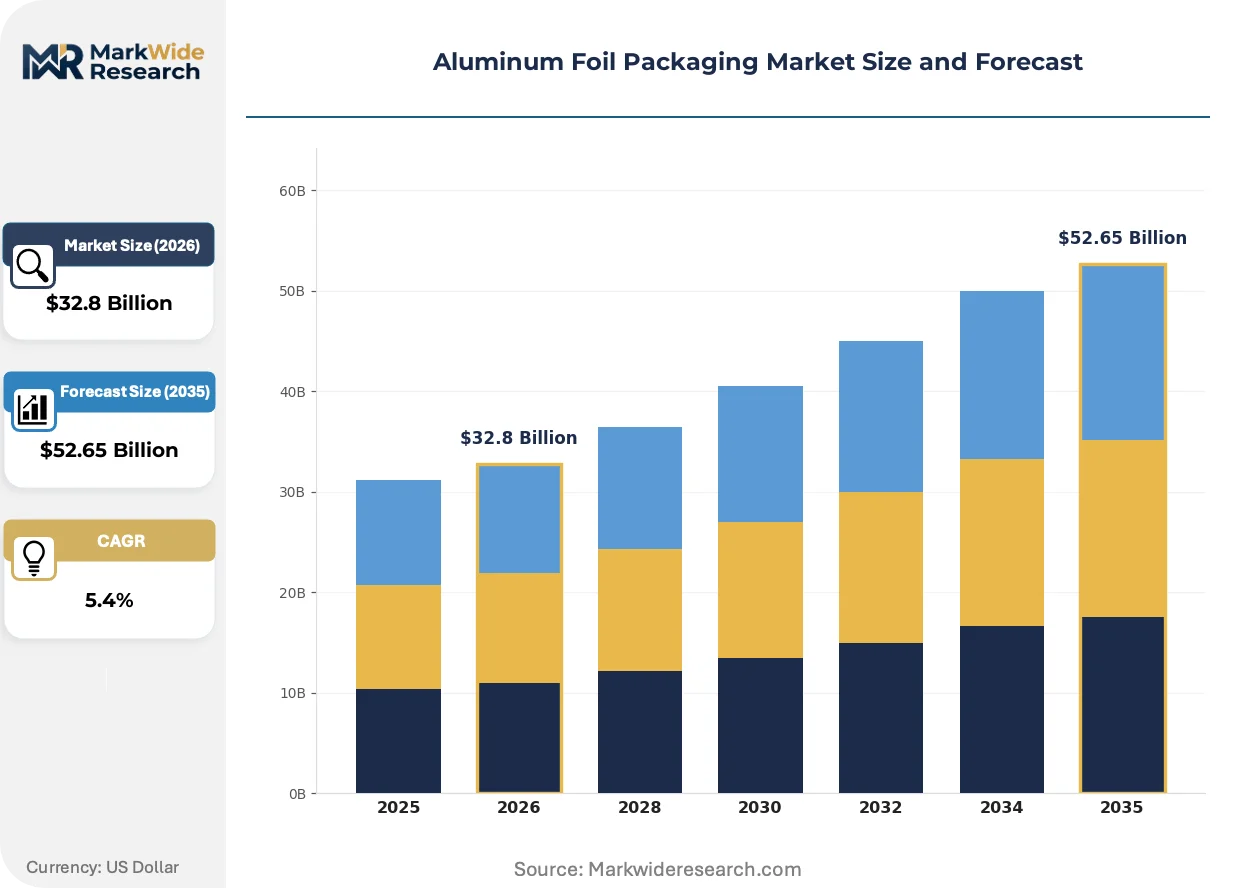
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rolls, Containers, Pouches, Stick Packs End Use Industry: Food Processing, Pharmaceuticals, Cosmetics, Electronics Thickness: Heavy Gauge, Standard Gauge, Light Gauge, Ultra Light Gauge Form: Sheet, Film, Laminated, Coated |
| Companies Covered | Amcor plc, Novelis Inc., Constantia Flexibles, Hindalco Industries Limited, China Hongqiao Group Limited, Reynolds Consumer Products, United Company RUSAL Plc, Hulamin, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Foil Packaging Market Strategic Shifts & Innovations
Active substitution of legacy multi-material laminates with engineered mono-aluminum constructions is reshaping converter R&D priorities and brand technical specifications simultaneously.
Ultrathin 5.5-6.5 micron household foils with reinforced tear resistance are displacing heavier 12-14 micron gauges in food service and retail wrap segments. Quick-service restaurant chains and institutional catering operations are specifying these reduced-weight formats to meet corporate packaging reduction targets. This gauge compression is forcing rolling mill investments in precision tension control and online thickness monitoring systems.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer-coated foils from European food contact applications by 2026. Converter technical teams are validating silicone and plant-based oil coatings as release alternatives for baking and grilling applications. Germany and France represent the largest affected demand pools, with reformulation timelines compressing as enforcement dates approach.
Brand technical buyers are consolidating supplier panels around converters offering closed-loop aluminum recycling and verified carbon footprint data. Certification to ASI Performance Standard or equivalent chain-of-custody schemes is becoming a gatekeeper criterion for beverage and dairy OEM contracts. This preference shift is most pronounced in Nordic markets and among multinational FMCG headquarters procurement functions.
Aluminum Foil Packaging Market Segmentation
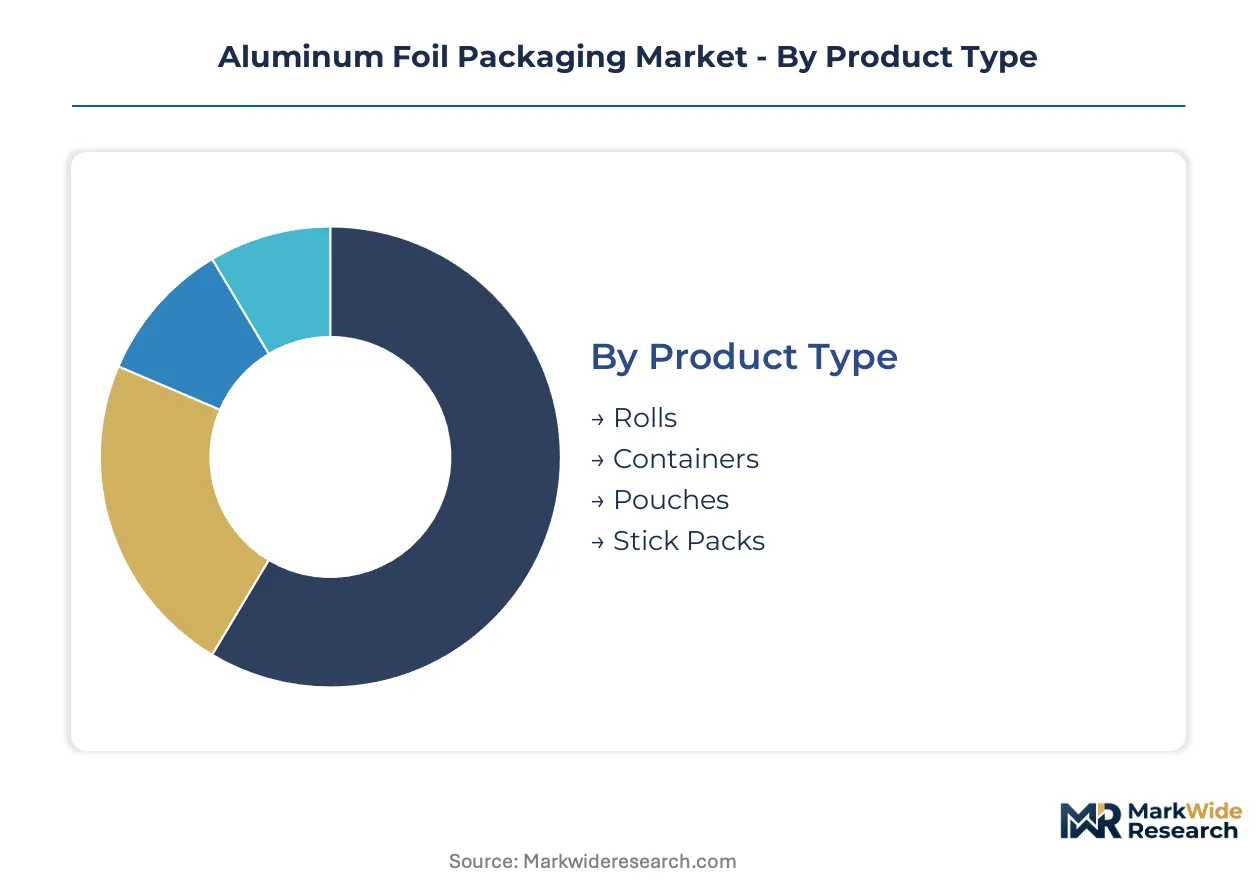
Aluminum foil packaging segments diverge sharply in their exposure to material substitution and regulatory compliance costs. Understanding these fault lines enables suppliers to prioritize R&D investment and brand qualification pathways across incompatible technical specifications.
Product Type:
Substitution pressure from flexible plastic films and fiber-based alternatives varies dramatically by format rigidity and barrier performance requirements.
- Rolls:Continuous wound aluminum strip between 6-200 micron thickness serves converter slitting operations and industrial lidding applications. Food processing plants in India and Brazil are expanding rollstock consumption for retort pouch production and tray lidding as domestic ready-to-eat output scales.
- Containers:Pressed or drawn rigid aluminum trays, pans, and compartmentalized meal boxes deliver structural integrity for oven-ready and frozen food applications. Quick-service restaurant chains across Germany are specifying proprietary container geometries with embossed branding surfaces to replace plastic clamshells under EU Packaging and Packaging Waste Regulation mandates.
- Pouches:Flexible three- or four-side-seal formats with aluminum foil barrier layers.
- Stick Packs:Single-serve narrow format sachets for powder and liquid dose packaging.
Rolls anchor the volume base while pouches gain share at the steepest rate.
End Use Industry:
Margin structure and certification intensity separate end-use segments into distinct commercial ecosystems with incompatible supplier qualification timelines.
- Food Processing:Barrier-sensitive foil formats for ready-to-eat meals, dairy lidding, and snack packaging dominate tonnage. REACH compliance and evolving EU Packaging and Packaging Waste Regulation are redirecting converter investments toward recyclable mono-material structures across German retail supply chains.
- Pharmaceuticals:Cold-form blister foils and child-resistant lidding command premium pricing due to shelf-life extension requirements and health authority validation. ANVISA regulatory alignment in Brazil is enabling local production for Latin American markets previously served by European converters.
- Cosmetics:Laminated foil tubes and sachets for premium personal care applications.
- Electronics:Static-dissipative foil wraps and moisture barrier bags for semiconductor and component shipping.
Food processing anchors the volume base while pharmaceuticals climbs the fastest on margin expansion.
Thickness:
Gauge selection determines rolling mill capital intensity and the competitive boundary with metallized polymer films.
- Heavy Gauge:Aluminum above 0.1 mm thickness for structural containers and industrial applications.
- Standard Gauge:0.02-0.1 mm range for general purpose wrapping and semi-rigid packaging.
- Light Gauge:0.006-0.02 mm foil for flexible lidding and pouch constructions. Ultrathin 5.5-6.5 micron household foils with reinforced tear resistance are displacing heavier 12-14 micron gauges in food service and retail wrap segments as quick-service restaurant chains specify reduced-weight formats.
- Ultra Light Gauge:Sub-6 micron foils approaching the technical thickness floor of conventional rolling mills. Conventional equipment cannot economically produce below 6 micron gauges demanded by weight-sensitive flexible packaging, ceding share to cast film alternatives in these applications.
Standard gauge anchors the volume base while ultra light gauge faces the steepest substitution headwinds.
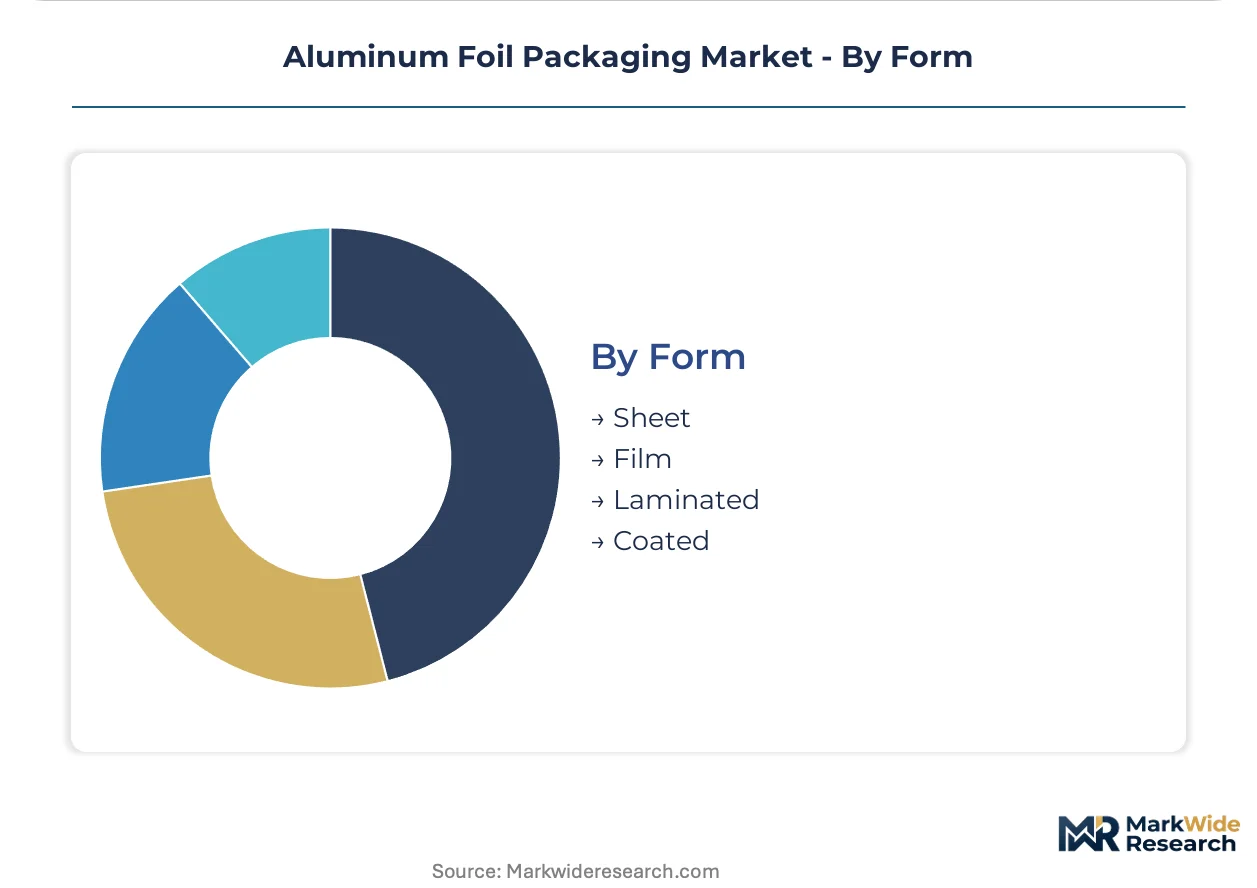
Form:
Surface engineering and lamination architecture define recyclability credentials under tightening extended producer responsibility schemes.
- Sheet:Flat cut-to-size aluminum blanks for manual wrapping and industrial applications.
- Film:Unlaminated pure aluminum foil in continuous web form. EU Green Deal circularity incentives now credit mono-aluminum packaging with higher recyclability scores, tilting brand procurement toward unlaminated film formats.
- Laminated:Multi-layer constructions with paper, plastic, or adhesive bonding.
- Coated:Surface-treated foils with silicone or plant-based oil release layers. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer-coated foils from European food contact applications, forcing validation of alternative coatings in Germany and France.
Film anchors the volume base while coated formats expand most quickly on functional specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational food and pharmaceutical OEMs concentrate procurement authority in Germany, India, Brazil, and China, creating divergent qualification demands across regulatory jurisdictions. Each geography presents distinct compliance thresholds and supply chain configurations.
Germany
Quick-service restaurant chains specify proprietary aluminum container geometries with embossed branding surfaces to replace plastic clamshells under EU Packaging and Packaging Waste Regulation mandates. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate fluoropolymer-coated foils from food contact applications by 2026. The Rhine-Ruhr industrial corridor hosts converter operations validating silicone and plant-based oil coating alternatives.
India
Domestic ready-to-eat and convenience food output scales rapidly, requiring barrier-sensitive foil for retort pouches and lidding applications across the subcontinent. FSSAI food contact metal standards and BIS certification requirements govern import and domestic production. Maharashtra and Gujarat industrial zones anchor South Asian supply through integrated alumina-to-foil capacity expansions.
Brazil
ANVISA regulatory alignment with ICH standards enables local blister foil production for Latin American markets previously served by European converters. Domestic pharmaceutical packaging output climbs as chronic medication demand expands. São Paulo state concentrations of converter operations target export qualification to Mercosur neighbors.
China
SAMR enforces GB standards for food contact metals that exporters must meet for market access, creating technical barriers for foreign foil suppliers. Over half of global primary aluminum capacity sits within state-controlled enterprises. Shandong and Henan provinces host rolling mill clusters serving both domestic flexible packaging and international converter supply.
United States
FDA 21 CFR governs indirect food contact substances through migration testing protocols that differ from EU methodologies. Beverage and dairy OEM procurement functions consolidate supplier panels around converters offering verified carbon footprint data. The Southeast industrial corridor attracts foil laminating investments serving quick-service restaurant chain specifications.
Aluminum Foil Packaging Market Key Industry Players
Player mix skews toward integrated primary aluminum producers with captive foil rolling capacity, supplemented by independent converters specializing in pharmaceutical and food-grade qualifications. Three archetypes dominate: smelter-integrated rollers controlling bauxite-to-foil value chains, independent laminators focused on multi-layer barrier constructions, and regional specialists serving ANVISA or FDA certification niches. Capacity expansion and strategic partnerships represent the dominant competitive moves, with converters seeking backward integration into rolling operations to secure gauge control.
Among integrated primary producers, Novelis Inc. and Hindalco Industries Limited exemplify the smelter-integrated archetype with captive aluminum supply chains. Constantia Flexibles occupies a position within the pharmaceutical-specialist tier, representing converters focused on health authority validation. These three companies anchor the competitive structure, with each representing distinct strategic postures across regulatory jurisdictions and end-use segments.
| Leading Market Players |
|---|
| Amcor plc |
| Novelis Inc. |
| Constantia Flexibles |
| Hindalco Industries Limited |
| China Hongqiao Group Limited |
| Reynolds Consumer Products |
| United Company RUSAL Plc |
| Hulamin |
| Alcoa Corporation |
| Others |
Cost & Logistics Intelligence
Ninety-day rolling inventory commitments at European converters now govern contract negotiations, concentrating pricing power among Hindalco and Novelis while forcing independent laminators to absorb alumina volatility through thinner margins. This inventory discipline links directly to the EU Packaging and Packaging Waste Regulation's recyclability mandates, which favor mono-material aluminum structures with predictable input costs.
Pricing Analysis
Cost-plus contracts indexed to LME aluminum spot prices dominate converter rollstock procurement, with premium-mid-economy pricing differentiation separating ASI-certified supply from generalist rollers. Food-grade ISO 22000 qualification commands margin premiums of fifteen to twenty percent above industrial grades. Pricing pressure stems from Guinea bauxite supply disruptions transmitting through smelter power costs. Quick-service restaurant chains exhibit highest price sensitivity due to corporate packaging reduction targets, while pharmaceutical OEMs prioritize barrier performance over unit economics.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp lanes elevates inbound logistics costs for European converters dependent on Guinean bauxite and Australian alumina. Primary supply concentrates in China, India, and Russia, with rolling mill capacity clustering in Shandong, Maharashtra, and the Rhine-Ruhr corridor. The value chain draws from bauxite mining, alumina refining, and continuous casting operations. Single-source vulnerability to Chinese state-controlled smelter output creates geopolitical exposure. Distribution runs through converter slitting operations serving FMCG and pharmaceutical OEMs with just-in-time rollstock delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, FDA 21 CFR, and ANVISA standards fragments supplier qualification pathways, creating specialist niches for certified converters in each jurisdiction. This compliance complexity rewards focused players over generalists.
For Market Incumbents: Fortify backward integration into rolling operations to secure gauge control below 6.5 microns, insulating margins from alumina price spikes. Prioritize ISO 22000 auditor retention in South Asia where six-to-twelve month backlogs delay multinational FMCG contracts. Capacity expansion in São Paulo state captures ANVISA-aligned pharmaceutical demand. For New Entrants and Emerging Players: FDA 21 CFR fast-track certification opens North American pharmaceutical blister foil segments previously closed to unvalidated suppliers. Target Brazil domestic pharmaceutical growth where ANVISA-ICH alignment enables export to Mercosur neighbors. Digital printing convergence on foil substrates offers SKU proliferation services without cylinder changeover costs. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated primary aluminum producers seeking to divest downstream converting assets. Five-to-ten year viability hinges on recyclability credentials under tightening extended producer responsibility schemes. Monitor EU Green Deal circularity incentives as the inflection signal tilting brand procurement toward mono-aluminum structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rolling Operations | Captive gauge control below 6.5 microns secures ultralight flexible packaging contracts from weight-sensitive QSR chains. |
| ISO 22000 Certification Fast-Track | Accelerated food safety qualification unlocks multinational FMCG procurement panels with six-month backlog advantages. |
| Digital Printing Convergence | Hybrid flexo-digital presses enable short-run cosmetic and nutraceutical segments without cylinder changeover delays. |
| ANVISA Regulatory Alignment | ICH-standard blister foil production in São Paulo state targets Latin American export markets previously served by European converters. |
| Closed-Loop Recycling Network | ASI Performance Standard certification satisfies Nordic beverage OEM carbon footprint verification requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with converter plant managers, pharmaceutical packaging procurement leads, quick-service restaurant chain sustainability directors, and aluminum rolling mill technical directors. Secondary validation drew from ECHA REACH filings, FDA 21 CFR indirect food contact substance databases, ANVISA pharmaceutical packaging guidelines, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Across the projection horizon, analytical frameworks modeled product type segmentation by format rigidity, end-use industry by certification intensity, thickness gauge by rolling mill capital requirements, and surface engineering by recyclability credentials. CAGRs were derived from regression analysis of historical volume trajectories and regulatory mandate implementation timelines. Forecast inputs included alumina price volatility indices and extended producer responsibility scheme adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained EU regulatory stringency and India food manufacturing expansion; material deviation in Guinea bauxite supply or Chinese smelter output would warrant model refresh. Practitioners should keep alternative scenarios live as REACH Annex XVII enforcement dates and fluoropolymer coating substitution timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
India Metal Cans Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Metal Aerosol Packaging Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Metal Containers Market