
 Pizza Cartons Market | 2026-2036
Pizza Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Cartons Market Analytics
Consolidation among quick-service pizza chains and delivery aggregator platforms is restructuring procurement dynamics across the pizza cartons value chain. Smurfit Kappa Group leverages its integrated containerboard and converting footprint to secure multi-year supply agreements with top restaurant operators. DS Smith anchors its competitive position through circular-design expertise and lightweight corrugated engineering that reduces logistics costs for high-volume buyers. WestRock Company differentiates via automated packaging line integration and digital print capabilities that support brand customization at scale.
Pizza cartons are corrugated fiberboard or solid-board containers engineered with food-grade liners, grease-resistant coatings, and venting apertures to maintain product temperature, structural integrity, and hygiene during transit from oven to consumer. Regular boxes dominate current volume owing to their compatibility with standard 12-inch and 14-inch pies, while window boxes command premium positioning through enhanced product visibility that drives impulse purchases in retail and supermarket channels. Kraft paper and cardboard substrates lead material demand due to favorable recycling economics and established collection infrastructure, though biodegradable plastics are gaining trial among operators targeting plastic-reduction commitments.
The US FDA governs food-contact substance safety under 21 CFR, while the EPA regulates recycled fiber processing emissions and wastewater discharge from paperboard mills; both frameworks elevate compliance costs for converters serving the pizza segment. The EU F-Gas Regulation and REACH restrictions on certain coatings also shape export-oriented production standards for carton suppliers with cross-border customer bases. Stakeholders must monitor evolving extended producer responsibility mandates and single-use packaging taxes that will determine material substitution timelines and capital allocation priorities across manufacturing networks.
Market Dynamics
Consolidation among quick-service pizza chains and delivery aggregator platforms is restructuring procurement dynamics across the pizza cartons value chain. Large buyers now negotiate multi-year supply agreements that favor converters with integrated containerboard mills and automated converting lines, squeezing smaller regional suppliers out of tier-one procurement tiers.
Growth Catalysts
- Third-party delivery aggregator expansion:Platform consolidation in the United States, Italy, and China is driving carton procurement volumes upward as aggregators standardize packaging specifications across restaurant networks.
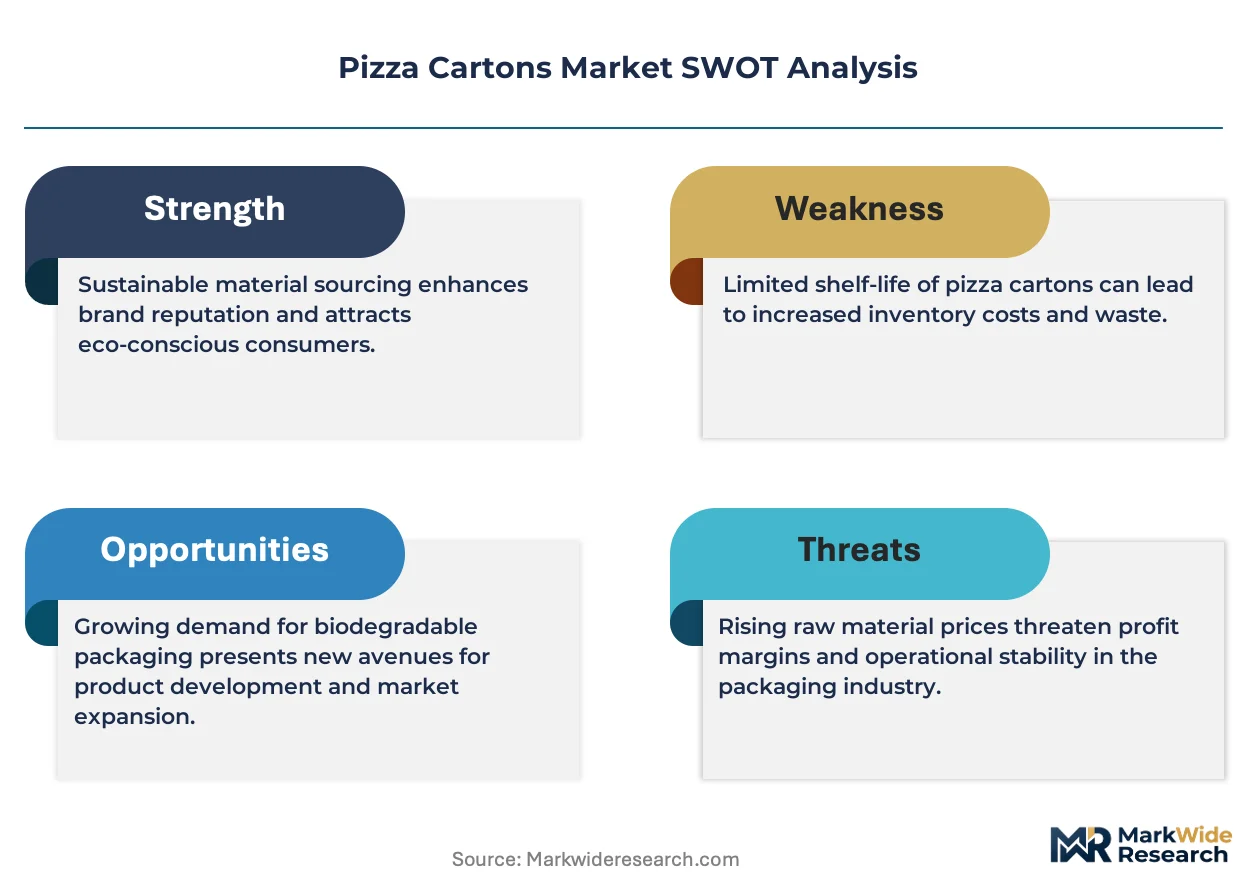
- REACH restrictions on certain coatings:European chemical safety frameworks are accelerating substitution toward water-based barrier coatings that maintain food-contact compliance while reducing environmental liability.
- Lightweight corrugated engineering:Advances in flute profiling and linerboard grammage reduction are cutting logistics costs for high-volume buyers without sacrificing stack strength during delivery operations.
Market Restraints
- Old corrugated container supply volatility:Recycled fiber input costs fluctuate with municipal collection rates and export demand from Asian packaging mills, compressing converter margins unpredictably.
- Grease-resistant coating technical limitations:Current bio-based barrier technologies fail to match polyethylene performance at temperature extremes above 85°C, limiting adoption for ultra-hot delivery segments.
- Extended producer responsibility mandates:Emerging packaging waste fees in multiple jurisdictions are adding compliance overhead before collection infrastructure matures to offset these costs.
Strategic Opportunities
- Biodegradable plastics trial penetration:Operators with plastic-reduction commitments present white-space demand for certified compostable window films and structural reinforcements in premium positioning tiers.
- Digital print capabilities convergence:Integration of inkjet systems with existing corrugating lines enables brand customization at scale without plate changeover downtime, opening short-run seasonal campaigns.
- Supermarket retail channel expansion:Take-and-bake pizza growth in grocery retail is creating demand for window boxes with enhanced visibility that drive impulse purchases at point-of-sale.
Industry Challenges
- Food-contact substance safety certification timelines:FDA notification processes under 21 CFR for novel barrier coatings extend 18-24 months, delaying product launches and freezing formulation pipelines.
- Automated packaging line integration complexity:Retrofitting legacy converting equipment with vision systems and robotic case packers demands capital allocation that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Cartons Market |
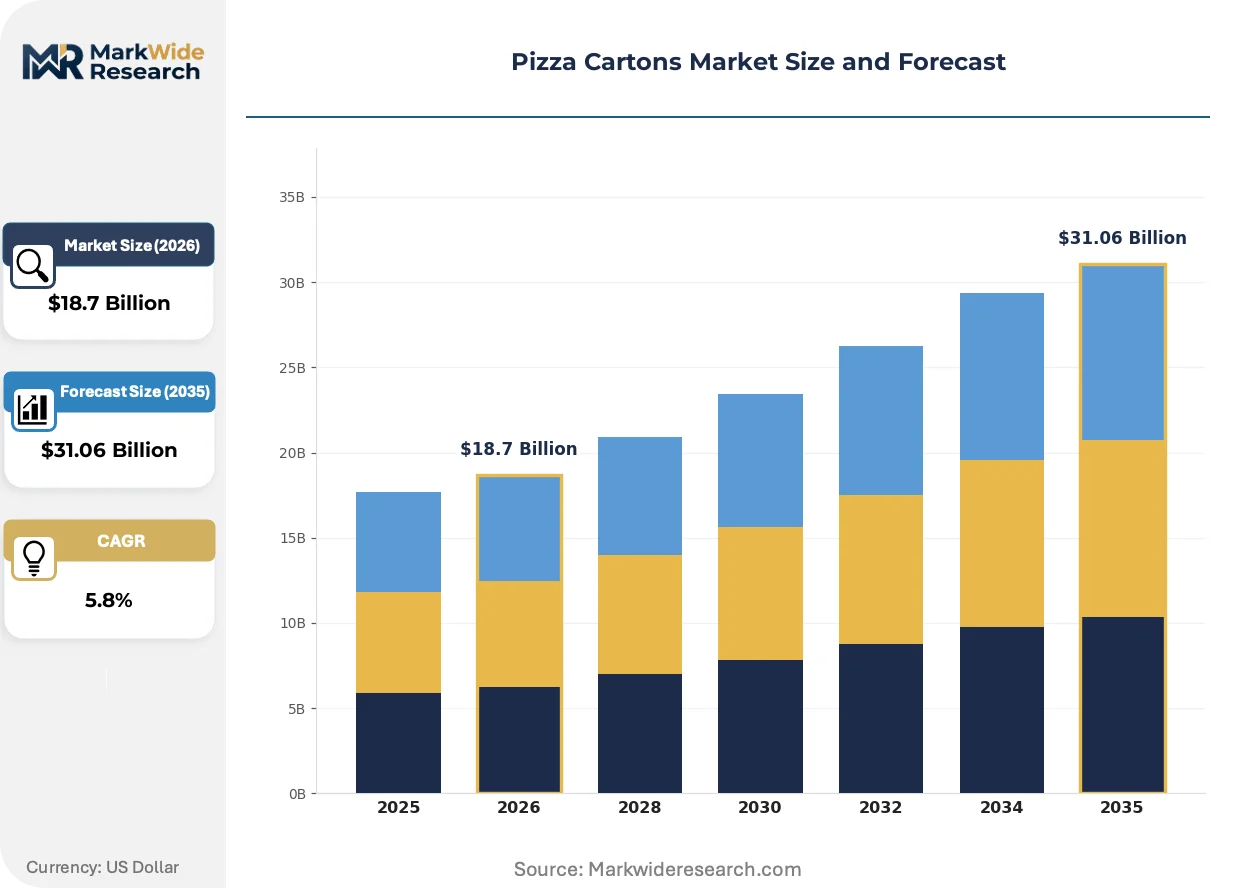
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Boxes, Extra Large Boxes, Stackable Boxes, Window Boxes Material: Cardboard, Biodegradable Plastics, Kraft Paper, PVC Size: 10 Inch, 12 Inch, 14 Inch, 16 Inch End User: Restaurants, Food Trucks, Catering Services, Supermarkets |
| Companies Covered | Smurfit Kappa Group, DS Smith, WestRock Company, International Paper Company, Mondi Group, Huhtamaki Oyj, Georgia-Pacific, New Method Packaging, Pratt Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Cartons Market Evolving Landscape
Active experimentation with material formulations and production workflows is compressing development cycles across the pizza carton supply base. Converters are racing to align product portfolios with tightening food-contact regulations while meeting brand-owner demands for differentiation at the point of delivery.
Smart venting aperture designs are modularizing how thermal management integrates with structural engineering in corrugated pizza packaging. Chain pizzerias operating high-volume delivery fleets are adopting laser-perforated patterns that balance steam release with heat retention. This approach is modularizing the trade-off between product quality preservation and box integrity under stacked loading conditions.
The EU F-Gas Regulation and parallel EPA frameworks on fluorinated substances are forcing systematic reformulation of grease-resistant treatments across export-oriented production lines. Paperboard mills serving cross-border customers must maintain dual certification tracks for PFAS-free and traditional barrier coatings. Small-format urban delivery specialists in Northern Europe are responding fastest, locking in supply agreements with early-adopter converters ahead of 2025 compliance deadlines.
Aggregator platform procurement standardization is compressing supplier diversity among independent pizzerias. Third-party delivery networks in the United States are mandating uniform carton specifications to streamline logistics sorting and brand presentation. This consolidation is most visible in metropolitan markets where platform market penetration exceeds forty percent of total delivery volume.
Pizza Cartons Market Segmentation
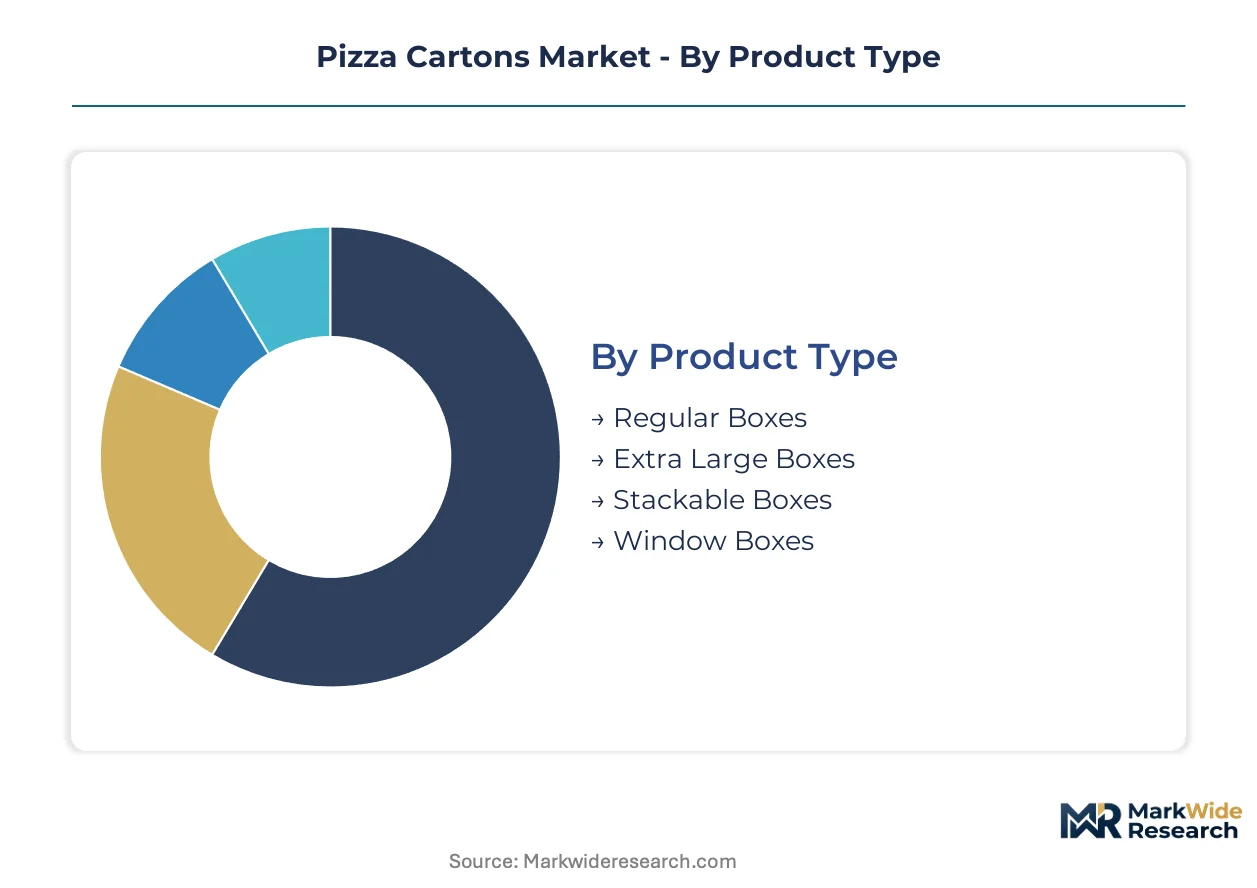
Pizza carton procurement varies sharply by operational context. Chain restaurants demand volume-standardized specifications, while independent operators prioritize flexibility. Material certification requirements and thermal performance thresholds further differentiate segment economics across the value chain.
Product Type:
FDA food-contact notification under 21 CFR applies universally, though window boxes face additional EU F-Gas Regulation scrutiny for film adhesives. Stackable designs trigger structural load-testing protocols that extend certification timelines.
- Regular Boxes:Corrugated fiberboard construction with standard flute profiles dominates procurement volumes. Chain pizzerias in the United States specify these for 12-inch and 14-inch pies, prioritizing compatibility with automated case erectors and thermal retention during 30-minute delivery windows.
- Window Boxes:Die-cut apertures with food-grade PET or PLA films enable product visibility. Supermarket retail channels in Italy and the United States are standardizing these for take-and-bake displays, where impulse conversion rates justify 15-20% packaging cost premiums.
- Extra Large Boxes:Heavy-duty board grades with reinforced corners accommodate party-size pies and sheet pizzas.
- Stackable Boxes:Interlocking tab designs and vented lids optimize multi-order delivery logistics for aggregator platforms.
Regular Boxes sit at the top of the volume ranking, with Window Boxes climbing the fastest.
Material:
Cost tiers separate segments by raw material input volatility and recycling infrastructure dependency. Kraft paper and cardboard leverage established OCC collection streams, while biodegradable plastics carry composting certification premiums.
- Cardboard:Recycled-content corrugated board with clay-coated liners provides grease resistance through polyethylene extrusion. United States converters favor this substrate for its compatibility with existing flexographic print lines and established FDA GRAS status for food-contact applications.
- Kraft Paper:Unbleached virgin or recycled fiber with natural aesthetic positioning. European operators targeting plastic-reduction commitments specify kraft for premium positioning, though moisture sensitivity limits hot-holding duration compared to polymer-barrier alternatives.
- Biodegradable Plastics:PLA and PHA formulations certified to ASTM D6400 or EN 13432 for industrial composting.
- PVC:Rigid or semi-rigid applications limited by regulatory pressure and recycling challenges.
Cardboard commands the dominant share of procurement spend, while Biodegradable Plastics are expanding most quickly among sustainability-focused operators.
Size:
Volume concentration tracks pizza format standardization across major consuming markets. Dimensional uniformity enables logistics optimization for third-party delivery platforms.
- 12 Inch:The reference specification for individual and small-group orders. United States chain operators specify this as the baseline format, with carton interior dimensions calibrated to prevent pie movement while minimizing material usage per unit.
- 14 Inch:Family-size format with growing share in catering and group delivery segments. Chinese aggregator platforms are standardizing 14-inch specifications for shared-order economics in dense urban markets.
- 10 Inch:Personal-size and snack formats for quick-service and convenience channels.
- 16 Inch:Extra-large party formats with limited but stable demand from event catering.
12 Inch maintains the highest shipment volumes, with 14 Inch gaining share fastest in aggregator-dominated metropolitan markets.
End User:
Customer type determines specification complexity, order frequency, and brand customization requirements. Direct-operated chains negotiate multi-year supply agreements, while fragmented independents purchase through distribution intermediaries.
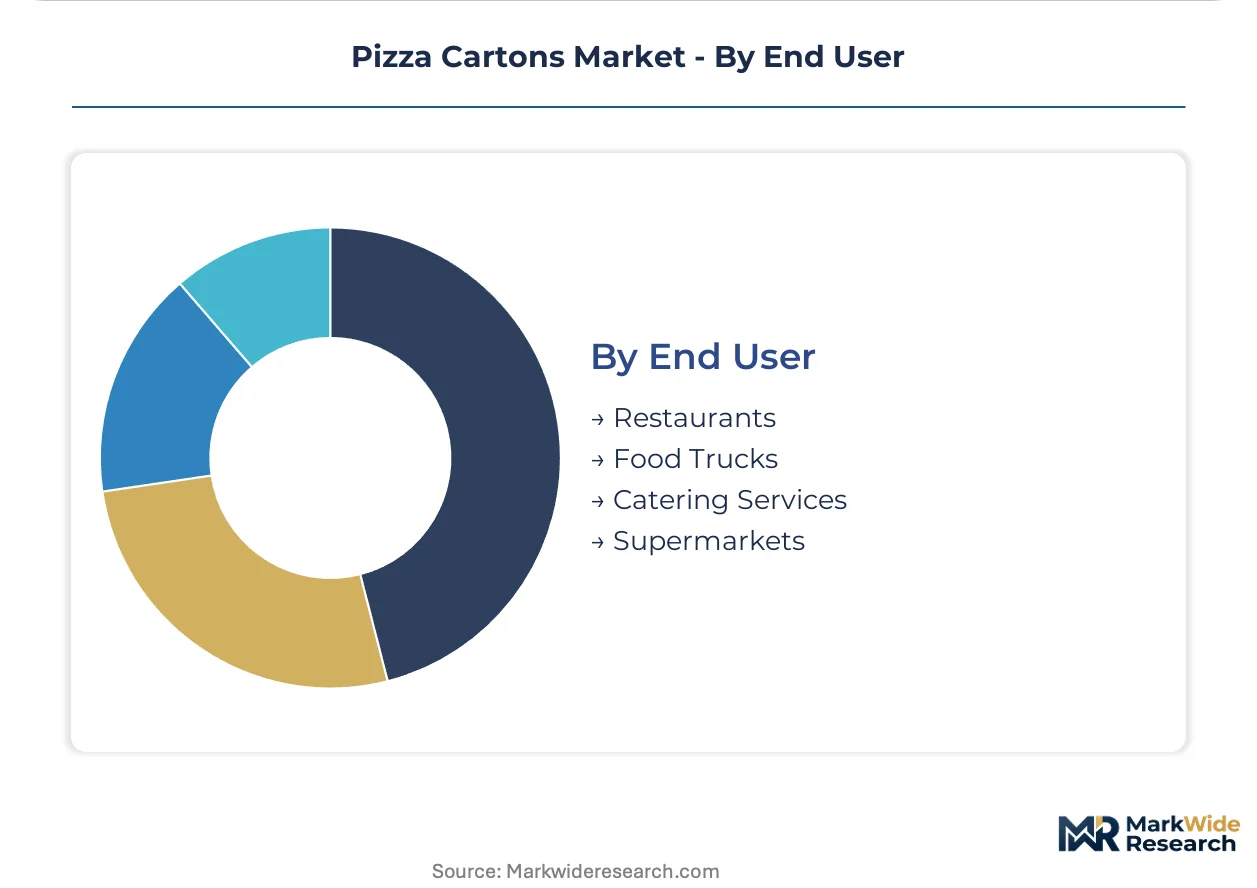
- Restaurants:Full-service and quick-service pizza operators with the most sophisticated packaging requirements. Major United States chains specify custom-printed cartons with integrated QR codes and thermal management features, locking in supply agreements with converters offering automated packaging line integration.
- Supermarkets:Retail grocery channels with distinct visibility and shelf-life priorities. Take-and-bake programs in Italy and the United States are driving adoption of window boxes with modified atmosphere compatibility and prominent brand paneling.
- Food Trucks:Mobile operators with space-constrained storage and high-turnover service models.
- Catering Services:Event-focused operators with bulk-order economics and transport durability requirements.
Restaurants anchor procurement volumes, with Supermarkets representing the steepest expansion trajectory as retail pizza penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Italy diverge sharply in carton specification complexity despite comparable per-capita pizza consumption, with American operators prioritizing automated line compatibility while Italian buyers emphasize retail visibility features.
United States
Chain pizzerias and third-party delivery platforms drive procurement volumes through multi-year supply agreements. FDA notification processes under 21 CFR govern food-contact substance safety, extending certification timelines for novel barrier coatings. The Midwest and Southeast manufacturing corridors host integrated containerboard mills serving quick-service restaurant networks.
Italy
Take-and-bake retail expansion in supermarket channels accelerates demand for window boxes with enhanced product visibility. EU F-Gas Regulation and REACH restrictions shape coating formulations for export-oriented production. Northern industrial clusters around Milan and Bologna concentrate converting capacity for premium positioning tiers.
China
Aggregator platform standardization in dense urban markets drives 14-inch carton adoption for shared-order economics. SAMR food-contact material standards and GB technical regulations establish compliance baselines for domestic and export production. Yangtze River Delta manufacturing zones supply both domestic delivery networks and international buyers.
Germany
Small-format urban delivery specialists lock in PFAS-free coating supply agreements ahead of 2025 compliance deadlines. ECHA chemical safety frameworks accelerate water-based barrier substitution across paperboard mills. Industrial converting capacity concentrates in North Rhine-Westphalia and Baden-Württemberg.
United Kingdom
Supermarket retail channel penetration for chilled pizza creates demand for modified-atmosphere compatible cartons. Extended producer responsibility mandates and packaging waste fees add compliance overhead for converters. Manufacturing activity clusters in the Midlands and Northwest England near recycled fiber collection infrastructure.
Pizza Cartons Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement categories. The vendor base organizes around three strategic archetypes: integrated containerboard-to-converting operators, standalone specialty converters, and diversified packaging conglomerates with multi-material portfolios. Dominant competitive moves include backward integration into recycled fiber processing and strategic partnerships with automated packaging line integrators.
Among Ireland-based integrated operators, Smurfit Kappa Group occupies a position exemplifying captive containerboard supply advantages. DS Smith represents the circular-design specialist archetype within UK-headquartered competitors. WestRock Company anchors the North American diversified conglomerate tier. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors across procurement tiers.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith |
| WestRock Company |
| International Paper Company |
| Mondi Group |
| Huhtamaki Oyj |
| Georgia-Pacific |
| New Method Packaging |
| Pratt Industries |
| Others |
Value Network & Pricing Analysis
Captive containerboard supply from integrated mills in the United States and Ireland anchors converter pricing power against recycled fiber volatility. This upstream control insulates tier-one suppliers from OCC spot-market swings while squeezing standalone converters into commodity-margin tiers.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for PFAS-free barrier coatings as mills compete for early-adopter premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and volume commitment, with FDA food-contact notification status commanding sustained premiums. Pricing pressure stems from aggregator platform procurement standardization that consolidates buyer power in metropolitan markets. Independent pizzerias exhibit highest price sensitivity due to fragmented purchasing volumes, while chain operators trade price for supply security and automated line compatibility.
Supply Chain Analysis
Workforce availability constraints in the Midwest United States and Northern Italy manufacturing corridors are tightening operational flexibility at integrated mills. Supply concentrates in the United States, China, and Germany as these geographies host both containerboard production and high-volume converting capacity. Raw material dependencies center on old corrugated container streams, virgin kraft pulp, and water-based barrier chemicals. Single-source vulnerability runs through Asian OCC export demand fluctuations that destabilize recycled fiber input costs. Distribution runs through direct mill-to-chain agreements for tier-one buyers and distribution intermediaries for fragmented independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pizza cartons market reads as a late-cycle quality story where chain pizzerias and supermarket retailers are shifting procurement toward premium specifications with enhanced thermal management and retail visibility features.
For Market Incumbents: Anticipate regulatory compression on PFAS-containing coatings by accelerating water-based barrier certification timelines ahead of EPA and EU F-Gas deadlines. Defensive consolidation into automated packaging line integration capabilities protects against emerging pure-play digital print specialists. Backward integration into recycled fiber processing secures margin control against OCC export demand volatility from Asian packaging mills.
For New Entrants and Emerging Players: Supermarket retail channel partners represent the most penetrable entry vector given take-and-bake expansion and window box specification gaps among incumbent converters. Target white-space demand in biodegradable plastic window films for sustainability-committed operators in Northern Europe. A go-to-market angle anchored in short-run digital print capabilities for seasonal campaigns bypasses incumbent plate-changeover advantages.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier specialty converters because aggregator platform standardization is displacing fragmented independents into supplier consolidation. Long-term viability hinges on captive containerboard supply or differentiated coating certification tracks. The signal to watch is PFAS-free coating capacity utilization rates as a leading indicator of regulatory compliance-driven supplier switching.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Certification | EPA and EU F-Gas deadlines are forcing systematic barrier reformulation across export-oriented production lines. |
| Automated Packaging Line Integration | Vision systems and robotic case packers lock in multi-year supply agreements with high-volume chain operators. |
| Digital Print Capability Investment | Inkjet integration with corrugating lines enables brand customization without plate changeover downtime penalties. |
| Recycled Fiber Processing Control | Captive OCC supply insulates converter margins from Asian export demand volatility and collection rate fluctuations. |
| Supermarket Retail Channel Expansion | Take-and-bake growth in Italy and the United States drives window box demand with modified atmosphere compatibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging procurement managers at quick-service chains, corrugated mill operations directors, and third-party delivery platform supply chain leads with secondary validation. Regulatory filings from the FDA and EPA, trade data on old corrugated container flows, and SEC disclosures from integrated packaging conglomerates anchored the data foundation. Bottom-up volume modeling triangulated against top-down market sizing across product type, material, size, and end-user segments.
Segment-weighting approaches distributed value and volume across regular boxes, window boxes, and stackable designs by end-user procurement tier. Modeled dimensions included chain versus independent operator purchasing patterns, automated line compatibility requirements, and retail versus delivery channel specifications. CAGRs derived from historical shipment correlations with pizza consumption indices and delivery platform penetration rates. Forecast inputs incorporated recycled fiber price elasticity and regulatory compliance timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to extended producer responsibility mandate implementation timelines and biodegradable plastic composting infrastructure buildout. Assumptions reflect current regulatory trajectories and platform consolidation patterns. Material deviation in PFAS regulatory enforcement or aggregator platform market share thresholds warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Pick and Place Carton Packers Market
Cartons
Carton Bottle Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Mailers Market
Cartons
Cupcake Box Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Tuck Top Box Market
Cartons
Litho Laminated Cartons Market
Cartons
XXL Packaging Market
Cartons
Liquid Packaging Cartons Market
Cartons
Pulp Roll Cradles Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Luxury Folding Carton Market
Cartons
Child-Resistant Carton Box Market
Cartons
Soap Boxes Market