
 Africa Folding Carton Market | 2026-2036
Africa Folding Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Folding Carton Market Outlook
The gap between premium coated cartons and commodity recycled board is expanding across African consumer markets. Shave & Gibson leverages its Southern African manufacturing footprint to dominate high-margin personal care contracts. AR Packaging Nigeria Ltd anchors supply for Lagos-based beverage bottlers through localized converting capacity. Nampak Limited competes across both tiers, sustaining volume leadership in standard cartons while extending R&D into barrier-coated structures for dairy and juice applications.
Africa folding cartons are paper-based packaging containers produced from folding boxboard or solid bleached sulfate board, typically 200-400 gsm, formed by creasing, cutting, and gluing flat blanks into rigid rectangular containers for retail shelf display and product protection. Die-cut cartons lead growth in healthcare and electronics segments where precise dimensional tolerances and tamper-evident closures command premium positioning. Recycled paperboard occupies the volume base across food & beverage wholesale channels, while coated paperboard captures margin pools in personal care and premium retail where print fidelity and surface aesthetics drive brand differentiation.
South Africa's Department of Forestry, Fisheries and the Environment applies extended producer responsibility frameworks that mandate recycling targets for paper packaging producers, while Nigeria's Standards Organisation of Nigeria enforces cartonboard hygiene standards for food-contact applications. Kenya's National Environment Management Authority is drafting similar packaging waste regulations that will reshape compliance costs for converters serving East African markets. Stakeholders must monitor how divergent national enforcement timelines affect cross-border supply chain planning and capital allocation across the continent's fragmented regulatory landscape.
Market Dynamics
Extended producer responsibility enforcement across Southern and West Africa is restructuring converter economics and recycling infrastructure investments. South Africa's Department of Forestry, Fisheries and the Environment mandates paper packaging recovery targets that cascade through supply chains into Nigeria and Kenya.
Growth Catalysts
- Lagos beverage bottling corridor:Nigeria's concentrated soft drink and beer production generates sustained carton demand from international bottlers seeking localized packaging supply.
- Barrier-coated board adoption:Dairy and juice processors across Gauteng and Western Cape are specifying liquid packaging board with polyethylene barriers to extend shelf life without refrigeration.
- Extended producer responsibility frameworks:South Africa's recycling mandates are forcing brand owners to source certified recycled content, creating pull-through demand for compliant converters.
Market Restraints
- Pulp price volatility:Folding boxboard converters face margin compression when global hardwood pulp prices spike, with limited pass-through power against multinational FMCG procurement teams.
- Coated paperboard supply concentration:Premium SBS board for personal care applications relies on imports from European and Asian mills, exposing African converters to currency and shipping cost swings.
- Recycled fiber quality inconsistency:Local recovered paper streams contain high contamination rates that limit mechanical pulp yield and print surface uniformity.
Strategic Opportunities
- Kenya's regulatory preparation:The National Environment Management Authority's draft packaging waste rules will create first-mover advantage for converters establishing recycling partnerships before enforcement begins.
- Die-cut healthcare cartons:Pharmaceutical serialization requirements and tamper-evident specifications are opening premium niches for converters with precision cutting and cold-foil stamping capabilities.
- E-commerce ready packaging:Direct-to-consumer beauty brands in Johannesburg and Cape Town are specifying ship-ready cartons that eliminate secondary boxing, merging retail presentation with logistics protection.
Industry Challenges
- Prepress technician scarcity:Advanced color management and expanded gamut printing require skills that outpace vocational training output in Lagos and Nairobi converter clusters.
- Food-contact certification timelines:Standards Organisation of Nigeria hygiene audits for dairy and beverage cartons create 4-6 month approval delays that mismatch just-in-time procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Folding Carton Market |
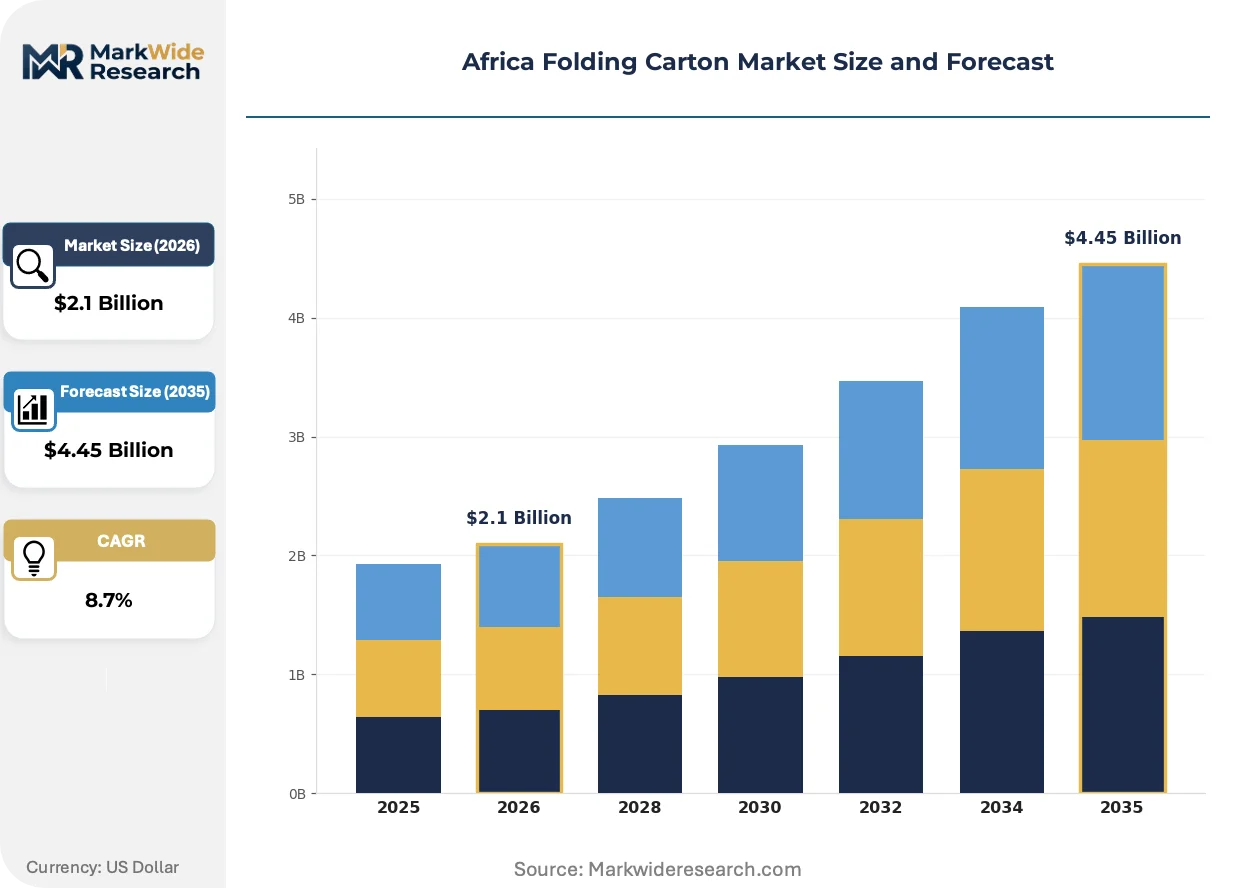
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cartons, Die-Cut Cartons, Retail Cartons, DISPLAY Cartons End User: Food & Beverage, Healthcare, Personal Care, Consumer Electronics Material: Recycled Paperboard, Coated Paperboard, Kraft Paperboard, Polyethylene-Laminated Paperboard Distribution Channel: Direct Sales, Wholesalers, E-Commerce, Retail Stores |
| Companies Covered | Shave & Gibson, AR Packaging Nigeria Ltd, CTP Cartons and Label, Catron Manufacturer Limited, Atlas Packaging, Kemtek, Britepak, Nampak Limited, Masterpack Cape, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Folding Carton Market Strategic Shifts
Digital print integration and barrier coating advances are compressing minimum order quantities while extending product protection capabilities. Converter investment patterns reveal a pivot toward flexible manufacturing systems.
Water-based barrier coatings are modularizing the traditional liquid packaging value chain. These formulations replace extruded polyethylene with spray-applied or curtain-coated moisture barriers that run on standard folding carton lines. Nigerian juice processors and Kenyan dairy cooperatives are piloting specifications that accept 12-18 month shelf life from coated SBS rather than multi-material laminates. The technology is modularizing converter asset utilization by allowing single presses to switch between dry and liquid food applications without dedicated extrusion equipment.
South Africa's extended producer responsibility regulations are mandating recycled content thresholds and recovery rate targets for paper packaging. Brand owners must now fund or operate collection and reprocessing infrastructure to maintain market access. Dairy and beverage cartons face the steepest compliance costs due to multi-material construction, pushing converters toward mono-material barrier designs that simplify pulping and fiber recovery.
Brand owners in Lagos and Johannesburg are consolidating carton procurement under direct supplier relationships that bypass traditional merchant distributors. Multinational FMCG procurement teams now specify print quality, barrier performance, and recycling compliance in unified tenders rather than sourcing commodity board and converting services separately. Personal care and premium food segments in Cape Town and Abuja are driving this consolidation fastest, where brand equity sensitivity rewards tight quality control over transactional cost minimization.
Africa Folding Carton Market Segmentation
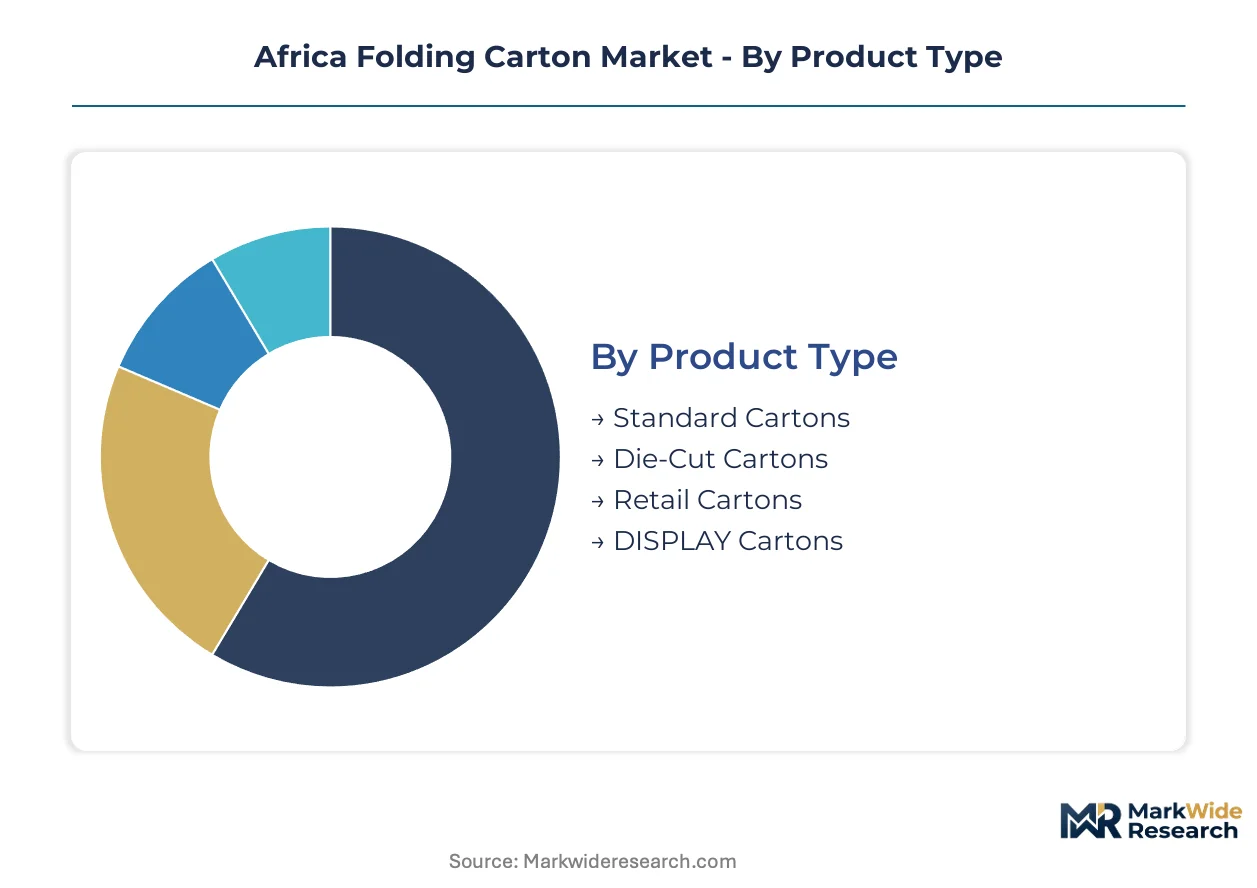
Converter investment decisions across Africa hinge on matching carton specifications to end-use shelf-life requirements and retail channel formats. Each segmentation dimension reveals distinct margin structures and capital intensity profiles that shape competitive positioning.
Product Type:
Upgrade cycles in beverage and pharmaceutical packaging are shortening as brand owners specify precision-formed cartons with integrated tamper-evidence and premium print surfaces.
- Standard Cartons:These rectangular folding boxes use 200-350 gsm paperboard with standard crease patterns for dry goods and ambient beverages. Nigerian flour millers and South African maize meal packers specify these for cost-sensitive retail channels where protection requirements remain basic.
- Die-Cut Cartons:Precision-engineered blanks with custom perforations and window apertures enable pharmaceutical blister packs and electronics accessories to achieve retail differentiation. Johannesburg-based healthcare converters report rising specifications for serialization-ready cartons with integrated tear strips.
- Retail Cartons:Shelf-ready designs with integrated handles and stacking features serve Lagos supermarket chains and Cape Town convenience store networks.
- Display Cartons:Point-of-sale units with reinforced bases and header cards anchor promotional campaigns for seasonal beverages and personal care launches across Abuja and Nairobi retail corridors.
Standard Cartons sits at the top of the volume ranking, with Die-Cut Cartons climbing the fastest.
End User:
Cost tier stratification separates commodity converters serving bulk food distributors from specialists capturing premium personal care and healthcare contracts.
- Food & Beverage:Dairy processors across Gauteng and Western Cape specify barrier-coated board for extended shelf life, while Nigerian juice bottlers drive volume through recycled-content cartons for ambient distribution.
- Healthcare:Cold-chain pharmaceutical distribution in South Africa demands cartons with moisture barriers and child-resistant closures. Serialization mandates from the national health regulator are pushing converters toward precision die-cutting capabilities.
- Personal Care:Premium cosmetic brands in Cape Town and Lagos specify coated SBS board with foil stamping and embossed logos to command retail shelf presence.
- Consumer Electronics:Smartphone accessories and small appliance packaging across Nairobi and Johannesburg require anti-static coatings and precise fitments to protect sensitive components.
Food & Beverage commands absolute volume leadership, though Healthcare demonstrates the steepest expansion trajectory as regulatory compliance deepens.
Material:
Application-specific performance requirements dictate material selection, with liquid food and premium personal care segments accepting cost premiums for barrier functionality.
- Recycled Paperboard:Post-consumer fiber content averaging 80-100% serves dry food wholesalers and ambient beverage distributors across Nigeria's northern states. South Africa's extended producer responsibility mandates are tightening specifications for contamination rates and print surface uniformity.
- Coated Paperboard:Solid bleached sulfate board with clay or polymer coatings delivers the print fidelity and surface aesthetics that personal care brands in Lagos and Abuja require for premium positioning.
- Kraft Paperboard:Unbleached natural fiber board appeals to organic food marketers and sustainable packaging claims in Cape Town's specialty retail channels.
- Polyethylene-Laminated Paperboard:Extruded or spray-applied moisture barriers enable dairy and juice applications without dedicated liquid packaging lines, modularizing converter asset utilization across Kenyan and Nigerian plants.
Recycled Paperboard retains volume dominance, while Polyethylene-Laminated Paperboard gains share fastest as dairy processors seek shelf-life extension without refrigeration infrastructure.
Distribution Channel:
Customer type fragmentation separates multinational procurement teams from fragmented wholesale and retail buyer bases with divergent service expectations.
- Direct Sales:Multinational FMCG procurement teams in Lagos and Johannesburg consolidate carton sourcing under unified tenders specifying print quality, barrier performance, and recycling compliance. These relationships bypass traditional merchant distributors and demand dedicated account management.
- Wholesalers:Regional paper merchants aggregate demand from small and mid-sized food processors across Nigeria's secondary cities and Kenya's agricultural belts, accepting standard specifications with shorter lead times.
- E-Commerce:Direct-to-consumer beauty brands in Johannesburg specify ship-ready cartons that merge retail presentation with logistics protection, eliminating secondary boxing costs.
- Retail Stores:Independent supermarkets and convenience chains in Nairobi and Accra source through local converting jobbers with limited technical specification capabilities.
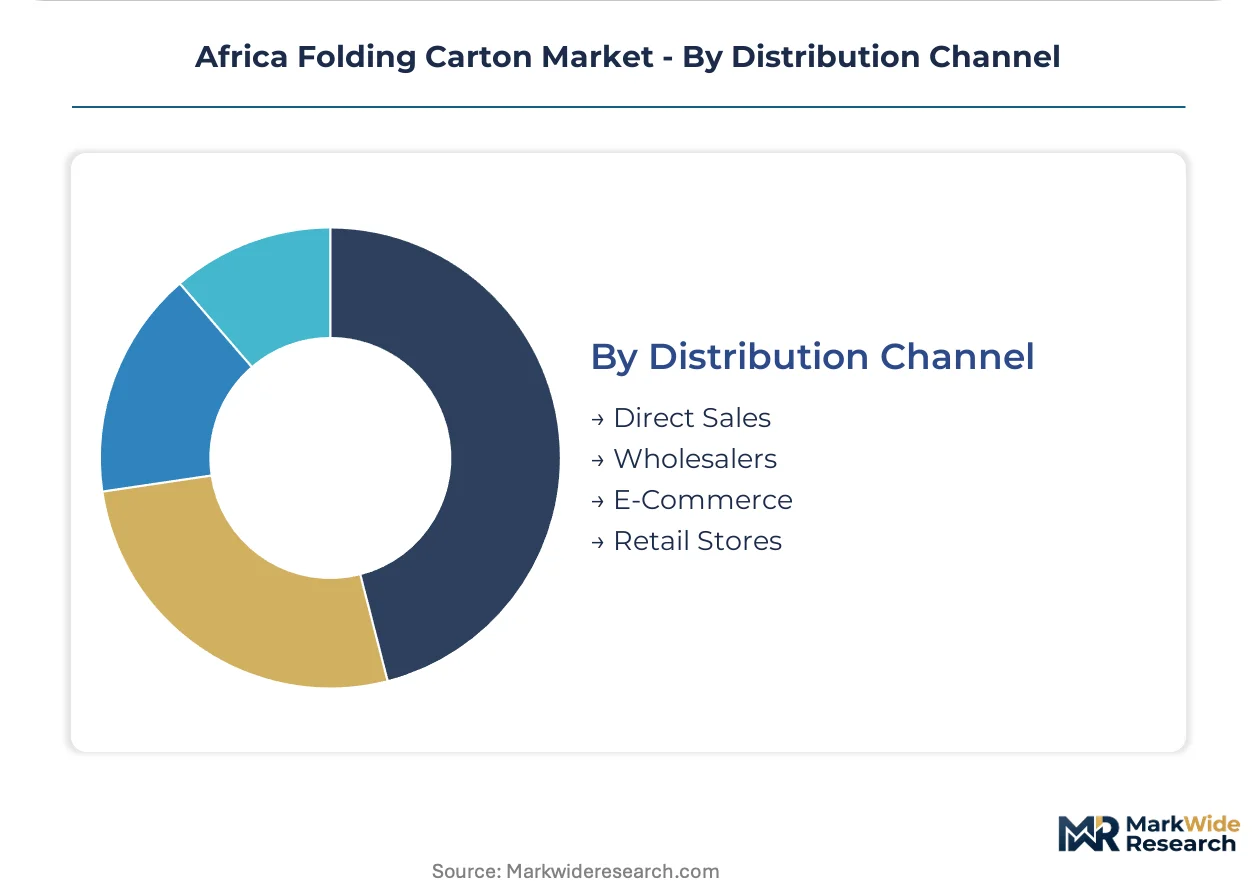
Direct Sales anchors the revenue base, with E-Commerce expanding most quickly as digital-native brands scale across Southern and West African urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter talent clusters in Lagos, Johannesburg, and Nairobi anchor Africa's folding carton capacity. Technical prepress and die-cutting specialists concentrate in these nodes, creating localized ecosystems that serve surrounding demand basins.
Nigeria
Lagos beverage bottlers and flour millers drive carton consumption across West Africa. The Standards Organisation of Nigeria enforces hygiene certification for food-contact packaging, creating 4-6 month approval timelines. The Lagos industrial corridor hosts converting capacity serving international soft drink and beer producers.
South Africa
Gauteng dairy processors and Western Cape juice manufacturers specify barrier-coated board for shelf-life extension. The Department of Forestry, Fisheries and the Environment mandates extended producer responsibility recycling targets for paper packaging. Johannesburg and Cape Town converter clusters dominate high-margin personal care and pharmaceutical contracts.
Kenya
Nairobi-based dairy cooperatives and agricultural processors generate demand for liquid packaging alternatives. The National Environment Management Authority is drafting packaging waste regulations that will reshape compliance costs. The Rift Valley and Central Province dairy belts are piloting water-based barrier coatings on standard folding carton lines.
Egypt
Cairo pharmaceutical distributors and Alexandria food processors import coated board for premium applications. The country's national environmental regulator is developing waste management frameworks for paper-based packaging. The Greater Cairo industrial zone concentrates converting activity serving North African export markets.
Ghana
Accra consumer goods distributors and Tema port logistics operators handle transit carton volumes for regional re-export. Ghana's national standards authority applies food-contact packaging rules aligned with West African harmonization efforts. The Tema free zone hosts converting operations targeting Sahel market access.
Africa Folding Carton Market Competitive Environment
Capital-heavy integrated producers compete with asset-light converting specialists across Africa's fragmented carton supply base. The market structures around three tiers: multinational packaging groups with captive pulp and board supply, regional converters with localized finishing capacity, and merchant distributors aggregating imported board for small-batch jobbing. Strategic differentiation centers on barrier coating capabilities and recycling compliance certification rather than scale alone. Consolidation pressure is accelerating as brand owners unify procurement under direct supplier relationships.
Among Southern African integrated producers, Nampak Limited occupies a position spanning commodity volume and premium barrier-coated development. West African converting capacity anchors around AR Packaging Nigeria Ltd, which exemplifies localized supply relationships with Lagos beverage bottlers. Shave & Gibson represents the specialist tier, concentrating on high-margin personal care contracts through precision finishing capabilities. These three archetypes capture distinct margin pools as regulatory compliance and print quality requirements stratify procurement decisions.
| Leading Market Players |
|---|
| Shave & Gibson |
| AR Packaging Nigeria Ltd |
| CTP Cartons and Label |
| Catron Manufacturer Limited |
| Atlas Packaging |
| Kemtek |
| Britepak |
| Nampak Limited |
| Masterpack Cape |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters across Lagos and Johannesburg anchor supply discipline through generational capital allocation patterns that resist short-term margin erosion. Their ownership structure sustains patient pricing power against multinational FMCG procurement teams while limiting aggressive capacity expansion that would destabilize regional board markets.
Pricing Analysis
Board-plus-converting service bundles dominate procurement relationships with Lagos beverage bottlers and Gauteng dairy processors, while unbundled merchant board sales persist for smaller Nigerian flour millers and Kenyan agricultural cooperatives. Price differentiation hinges on barrier coating certification tiers and volume scale commitments, with personal care brands in Cape Town accepting substantial premiums for foil-stamped SBS board. Cost compression in recycled-content tiers is intensifying because South Africa's extended producer responsibility mandates force converters to absorb collection infrastructure investments. Small-batch jobbing customers in Nairobi's independent retail sector exhibit the highest price sensitivity, while multinational pharmaceutical serialization contracts show minimal elasticity.
Supply Chain Analysis
Dual-sourcing qualification requirements from Nigerian and South African brand owners mandate converters maintain relationships with both European SBS mills and Asian folding boxboard suppliers. Geographic supply concentration centers on Finland and Sweden for premium coated grades, China and Indonesia for volume board, and local Southern African recycled fiber operations. Raw material dependencies include hardwood pulp, kaolin clay coatings, and polyethylene barrier resins. Single-source vulnerability from concentrated European SBS supply exposes African converters to euro currency swings and maritime logistics disruptions. Distribution runs through direct mill relationships for multinational accounts and regional paper merchants aggregating fragmented SME demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where South Africa's extended producer responsibility enforcement creates structural demand for certified recycled content and compliance-capable converter capacity.
For Market Incumbents: Cement barrier coating R&D leadership through dedicated liquid packaging board lines serving Gauteng dairy processors, while acquiring distressed converting assets in Nigeria's northern states to preempt emerging regional specialists. Nampak Limited's integrated pulp-to-carton model demonstrates how captive fiber supply defends margin position against imported board price volatility. For New Entrants and Emerging Players: Enter via water-based barrier coating retrofit partnerships with Kenyan dairy cooperatives in the Rift Valley, where regulatory preparation by the National Environment Management Authority has not yet attracted established converter investment. Target pharmaceutical serialization-ready die-cut capacity in Johannesburg, where cold-chain distribution expansion outpaces local precision finishing supply. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light Lagos converting specialists with entrenched beverage bottler relationships but limited barrier coating capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Watch for Kenya's packaging waste regulation finalization as the signal triggering consolidation premiums for early recycling partnership entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Line Investment | Gauteng dairy processors specify liquid packaging board for ambient distribution without refrigeration infrastructure. |
| Recycling Partnership Formation | South Africa's Department of Forestry, Fisheries and the Environment mandates recovery targets that reshape converter economics. |
| Pharmaceutical Serialization Capability | South Africa's national health regulator drives demand for precision die-cutting and tamper-evident carton specifications. |
| Direct Sales Channel Expansion | Multinational FMCG procurement teams in Lagos consolidate sourcing under unified quality and compliance tenders. |
| Water-Based Barrier Pilot Programs | Kenyan dairy cooperatives in the Rift Valley test spray-applied moisture barriers on standard folding carton lines. |
Study Parameters
Bottom-up food and beverage end-use modeling reconciled against top-down pulp and board supply tracking forms the analytical core of this study. Primary interviews with converter operations managers, multinational FMCG procurement directors, dairy processor packaging engineers, and Standards Organisation of Nigeria certification auditors combined with secondary validation from customs import records, forestry department recycling compliance filings, and folding boxboard mill capacity disclosures. Trade flow analysis from European and Asian export statistics triangulates against domestic production estimates from South African integrated paper groups.
Historical trendline analysis of carton consumption against beverage production volumes and pharmaceutical distribution expansion established baseline growth coefficients across the projection horizon. Segmentation dimensions modeled include product type precision requirements, end-use shelf-life specifications, material barrier functionality tiers, and distribution channel consolidation patterns. CAGRs were derived from regression-weighted capacity utilization trajectories and brand owner procurement cycle analysis, with pulp price elasticity and regulatory compliance cost curves as industry-specific forecast inputs.
Inputs from forestry department enforcement schedules and standards organization certification timelines were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term supply-demand balance assumptions. Deviation in Kenya's packaging waste regulation implementation timeline or Nigerian naira volatility against euro-denominated SBS board contracts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Pick and Place Carton Packers Market
Cartons
Fully Enclosed Cartons Market
Cartons
Beverage Cartons Market
Cartons
Carton Sealer Market
Cartons
End Load Cartoning Machine Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Tetrahedron Carton Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Interlocking Boxes Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
MET-PET Cartons Market
Cartons
Europe Corrugated Box Market
Cartons
Brick Liquid Carton Market
Cartons
Child-Resistant Carton Box Market
Cartons
XXL Packaging Market