
 Shrink Sleeve Labels Market | 2026-2036
Shrink Sleeve Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Sleeve Labels Market Outlook
North American film extruders is pivoting toward PETG-dominant output to serve heat-sensitive container markets. Avery Dennison leverages its pressure-sensitive heritage to extend coating chemistry into sleeve-compatible adhesives. CCL Industries anchors North American supply through integrated sheet extrusion and printing assets. Fuji Seal International dominates Asian beverage sleeve contracts through localized gravure cylinder networks.
Shrink sleeve labels are cylindrical polymer films, typically 40–70 micron PETG or PVC, that contract radially when exposed to controlled heat steam tunnels to conform tightly to irregular container geometries. Their primary commercial purpose is to deliver full-body decorative coverage, tamper-evident seals, and multi-pack bundling across rigid packaging formats. PETG substrates lead value contribution due to superior shrink clarity and recycling compatibility, while digital printing technology captures the fastest expansion as brand owners shorten run lengths and demand versioning flexibility. Food and Beverage end users occupy the largest volume pool, though Pharmaceutical applications sustain premium margin tiers through serialization and anti-counterfeiting integration.
FDA regulates indirect food-contact substrates under 21 CFR 177.1630, compelling resin purity and migration testing that shapes supplier qualification timelines. ECHA REACH restrictions on chlorinated materials and plasticizers are accelerating PVC displacement across European personal care lines. China's SAMR enforces GB standards for packaging material safety that condition import access for foreign film suppliers. Stakeholders must monitor regulatory divergence between biodegradability mandates and functional performance requirements as substrate selection decisions carry multi-year equipment lock-in consequences.
Market Dynamics
Beverage bottlers are consolidating procurement around sleeve-compatible PETG substrates as 360-degree branding requirements collide with EU REACH chemical phase-outs, forcing substrate selection decisions that lock in equipment configurations for multi-year horizons.
Growth Catalysts
- REACH Article 57 SVHC restrictions:ECHA's tightening controls on chlorinated plasticizers are accelerating PVC displacement across European personal care packaging lines, opening volume to PETG alternatives.
- Digital gravure hybridization:Shorter run lengths and SKU proliferation among craft beverage producers are pulling investment toward digitally-enabled sleeve printing assets.
- Contract packaging clusters:Concentrated bottling infrastructure in Germany, China, and the United States generates localized demand density that justifies dedicated sleeve extrusion capacity.
Market Restraints
- Resin feedstock volatility:Purified terephthalic acid and ethylene glycol spot pricing swings compress PETG margin predictability for film extruders.
- Steam tunnel capital intensity:Heat-shrink application equipment requires substantial facility retrofitting that bottlers defer during capacity expansion cycles.
- Mechanical recycling incompatibility:Multi-layer sleeve constructions and adhesive chemistries complicate sortation at materials recovery facilities, creating post-consumer collection friction.
Strategic Opportunities
- Pharmaceutical serialization integration:Track-and-trace mandates under FDA DSCSA and EU Falsified Medicines Directive are creating premium sleeve segments combining tamper evidence with variable data printing.
- India contract manufacturing expansion:Emerging beverage and personal care bottling clusters in Maharashtra and Gujarat remain underpenetrated by sleeve-qualified suppliers.
- Bio-based PETG development:Renewable feedstock pathways using bio-para-xylene are enabling carbon accounting claims that align with EU Green Deal procurement criteria.
Industry Challenges
- Gravure cylinder lead times:Skilled engraving capacity scarcity extends pre-press timelines for high-volume beverage contracts, compressing production windows.
- Cross-functional color management:Sleeve-to-bottle hue matching requires coordination between extrusion, printing, and container molding operations that many converters lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Sleeve Labels Market |
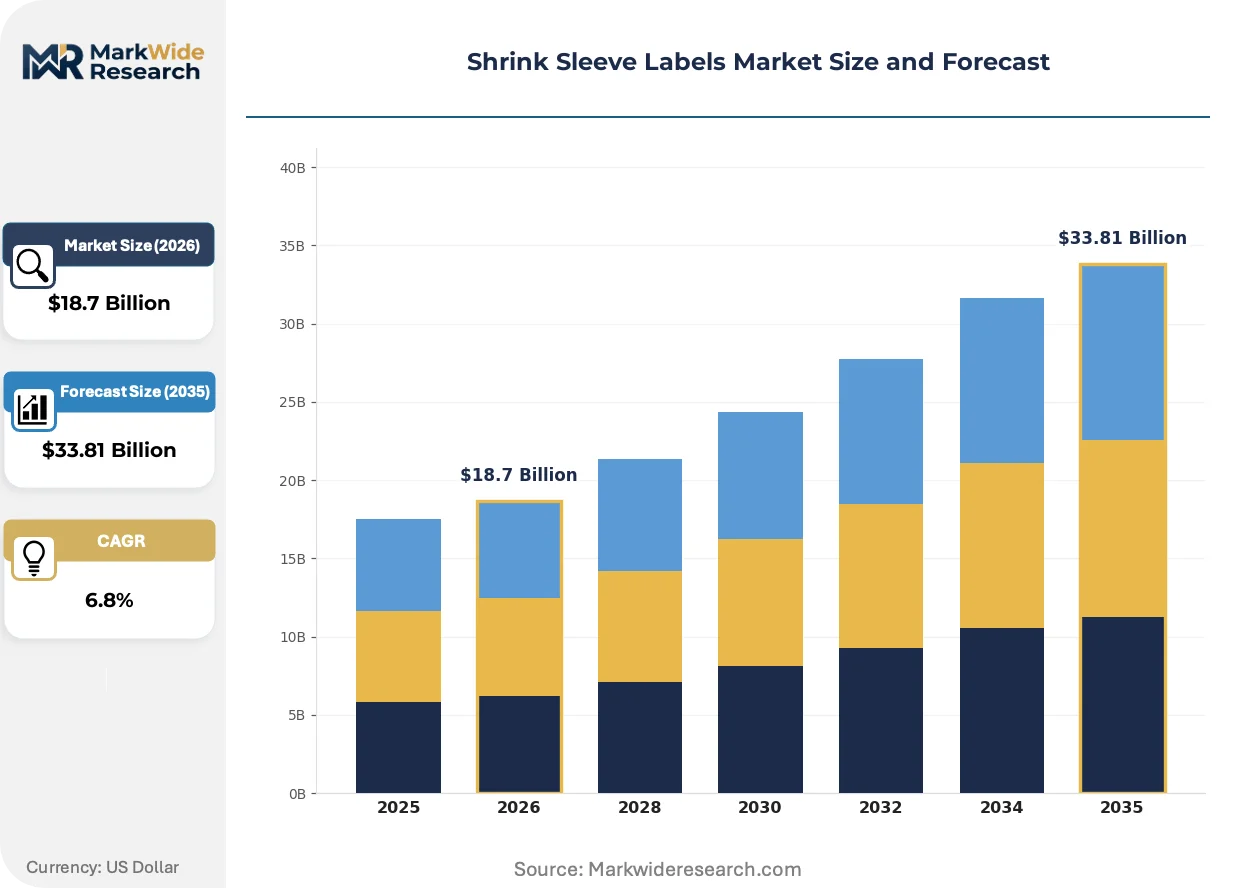
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, PVC, PETG End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Application: Bottle Labeling, Jar Labeling, Blister Packaging, Product Bundling Printing Technology: Flexographic, Gravure, Digital, Offset |
| Companies Covered | Berry Global, Avery Dennison, CCL Industries, Fuji Seal International, Klockner Pentaplast, Mondi Group, Schreiner Group, Sleever International, Multi-Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Sleeve Labels Market Strategic Shifts
Active materials experimentation and regulatory chemistry restrictions are simultaneously pulling substrate portfolios toward PETG dominance while opening niche opportunities for bio-derived and recycle-friendly alternatives.
Digital printing is expanding into shrink sleeve production as beverage brand owners compress new product introduction cycles and demand versioning flexibility for seasonal and regional SKUs. Mid-size craft distillers and functional drink startups are adopting digitally printed sleeves at run lengths below ten thousand units, bypassing gravure cylinder costs entirely. This capability is compressing minimum viable order thresholds and fragmenting volume across a wider supplier base.
ECHA REACH restrictions on chlorinated materials are forcing European personal care and household chemical brands to eliminate PVC sleeves from packaging portfolios by specified compliance deadlines. Film extruders serving German and French markets are reallocating production lines to PETG and OPS alternatives ahead of enforcement phases. Personal care lines with established European retail distribution are absorbing reformulation and qualification costs fastest, while value-tier brands face margin compression from substrate switching.
Brand owner sustainability procurement criteria are elevating recycle-friendly sleeve constructions that separate cleanly from PET bottles during hot-wash recycling operations. Major beverage bottlers in the United States are specifying floatable, label-separable designs as condition of contract renewal, displacing conventional adhesive systems. This specification shift is most visible among carbonated soft drink and bottled water producers with established post-consumer recycled content commitments.
Shrink Sleeve Labels Market Segmentation
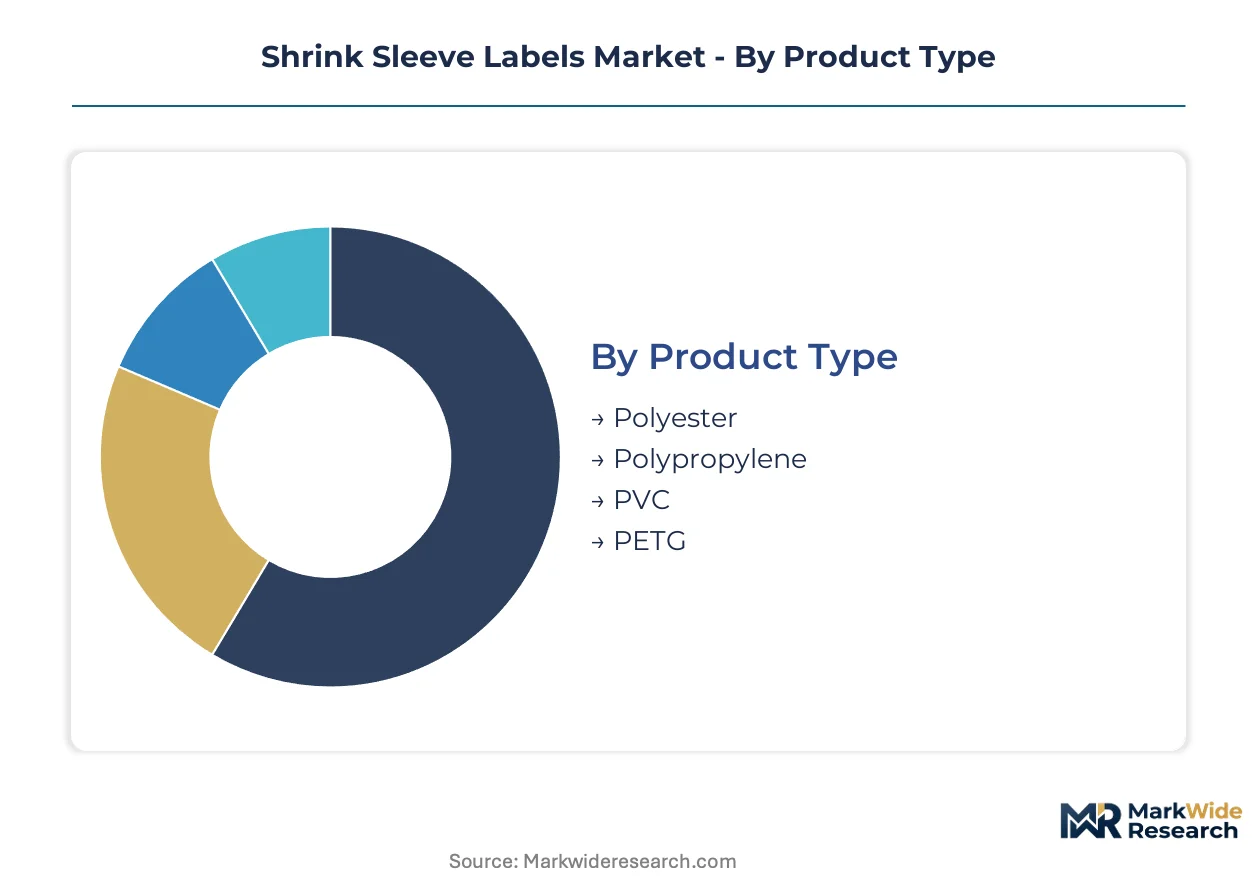
Substrate selection and printing technology choices in shrink sleeve labels carry multi-year equipment lock-in consequences. Brand owners segment procurement across material performance tiers and regulatory compliance thresholds that vary sharply by end-use application.
Product Type:
Material upgrade cycles accelerate as REACH chemical restrictions and recycling compatibility mandates displace legacy substrates.
- PETG:Glycol-modified polyester delivers superior shrink clarity and controlled contraction ratios between 65-75%. Beverage bottlers in Germany and the United States specify PETG for heat-sensitive container applications where dimensional stability matters.
- Polyester:Standard PET substrates offer cost efficiency for high-volume runs with moderate shrink requirements. Personal care brands in France prioritize polyester for established product lines where reformulation costs outweigh substrate switching benefits.
- Polypropylene:Oriented polypropylene films provide stiffness and moisture resistance for household chemical applications. The material dominates Asian markets where humidity tolerance shapes procurement specifications.
- PVC:Chlorinated polymer faces accelerating displacement across European personal care packaging as ECHA REACH Article 57 SVHC enforcement deadlines approach. Legacy beverage contracts in emerging markets sustain residual demand.
PETG sits at the top of the volume ranking, with polyester climbing the fastest as mid-tier brands absorb substrate switching costs.
End User:
Application-specific compliance requirements create divergent margin structures across customer categories.
- Food & Beverage:Carbonated soft drink and bottled water producers drive the largest absolute volume. FDA 21 CFR 177.1630 food-contact compliance and EU packaging waste directives shape supplier qualification timelines for this segment.
- Personal Care:Premium shampoo and cosmetic brands leverage 360-degree decorative coverage for shelf differentiation. ECHA restrictions on chlorinated plasticizers force accelerated PVC displacement across German and French retail distribution.
- Pharmaceuticals:Tamper-evident seals combine with FDA DSCSA serialization mandates. Track-and-trace integration commands premium pricing tiers through variable data printing capabilities.
- Household Products:Bleach and cleaning chemical containers require chemical-resistant adhesives and substrate constructions. The segment tolerates lower decorative complexity in exchange with durability performance.
Food & Beverage captures the dominant share, though Pharmaceuticals sustains the steepest margin expansion trajectory.
Application:
Container geometry and handling requirements dictate sleeve specification and application equipment selection.
- Bottle Labeling:Cylindrical and contoured beverage containers represent the core application. Steam tunnel configurations must accommodate PETG shrink temperatures without container deformation.
- Jar Labeling:Wide-mouth food containers require precise shrink control to avoid panel distortion. Glass compatibility constraints limit adhesive chemistry options.
- Blister Packaging:Pharmaceutical unit-dose applications integrate tamper evidence with child-resistant functionality. The format demands tight dimensional tolerances for automated filling lines.
- Product Bundling:Multi-pack sleeves for promotional configurations use heavier gauge films. Retail club store specifications drive thickness and print coverage requirements.
Bottle Labeling maintains volume leadership, with Product Bundling expanding most quickly as promotional packaging cycles compress.
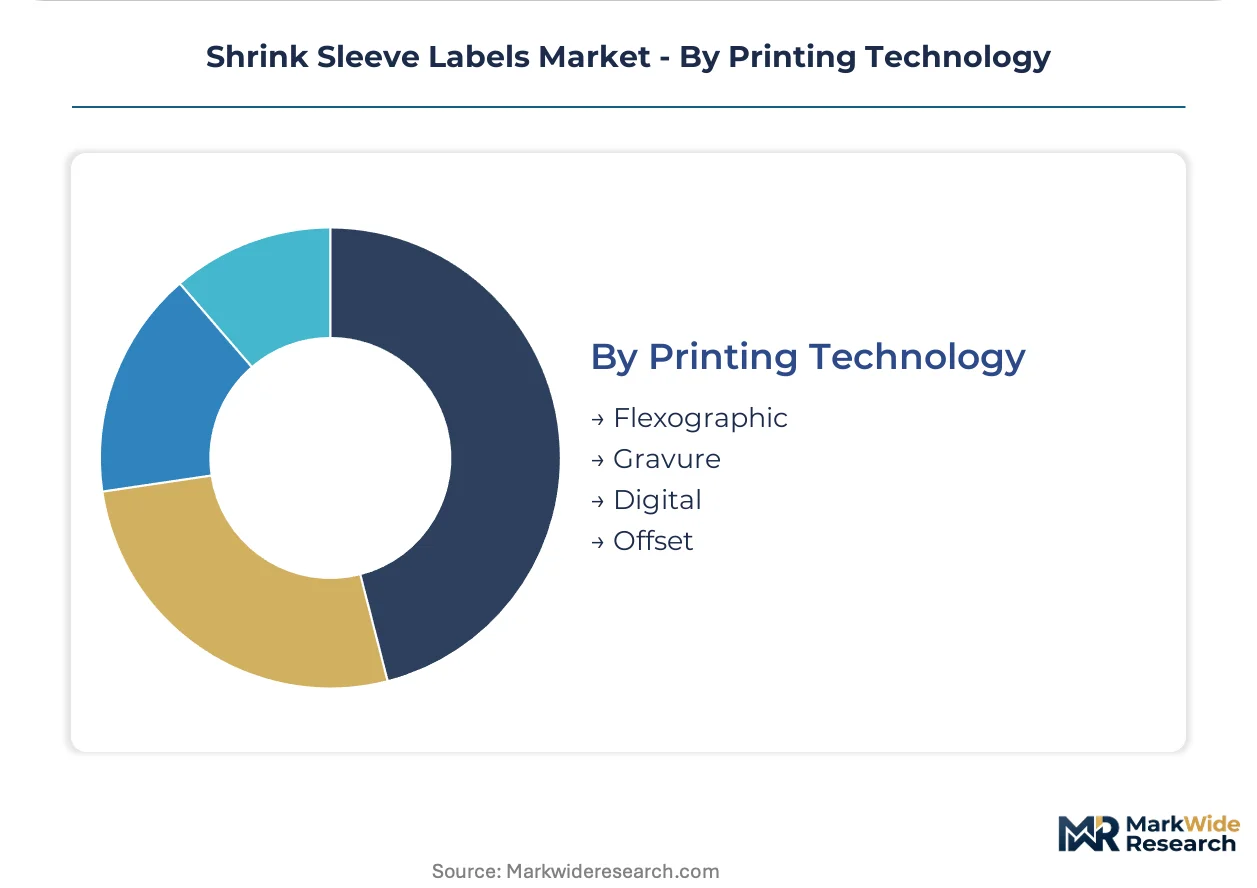
Printing Technology:
Run length economics and versioning flexibility determine technology adoption patterns across converter investments.
- Gravure:Cylinder-based engraving delivers unmatched color consistency for high-volume beverage contracts. Skilled engraving capacity scarcity extends pre-press timelines and compresses production windows.
- Digital:Inkjet and toner systems enable run lengths below ten thousand units without cylinder costs. Craft distillers and functional drink startups adopt digital for seasonal and regional SKU proliferation.
- Flexographic:Plate-based relief printing balances setup efficiency with mid-volume economics. The technology serves personal care and household product lines with moderate graphic complexity.
- Offset:Lithographic transfer achieves fine detail reproduction for premium cosmetic applications. The process requires smooth substrate surfaces that limit material compatibility.
Gravure retains the highest volume position, with Digital gaining share fastest as brand owners compress new product introduction cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as film extruders migrate capacity toward jurisdictions with clearer compliance pathways and lower cost-of-qualification timelines for food-contact substrates.
United States
Beverage bottlers in Georgia and Texas are consolidating procurement around PETG-compatible steam tunnel configurations. FDA 21 CFR 177.1630 migration testing requirements extend supplier qualification timelines to 18-24 months. The Southeast packaging corridor from Atlanta to Charlotte hosts dedicated sleeve extrusion capacity serving carbonated soft drink producers with established post-consumer recycled content commitments.
Germany
Personal care brands in Hamburg and Düsseldorf face accelerated PVC displacement deadlines under ECHA REACH Article 57 SVHC enforcement phases. The country's central position within EU distribution networks attracts gravure cylinder engraving specialists serving pan-European beverage contracts. Baden-Württemberg film converters are reallocating production lines to PETG alternatives ahead of 2026 compliance milestones.
China
SAMR GB standards for packaging material safety condition import access for foreign film suppliers seeking beverage sector contracts. The Yangtze River Delta concentration of contract bottling infrastructure in Jiangsu and Zhejiang provinces generates localized demand density for OPS and PETG substrates. Shanghai-based gravure networks dominate Asian beverage sleeve procurement through integrated cylinder production and print finishing assets.
India
Maharashtra and Gujarat beverage bottling clusters remain underpenetrated by sleeve-qualified suppliers despite expanding contract manufacturing capacity. BIS certification requirements for food-contact plastics create qualification barriers that favor domestic film extruders with established testing relationships. The Mumbai-Pune industrial corridor is attracting preliminary investments in digital sleeve printing assets serving craft distillery and functional drink startups.
Japan
METI guidance on plastic resource circulation is elevating recycle-friendly sleeve specifications among premium cosmetic brands in Osaka and Tokyo. Kansai-region personal care manufacturers specify floatable, label-separable designs as condition of supplier renewal. Domestic gravure specialists maintain cylinder engraving capacity for high-volume beverage contracts with compressed production windows.
Shrink Sleeve Labels Market Competitive Environment
North American producers anchor one tier; Asian specialists hold gravure cylinder networks and localized beverage contracts. The vendor base clusters around integrated film extrusion-printing assets and standalone converting operations with equipment lock-in to specific substrate portfolios. Three archetypes dominate: multinational packaging conglomerates with captive resin supply, regional gravure specialists with cylinder engraving capacity, and digital-enabled converters serving fragmented craft beverage demand. Competitive moves center on substrate qualification speed and recycling-compatible adhesive system development.
Among North American packaging conglomerates, Berry Global and CCL Industries exemplify integrated film-to-print operations with dedicated sleeve extrusion assets. Fuji Seal International occupies a position within the Asian gravure specialist tier, leveraging localized cylinder networks for beverage sector procurement density. Avery Dennison represents the adhesive chemistry extension archetype, translating pressure-sensitive heritage into sleeve-compatible coating systems. These three anchors illustrate divergent strategic positions across substrate supply, print technology, and geographic concentration vectors.
| Leading Market Players |
|---|
| Berry Global |
| Avery Dennison |
| CCL Industries |
| Fuji Seal International |
| Klockner Pentaplast |
| Mondi Group |
| Schreiner Group |
| Sleever International |
| Multi-Color Corporation |
| Others |
Value Chain & Pricing Dynamics
Purified terephthalic acid and ethylene glycol spot pricing swings compress PETG margin predictability for film extruders, cascading through converter pricing tiers as beverage bottlers negotiate multi-year sleeve supply contracts. Resin feedstock volatility forces substrate selection decisions that lock in equipment configurations and channel margin structures across the value chain.
Pricing Analysis
Direct-to-OEM volume discounts dominate high-volume beverage contracts, while distributor markups persist for mid-tier personal care brands lacking procurement scale. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical serialization-integrated sleeves from commodity beverage applications. Cost compression in standard-grade PETG is intensifying because Asian extruders are expanding capacity faster than demand absorption. Craft beverage startups exhibit highest price sensitivity, while pharmaceutical contract manufacturers tolerate premium tiers for compliance-integrated solutions.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns serving concentrated bottling clusters. Film extrusion capacity concentrates in Germany, China, and the United States, with gravure cylinder engraving specialists concentrated in Japan and Germany. Raw material supply draws from purified terephthalic acid producers in the United States and South Korea, plus ethylene glycol from Middle Eastern petrochemical complexes. Single-source vulnerability around gravure cylinder engraving capacity extends pre-press timelines. Distribution runs through converter-direct relationships for large beverage bottlers and packaging distributors for fragmented personal care brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical serialization tiers and recycle-friendly substrate formulations, as substrate switching costs and sustainability procurement criteria elevate premium pricing power.
For Market Incumbents: Deepen backward integration into PETG resin supply to defend against feedstock volatility and Asian extruder price competition. Secure ECHA REACH Article 57 SVHC-compliant substrate qualifications ahead of enforcement deadlines to lock in European personal care contracts. Expand cylinder engraving capacity in Germany to compress production windows for high-volume beverage procurement. For New Entrants and Emerging Players: Launch via digital sleeve printing assets serving Maharashtra and Gujarat craft distillery clusters, where BIS certification barriers favor domestic entrants with local testing relationships. Target pharmaceutical contract manufacturers in India seeking serialization-integrated tamper-evident solutions. Penetrate through seasonal SKU versioning services that bypass gravure cylinder lead times. For Investors and Strategic Acquirers: Consolidation pressure builds where film extruders lack integrated printing assets and face equipment lock-in to displaced PVC portfolios. Long-term viability favors converters with digital-gravure hybrid capabilities and pharmaceutical serialization integration. Acquisition target archetype: regional gravure specialists with beverage sector contracts and underutilized cylinder capacity. Watch ECHA REACH enforcement acceleration as inflection signal for PVC displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PETG Resin | Captive supply of purified terephthalic acid buffers margin compression from Asian extruder expansion. |
| Digital-Gravure Hybrid Capacity | Dual technology platforms capture craft beverage versioning demand alongside high-volume beverage contracts. |
| Pharmaceutical Serialization Certification | FDA DSCSA compliance unlocks premium pricing tiers through variable data tamper-evident integration. |
| Recycle-Friendly Adhesive Development | Floatable label-separable designs meet major US bottler procurement criteria for post-consumer recycled content commitments. |
| Gravure Cylinder Engraving Expansion | Skilled capacity scarcity in Germany and Japan creates bottleneck for beverage contract production windows. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with film extrusion plant managers, beverage procurement leads, gravure cylinder engraving specialists, and pharmaceutical packaging engineers. Secondary validation draws from FDA 21 CFR filings, ECHA REACH SVHC candidate lists, SAMR GB standard publications, and customs trade data for PETG substrate flows. Bottom-up demand modeling from converter capacity and top-down market sizing from end-use consumption patterns undergo triangulation.
Rate-of-change decomposition separates volume growth from value expansion across substrate type, printing technology, end-use application, and regional regulatory cluster dimensions. CAGRs derive from segmented demand modeling incorporating SKU proliferation velocity, REACH compliance deadline phasing, and digital printing adoption curves. Forecast inputs include steam tunnel installation rates at beverage bottling facilities and pharmaceutical track-and-trace mandate implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under resin feedstock price volatility and ECHA enforcement acceleration scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Self-Adhesive Labels Market
Labels
Printable Tags Market
Labels
Label Applicator Market
Labels
Time Temperature Indicator Labels Market
Labels
Eco-Friendly Labels Market
Labels
Self-Laminating Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Ethical Label Market
Labels
Global Thermal Transfer Label Market
Labels
Sheeted Labels Market
Labels
Coated Wet Glue Label Market
Labels
Thermal Labels Market
Labels
Extended Text Labels Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Global Waterproof Labels Market
Labels
Pin Feed Labels Market