
 Wax Boxes Market | 2026-2036
Wax Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Wax Boxes Market Outlook
Skilled machine operators for wax coating lines is bifurcating the competitive landscape between automated and labor-dependent producers. Georgia-Pacific leverages its integrated pulp-to-box infrastructure across the southeastern United States to sustain cost leadership in wax-impregnated board. International Paper anchors its position through captive resin and wax sourcing that insulates margin pools from petrochemical volatility.
Wax boxes are fiber-based containers treated with paraffin or microcrystalline wax emulsions to achieve moisture resistance, typically rated for wet strength retention above 30 minutes under TAPPI T-812 testing protocols, serving primarily food transport and cold-chain logistics applications. The material dimension shows cardboard and paperboard grades dominating volume while plastic-laminated hybrid constructions capture expanding margin pools in pharmaceutical and premium food segments. Retailers and e-commerce channels within the end-user split are pulling demand toward custom-printed wax boxes that double as shelf-ready display units, compressing traditional wholesale-specification volumes.
The EPA governs volatile organic compound emissions from wax coating ovens under Clean Air Act Title V permitting, while OSHA mandates confined-space protocols around molten wax storage tanks that elevate compliance costs for smaller coating operations. The EU Green Deal and associated Packaging and Packaging Waste Regulation are forcing reformulation toward bio-based wax alternatives, tightening market access for conventional paraffin-dependent suppliers. Stakeholders must monitor regulatory divergence between North American petrochemical wax tolerance and European bio-wax mandates when allocating R&D and capital deployment across manufacturing footprints.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing demand for conventional paraffin-coated boxes while bio-wax formulation R&D absorbs disproportionate capital allocation across European coating operations.
Growth Catalysts
- E-commerce fulfillment networks:Cold-chain grocery delivery platforms in Germany and the Netherlands are specifying wax-impregnated corrugated for last-mile moisture protection, pulling volume from traditional wholesale channels.
- REACH bio-wax mandates:The EU Green Deal's packaging waste targets are accelerating supplier qualification programs for vegetable-based wax emulsions, opening procurement doors for certified bio-coating specialists.
- Food logistics infrastructure:Perishable distribution hubs across France and Italy require secondary packaging with TAPPI T-812 wet strength retention above 30 minutes, sustaining baseline demand for moisture-resistant fiber containers.
Market Restraints
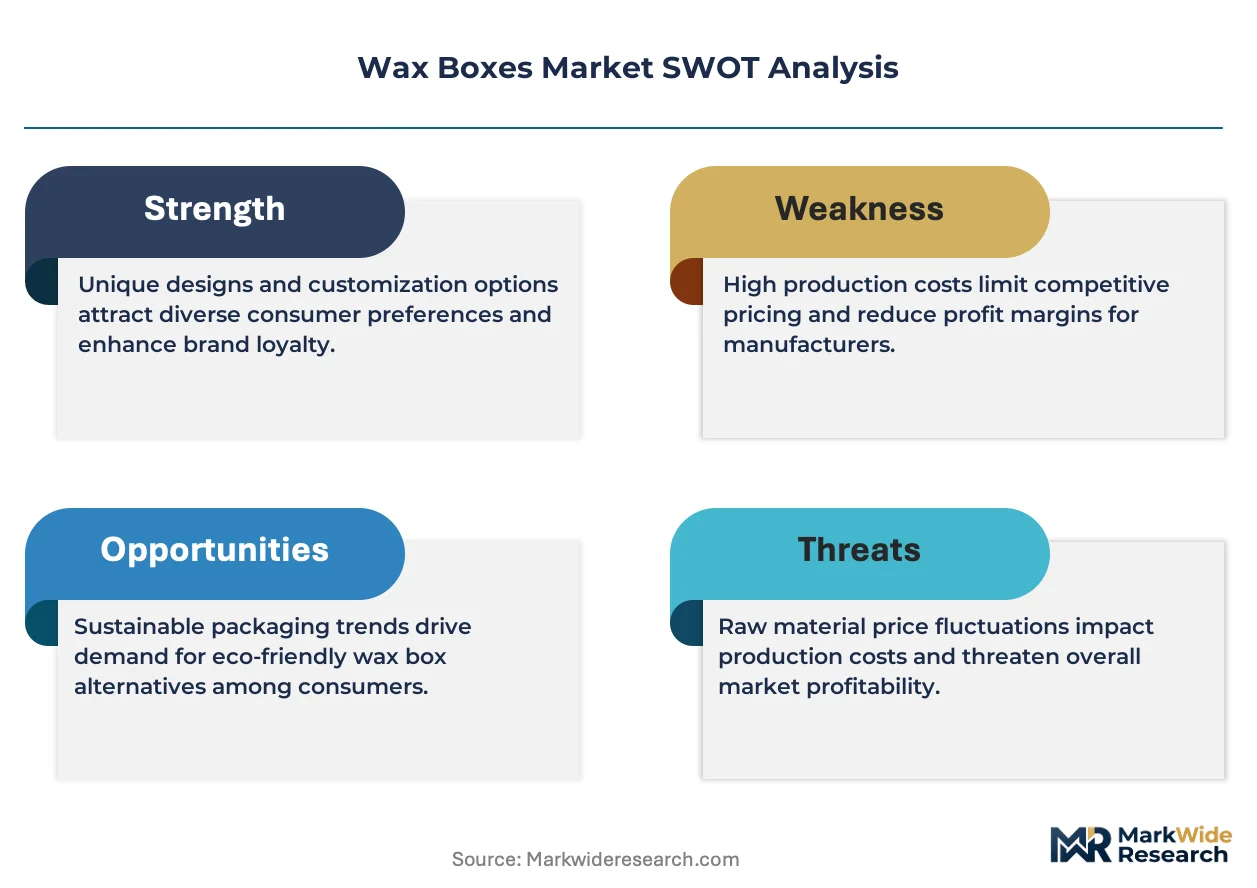
- Petrochemical input volatility:Paraffin and microcrystalline wax prices track crude oil futures, compressing margin pools for coating operations without captive resin sourcing.
- European regulatory fragmentation:Divergent national implementation timelines for the EU Packaging and Packaging Waste Regulation create compliance cost uncertainty for cross-border suppliers.
- Plastic-laminated substitutes:Polyethylene-coated paperboard from Asian producers is capturing pharmaceutical and premium food segments with superior moisture barrier performance.
Strategic Opportunities
- Underpenetrated Central European markets:Poland and Czech Republic cold-chain networks remain dependent on uncoated corrugated, presenting first-mover openings for certified wax box suppliers.
- Pharmaceutical serialization compliance:The EU MDR's track-and-trace requirements favor tamper-evident wax-coated secondary packaging with integrated RFID compatibility.
- Bio-wax technology convergence:Blending enzymatically modified plant waxes with conventional coatings is yielding drop-in replacements that satisfy EFSA food contact approvals without line reconfiguration.
Industry Challenges
- Skilled operator scarcity:Molten wax coating line technicians with confined-space certification under OSHA-equivalent EU directives command wage premiums that strain smaller coating operations.
- Capital equipment reconfiguration:Transitioning from paraffin to bio-wax formulations requires oven temperature profile modifications and emission control upgrades that extend payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wax Boxes Market |
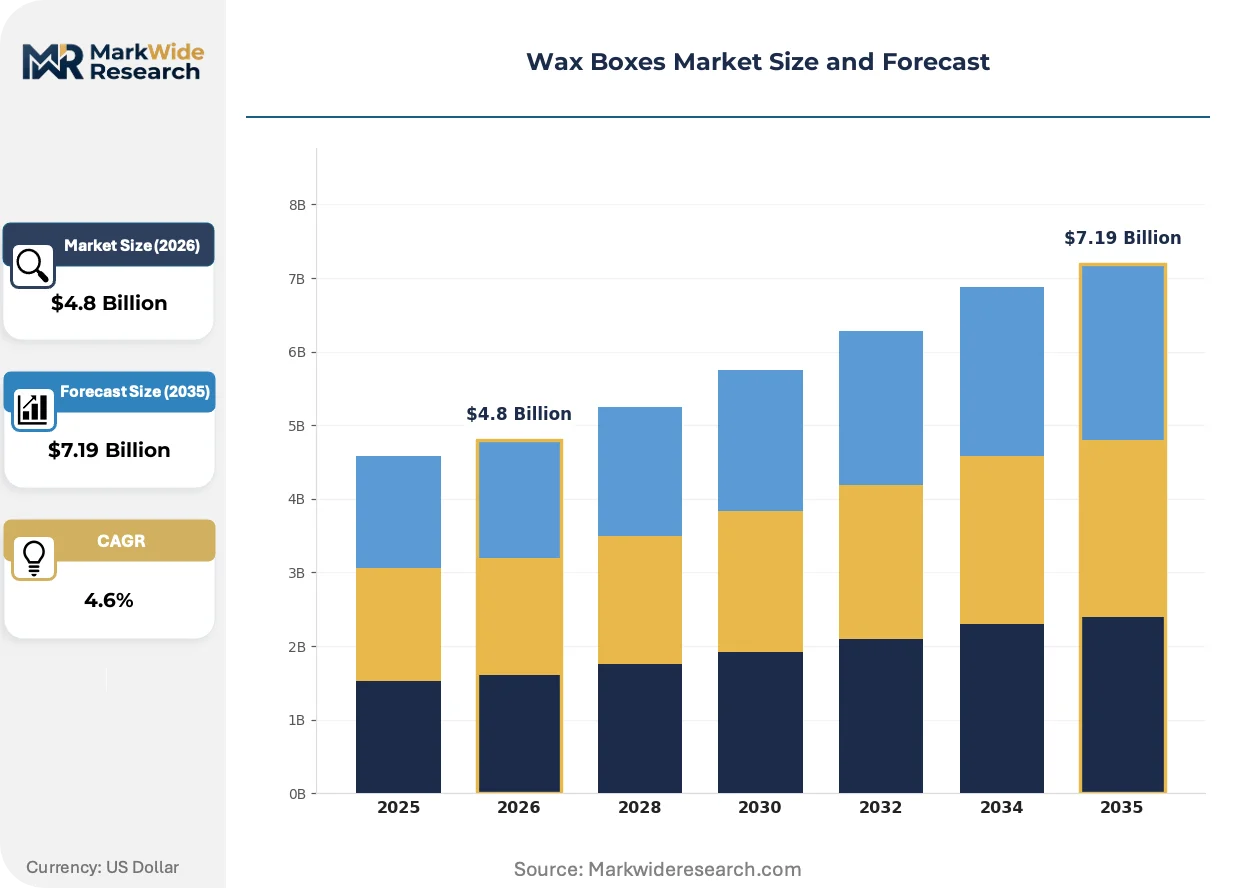
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
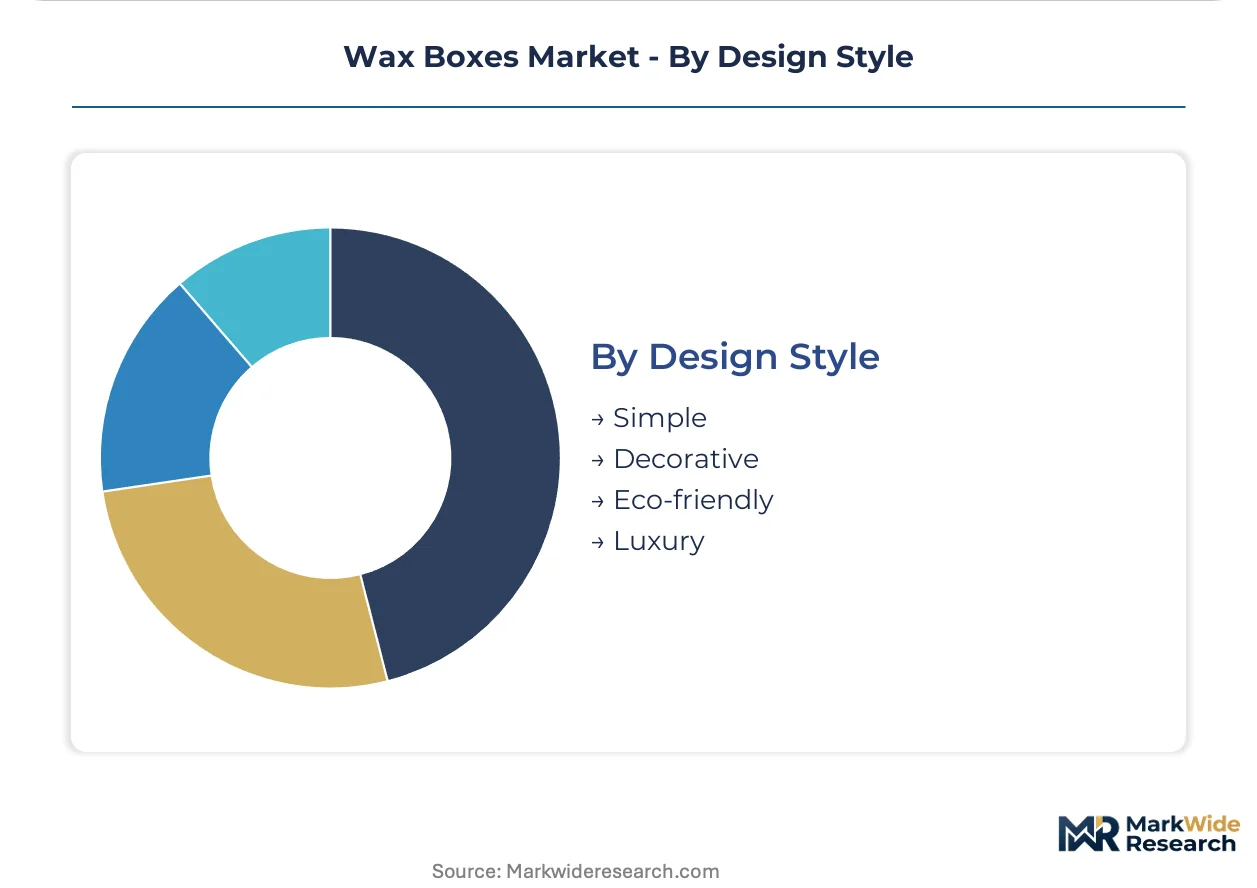
| Segmentation | Packaging Type: Retail Boxes, Gift Boxes, Storage Boxes, Custom Boxes Material: Cardboard, Paperboard, Plastic, Wood End User: Retailers, E-commerce, Wholesalers, Manufacturers Design Style: Simple, Decorative, Eco-friendly, Luxury |
| Companies Covered | Georgia-Pacific LLC, Packaging Corporation of America, International Paper Company, Mondi, Stora Enso, WestRock Company, DS Smith, Sonoco, Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wax Boxes Market Strategic Shifts
Coating chemistry reformulation and digital printing integration are redefining value capture in fiber-based protective packaging, compressing traditional specification-based procurement models.
Microcrystalline wax emulsions with enzymatic bio-additives are displacing conventional paraffin coatings in food-contact applications. Cold-chain logistics operators in Germany and France are qualifying these formulations at accelerated pace. The technology is displacing legacy coating lines that cannot achieve EFSA compliance without capital-intensive rebuilds.
The EU Packaging and Packaging Waste Regulation's material recovery mandates are forcing coating reformulation toward mono-material recyclability. Paraffin-dependent suppliers face market access restrictions unless they achieve certified compostability under EN 13432. Premium food and pharmaceutical segments in Benelux and Scandinavia are migrating procurement specifications to bio-wax-compliant suppliers ahead of enforcement deadlines.
Retailer consolidation is compressing supplier bases and demanding shelf-ready display functionality from secondary packaging. E-commerce channels in Germany and the Netherlands now specify custom-printed wax boxes that eliminate tertiary display units. This behavior is most visible in fresh produce and chilled ready-meal categories where unboxing experience drives repeat purchase metrics.
Wax Boxes Market Segmentation
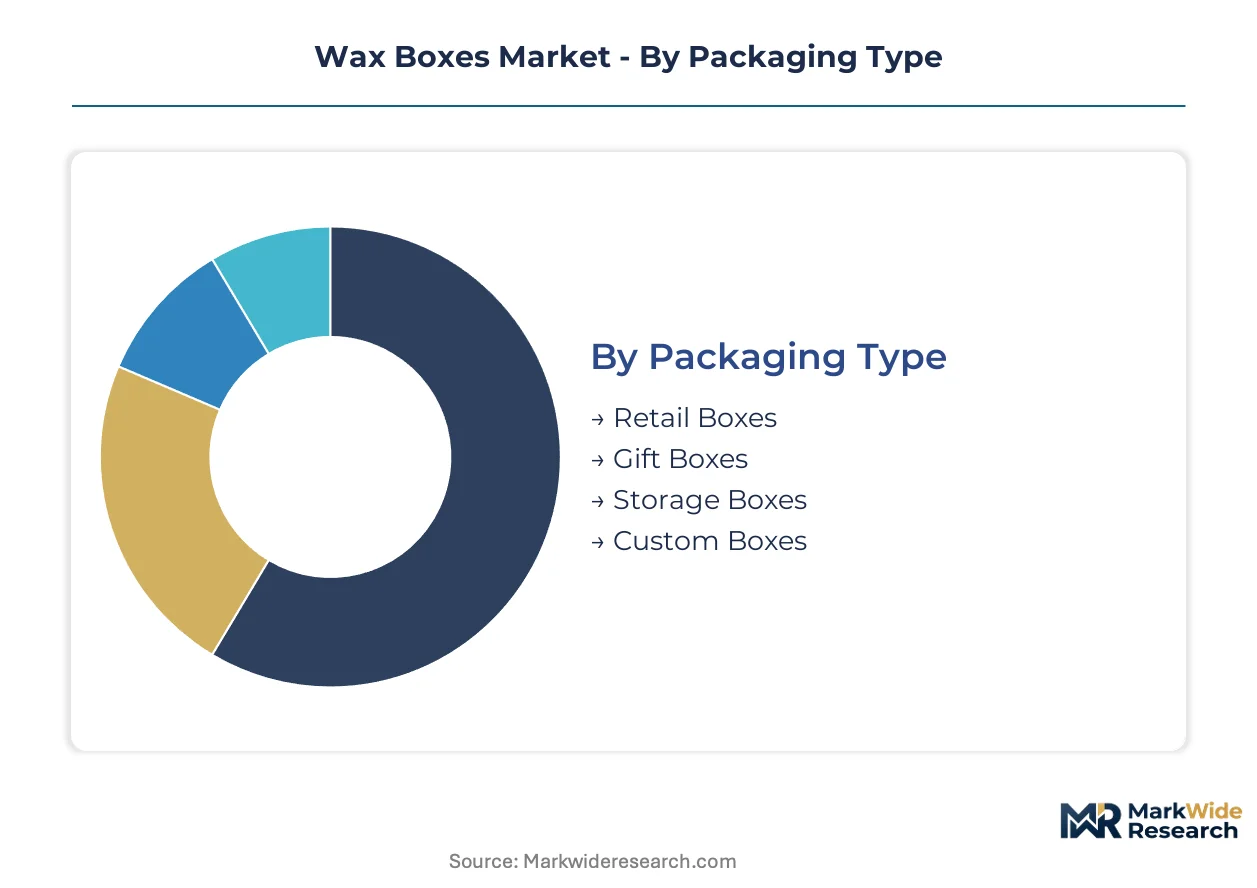
Wax box procurement channels fragment sharply across end-use applications, with cold-chain logistics networks pulling specifications toward moisture-resistant corrugated while retail consolidation compresses supplier bases toward display-capable formats. Understanding segment-channel alignment exposes where margin pools concentrate versus where volume commoditizes.
Packaging Type:
Channel-mix dynamics determine which packaging formats capture investment: retail boxes flow through consolidated grocery networks, gift boxes through premium e-commerce platforms, storage boxes through industrial procurement, and custom boxes through direct brand relationships.
- Retail Boxes:Standardized wax-impregnated corrugated rated for TAPPI T-812 wet strength retention above 30 minutes. German and Dutch cold-chain grocery networks specify these for last-mile moisture protection, pulling volume from traditional wholesale channels as e-commerce fulfillment accelerates.
- Custom Boxes:Digital-printed wax-coated containers doubling as shelf-ready display units. Retailer consolidation in Benelux and Scandinavia demands these formats, compressing traditional wholesale-specification volumes as unboxing experience drives repeat purchase metrics.
- Gift Boxes:Decorative wax-treated containers for premium food and pharmaceutical gifting segments.
- Storage Boxes:Heavy-duty wax-impregnated fiber containers for industrial cold-chain hubs.
Retail boxes dominate installed base. Custom boxes are where expansion concentrates.
Material:
Cost-tier stratification separates commodity fiber grades from performance-engineered alternatives, with coating chemistry and substrate integration determining qualification barriers.
- Cardboard:Recycled-content corrugated with paraffin or microcrystalline wax emulsion coatings. E-commerce channels in Germany and the Netherlands specify these for moisture-resistant secondary packaging, though EU Packaging and Packaging Waste Regulation mandates are forcing reformulation toward bio-wax alternatives.
- Paperboard:Higher-grade bleached kraft with precision wax saturation for food-contact compliance. Pharmaceutical serialization requirements under EU MDR favor these substrates for tamper-evident secondary packaging with integrated RFID compatibility.
- Plastic:Polyethylene-laminated hybrid constructions capturing pharmaceutical and premium food segments with superior moisture barrier performance.
- Wood:Specialty wax-impregnated timber containers for heavy industrial cold-chain applications.
Cardboard commands volume scale. Paperboard captures expanding margin pools.
End User:
Customer-type concentration reveals where specification power resides: retailers and e-commerce platforms now dictate shelf-ready functionality, while wholesalers and manufacturers lag in format modernization.
- E-commerce:Cold-chain grocery delivery platforms in Germany and the Netherlands specifying wax-impregnated corrugated for last-mile moisture protection. These operators pull procurement specifications toward custom-printed formats that eliminate tertiary display units.
- Retailers:Consolidated grocery and fresh-produce chains demanding shelf-ready display functionality from secondary packaging. Benelux and Scandinavian retailers are migrating procurement to bio-wax-compliant suppliers ahead of EU enforcement deadlines.
- Wholesalers:Traditional volume purchasers of standardized wax-coated containers for food logistics networks.
- Manufacturers:Industrial cold-chain operators requiring TAPPI T-812 certified moisture-resistant fiber containers for perishable distribution.
E-commerce is climbing the fastest. Retailers anchor specification power.
Design Style:
Maturity-stage differentiation separates legacy functional formats from emerging compliance-driven and experience-focused alternatives, with regulatory pressure and consumer preference reshaping investment allocation.
- Eco-friendly:Bio-wax formulations using enzymatically modified plant waxes blended with conventional coatings. EU Green Deal packaging waste targets and EFSA food contact approvals are accelerating supplier qualification programs for these drop-in replacements.
- Luxury:Premium wax-coated containers with high-fidelity digital printing and tactile finishes. Pharmaceutical and premium food segments in Benelux specify these for brand differentiation and unboxing experience metrics.
- Simple:Unprinted or minimally treated wax boxes for cost-sensitive industrial applications.
- Decorative:Ornamented wax-treated containers for seasonal and gift-market applications.
Simple designs dominate legacy volume. Eco-friendly formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands a premium over Polish markets due to stricter bio-wax compliance mandates and concentrated cold-chain infrastructure investment. This asymmetry shapes capital allocation decisions across European coating operations.
Germany
Cold-chain grocery delivery platforms in Berlin and Hamburg specify wax-impregnated corrugated for last-mile moisture protection, pulling procurement specifications toward custom-printed formats. The EU Packaging and Packaging Waste Regulation forces coating reformulation toward bio-wax alternatives through certified compostability requirements. The Rhine-Ruhr industrial corridor hosts concentrated coating line operations serving perishable distribution networks.
France
Perishable distribution hubs across Île-de-France and Lyon require secondary packaging with TAPPI T-812 wet strength retention above 30 minutes, sustaining baseline demand for moisture-resistant fiber containers. EFSA food contact approvals accelerate supplier qualification programs for enzymatically modified plant wax formulations. The Paris Basin anchors pharmaceutical serialization compliance demand under EU MDR track-and-trace requirements.
Netherlands
E-commerce channels in Amsterdam and Rotterdam now specify custom-printed wax boxes that eliminate tertiary display units, compressing traditional wholesale-specification volumes. REACH bio-wax mandates under the EU Green Deal open procurement doors for certified bio-coating specialists. The Randstad logistics cluster concentrates last-mile fulfillment infrastructure demanding shelf-ready display functionality.
Poland
Central European cold-chain networks remain dependent on uncoated corrugated, presenting first-mover openings for certified wax box suppliers entering Warsaw and Krakow markets. Divergent national implementation timelines for the EU Packaging and Packaging Waste Regulation create compliance cost uncertainty for cross-border suppliers. The Silesian industrial region shows emerging demand from food logistics infrastructure modernization programs.
Italy
Pharmaceutical and premium food segments in Milan and Turin are migrating procurement specifications to bio-wax-compliant suppliers ahead of EU enforcement deadlines. The EU MDR's track-and-trace requirements favor tamper-evident wax-coated secondary packaging with integrated RFID compatibility. Northern Italy's packaging machinery cluster supports coating line technology upgrades for bio-wax formulation transitions.
Wax Boxes Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated pulp-to-box operators sustaining margin pools through captive resin sourcing while specialized coating houses capture premium tiers through bio-wax certification. The vendor base concentrates around three strategic tiers: multinational integrated paperboard producers, regional coating specialists, and captive packaging operations of major food retailers. Dominant competitive moves include backward integration into wax resin supply and geographic expansion into underpenetrated Central European markets.
Among North American integrated producers, Georgia-Pacific LLC and International Paper Company exemplify the cost-leadership archetype through pulp-to-box infrastructure control, while Mondi represents the European bio-wax transition specialist tier navigating EFSA compliance requirements. These three anchors demonstrate how captive supply chain positioning determines competitive resilience against petrochemical input volatility.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| Packaging Corporation of America |
| International Paper Company |
| Mondi |
| Stora Enso |
| WestRock Company |
| DS Smith |
| Sonoco |
| Smurfit Kappa Group |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day wax resin inventory cycles in European coating operations compress margin pools when petrochemical volatility spikes, concentrating pricing power with integrated producers holding captive paraffin supply while fragmenting leverage across smaller toll-coating houses dependent on spot resin markets.
Pricing Analysis
German bio-wax-compliant wax boxes command substantial premiums over Polish paraffin-dependent equivalents due to EU Packaging and Packaging Waste Regulation enforcement timelines. Three-tier pricing structure across premium bio-wax certified, standard paraffin-coated, and economy uncoated grades separates qualification tiers. Cost compression in standard paraffin tiers is intensifying because crude oil futures volatility passes through to coating operations without hedging infrastructure. E-commerce platforms show least price sensitivity due to unboxing experience requirements, while industrial cold-chain operators anchor volume with highest sensitivity.
Supply Chain Analysis
Rotterdam port congestion on Asia-Europe container lanes elevates inbound logistics costs for Asian polyethylene-laminated substitutes competing in pharmaceutical segments. Wax box supply concentrates in Germany, Poland, and Italy, with coating line density tracking food logistics infrastructure investment. Raw material dependencies center on paraffin and microcrystalline wax feedstocks, enzymatically modified plant wax alternatives, and bleached kraft pulp substrates. Single-source vulnerability runs through petrochemical wax refiners without bio-wax pivot capacity. Distribution runs through consolidated grocery networks and direct e-commerce fulfillment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU member states fragments procurement specifications, creating niche openings for bio-wax specialists and Central European first-movers as cold-chain infrastructure modernizes.
For Market Incumbents: Compound technology leadership through captive bio-wax resin production and accelerated EFSA certification pipelines. Georgia-Pacific and International Paper demonstrate how upstream control over wax sourcing insulates margin pools from petrochemical volatility. Defend position by locking long-term offtake agreements with German e-commerce platforms before REACH bio-wax mandates fully enforce. For New Entrants and Emerging Players: Differentiate on enzymatic bio-wax formulation expertise targeting Poland and Czech Republic cold-chain networks still dependent on uncoated corrugated. The most penetrable white-space sits in pharmaceutical serialization compliance under EU MDR track-and-trace requirements. Pursue direct supplier qualification with Benelux retailers migrating procurement ahead of enforcement deadlines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Green Deal packaging waste targets will structurally disadvantage paraffin-dependent assets while rewarding early bio-wax certification. Target coating specialists with existing EFSA approvals and scalable enzymatic formulation capacity. Watch for inflection when EU Packaging and Packaging Waste Regulation national implementation timelines converge, compressing cross-border compliance cost uncertainty.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Wax Resin Production | Captive supply of enzymatically modified plant waxes insulates margin pools from petrochemical volatility and secures EFSA compliance ahead of REACH mandates. |
| EFSA Certification Pipeline Investment | Accelerated food-contact approval timelines open procurement doors with German and Dutch cold-chain grocery platforms specifying bio-wax formats. |
| Central European Geographic Expansion | First-mover positioning in Poland and Czech Republic cold-chain networks captures infrastructure modernization spend before competitor coating lines qualify. |
| Digital Printing Integration for Shelf-Ready Formats | Custom-printed wax boxes eliminating tertiary display units capture retailer consolidation demand in Benelux and Scandinavian markets. |
| Pharmaceutical Serialization Compliance Partnership | EU MDR track-and-trace requirements favor tamper-evident wax-coated secondary packaging with integrated RFID compatibility in Milan and Turin hubs. |
Study Parameters
Initial hypotheses were tested against primary input from coating line operations managers, cold-chain logistics procurement leads, EFSA regulatory affairs specialists, and corrugated plant engineers and refined through secondary validation against EU Packaging and Packaging Waste Regulation implementation documents, TAPPI T-812 testing protocol publications, customs trade data on wax resin imports, and SEC filings from integrated paperboard producers. Bottom-up volume builds triangulated against top-down macroeconomic elasticity assumptions.
Variance decomposition across packaging type, material grade, end-user channel, and design style maturity stages structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro drivers. Forecast inputs included coating line capacity utilization rates by country, e-commerce cold-chain penetration trajectories, and bio-wax formulation R&D spend allocation patterns.
Material uncertainties — abrupt EU member state regulatory enforcement acceleration, enzymatic bio-wax scale-up failures, or polyethylene-laminated substitute cost breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions documented in segmentation granularity and input cost passthrough coefficients. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Global Folding Carton Packaging Market
Cartons
Mailers Market
Cartons
Beverage Cartons Market
Cartons
Pick and Place Carton Packers Market
Cartons
Folding Cartons Market
Cartons
Fully Enclosed Cartons Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Carton Bottle Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Global Hand Carton Sealers Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Carton Display Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Tetrahedron Carton Market
Cartons
Twist Opening Cartons Market