
 Cartoning Machines Market | 2026-2036
Cartoning Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Cartoning Machines Market Analysis
Germany is rewriting the competitive map for cartoning machinery through its dense engineering ecosystem and export-oriented production base. Krones AG leverages its beverage packaging heritage to anchor high-speed cartoning lines for multinational bottlers. Syntegon Technology specializes in pharmaceutical-grade containment and serialization systems that sustain premium positioning across regulated markets. IMA Group dominates solid-dose cartoning with integrated blister-to-carton workflows that extend its footprint in oncology and orphan drug packaging.
Cartoning machines form electromechanical systems that erect, load, and close paperboard cartons at speeds ranging from 50 to 500 units per minute depending on configuration and product stability requirements. Horizontal cartoning configurations lead in food and beverage applications where product orientation and gentle handling preserve package integrity through high-speed transfer points. Fully automated technology lines command the strongest margin pools by reducing changeover downtime and integrating directly with upstream filling and downstream palletizing equipment. Pharmaceutical end users increasingly specify robotic loading modules to eliminate human contact with sterile or high-potency products.
EU MDR serialization requirements and FDA track-and-trace regulations under the Drug Supply Chain Security Act compel pharmaceutical cartoning investments with integrated aggregation and verification hardware. REACH compliance on adhesive and ink chemistries shapes material selection for carton sealing and marking systems sold into European markets. Stakeholders must weigh capital allocation between modular retrofit platforms and greenfield integrated lines as regulatory deadlines tighten and batch-size flexibility becomes a decisive operational variable.
Market Dynamics
EU MDR serialization mandates and FDA track-and-trace enforcement are compressing pharmaceutical packaging timelines, forcing manufacturers to prioritize integrated cartoning lines with built-in aggregation and verification hardware over modular retrofits.
Growth Catalysts
- EU MDR serialization mandates:Pharmaceutical manufacturers must install cartoning systems with aggregation capabilities by regulatory deadlines, creating immediate equipment replacement cycles across European production facilities.
- Machine learning vision inspection:AI-powered defect detection systems reduce false rejection rates and enable real-time quality adjustments, accelerating adoption in high-value pharmaceutical and food packaging lines.
- Stuttgart-Cologne machinery cluster:Germany's concentrated engineering ecosystem delivers short lead times and deep technical support, sustaining export competitiveness into Middle Eastern and Latin American markets.
Market Restraints
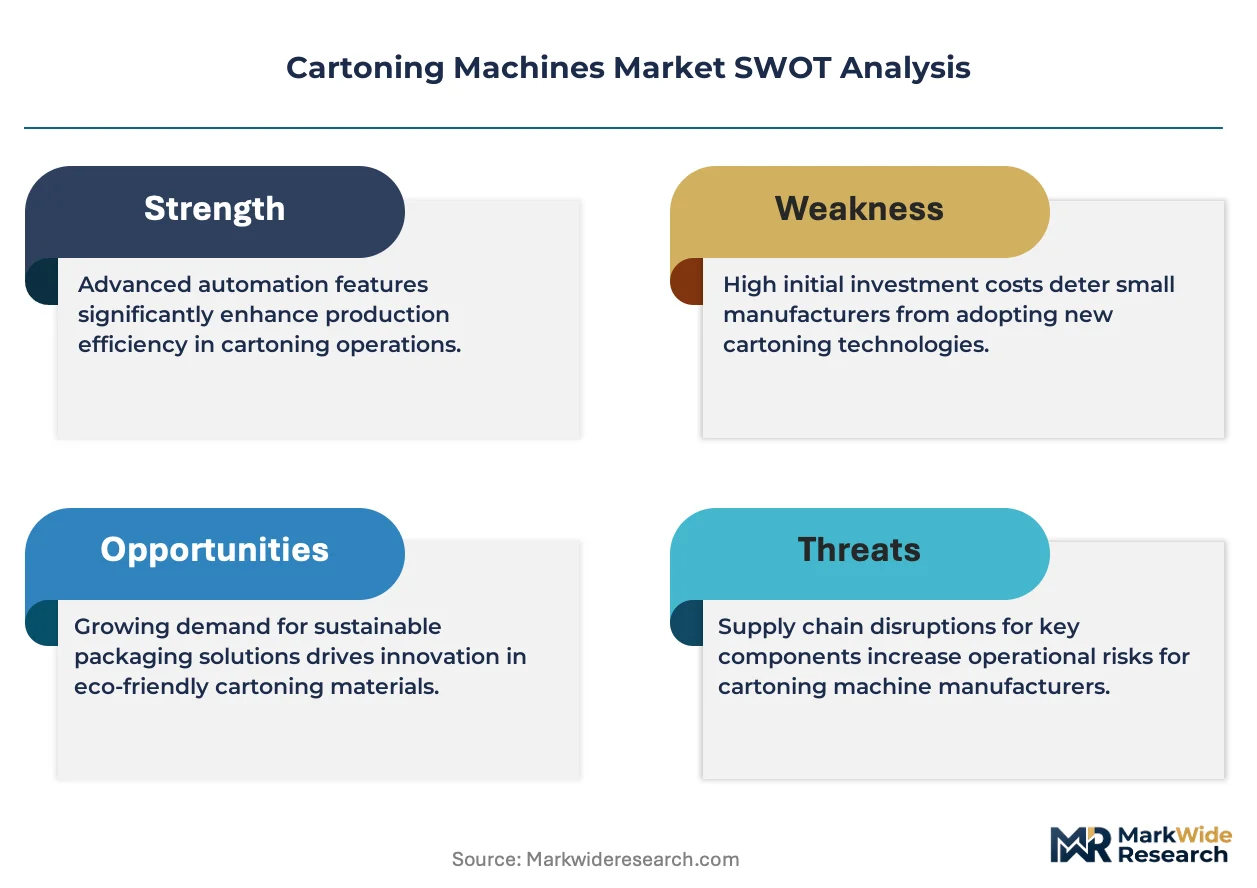
- Stainless steel and servo motor cost volatility:Input price swings for pharmaceutical-grade construction materials compress margin predictability for equipment builders serving regulated industries.
- Technical limitation in changeover speed:Mechanical complexity of format-part systems caps rapid product switching below pharmaceutical batch-size flexibility requirements, frustrating just-in-time production schedules.
- REACH adhesive compliance friction:Restricted substance lists for carton sealing chemistries force reformulation cycles that delay European market entry for non-compliant machinery configurations.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO serialization requirements and PLI scheme incentives are driving greenfield facility investments that specify integrated cartoning-serialization lines.
- Robotic loading module convergence:Collaborative robot integration with isolator technology opens sterile handling applications in high-potency oncology drug packaging previously reserved for manual operations.
- Outcome-based service contracts:Performance-guaranteed uptime agreements replace traditional maintenance models, locking in long-term revenue streams for OEMs with predictive diagnostics capabilities.
Industry Challenges
- Mechatronics technician scarcity:Shortage of engineers skilled in servo drive programming and vision system calibration extends commissioning timelines and inflates service costs.
- Legacy SCADA integration complexity:Brownfield pharmaceutical sites struggle to connect new cartoning lines with established manufacturing execution systems, requiring costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cartoning Machines Market |
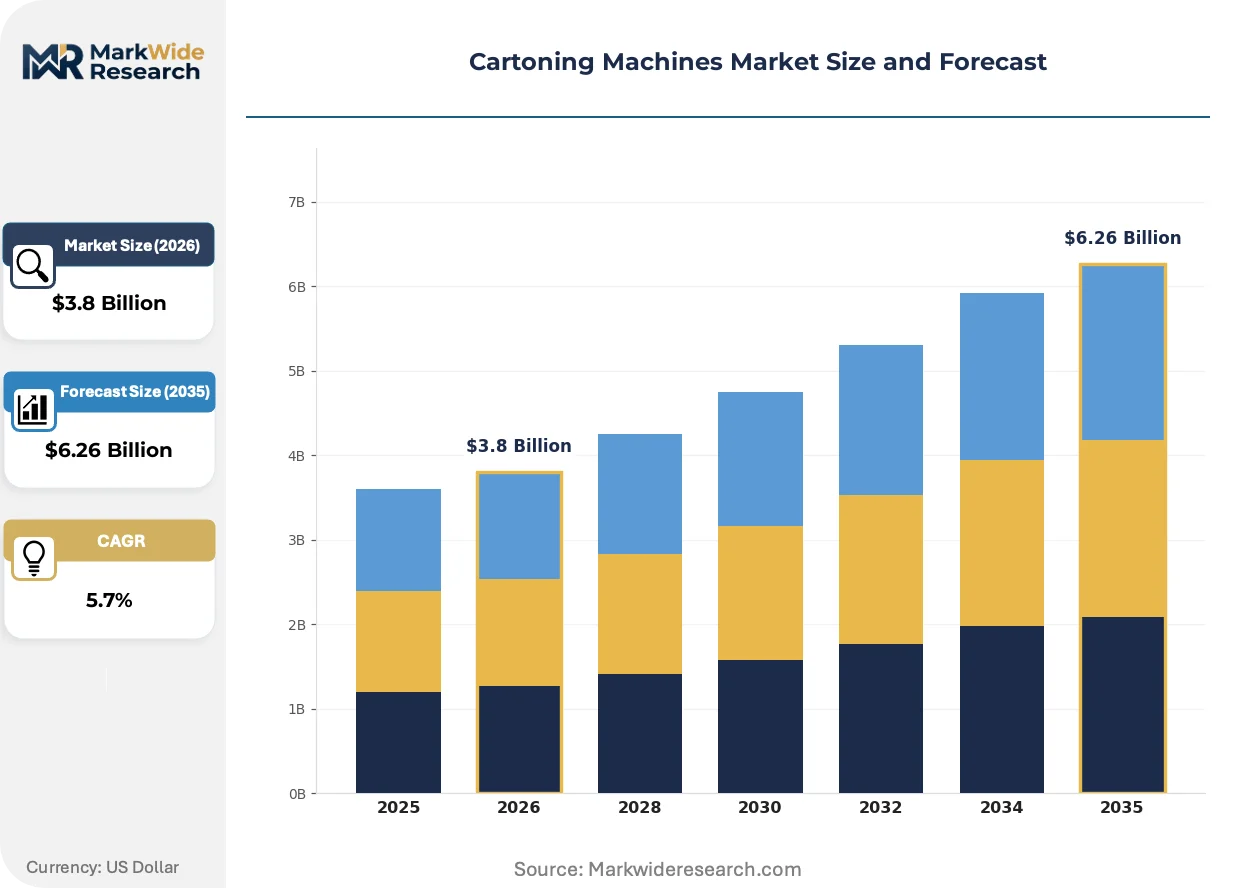
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Automatic, Semi-Automatic End User: Food & Beverage, Pharmaceuticals, Household Goods, Personal Care Technology: Robotic, Manual, Semi-Automated, Fully Automated Packaging Type: Box, Tray, Sleeve, Carton |
| Companies Covered | Krones AG, R.A. Jones, JOCHAMP Machinery, Wenzhou Jiade Packing Machinery, Shanghai Tops, IMA Group, Coesia Group, AIPAK, Syntegon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cartoning Machines Market Emerging Trajectories
Digital thread technologies and predictive maintenance architectures are displacing reactive service models, while regulatory serialization deadlines compress equipment procurement cycles toward turnkey integrated solutions.
Continuous motion cartoning technology is rendering obsolete intermittent-motion systems in high-volume beverage and food applications. Multinational bottlers in Germany and the Netherlands have standardized on continuous horizontal configurations operating above 400 units per minute. The technology is rendering obsolete mechanical cam-driven mechanisms in favor of servo-synchronized motion control that reduces vibration and extends component life.
EU MDR Article 16 and FDA DSCSA Phase II enforcement require line-level aggregation with parent-child serial number relationships. Pharmaceutical contract packagers in Ireland and Switzerland are specifying cartoning modules with integrated camera tunnels and reject verification stations. Solid-dose manufacturers face the steepest compliance burden, driving consolidation toward suppliers with pre-validated software stacks.
Buyer concentration among multinational pharmaceutical conglomerates has compressed equipment evaluation cycles from 18 months to 9 months. Procurement teams now mandate referenceable installations at three comparable facilities before technical approval. This pattern is most visible in German-speaking markets, where Bayer and Boehringer Ingelheim have standardized vendor qualification protocols across their European packaging networks.
Cartoning Machines Market Segmentation
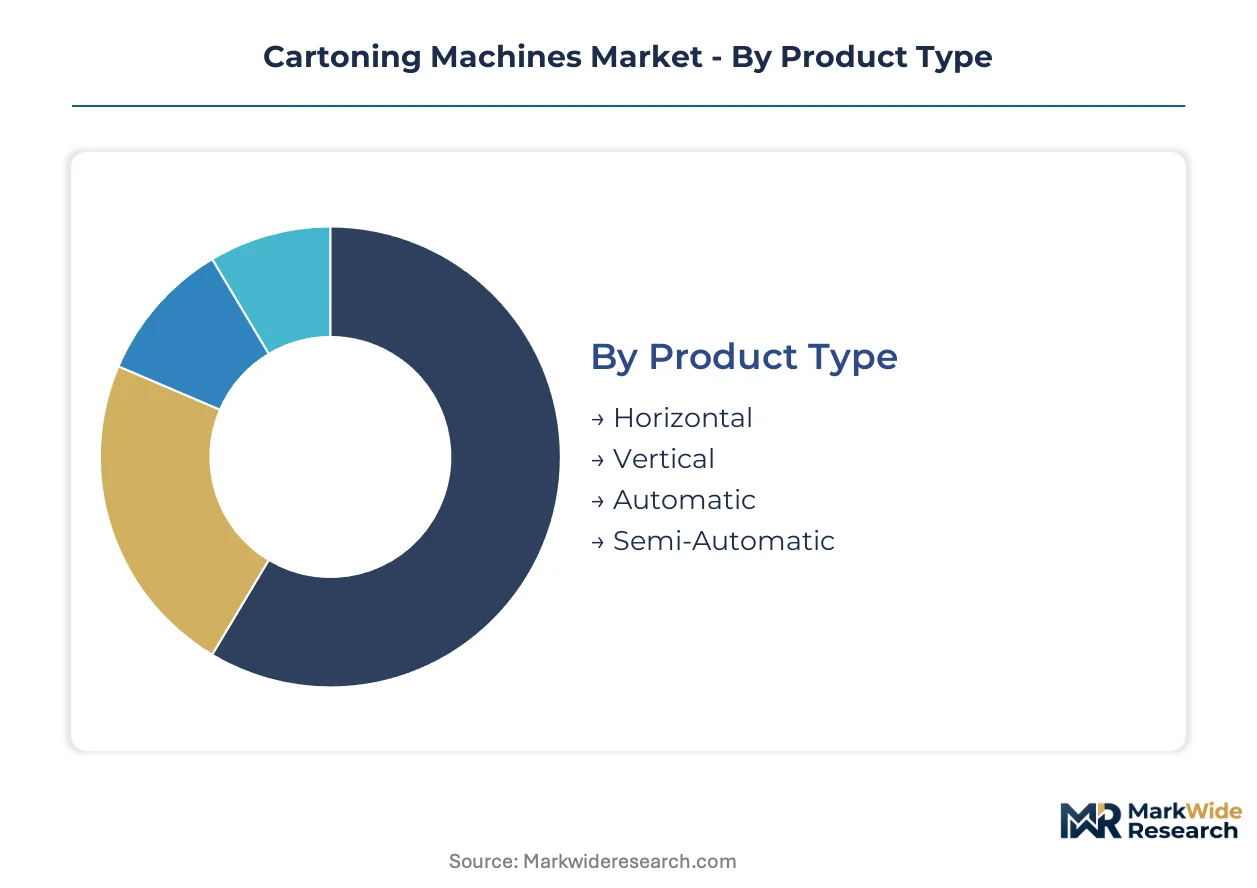
Cartoning machine procurement decisions pivot on after-sales service intensity, where pharmaceutical-grade installations demand 24/7 technical support contracts and rapid spare parts availability. Equipment segmentation reveals divergent margin profiles across automation tiers and end-use regulatory burdens. Buyers prioritize modular architectures that minimize commissioning downtime and extend operational life through predictive maintenance integration.
Product Type:
After-sales service intensity varies sharply across product configurations, with continuous-motion horizontal systems requiring specialized servo technicians and pharmaceutical-grade vertical units demanding isolator-qualified field engineers.
- Horizontal:Continuous-motion configurations synchronize multiple servo axes to maintain carton integrity through high-speed transfer points above 400 units per minute. Beverage bottlers in Germany and the Netherlands specify these systems for gentle handling of fragile containers, though vibration dampening and cam replacement cycles drive service contract premiums.
- Vertical:Gravity-fed loading mechanisms orient products for top-loading carton formation, dominating pharmaceutical applications where sterile product handling and isolator integration are mandatory. Solid-dose manufacturers in Switzerland and Ireland specify vertical systems with integrated aggregation tunnels to satisfy EU MDR serialization mandates.
- Automatic:Self-adjusting format parts and recipe-driven changeovers reduce operator intervention, concentrating demand among contract packagers serving multiple SKUs with compressed batch sizes.
- Semi-Automatic:Operator-fed loading stations suit low-volume specialty producers and pilot manufacturing facilities where capital constraints outweigh throughput requirements.
Horizontal configurations hold the largest share; momentum sits with vertical systems as pharmaceutical serialization deadlines tighten.
End User:
Cost tier differentiation separates premium pharmaceutical installations from standard food and beverage lines, with household goods and personal care occupying mid-tier positioning on automation and containment specifications.
- Food & Beverage:High-throughput horizontal cartoning lines handle fragile containers with gentle transfer mechanisms, with German multinational bottlers driving standardization toward servo-synchronized continuous motion above 400 units per minute.
- Pharmaceuticals:Integrated serialization-aggregation systems with camera tunnels and reject verification stations command premium pricing; EU MDR and FDA DSCSA compliance deadlines compress procurement cycles toward pre-validated turnkey solutions.
- Household Goods:Durable product handling permits simpler mechanical configurations, with demand concentrating in automated detergent and cleaning product packaging lines.
- Personal Care:Cosmetic and fragrance cartoning emphasizes gentle handling and premium finishing, with batch-size flexibility requirements favoring quick-changeover modular platforms.
Pharmaceuticals command the highest equipment margins; personal care is expanding most quickly as premium cosmetic brands automate secondary packaging.
Technology:
Volume concentration in fully automated lines reflects labor cost pressures and quality consistency demands, while robotic modules penetrate high-potency pharmaceutical applications previously reserved for manual operations.
- Robotic:Collaborative robot integration with isolator technology enables sterile handling of high-potency oncology drugs, eliminating human contact in containment-critical packaging operations.
- Manual:Operator-dependent loading persists in specialty pharmaceutical batches and artisanal food producers where flexibility outweighs throughput economics.
- Semi-Automated:Hybrid configurations balance capital efficiency with productivity gains, serving mid-tier contract packagers with variable batch requirements.
- Fully Automated:Servo-driven motion control and integrated vision inspection minimize changeover downtime, with pharmaceutical manufacturers specifying these lines for serialization-compliant production.
Fully automated technology dominates installed base; robotic loading shows the steepest expansion trajectory as sterile handling requirements proliferate.
Packaging Type:
Application-specific material handling properties dictate machinery selection, with carton forming complexity driving greater automation investment than tray or sleeve configurations.
- Box:Six-panel carton erection with glue or tuck closure dominates mainstream consumer goods packaging, with high-speed beverage applications demanding precision flap control.
- Tray:Open-top configurations suit display-ready retail packaging and secondary containment, with food service and club-store channels driving demand.
- Sleeve:Wrap-around banding applications concentrate in multi-pack beverage and personal care bundling, with shrink-sleeve integration expanding in premium cosmetic presentation.
- Carton:Folding carton formats with complex die-cut windows and premium finishing require gentle handling systems, concentrating demand in pharmaceutical patient information inserts and luxury goods.
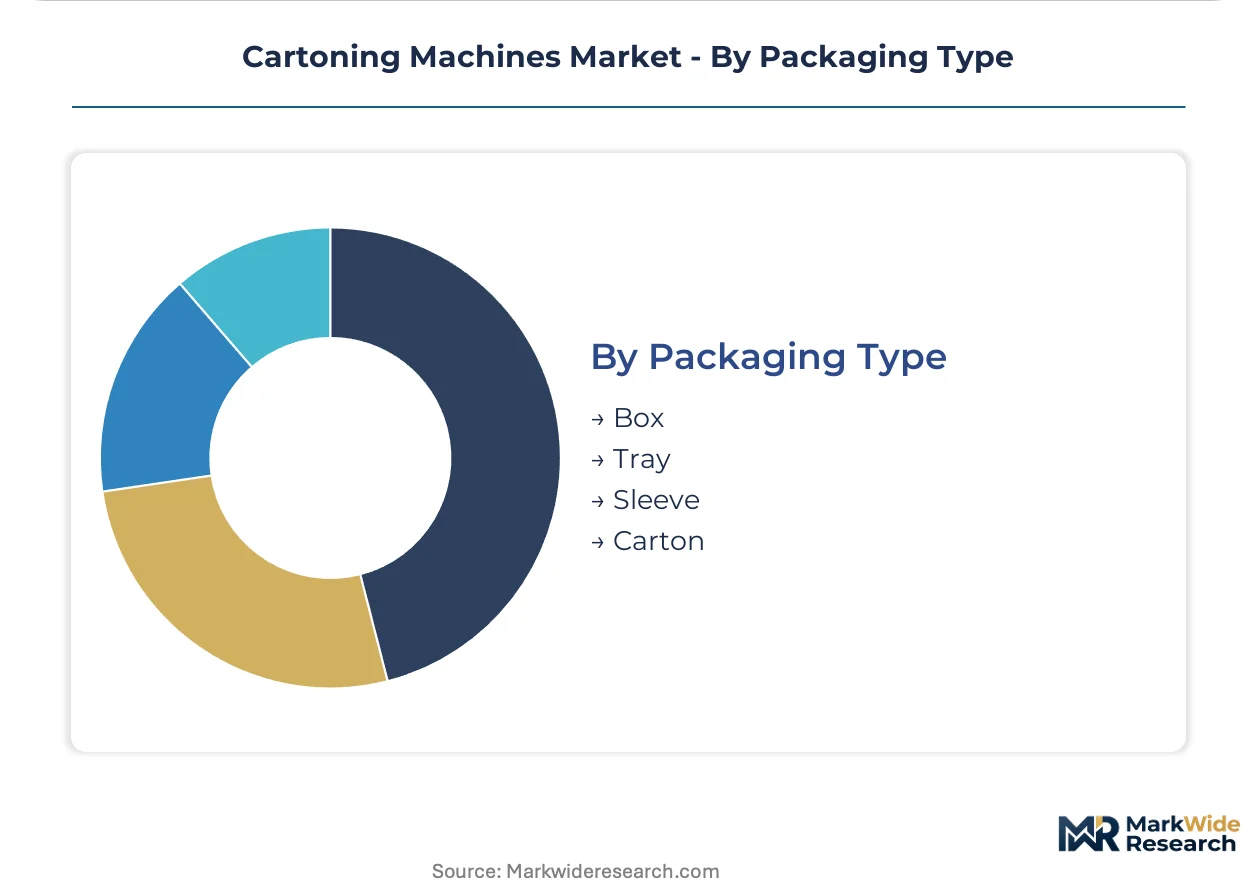
Box cartoning holds the largest share; sleeve applications are gaining share fastest as retail-ready multipack formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA serialization mandates and FDA enforcement timelines anchor pharmaceutical packaging investments in Germany and the United States, while machinery exports from Stuttgart and Cologne extend German engineering reach into Middle Eastern and Latin American markets.
Germany
Stuttgart-Cologne machinery clusters deliver short lead times for high-speed beverage cartoning lines serving multinational bottlers. REACH compliance on adhesive chemistries forces reformulation cycles for carton sealing systems bound for European markets. Krones AG leverages its beverage packaging heritage to anchor export competitiveness across regulated industries.
United States
FDA DSCSA Phase II enforcement compresses procurement cycles toward pre-validated turnkey cartoning solutions with aggregation hardware. Solid-dose manufacturers face steep compliance burdens for parent-child serial number relationships. Contract packagers in the Northeast and Midwest specify integrated camera tunnels and reject verification stations.
India
CDSCO serialization requirements and PLI scheme incentives drive greenfield pharmaceutical facility investments specifying integrated cartoning-serialization lines. Domestic machinery demand concentrates in Maharashtra and Gujarat where contract manufacturing organizations expand secondary packaging capacity. Local fabricators compete with European imports on cost-sensitive food and beverage applications.
Switzerland
Swissmedic oversight and high-value oncology drug packaging sustain premium positioning for vertical cartoning systems with isolator integration. Solid-dose manufacturers in Basel and Zurich specify robotic loading modules to eliminate human contact with high-potency products. IMA Group dominates blister-to-carton workflows serving orphan drug packaging requirements.
China
NMPA track-and-trace regulations and domestic pharmaceutical manufacturing expansion drive demand for automated cartoning lines in Jiangsu and Zhejiang provinces. Local machinery builders compete on cost while multinational OEMs serve joint-venture facilities requiring validated software stacks. Shanghai-based packagers prioritize batch-size flexibility for variable contract manufacturing schedules.
Cartoning Machines Market Vendor Landscape
Diversified packaging conglomerates and specialized pharmaceutical machinery builders split the market along regulatory complexity lines. Tiered competitive dynamics separate premium-tier suppliers with pre-validated serialization stacks from cost-optimized fabricators serving food and beverage applications. Two strategic archetypes dominate: integrated-line specialists capturing pharmaceutical compliance premiums, and high-volume horizontal cartoning suppliers anchoring beverage industry standardization. Competitive moves concentrate on M&A for serialization software capabilities and geographic expansion into Indian pharmaceutical manufacturing clusters.
Among Germany-based diversified packaging groups, Krones AG and Syntegon Technology exemplify the integrated-line specialist archetype with pharmaceutical-grade containment expertise. IMA Group anchors Italian machinery competitiveness in solid-dose cartoning workflows. Chinese fabricators including JOCHAMP Machinery and Wenzhou Jiade Packing Machinery occupy cost-competitive positions in regional food and beverage applications.
| Leading Market Players |
|---|
| Krones AG |
| R.A. Jones |
| JOCHAMP Machinery |
| Wenzhou Jiade Packing Machinery |
| Shanghai Tops |
| IMA Group |
| Coesia Group |
| AIPAK |
| Syntegon Technology |
| Others |
Supply Flow & Price Mechanics
Stuttgart-Cologne machinery clusters concentrate high-value cartoning capacity, translating engineering density into pricing power for pharmaceutical-grade systems while compressing margins on standardized beverage lines. EU MDR serialization mandates and FDA track-and-trace enforcement have shifted buyer procurement toward integrated turnkey solutions, amplifying premium capture for suppliers with pre-validated software stacks.
Pricing Analysis
Price spreads between German-engineered pharmaceutical lines and Asian-fabricated food-grade systems exceed threefold, with EU MDR compliance certification and 24/7 service bundling commanding substantial premia. Three-tier pricing structure across premium, standard, and economy levels separates isolator-integrated oncology systems from modular retrofit platforms and basic semi-automatic units. Cost compression in economy tiers intensifies because Chinese fabricators compete aggressively on lead times for beverage applications. Contract packagers serving multiple SKUs exhibit highest price sensitivity, while solid-dose manufacturers prioritize compliance over unit economics.
Supply Chain Analysis
Contract manufacturing concentration among Swiss and Irish pharmaceutical packagers anchors demand for vertical cartoning systems with integrated serialization tunnels. Component sourcing draws from Germany for precision servo drives, Italy for cam mechanisms and control systems, and China for structural steel frames and pneumatic elements. Single-source vulnerability in pharmaceutical-grade vision inspection modules creates supply risk given limited qualified suppliers for FDA-validated camera systems. Distribution runs through OEM-direct sales for large pharmaceutical accounts and machinery dealer networks serving mid-tier food and beverage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics technician scarcity constrains commissioning velocity and aftermarket service capacity, creating competitive differentiation for OEMs with captive training academies and predictive diagnostics platforms.
For Market Incumbents: Insulate pharmaceutical margins by deepening backward integration into serialization software stacks, reducing dependency on third-party aggregation module suppliers. Accelerate servo drive calibration automation to offset technician scarcity that extends commissioning timelines. Prioritize outcome-based service contracts with guaranteed uptime clauses to lock in recurring revenue streams and deter modular retrofit competitors. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-compliant pharmaceutical packaging segment where PLI scheme incentives drive greenfield facility investments and European OEMs face cost disadvantages. Target Maharashtra and Gujarat contract manufacturing clusters with localized service presence and rapid spare parts logistics. Differentiate through batch-size flexibility configurations that address variable contract manufacturing schedules prevalent in domestic pharmaceutical operations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized pharmaceutical packaging divisions lacking integrated serialization capabilities. Long-term viability hinges on software-defined service architectures that transition revenue from equipment sales to performance-guaranteed uptime agreements. Monitor FDA DSCSA enforcement intensity and EU MDR aggregation deadline compliance rates as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Software Stack Acquisition | Pre-validated aggregation modules command pharmaceutical compliance premia and reduce third-party dependency. |
| Robotic Loading Module Development | Collaborative robot integration with isolator technology opens sterile oncology applications previously manual. |
| Indian Manufacturing Footprint Expansion | CDSCO requirements and PLI incentives create localized demand for integrated cartoning-serialization lines. |
| Outcome-Based Service Contract Rollout | Performance-guaranteed uptime agreements replace transactional maintenance and lock in long-term revenue. |
| Predictive Maintenance Platform Deployment | AI-powered diagnostics reduce false rejection rates and enable real-time quality adjustments for pharmaceutical lines. |
Methodological Framework
A spread of perspectives from packaging machinery OEMs, pharmaceutical contract packagers, mechatronics service technicians, and regulatory affairs specialists converged on the working assumptions governing equipment procurement cycles and compliance investment timelines. Primary field engagement combined structured interviews with plant engineers at solid-dose manufacturing facilities and aftermarket service heads at German machinery clusters. Secondary validation drew from FDA DSCSA guidance documents, EMA MDR implementation reports, VDMA machinery production statistics, and customs trade data for packaging equipment imports. Bottom-up demand modeling across end-use segments was cross-checked against top-down capacity estimates from Stuttgart-Cologne production hubs.
Demand-supply-balance framing anchored the analytical approach, with pharmaceutical serialization deadline impacts modeled against stainless steel and servo motor input cost trajectories. Segmentation dimensions included product configuration (horizontal versus vertical), automation tier (manual through fully automated), end-use regulatory burden (pharmaceutical versus food versus personal care), and geographic compliance cluster (EU MDR, FDA DSCSA, CDSCO, NMPA). CAGRs were derived from equipment replacement cycle analysis and greenfield facility investment pipelines. Industry-specific forecast inputs incorporated REACH adhesive compliance friction and mechatronics technician wage inflation.
Stress conditions across raw material cost volatility, regulatory deadline acceleration, and technician availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding serialization hardware adoption curves and pharmaceutical batch-size flexibility requirements. Quarterly review of FDA DSCSA enforcement actions, EU MDR audit findings, and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Tetrahedron Carton Market
Cartons
End Load Cartoning Machine Market
Cartons
Shaped Liquid Cartons Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Metallized Folding Cartons Market
Cartons
Carton Serialization Machine Market
Cartons
Microwaveable Carton Market
Cartons
Folding Carton in Healthcare Market
Cartons
Pizza Cartons Market
Cartons
North America Corrugated Boxes Market
Cartons
Child-Resistant Carton Box Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Carton Sealer Market
Cartons
Tablet Cartons Market
Cartons
Folding Cartons Market