
 XXL Packaging Market | 2026-2036
XXL Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
XXL Packaging Market Analytics
Heavy-duty corrugated specifications for loads exceeding 500 kilograms is unwinding legacy commodity pricing across the XXL packaging landscape. Smurfit Kappa Group leverages integrated pulp-to-box operations across European ports to control input costs for industrial clients. DS Smith anchors its position through closed-loop recycling partnerships with major beverage bottlers, while WestRock competes via automated box-plant scale in North American manufacturing corridors.
XXL packaging denotes engineered containment and transport systems dimensioned beyond standard ISO pallet footprints, typically fabricated from multi-wall corrugated, thermoformed HDPE, or steel-reinforced composite materials rated for axial loads above one metric ton. These solutions protect capital-intensive goods during intermodal transit and long-cycle warehousing across chemical, aerospace, and construction supply chains. Bulk bags dominate volume flows in agricultural and mineral bulk handling where flexographic printing and UV-stabilized polypropylene tapes extend field service life. Composite materials capture expanding margin pools as aerospace OEMs specify carbon-fiber hybrid crates that reduce tare weight while maintaining ATA 300 Category I impact standards.
EPA hazardous materials packaging regulations and the EU Packaging and Packaging Waste Directive (PPWD) enforce recyclability thresholds and substance restrictions that filter market access for non-compliant imports. China's GB/T standards for transport packaging and the US Department of Transportation's 49 CFR hazmat rules further segment certification requirements by corridor and cargo class. Stakeholders must monitor evolving extended producer responsibility frameworks and material passport mandates that will determine which substrate-material combinations retain logistics-provider approval without retrofit cost penalties.
Market Dynamics
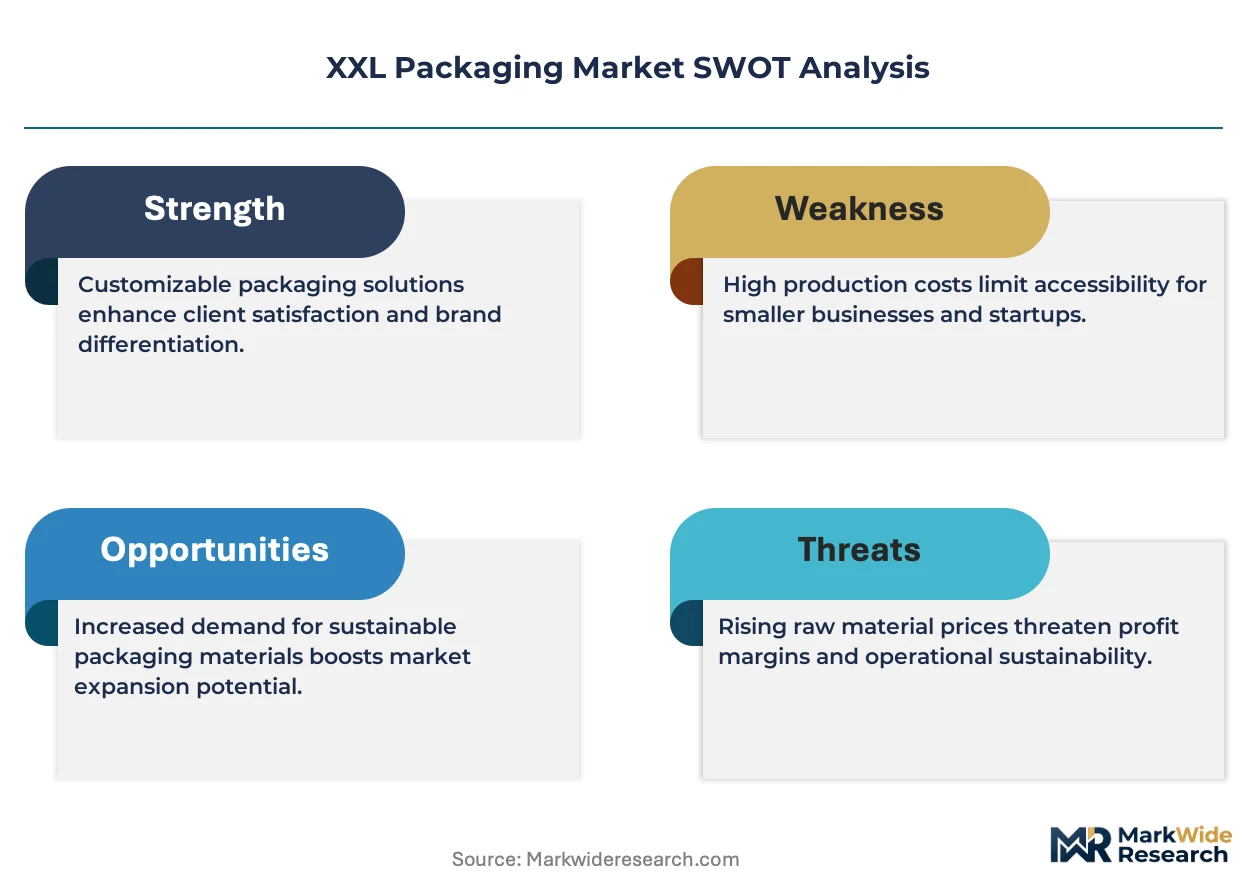
REACH substance restrictions and evolving EPA hazardous materials rules are forcing substrate substitutions across XXL packaging supply chains, compressing margins for non-compliant converters while creating certification premiums for engineered alternatives.
Growth Catalysts
- EU Packaging and Packaging Waste Directive recyclability mandates:Germany's industrial corridor demands closed-loop corrugated systems for automotive parts logistics, pulling investment into multi-wall board recycling infrastructure.
- Carbon-fiber hybrid crate specifications:Aerospace OEMs specify ATA 300 Category I compliant containment that reduces tare weight below steel alternatives for satellite and engine transport.
- China's export manufacturing zones:Petrochemical and heavy machinery clusters along the Yangtze River Delta drive bulk container demand for intermodal shipment to European and North American ports.
Market Restraints
- OCC pulp price volatility:Old corrugated containerboard input costs swing with Chinese import quotas, destabilizing converter margins for heavy-duty multi-wall specifications.
- HDPE resin supply concentration:Gulf Coast petrochemical hub disruptions from hurricane exposure concentrate thermoformed bulk container production risk in a single geography.
- Steel-reinforced composite weight penalties:Traditional metal hybrid crates face tare weight disadvantages against emerging fiber-reinforced alternatives in air freight applications.
Strategic Opportunities
- Extended producer responsibility frameworks:France's AGEC law and similar EU national implementations create material passport service revenue streams for packaging-as-a-service providers.
- Digital printing on flexographic bulk bags:UV-stabilized polypropylene substrates now accept variable-data branding for agricultural co-ops seeking supply chain traceability.
- Modular collapsible IBC systems:Chemical distributors in the US Gulf Coast adopt foldable intermediate bulk containers that reduce backhaul empty mileage by sixty percent.
Industry Challenges
- Structural engineer talent scarcity:Finite element analysis expertise for load-rated containment design concentrates among aging specialists in German and Japanese packaging institutes.
- UN certification timeline compression:DOT 49 CFR hazmat packaging approvals stretch eighteen to twenty-four months, delaying product launches for composite drum innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | XXL Packaging Market |
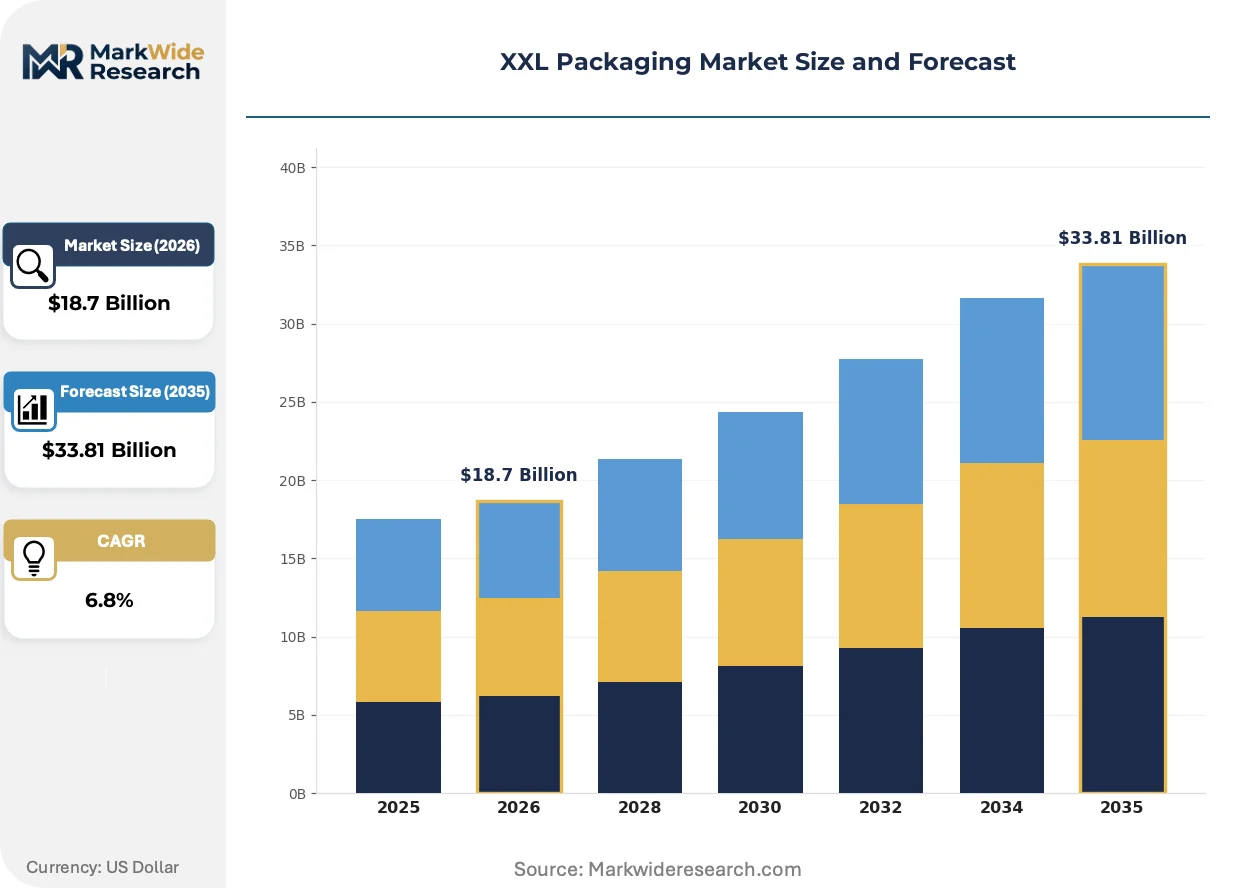
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Bags, Stretch Film, Pallet Wrap, Crates Material: Plastic, Wood, Metal, Composite End User: Aerospace, Chemical, Food & Beverage, Construction Application: Storage, Shipping, Transportation, Warehousing |
| Companies Covered | Smurfit Kappa Group, DS Smith, Canpak Packaging, ROBA Group, Sonoco, Georgia-Pacific, WestRock, Schur Pack, Graphic Packaging Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
XXL Packaging Market Evolving Landscape
Material science convergence with digital supply chain tracking is collapsing the traditional trade-off between containment strength and logistics visibility. Three developments command strategic attention.
Reusable RFID-embedded bulk containers are displacing single-use corrugated for closed-loop automotive component circuits between Mexico assembly plants and US Midwest stamping facilities. Tier-one suppliers at BMW's Spartanburg and Mercedes-Benz's Tuscaloosa operations now mandate scan-at-unload accountability, compressing inventory reconciliation cycles from days to hours. This visibility premium is displacing commodity-priced expendable packaging in just-in-time sequences where stockout costs exceed container amortization.
EPA's forthcoming updates to 40 CFR 262 hazardous waste generator rules will tighten secondary containment requirements for chemical transport packaging. Bulk intermediate container manufacturers serving the Texas-Louisiana petrochemical corridor face reformulation deadlines for UV-stabilized HDPE to meet leachate testing protocols. The regulatory friction most impacts small-batch specialty chemical distributors lacking in-house compliance teams, pushing them toward certified third-party logistics packaging services.
Buyers in capital equipment sectors now unbundle packaging specification from OEM procurement, engaging directly with engineered containment specialists for multimodal export crating. German machine tool exporters and Japanese precision equipment manufacturers increasingly source ATA 300 certified crates through independent packaging engineers rather than accepting default OEM solutions. This disintermediation concentrates in high-value aerospace and medical device verticals where damage-in-transit claims exceed packaging spend by orders of magnitude.
XXL Packaging Market Segmentation
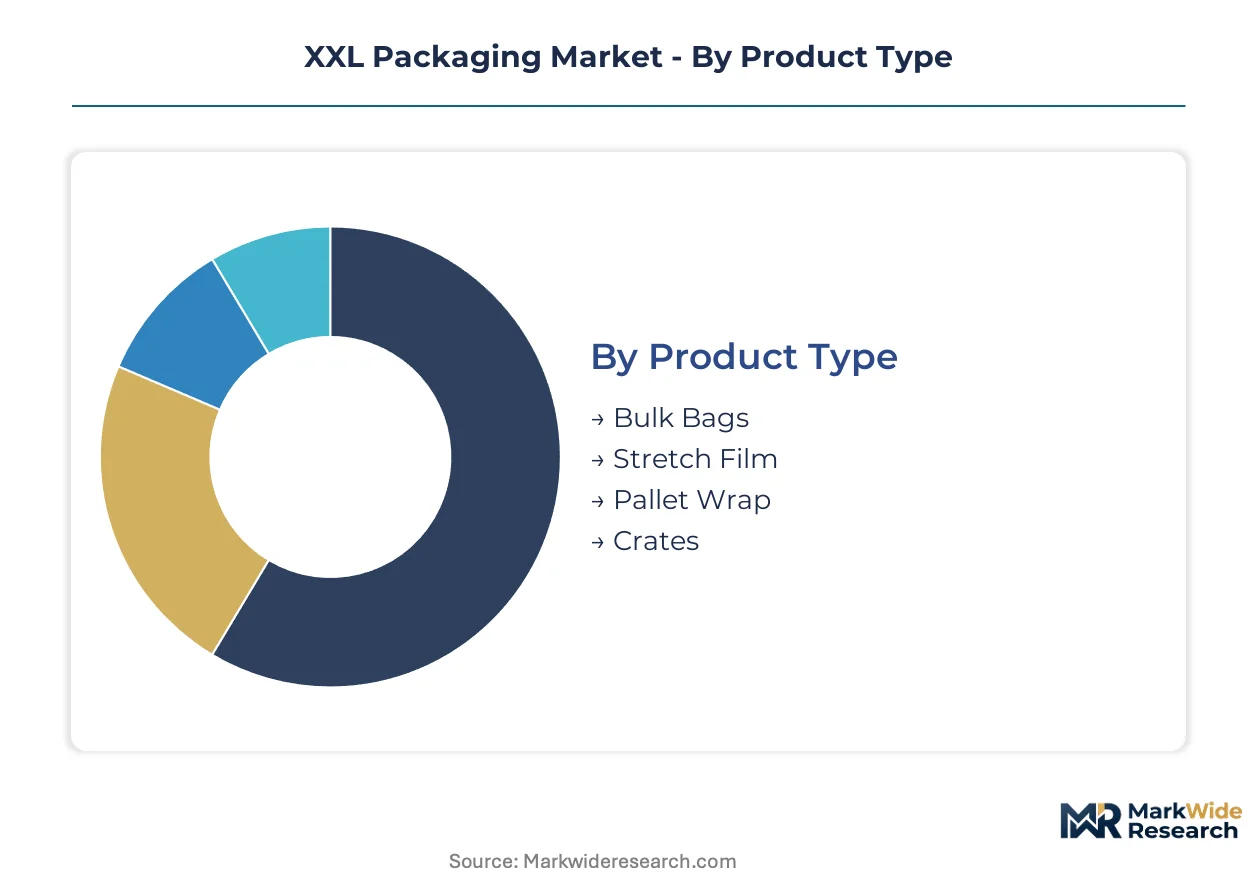
Regulatory divergence across jurisdictions fragments XXL packaging procurement, as REACH substance restrictions, EPA hazmat rules, and China's GB/T standards each favor different material combinations. Buyers must align segment selection with corridor-specific certification requirements rather than optimizing for unit cost alone.
Product Type:
REACH and EPA substance restrictions favor bulk bags with UV-stabilized polypropylene over PVC-laminated alternatives, while ATA 300 certification requirements for aerospace logistics elevate engineered crates above commodity containers.
- Bulk Bags:Woven polypropylene or polyethylene constructions rated for one-ton axial loads dominate agricultural mineral handling and petrochemical powder transport. Yangtze River Delta export zones pull heavy specifications for intermodal shipment to Hamburg and Rotterdam, with flexographic printing enabling co-op traceability branding.
- Crates:Multi-wall corrugated, thermoformed HDPE, or carbon-fiber hybrid assemblies protect capital-intensive goods during long-cycle warehousing. Aerospace OEMs specify ATA 300 Category I impact standards for satellite and engine transport, driving carbon-fiber adoption to reduce tare weight below steel-reinforced alternatives.
- Stretch Film:Linear low-density polyethylene formulations with cling additives secure palletized loads against moisture and dust intrusion.
- Pallet Wrap:Machine-grade cast film with pre-stretch capability reduces material consumption per wrapped unit in high-volume distribution centers.
Bulk Bags handle the majority of throughput; Crates are expanding most quickly on share as aerospace and medical device verticals disintermediate OEM procurement.
Material:
Cost tier stratification separates commodity substrates from engineered composites, with certification premiums widening the gap between compliant and non-compliant supply sources.
- Plastic:Thermoformed HDPE and injection-molded polypropylene dominate collapsible IBC systems and bulk containers. US Gulf Coast petrochemical corridor concentration exposes supply to hurricane disruption risk, pushing chemical distributors toward inventory buffers or dual-sourcing strategies.
- Composite:Carbon-fiber hybrid and glass-reinforced polymer constructions achieve strength-to-weight ratios impossible with homogeneous materials. German machine tool exporters and Japanese precision equipment manufacturers specify these for multimodal export crating where damage claims exceed packaging spend by orders of magnitude.
- Wood:ISPM-15 heat-treated hardwood and engineered plywood remain standard for heavy machinery crating despite weight penalties in air freight.
- Metal:Steel-reinforced frames and wire mesh containers persist in closed-loop automotive circuits but face displacement by RFID-embedded plastic alternatives.
Plastic commands the volume base; Composite substrates are climbing the fastest as aerospace and capital equipment specifications tighten.
End User:
Application severity and liability exposure determine packaging specification intensity, with aerospace and chemical sectors driving engineered containment premiums.
- Chemical:EPA 40 CFR 262 hazardous waste generator rules and forthcoming secondary containment mandates force reformulation of UV-stabilized HDPE for leachate compliance. Texas-Louisiana petrochemical corridor distributors face deadline pressure, pushing specialty chemical handlers toward certified third-party logistics packaging services.
- Aerospace:ATA 300 Category I certification requirements for satellite, engine, and airframe component transport specify impact-resistant containment with documented test protocols. Boeing's Charleston and Airbus's Mobile assembly plants mandate scan-at-unload accountability, compressing inventory reconciliation cycles.
- Construction:Heavy machinery and prefabricated module transport drives demand for steel-reinforced and engineered wood crating rated for construction site handling abuse.
- Food & Beverage:EU Packaging and Packaging Waste Directive recyclability thresholds and FDA food-contact compliance constrain material selection for bulk ingredient handling.
Chemical sector procurement dominates absolute spend; Aerospace specifications are gaining share fastest as damage-in-transit liability concentrates buyer attention.
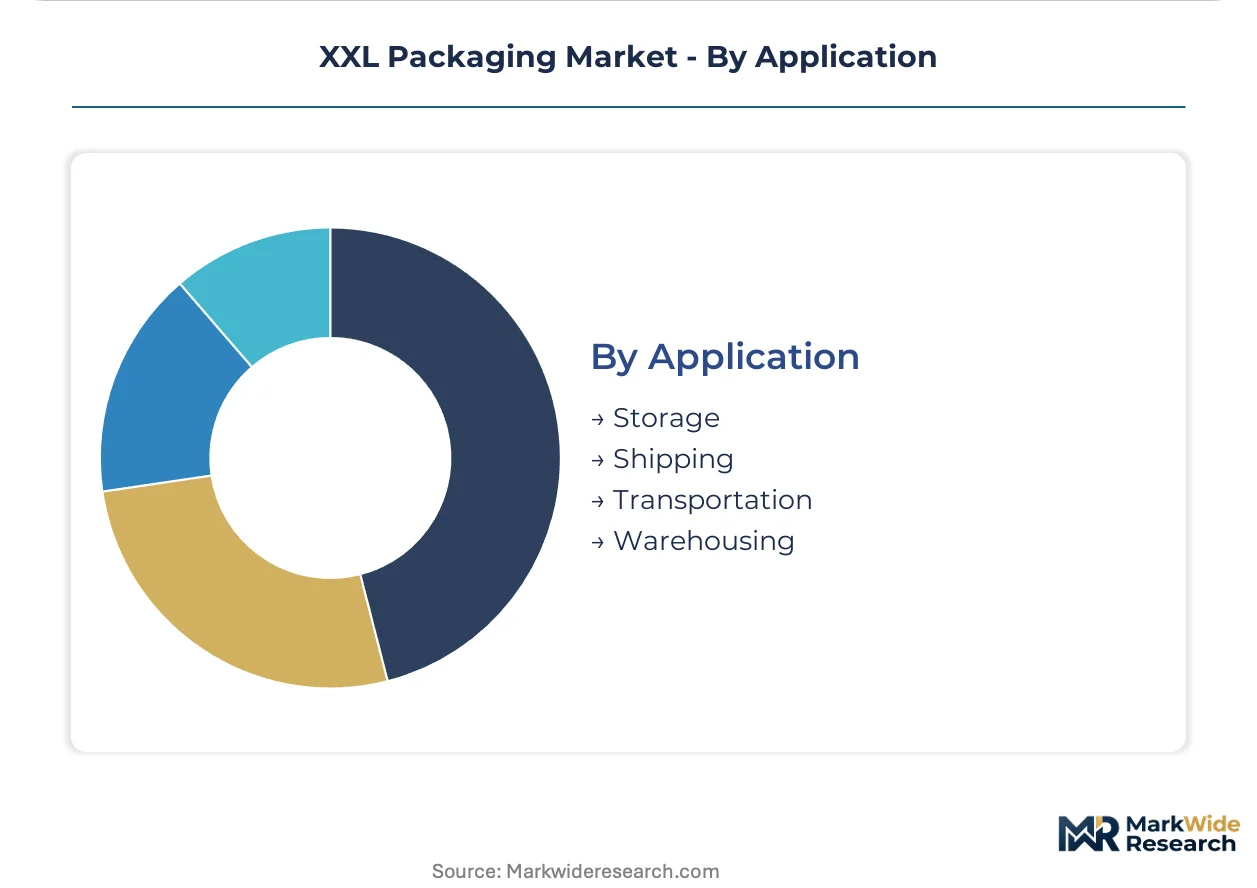
Application:
Customer type bifurcation separates just-in-time manufacturing circuits from long-cycle project logistics, with visibility requirements diverging procurement patterns.
- Transportation:Intermodal transit from China's export manufacturing zones to European and North American ports demands weather-resistant containment with forklift and crane handling compatibility. Multi-wall corrugated and woven bulk bags face salt spray and humidity exposure across ocean legs.
- Warehousing:Long-cycle storage of capital equipment and spare parts drives specification for stackable, moisture-barrier containment. German automotive component pools and US Midwest stamping facilities adopt reusable RFID-embedded containers to compress inventory reconciliation from days to hours.
- Shipping:Export crating for German machine tool and Japanese precision equipment manufacturers increasingly sources through independent packaging engineers rather than default OEM solutions.
- Storage:Static containment for agricultural minerals and petrochemical feedstocks prioritizes UV stabilization and field service life over handling frequency.
Transportation absorbs the highest unit volume; Warehousing applications are expanding most quickly as closed-loop automotive circuits displace single-use expendable packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across industrial corridors reshape XXL packaging procurement patterns. Heavy machinery shipments from Germany and petrochemical exports from the US Gulf Coast drive premium containment specifications, while China's manufacturing zones pull bulk container volumes for intermodal transit.
Germany
Automotive component logistics and machine tool exports anchor demand for ATA 300 certified crates. REACH substance restrictions filter material selections across Baden-Württemberg and Bavaria. Stuttgart's industrial corridor concentrates closed-loop corrugated systems for BMW and Mercedes-Benz just-in-time circuits.
United States
EPA 40 CFR hazardous materials rules and petrochemical export growth drive bulk intermediate container specifications. Hurricane exposure in the Gulf Coast concentrates HDPE resin supply risk for chemical distributors. Texas-Louisiana corridor distributors face reformulation deadlines for UV-stabilized containment.
China
GB/T transport packaging standards and Yangtze River Delta export manufacturing pull heavy-duty bulk bag specifications. Dual carbon goals reshape material recyclability mandates for intermodal shipment to European ports. Shanghai-Ningbo cluster drives flexographic-printed polypropylene demand for agricultural co-op traceability.
France
AGEC law extended producer responsibility frameworks create material passport service revenue streams. ECHA compliance pressures filter non-compliant substrate imports through Le Havre and Marseille-Fos corridors. Île-de-France logistics providers adopt certified packaging-as-a-service models for chemical distributors.
Japan
METI industrial standards and precision equipment export specifications elevate engineered composite crating. JIS certification requirements segment procurement for semiconductor and medical device logistics. Chubu-Nagoya manufacturing belt sources multimodal export containment through independent packaging engineers.
XXL Packaging Market Competitive Landscape
Concentration sits with integrated pulp-to-box operators and specialty engineered containment fabricators. Three archetypes dominate: European port-anchored integrated producers, North American automated box-plant scale operators, and composite material specialists serving aerospace certification requirements. Competitive moves center on closed-loop recycling partnerships and RFID-embedded reusable container platforms.
Within the integrated producer tier, Smurfit Kappa Group and DS Smith represent European port-anchored operations controlling input costs through captive pulp supply. WestRock occupies a position among North American scale-driven fabricators. These named entities exemplify the structural divide between commodity corrugated volume and engineered containment premiums.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith |
| Canpak Packaging |
| ROBA Group |
| Sonoco |
| Georgia-Pacific |
| WestRock |
| Schur Pack |
| Graphic Packaging Holding |
| Others |
Value Network & Pricing Analysis
Carbon-fiber hybrid crate adoption displacing steel-reinforced alternatives simultaneously shifts supply geography toward German and Japanese composite specialists while compressing pricing premiums for legacy metal-hybrid fabricators serving aerospace logistics corridors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in XXL packaging procurement. Certification grade for ATA 300 compliance and volume scale commitments differentiate price bands, with aerospace OEMs showing least price sensitivity due to damage-in-transit liability exposure. Cost compression in commodity corrugated tiers is intensifying because Old Corrugated Containerboard pulp costs swing with Chinese import quota volatility. Specialty chemical distributors in the US Gulf Coast corridor demonstrate highest price sensitivity, pushing toward certified third-party logistics packaging services.
Supply Chain Analysis
Hurricane exposure in the Gulf Coast petrochemical corridor underwrites concentrated thermoformed HDPE resin supply risk for bulk intermediate container manufacturers. Production gravity centers on Germany's industrial corridor for engineered composite crating, China's Yangtze River Delta for woven polypropylene bulk bags, and the US Texas-Louisiana hub for chemical-grade HDPE formulations. Raw material flows draw from Saudi Arabian petrochemical feedstocks, Brazilian pulp plantations, and Japanese carbon-fiber precursor supply. Single-source vulnerability concentrates in Gulf Coast resin production exposed to Atlantic hurricane disruption. Distribution runs through European port-anchored integrated producers, North American automated box-plant networks, and Asia-Pacific export manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated aerospace OEMs and automotive tier-one suppliers, as procurement centralization across BMW's Spartanburg and Mercedes-Benz's Tuscaloosa operations compresses supplier margins while elevating certification requirements.
For Market Incumbents: Secure closed-loop recycling partnerships with major beverage bottlers and automotive manufacturers to defend against emerging packaging-as-a-service providers. Backward integration into captive pulp supply across European ports controls input cost volatility from Chinese OCC import quotas. Certification investment in ATA 300 Category I compliance creates switching costs for aerospace OEM accounts. For New Entrants and Emerging Players: Lead with modular collapsible IBC systems targeting specialty chemical distributors in the US Gulf Coast corridor lacking in-house EPA 40 CFR compliance teams. The most penetrable white space sits with RFID-embedded reusable container platforms for just-in-time automotive circuits between Mexico assembly plants and US Midwest stamping facilities. A direct sales model engaging independent packaging engineers bypasses entrenched OEM procurement relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European corrugated converters lacking engineered composite capabilities for aerospace certification requirements. Long-term viability over a five-to-ten year window favors substrate-diversified platforms with exposure to both commodity volume and premium containment specifications. Watch for extended producer responsibility framework implementation velocity across EU member states as inflection indicator for packaging-as-a-service revenue model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Smurfit Kappa's European port operations control OCC input costs for industrial clients. |
| ATA 300 Certification Investment | Carbon-fiber hybrid crates meet Boeing Charleston impact standards for satellite transport. |
| RFID-Embedded Container Platforms | Tier-one suppliers at BMW Spartanburg mandate scan-at-unload inventory accountability. |
| Closed-Loop Recycling Partnerships | DS Smith's beverage bottler agreements secure volume commitments against commodity volatility. |
| Packaging-as-a-Service Model Launch | France's AGEC law creates material passport revenue streams for logistics providers. |
Research Methodology
Initial hypotheses were tested against primary input from packaging procurement managers at aerospace OEMs, chemical distribution executives, automotive tier-one supplier logistics directors, and engineered containment design engineers, then refined through secondary validation against EPA 40 CFR regulatory filings, EU Packaging and Packaging Waste Directive implementation reports, ATA 300 certification test protocols, and customs trade data for bulk bag imports. Bottom-up volume estimates from end-use application segments triangulated against top-down market sizing from substrate production capacity.
Variance decomposition across the projection horizon isolates growth contributions from regulatory compliance mandates, substrate substitution dynamics, and closed-loop adoption rates. Segmentation dimensions modeled include product type, material substrate, end-use vertical, and application mode. CAGRs were derived from logistic curve fitting to adoption saturation levels for RFID-embedded reusable containers and composite material penetration in aerospace logistics.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement stringency and EPA hazardous materials rule implementation would require recalibration. Practitioners should keep alternative scenarios live as extended producer responsibility framework adoption and carbon-fiber precursor supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Cardboard Crates Market
Cartons
Litho Laminated Cartons Market
Cartons
Global Cartonboard Market
Cartons
Braille Cartons Packaging Market
Cartons
Carton Sealer Market
Cartons
Mailers Market
Cartons
Metallized PET Cartons Market
Cartons
Africa Folding Carton Market
Cartons
Beverage Cartoners Market
Cartons
Global Folding Carton Packaging Market
Cartons
Europe Corrugated Box Market
Cartons
Soap Boxes Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Brick Carton Packaging Market
Cartons
Folding Carton in Healthcare Market