
 Beryllium Market | 2026-2036
Beryllium Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Market Intelligence
Specialized metallurgical expertise is unwinding capacity constraints across the beryllium supply chain as aging technician cohorts retire faster than training pipelines replenish. Materion Corporation leverages captive mining and refining assets in Utah to sustain North American supply security. IBC Advanced Alloys anchors its position through precision casting capabilities for defense-grade beryllium-aluminum components. NGK Metals Corporation competes via integrated copper-beryllium strip and wire production serving semiconductor probe card markets.
Beryllium is a lightweight alkaline earth metal with atomic number 4, density of 1.85 g/cm³, and the highest stiffness-to-weight ratio among structural metals, making it indispensable for precision instruments, aerospace structures, and nuclear moderators where dimensional stability under thermal stress is critical. Beryllium copper alloys dominate current revenue pools due to their non-sparking properties and fatigue resistance in oilfield and electronic connector applications. Beryllium oxide ceramics command premium positioning in high-thermal-conductivity substrates for radar and satellite systems. Aerospace and defense end-use channels absorb the majority of primary metal volumes, while electronics applications in semiconductor manufacturing equipment represent the fastest-growing demand segment.
The EPA regulates beryllium workplace exposure under 40 CFR Part 745, while OSHA enforces permissible exposure limits that shape fabrication economics and outsourcing decisions for downstream processors. The Department of Energy maintains strategic stockpile requirements that directly influence domestic production scheduling and price formation. REACH restrictions in Europe constrain import pathways for non-EU refined material, redirecting trade flows toward compliant producers. Stakeholders must monitor evolving toxicity classification debates and alternative material substitution thresholds in next-generation defense and space platforms.
Market Dynamics
Defense procurement for missile guidance systems is accelerating beryllium alloy consumption while EPA and OSHA toxic substance frameworks tighten extraction protocols, elevating compliance costs and concentrating supply among integrated producers with captive refining assets.
Growth Catalysts
- Nuclear modernization programs:The Department of Energy maintains strategic stockpile requirements that directly influence domestic production scheduling and sustain long-term offtake for primary metal.
- REACH restrictions in Europe:Import constraints for non-EU refined material redirect trade flows toward compliant producers, reinforcing North American supply security.
- Semiconductor manufacturing equipment:Electronics applications in probe card assemblies and thermal management substrates represent expanding demand channels for beryllium copper alloys.
Market Restraints
- Input cost volatility:Specialized metallurgical expertise shortages constrain capacity expansion as aging technician cohorts retire faster than training pipelines replenish.
- Supply concentration risk:Domestic production gravity centers on Utah mining and refining complexes, creating geographic vulnerability to localized disruption.
- Substitution threat:Alternative materials in next-generation defense and space platforms threaten displacement thresholds for beryllium oxide ceramics in satellite thermal management.
Strategic Opportunities
- Emerging aerospace structures:Dimensional stability requirements under thermal stress in next-generation launch vehicles expand addressable volume for primary beryllium metal.
- Technology convergence:Additive manufacturing integration with precision casting capabilities enables complex beryllium-aluminum component geometries previously unattainable through conventional methods.
- Regulatory tailwind:The IRA domestic content provisions incentivize onshore production of critical minerals, aligning with established North American refining infrastructure.
Industry Challenges
- Metallurgical skill attrition:Specialized beryllium handling and alloy formulation expertise is concentrating among diminishing practitioner pools as retirement outpaces apprenticeship completion.
- Compliance timeline compression:Evolving toxicity classification debates under OSHA permissible exposure limits force rapid process reconfiguration for downstream fabricators.
- Certification complexity:Defense-grade material qualification protocols extend validation cycles for new production entrants, entrenching incumbent supplier positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Market |
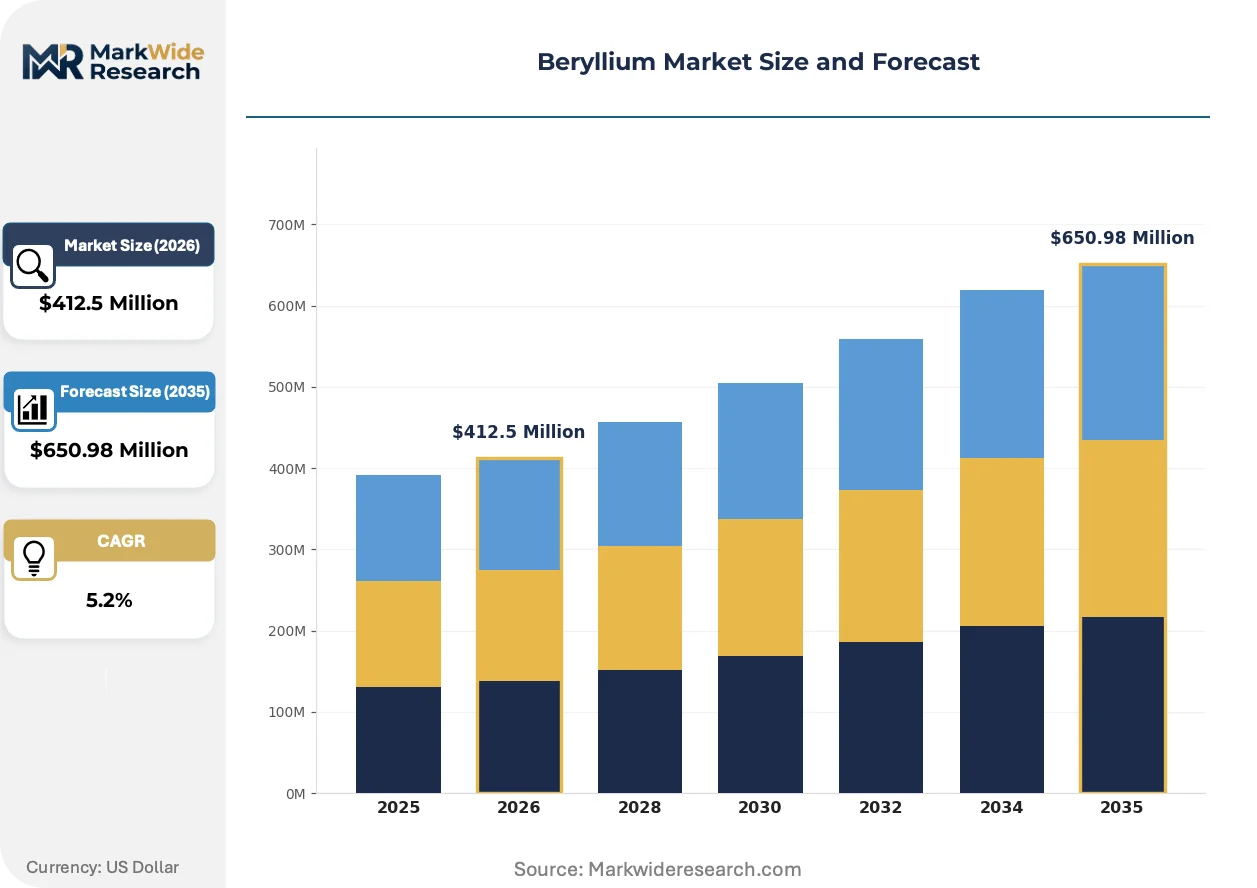
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $650.98 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beryllium Metal, Beryllium Alloy, Beryllium Oxide, Beryllium Copper End Use Industry: Aerospace, Defense, Electronics, Nuclear Application: X-ray Equipment, Telecommunications, Semiconductors, Optical Components Delivery Mode: Direct Sales, Online Sales, Distributors, Wholesale |
| Companies Covered | Materion Corporation, IBC Advanced Alloys, NGK Metals Corporation, American Beryllia Inc, Ulba Metallurgical Plant, Hunan Shuikoushan Nonferrous Metals Group Co. Ltd, American Elements, Belmont Metals, Aviva Metals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Market Strategic Shifts & Innovations
Additive manufacturing methods are penetrating beryllium component fabrication, enabling geometric complexity that conventional machining cannot achieve while reducing material waste in high-value aerospace applications.
Near-net-shape powder metallurgy is displacing conventional billet-to-final machining workflows in satellite structure production. Lockheed Martin and Northrop Grumman procurement teams are qualifying these processes for thermal management substrates. The shift is compressing lead times from eighteen months to under six for complex bracket geometries.
OSHA's revised beryllium workplace exposure standard under 29 CFR 1910.1024 is mandating engineering controls and respiratory protection upgrades across fabrication facilities. The rule's industrial consequence is accelerating automation investment in machining and grinding operations. Small-to-mid-tier processors in California and Texas are consolidating or exiting rather than absorbing compliance capital requirements.
Defense prime contractors are consolidating supplier bases around dual-use certified producers capable of serving both nuclear and aerospace programs. Long-term offtake agreements with Materion and IBC Advanced Alloys are displacing spot market purchasing for strategic inventory positions. The concentration is most visible in Department of Energy procurement for the Stockpile Stewardship program.
Beryllium Market Segmentation
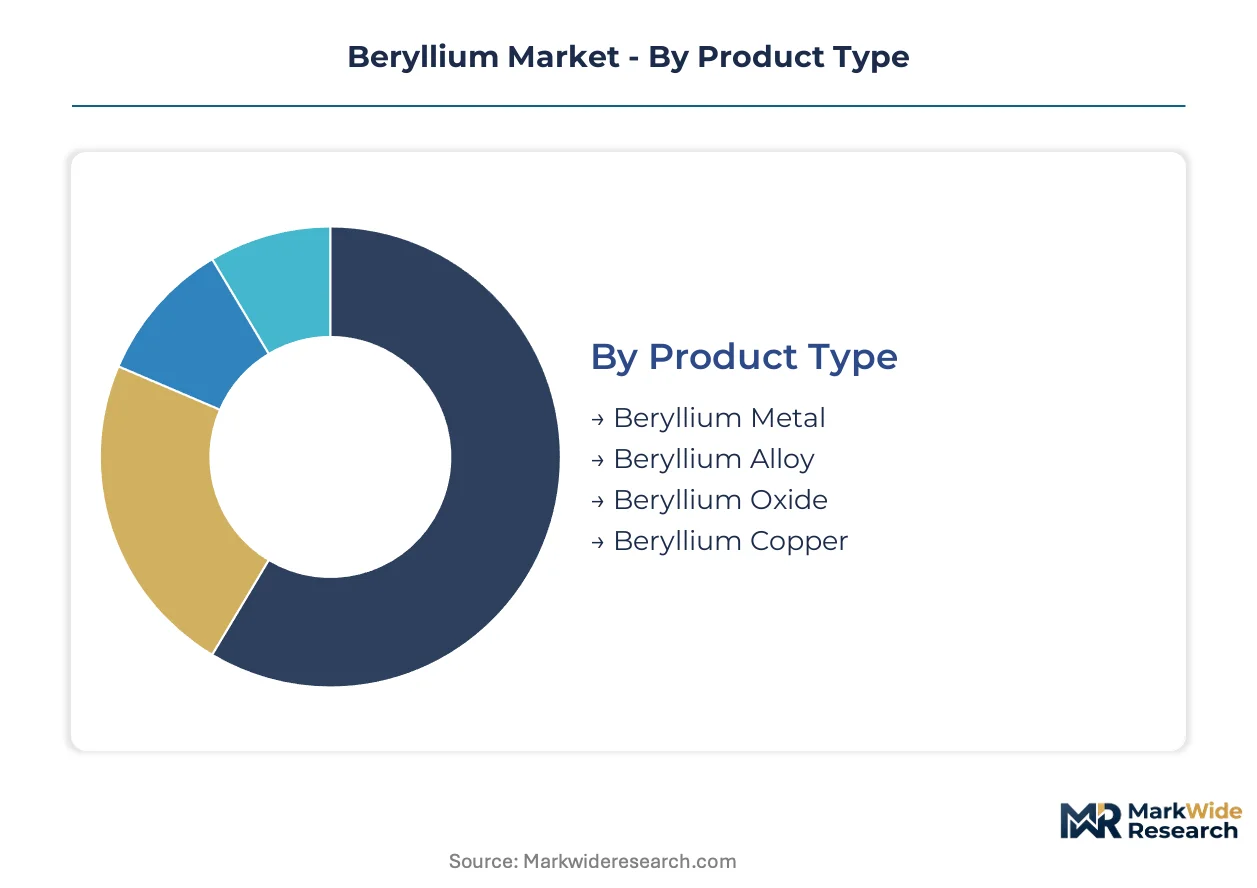
Beryllium procurement decisions hinge on regulatory compliance tiers, with defense-grade specifications demanding distinct handling protocols from commercial electronics applications. Segmentation reveals how toxicity classification frameworks reshape competitive positioning across product grades and delivery channels.
Product Type:
EPA 40 CFR Part 745 workplace exposure limits apply differentially across refined forms, with primary metal triggering the most stringent containment requirements.
- Beryllium Copper:Copper-beryllium alloys containing 0.5-3% beryllium deliver non-sparking properties and fatigue resistance for oilfield connectors and semiconductor probe cards. Electronics fabricators in the United States absorb the majority of strip and wire volumes, though REACH import constraints redirect European demand toward compliant North American suppliers.
- Beryllium Metal:Primary beryllium with 99%+ purity serves nuclear moderators and aerospace structures where stiffness-to-weight ratio and dimensional stability under thermal stress are critical. Department of Energy stockpile procurement sustains long-term offtake for this highest-purity grade.
- Beryllium Alloy:Aluminum-beryllium and other master alloys enable precision casting of complex geometries for missile guidance housings.
- Beryllium Oxide:Ceramic substrates command premium positioning in radar and satellite thermal management systems.
Established volume favors beryllium copper; emerging adoption favors beryllium oxide ceramics in satellite applications.
End Use Industry:
Customer procurement patterns diverge sharply between spot-market electronics purchasing and multi-year defense offtake agreements.
- Defense:Missile guidance systems and strategic stockpile programs drive alloy consumption through sole-source contracts with integrated producers. Materion's Utah refining complex anchors North American supply security for this channel.
- Electronics:Semiconductor manufacturing equipment represents the steepest expansion trajectory, with probe card assemblies and thermal management substrates absorbing growing volumes of beryllium copper alloys.
- Aerospace:Launch vehicle structures exploit beryllium's unmatched stiffness-to-weight ratio for precision instrument housings.
- Nuclear:Reactor moderator and reflector applications sustain baseline demand through Department of Energy scheduling.
Defense procurement commands price premiums; electronics volume is climbing the fastest.
Application:
Technical specifications vary dramatically across imaging, communications, and computing end-uses.
- Semiconductors:Wafer handling equipment and probe card assemblies demand beryllium copper for its elastic modulus and thermal conductivity. Equipment OEMs in the United States and East Asia concentrate procurement among dual-use certified producers.
- X-ray Equipment:Beryllium window foils enable low-attenuation transmission for medical and industrial imaging systems.
- Telecommunications:RF connectors and waveguide components exploit fatigue resistance in base station infrastructure.
- Optical Components:Telescope mirrors and precision instrumentation leverage beryllium's thermal stability.
Semiconductor applications gain share fastest; optical components maintain stable niche positioning.
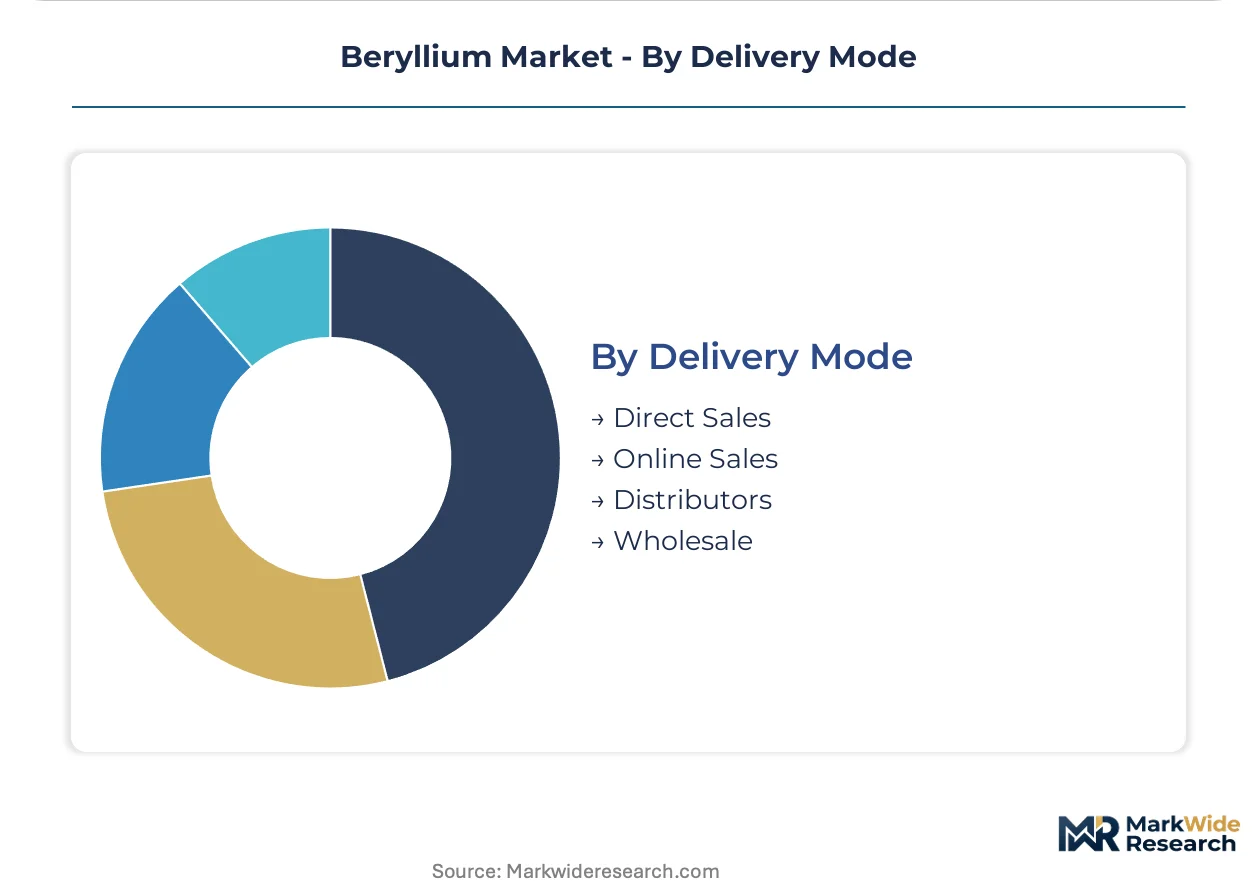
Delivery Mode:
Channel economics reflect lot size, certification requirements, and geographic proximity to refining assets.
- Direct Sales:Defense primes and nuclear contractors negotiate long-term offtake agreements with Materion and IBC Advanced Alloys, bypassing intermediaries for strategic inventory positions.
- Distributors:Electronics and oilfield service companies source beryllium copper strip and wire through specialized metal distributors with hazmat handling credentials.
- Wholesale:Master alloy volumes flow through metals merchants serving foundry customers.
- Online Sales:Small-lot specialty orders for research and prototyping move through qualified e-commerce channels with restricted access protocols.
Direct sales dominate value capture; distributor channels handle the widest SKU variety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace exposure standards under 29 CFR 1910.1024 shape operational economics across the United States, the world's dominant beryllium consumer. Department of Energy stockpile procurement and nuclear modernization programs sustain concentrated demand in North American refining corridors.
United States
Missile guidance systems and strategic stockpile programs absorb the majority of primary metal volumes through sole-source defense contracts. EPA 40 CFR Part 745 workplace exposure limits trigger stringent containment requirements at Utah refining complexes. Spor Mountain operations anchor North American supply security with captive mining and processing assets.
China
Semiconductor manufacturing equipment and electronics fabrication drive beryllium copper alloy consumption in coastal manufacturing zones. MIIT industrial standards and GB certification frameworks regulate import pathways for refined material. Yangtze River Delta foundries concentrate precision casting capacity for aerospace subcontracting.
Japan
Probe card assemblies and thermal management substrates for semiconductor equipment represent expanding demand channels. METI critical mineral policies prioritize supply chain resilience for defense-adjacent applications. Osaka-Kobe industrial corridor hosts specialized distributors serving electronics OEMs with hazmat handling credentials.
Germany
REACH restrictions constrain import pathways for non-EU refined beryllium, redirecting trade flows toward compliant North American suppliers. ECHA toxicity classification debates shape fabrication economics for downstream processors. Bavarian precision engineering clusters maintain niche demand for optical component applications.
Kazakhstan
Ulba Metallurgical Plant operations sustain legacy Soviet-era refining capacity serving regional aerospace programs. National atomic energy agency oversight governs export licensing for nuclear-grade material. Eastern mining districts concentrate bertrandite ore extraction for master alloy production.
Beryllium Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive refining assets determining competitive positioning in defense and nuclear channels. Market structure favors producers with backward integration into mining and in-house alloy formulation capabilities. Two archetypes dominate: Utah-based integrated refiners with Department of Energy contracts, and precision casting specialists serving missile guidance housing programs. Capacity expansion and strategic partnerships constitute the primary competitive moves, with compliance capital requirements forcing consolidation among small-to-mid-tier processors.
Among North American integrated producers, Materion Corporation exemplifies the captive-refining archetype through its Utah-based mining and refining complex. IBC Advanced Alloys occupies a position within the precision casting specialist tier, while NGK Metals Corporation represents the copper-beryllium strip and wire fabrication segment. These three anchors demonstrate how geographic proximity to defense procurement centers and dual-use certification capabilities stratify competitive positioning.
| Leading Market Players |
|---|
| Materion Corporation |
| IBC Advanced Alloys |
| NGK Metals Corporation |
| American Beryllia Inc |
| Ulba Metallurgical Plant |
| Hunan Shuikoushan Nonferrous Metals Group Co. Ltd |
| American Elements |
| Belmont Metals |
| Aviva Metals |
| Others |
Cost & Logistics Intelligence
Captive refining scale at Utah mining complexes creates asymmetric pricing power for integrated producers, concentrating margin capture among operators with backward control over bertrandite extraction and master alloy production. This concentration elevates price floors for defense-grade material while compressing spreads available to toll processors lacking captive ore supply.
Pricing Analysis
Price spreads between North American and European delivery points widen during REACH compliance bottlenecks, redirecting spot demand toward OSHA-certified Utah refiners. Three-tier pricing structure across defense-grade, dual-use certified, and commercial electronics tiers reflects certification burden and volume scale. Pricing pressure stems from metallurgical technician shortages elevating labor costs across fabrication stages. Electronics probe card buyers exhibit highest price sensitivity, while Department of Energy stockpile procurement shows minimal elasticity.
Supply Chain Analysis
Inbound logistics costs from Kazakh bertrandite shipments through Black Sea corridors fluctuate with regional port congestion, elevating working capital requirements for European alloy processors. Supply concentrates in the United States, Kazakhstan, and China, with ore quality variance complicating blending economics at master alloy foundries. Raw material dependencies encompass bertrandite ore, copper cathode, and aluminum ingot feedstocks. Single-source vulnerability concentrates at Spor Mountain mining operations. Distribution runs through defense prime direct contracts and specialized hazmat distributors serving electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in semiconductor manufacturing equipment is accelerating beryllium copper offtake faster than primary metal supply can respond, creating favorable demand elasticity for qualified producers.
For Market Incumbents: Shield margin structure by accelerating automation investment ahead of OSHA exposure limit enforcement timelines. Consolidate toll processing relationships to secure captive feedstock access, countering substitution threats from aluminum-silicon carbide composites in satellite thermal management. For New Entrants and Emerging Players: Anchor in precision casting capabilities for aluminum-beryllium missile guidance housings, the segment with lowest certification barriers relative to defense revenue potential. Target semiconductor equipment OEMs in East Asia with probe card assembly partnerships, leveraging REACH redirection tailwinds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dual-use certified producers with existing Department of Energy relationships. Long-term viability hinges on nuclear modernization program continuity and space launch cadence expansion. Watch for additive manufacturing qualification milestones at Lockheed Martin and Northrop Grumman as inflection indicators for near-net-shape powder metallurgy adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Refining Expansion | Backward integration into Utah bertrandite mining secures defense contract eligibility against REACH-constrained European rivals. |
| Automation Capital Deployment | OSHA 29 CFR 1910.1024 compliance mandates robotic machining investments that smaller processors cannot absorb. |
| Dual-Use Certification Investment | Simultaneous nuclear and aerospace qualification opens sole-source Department of Energy procurement channels. |
| Additive Manufacturing Qualification | Near-net-shape powder metallurgy adoption at Lockheed Martin compresses lead times for complex bracket geometries. |
| Long-Term Offtake Agreements | Defense prime consolidation around strategic inventory positions displaces spot market exposure for integrated producers. |
Research Approach
Desk research of SEC 10-K filings, customs trade records, and Department of Energy procurement databases preceded structured interviews with plant managers at Utah refining complexes, defense procurement officers, semiconductor equipment OEM sourcing leads, and specialized metals distributors. Primary fieldwork with alloy formulation technicians and EPA compliance officers cross-validated secondary estimates of capacity utilization and regulatory cost burdens. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers.
Variance decomposition across product type, end-use industry, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and price elasticity assumptions reflected defense budget authorization patterns and semiconductor capital equipment spending cycles. Modeled inputs incorporated nuclear modernization program schedules and REACH enforcement intensity scenarios.
Underlying assumptions cover sustained Department of Energy stockpile procurement and OSHA compliance timeline adherence, with deviation risk concentrated in alternative material substitution thresholds for satellite thermal management substrates. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Lightweight Aluminium Pistons Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
South America Metal Finishing Market
Metals
Ferrosilicon Magnesium Market
Metals
Nickel Oxide Target Market
Metals
Europe Aluminium Wire Rod Market
Metals
North America Aluminum Casting Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Aluminium Forging Market
Metals
US Copper Scrap Market
Metals
Zinc Plating Market
Metals
Metal Finishing Market
Metals
Aluminum Extrusion Market
Metals
HSLA Steel Plate Market
Metals
Steel Long Products Market
Metals
Osmium Market