
 Asia-Pacific Aluminum Casting Market | 2026-2036
Asia-Pacific Aluminum Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aluminum Casting Market Outlook
Asset-light leasing models for high-pressure die casting cells is fragmenting competitive access across the Asia-Pacific Aluminum Casting Market. Alcoa Corporation leverages captive smelter capacity to anchor regional supply chains. Aluminum Corporation of China Limited dominates domestic volume through integrated bauxite-to-casting operations. Ryobi Limited specializes in precision automotive powertrain castings for Japanese OEM export programs.
Asia-Pacific aluminum casting encompasses the shaped metal forming of aluminum alloys through molten metal injection or gravity pouring into molds, typically achieving dimensional tolerances of CT4-CT8 and producing components with strength-to-weight ratios critical for transportation electrification. Die casting occupies the largest share of regional output value, while vacuum die casting is gaining fastest in EV battery tray applications where porosity below 0.5% prevents thermal runaway propagation. Automotive Components remains the dominant application segment, though Electronics Housings for 5G infrastructure and server thermal management represent expanding margin pools.
China's MIIT enforces GB standards for automotive aluminum alloy chemistry and recyclate content, while India's BIS mandates BIS-IS 617 certification for pressure die cast structural components. Japan's METI guides JIS H 5302 specifications that govern export-qualified casting quality across ASEAN supply chains. Stakeholders must monitor how China's SAMR implements dual carbon goals through foundry energy intensity caps and how India's PLI scheme revisions alter domestic value-add requirements for foreign die casting equipment suppliers.
Market Dynamics
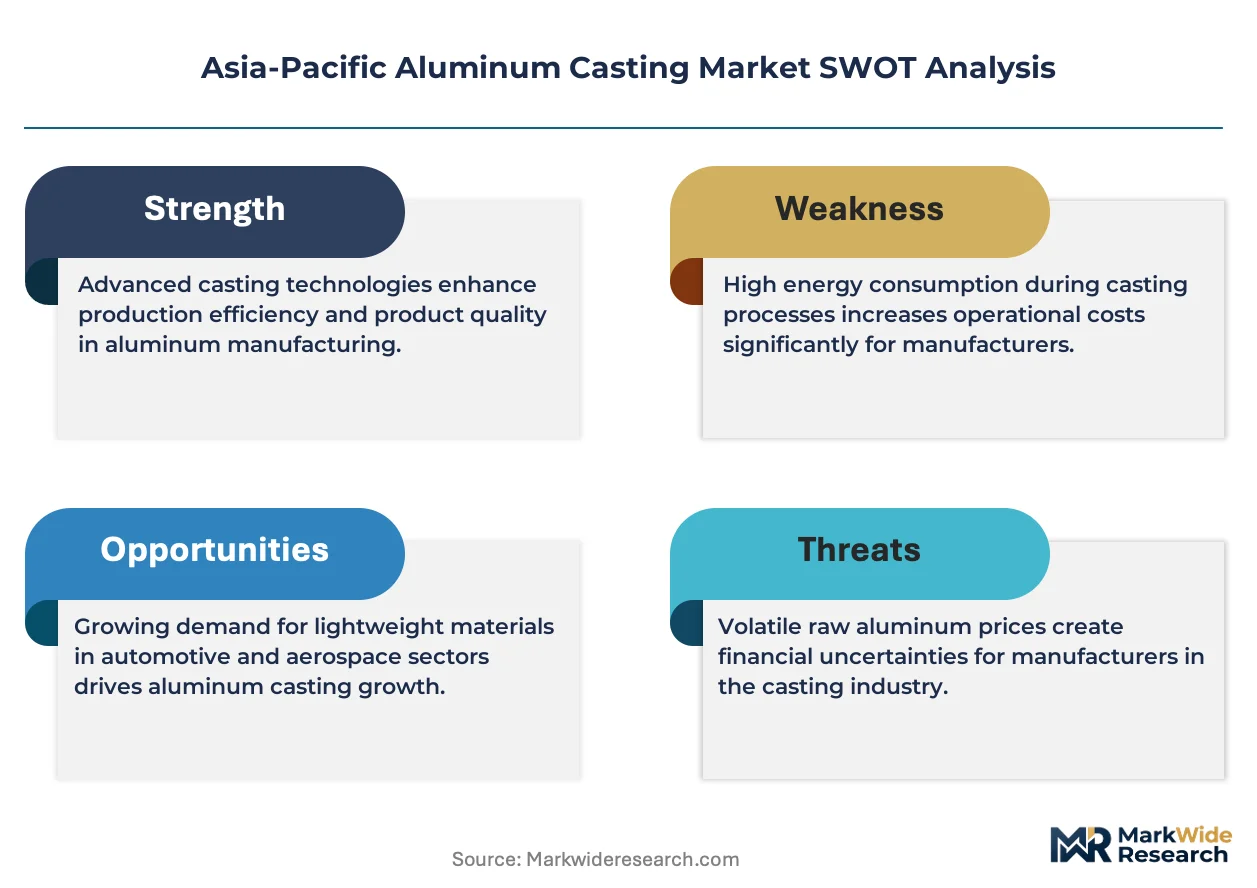
Lightweight chassis mandates from China's dual carbon goals and India's PLI scheme are forcing automotive OEMs to requalify aluminum casting suppliers at unprecedented velocity, compressing certification timelines and fragmenting incumbent market positions.
Growth Catalysts
- EV Battery Tray Demand:Vacuum die casting with sub-0.5% porosity specifications is becoming mandatory for thermal runaway prevention in electric vehicle battery enclosures across Chinese and Indian OEM programs.
- China's MIIT Energy Intensity Caps:Foundry consolidation is accelerating as smaller operators fail to meet mandated efficiency thresholds, creating volume migration opportunities for compliant Tier-1 suppliers.
- 5G Infrastructure Rollout:Electronics housings for server thermal management and base station equipment represent expanding margin pools beyond traditional automotive applications in the Yangtze River Delta cluster.
Market Restraints
- Primary Aluminum Price Volatility:LME aluminum price swings above fifteen percent annually are eroding fixed-price contract margins for independent die casting houses without captive smelter access.
- Bauxite Supply Concentration:China's Aluminum Corporation controls integrated bauxite-to-casting operations, creating input cost asymmetries for non-integrated competitors in domestic procurement.
- Magnesium Substitution Threat:Thixomolded magnesium alloys are penetrating interior structural applications where crash performance requirements permit lower density alternatives to aluminum castings.
Strategic Opportunities
- Vietnam and Indonesia Underpenetration:Japanese OEM supplier parks in Hai Phong and Bekasi lack qualified high-pressure die casting capacity for localized powertrain component supply.
- Asset-Light Leasing Models:Die casting cell leasing is fragmenting competitive access by lowering capital barriers for mid-tier entrants seeking automotive certification without full equipment ownership.
- India's PLI Scheme Revisions:Domestic value-add thresholds for foreign equipment suppliers are creating partnership structures with local engineering firms for technology transfer compliance.
Industry Challenges
- Tooling Engineer Scarcity:High-pressure die casting die design expertise concentrates in Japan and Germany, forcing Asia-Pacific foundries to rely on expatriate technical staffing or extended qualification cycles.
- GB Standard Compliance Timelines:China's MIIT automotive aluminum alloy chemistry certifications require eighteen-month validation windows that delay new alloy introduction for EV-specific thermal conductivity requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aluminum Casting Market |
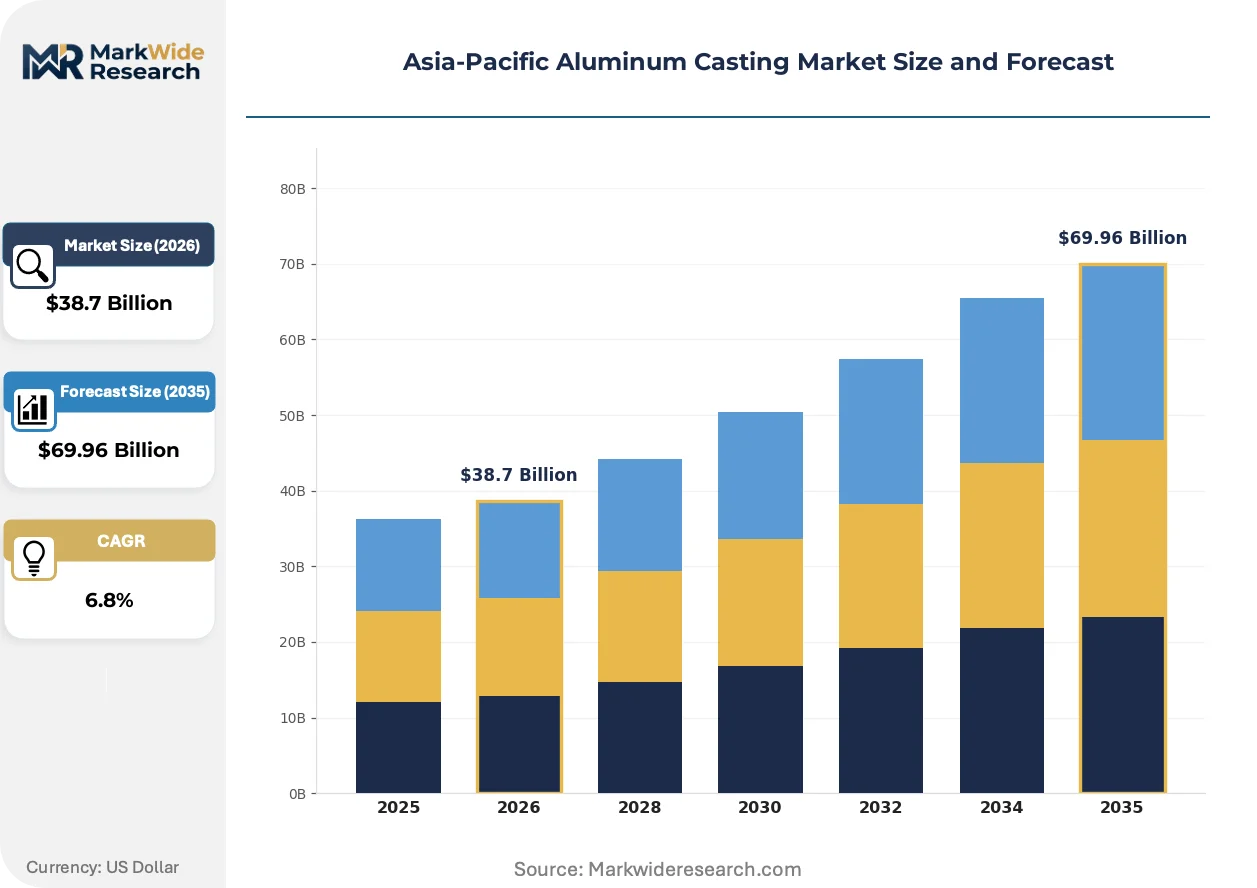
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die Casting, Sand Casting, Permanent Mold Casting, Investment Casting Application: Automotive Components, Aerospace Parts, Electronics Housings, Industrial Equipment End User: OEM Manufacturers, Aftermarket Suppliers, Electronics Manufacturers, Tooling Companies Technology: High Pressure Die Casting, Low Pressure Die Casting, Vacuum Die Casting, Gravity Die Casting |
| Companies Covered | Endurance Technologies Limited, Alcoa Corporation, Aluminum Corporation of China Limited, Ryobi Limited, Dynacast, NEMAK SAB de CV, Guangdong Hongtai Technology, Chongqing Yujiang Die Casting Co., Ltd., Craftsman Automation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aluminum Casting Market Strategic Shifts
Process control digitization and alloy formulation advances are compressing the gap between prototype validation and production scale, while regulatory chemistry mandates are forcing foundries to requalify legacy supply chains.
Real-time porosity detection using X-ray computed tomography integrated into high-pressure die casting cells is rendering obsolete post-casting batch inspection protocols that previously added twelve to twenty-four hours to cycle times. Automotive OEMs in China's Yangtze River Delta manufacturing cluster are mandating inline inspection adoption for EV battery tray suppliers. This compression is eliminating quality hold buffers and forcing foundries to absorb rework costs previously passed to downstream assembly.
India's BIS-IS 617 certification mandates for pressure die cast structural components are tightening chemistry traceability requirements to lot-level documentation. The regulation forces foundries to deploy spectrometry stations at melt furnaces rather than relying on supplier mill certificates. Tier-1 automotive suppliers in the Pune-Chennai corridor are responding by consolidating supplier bases to reduce audit complexity.
Automotive OEM procurement teams are unbundling tooling ownership from piece-price contracts, creating separate capital streams for die casting die fabrication. Tier-1 suppliers previously absorbing tooling amortization across volume commitments are now facing direct tooling cash calls from OEMs seeking asset control. This shift is most visible in Japanese OEM programs where die ownership transfer clauses are becoming standard in RFQ documentation.
Asia-Pacific Aluminum Casting Market Segmentation
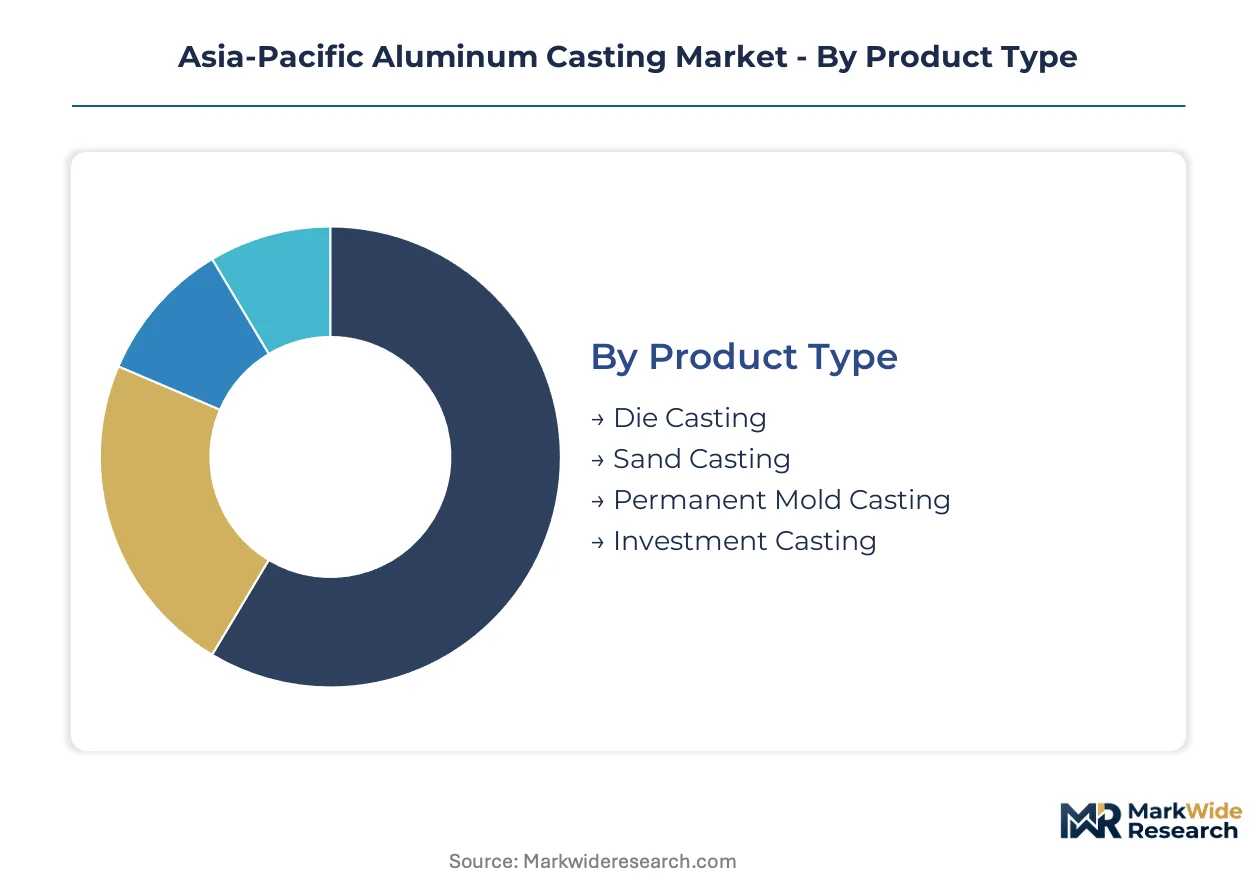
Segmentation reveals how aluminum casting value pools split between high-volume automotive programs and precision aerospace contracts with radically different tooling amortization cycles. Understanding these velocity differences exposes where capital efficiency concentrates and where margin compression threatens.
Product Type:
Die casting cells turn inventory fastest at twelve to fifteen cycles per minute, while investment casting furnaces hold molten alloy for hours per batch, creating working capital intensity gaps that reshape competitive access.
- Die Casting:Molten aluminum injects into hardened steel dies under pressures exceeding 1,000 bar, achieving CT4-CT6 tolerances for powertrain housings. China's Yangtze River Delta cluster concentrates demand from EV battery tray programs where vacuum-assisted variants now dominate new capacity installations.
- Sand Casting:Green sand or chemically bonded molds accommodate single-run prototypes and low-volume industrial components without die fabrication lead times. India's Pune foundries leverage this flexibility for agricultural equipment castings where annual volumes fall below die casting economic thresholds.
- Permanent Mold Casting:Gravity-fed metal fills reusable steel or cast iron molds for wheel rims and cylinder heads requiring directional solidification control.
- Investment Casting:Ceramic shell molds around wax patterns deliver near-net-shape aerospace components with surface finishes below Ra 3.2 micrometers.
Die casting dominates installed base. Investment casting is where expansion concentrates.
Application:
Cost tiers separate mass-market automotive chassis programs from aerospace qualification premiums that absorb ten-year amortization horizons.
- Automotive Components:Structural castings for electric vehicle platforms now absorb over half of regional high-pressure die casting capacity. China's MIIT mandates lightweight chassis adoption through dual carbon enforcement, compressing supplier requalification timelines.
- Electronics Housings:5G base station and server thermal management enclosures demand thin-wall castability with heat dissipation coefficients above 200 W/mK. The Yangtze River Delta manufacturing cluster anchors this demand as domestic cloud infrastructure scales.
- Aerospace Parts:Wing rib and landing gear castings require NADCAP-certified heat treatment and penetrant inspection protocols.
- Industrial Equipment:Pump housings and valve bodies for process industries tolerate coarser tolerances than transportation applications.
Automotive Components commands volume concentration. Electronics Housings is climbing the fastest.
End User:
Customer type determines contract structure, with OEM manufacturers demanding piece-price transparency while tooling companies absorb capital risk for die ownership.
- OEM Manufacturers:Automotive original equipment manufacturers in China and India now unbundle tooling ownership from casting supply agreements, transferring die asset control to captive foundry networks or Tier-1 suppliers.
- Aftermarket Suppliers:Independent distributors source replacement transmission cases and engine blocks through spot purchasing without long-term volume commitments.
- Electronics Manufacturers:Server OEMs and telecommunications equipment vendors specify thermal management castings with lot-level chemistry traceability.
- Tooling Companies:Die fabrication specialists increasingly retain mold ownership under leasing arrangements that fragment casting house capital barriers.
OEM Manufacturers dominates contract value. Tooling Companies is gaining share fastest.
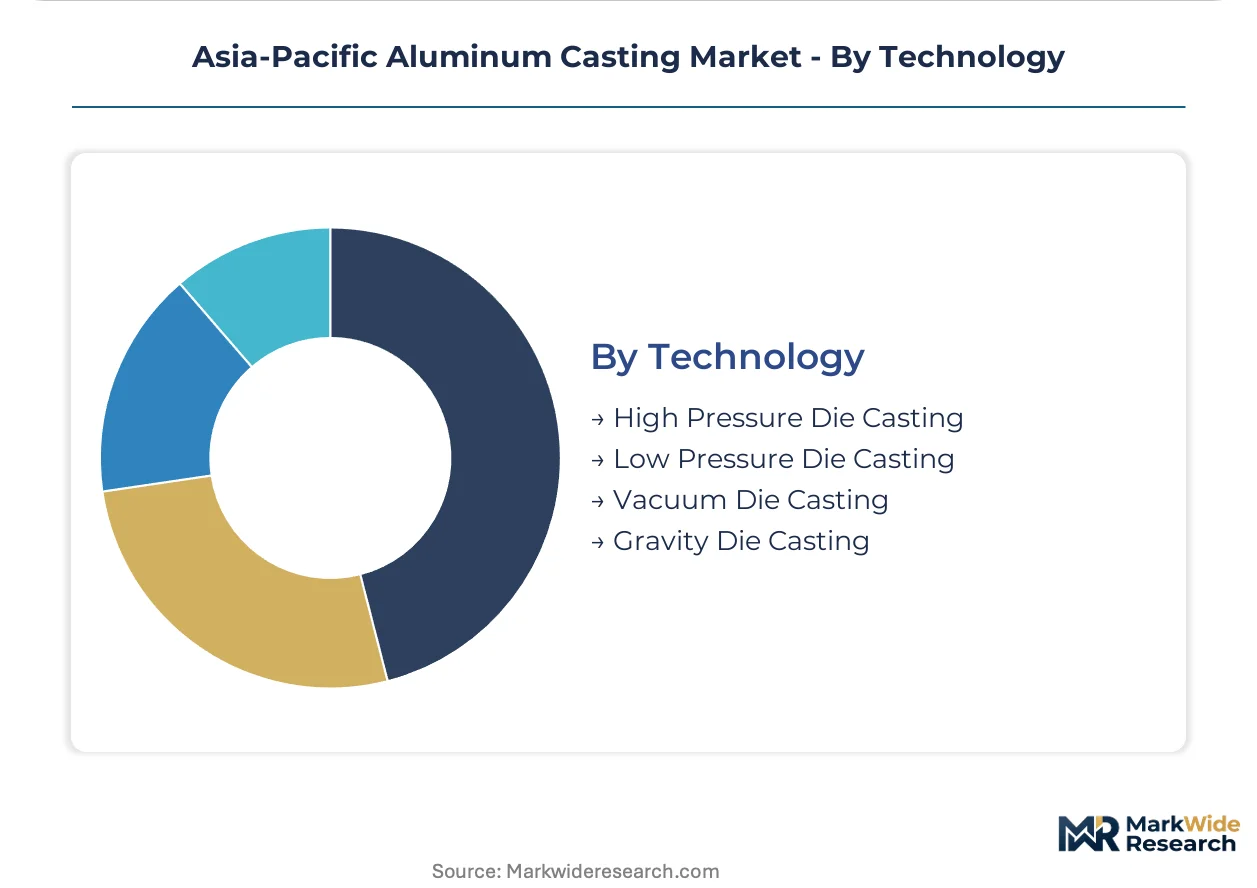
Technology:
Process maturity separates established high-pressure methods from vacuum-assisted variants still penetrating EV battery safety applications.
- Vacuum Die Casting:Evacuated die cavities before metal injection eliminate gas porosity below 0.5 percent, satisfying thermal runaway prevention mandates for electric vehicle battery enclosures. Chinese OEMs now specify this process for all new platform battery trays.
- High Pressure Die Casting:Conventional unassisted injection dominates legacy powertrain production with established tooling supply chains and qualified maintenance protocols across the Asia-Pacific region.
- Low Pressure Die Casting:Pressurized riser tubes feed molten metal upward into permanent molds for wheel and cylinder head applications requiring porosity control without vacuum infrastructure.
- Gravity Die Casting:Simple tilt-pour or static gravity filling serves brake calipers and structural brackets where mechanical properties outweigh cosmetic surface requirements.
High Pressure Die Casting dominates installed capacity. Vacuum Die Casting is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and India's PLI scheme for auto components are redirecting capital flows across Asia-Pacific aluminum casting markets, compressing supplier certification timelines and accelerating foundry consolidation in key manufacturing corridors.
China
MIIT energy intensity caps are shuttering smaller foundries while vacuum die casting capacity expands for EV battery tray production. GB standards for automotive aluminum alloy chemistry now mandate eighteen-month validation windows that delay new alloy introduction. The Yangtze River Delta manufacturing cluster anchors this transformation as domestic OEMs localize thermal runaway prevention specifications.
India
PLI scheme revisions are tightening domestic value-add thresholds for foreign die casting equipment suppliers, forcing partnership structures with local engineering firms. BIS-IS 617 certification mandates lot-level chemistry traceability through spectrometry stations at melt furnaces. The Pune-Chennai automotive corridor concentrates Tier-1 supplier consolidation as audit complexity drives base reduction.
Japan
METI-guided JIS H 5302 specifications govern export-qualified casting quality across ASEAN supply chains, preserving technical barriers for precision powertrain components. Japanese OEM supplier parks in Hai Phong and Bekasi lack qualified high-pressure die casting capacity, creating supply chain gaps for localized production. Domestic foundries maintain die design expertise concentration that Asia-Pacific competitors must license or staff through expatriate deployment.
Vietnam
Japanese automotive investment in Hai Phong industrial zones is outpacing qualified local die casting capacity for powertrain component supply. The country's national industrial regulator has not yet implemented equivalent chemistry certification mandates to Chinese or Indian standards. Northern manufacturing provinces are attracting leasing-based die casting cell investments that lower capital barriers for mid-tier market entry.
Indonesia
Bekasi automotive corridors near Jakarta lack sufficient high-pressure die casting infrastructure to serve expanding Japanese OEM localization programs. Government industrial policy prioritizes downstream metal fabrication but has not matched incentive intensity to India's PLI scheme. Domestic foundries remain concentrated in low-volume sand casting for agricultural equipment rather than automotive precision applications.
Asia-Pacific Aluminum Casting Market Competitive Environment
On the supply side, the industry is consolidating around integrated bauxite-to-casting operators and fragmenting among asset-light leasing specialists. Three strategic archetypes dominate: captive smelter-backed volume players, precision automotive powertrain specialists, and equipment-leasing intermediaries. Capacity expansion through vacuum die casting cell installation and backward integration into primary aluminum supply represent the dominant competitive moves reshaping regional positioning.
Within the integrated upstream tier, Aluminum Corporation of China Limited and Alcoa Corporation exemplify divergent geographic anchoring strategies for captive raw material access. Among precision automotive specialists, Ryobi Limited occupies a position representing Japanese OEM export program qualification standards. Endurance Technologies Limited sits within the India-focused Tier-1 supplier archetype navigating PLI scheme compliance requirements.
| Leading Market Players |
|---|
| Endurance Technologies Limited |
| Alcoa Corporation |
| Aluminum Corporation of China Limited |
| Ryobi Limited |
| Dynacast |
| NEMAK SAB de CV |
| Guangdong Hongtai Technology |
| Chongqing Yujiang Die Casting Co., Ltd. |
| Craftsman Automation |
| Others |
Value Chain & Pricing Dynamics
Shanghai Port to Nhava Sheva freight corridors carry bauxite concentrate and primary aluminum ingots that feed Yangtze River Delta foundries and Pune-Chennai automotive suppliers, with container rate volatility amplifying cost asymmetries between integrated smelter operators and independent die casting houses while compressing margins for non-captive producers serving price-sensitive aftermarket distributors.
Pricing Analysis
Certification level creates the primary spread, with BIS-IS 617 and JIS H 5302 qualified castings commanding premium piece-prices over uncertified industrial grades. Three-tier pricing structure separates vacuum die casting for EV battery trays, conventional high-pressure die casting for powertrain housings, and gravity die casting for brake calipers. Pricing pressure stems from LME aluminum volatility above fifteen percent annually, eroding fixed-contract margins. Aftermarket suppliers exhibit highest price sensitivity, while OEM manufacturers absorb premiums for traceability documentation.
Supply Chain Analysis
Tariff exposure between China and ASEAN markets dominates supply chain risk assessment for Japanese OEM supplier parks in Hai Phong and Bekasi. Primary aluminum supply concentrates in China, India, and Australia, while die casting equipment and precision tooling draw from Japan and Germany. Bauxite ore, magnesium alloying elements, and ceramic shell materials for investment casting constitute critical input dependencies. Distribution runs through Tier-1 automotive supplier networks with consolidated direct-to-OEM contracts replacing spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure die casting die design expertise concentrates in Japan and Germany, creating acute capability gaps across Asia-Pacific foundries that reshape competitive access and capital deployment priorities for every participant archetype.
For Market Incumbents: Entrench through backward integration into primary aluminum supply and captive spectrometry deployment at melt furnaces to satisfy BIS-IS 617 lot-level traceability mandates. Accelerate vacuum die casting cell installation in Yangtze River Delta clusters before MIIT energy intensity caps shutter smaller competitors. Magnesium thixomolding substitution in interior structural applications represents the priority threat requiring alloy R&D counterinvestment. For New Entrants and Emerging Players: Vietnamese and Indonesian automotive corridors represent the most penetrable entry points, with Japanese OEM supplier parks in Hai Phong and Bekasi lacking qualified high-pressure die casting capacity for localized powertrain supply. Asset-light leasing models for die casting cells lower capital barriers without full equipment ownership. Partnership structures with local engineering firms satisfy India's PLI scheme domestic value-add thresholds for foreign equipment suppliers. For Investors and Strategic Acquirers: Precision automotive powertrain specialists with established Japanese OEM export program qualifications offer the strongest acquisition profile for long-term viability across the electrification transition. Monitor China's SAMR implementation of dual carbon goals through foundry energy intensity caps as the inflection signal for volume migration opportunities toward compliant Tier-1 suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Die Casting Capacity Expansion | Chinese OEMs now mandate sub-0.5% porosity specifications for all new EV battery tray platforms. |
| Backward Integration into Primary Aluminum | Captive smelter access insulates margins from LME volatility eroding independent die casting houses. |
| Spectrometry Station Deployment | BIS-IS 617 certification requires lot-level chemistry traceability eliminating supplier mill certificate reliance. |
| Die Casting Cell Leasing Models | Asset-light structures fragment competitive access by lowering capital barriers for mid-tier automotive certification seekers. |
| Local Engineering Firm Partnerships | India's PLI scheme revisions force technology transfer compliance structures for foreign equipment suppliers. |
Study Parameters
Operator-level perspectives from foundry operations managers, Tier-1 automotive supplier procurement leads, OEM platform engineers, and die casting equipment technical specialists anchored the qualitative base. Primary interview insights triangulated against customs and trade data, MIIT and BIS regulatory filings, SEC 10-K disclosures from listed aluminum producers, and vehicle production databases from IHS Markit. Bottom-up capacity installation tracking across Yangtze River Delta and Pune-Chennai corridors combined with top-down aluminum consumption modeling to validate segment splits.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic, baseline, and conservative cases reflecting differential EV adoption trajectories and regulatory enforcement intensity. Segmentation dimensions modeled include casting process type, application end-use, propulsion architecture, OEM tier positioning, and regional production cluster. CAGRs derived from installed capacity expansion pipelines, alloy formulation qualification timelines, and OEM platform lifecycle commitments. Primary aluminum price volatility and tooling engineer scarcity served as key forecast sensitivity inputs.
Practitioners should monitor China's SAMR dual carbon enforcement pace and India's PLI scheme revision timing for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Magnesium Metal Market
Metals
Precious Metals Wire Market
Metals
Global Tool Steel Market
Metals
Huntite Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Beryllium Copper Billet Market
Metals
Global Flat Steel Market
Metals
Aluminium Collars Market
Metals
Metallurgical Silicon Market
Metals
Molybdenum Market
Metals
Europe Welding Consumables Market
Metals
Motor Lamination Material Market
Metals
Global Steel Market
Metals
Aluminum Slugs Market
Metals
Aluminum Flat-Rolled Products Market
Metals
US Ferrochrome Market