
 Global Chemical Licensing Market | 2026-2036
Global Chemical Licensing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Licensing Market Foresight
Middle Eastern petrochemical expansion is reshaping global licensing flows as Saudi Arabia and Qatar commission integrated refinery-chemical complexes. UOP LLC leverages its proprietary catalytic reforming portfolio to anchor technology supply for aromatics units across the Gulf. Lummus Technology LLC competes through its ethylene cracker designs, sustaining engineering margins on large-scale polyethylene projects. Technip Energies N.V. differentiates via modular construction expertise, positioning its licensing bundles for faster deployment timelines.
Chemical licensing encompasses the contractual transfer of proprietary process technologies, catalyst formulations, and engineering designs enabling licensees to manufacture specified chemical products under defined performance parameters. The practice spans fixed-bed reactor configurations, fluid catalytic cracking units, and polymerization systems governed by guaranteed output specifications and catalyst life warranties. Exclusive license arrangements command premium positioning in pharmaceuticals and agrochemicals where patent cliffs create urgent manufacturing access needs. Royalty-based models dominate specialty chemicals as licensors capture ongoing value from high-margin formulations without capital deployment.
EPA emissions standards in the United States, REACH compliance obligations under ECHA oversight in Europe, and China's GB standards administered by MEE collectively elevate process selection criteria for licensed technologies. These frameworks push licensors to certify lower-carbon process alternatives and document full material safety profiles before technology transfer completion. Stakeholders must monitor how carbon border adjustments and evolving green chemistry mandates alter the competitive value of legacy versus next-generation process licenses.
Market Dynamics
The EU Green Deal's emissions trading framework is forcing licensors to redesign catalytic processes around carbon intensity benchmarks, compressing the value of legacy steam-cracking licenses while elevating bio-based and hydrogen-integrated alternatives.
Growth Catalysts
- Polymer manufacturer demand for sustainable feedstocks:Specialty chemical licensors are capturing expanded engineering scope as polyethylene and polypropylene producers seek pyrolysis and chemical recycling technologies to meet circular economy mandates.
- REACH compliance obligations:ECHA oversight is elevating process selection criteria across European chemical manufacturing, favoring licensors who certify full material safety profiles and lower-carbon process alternatives before technology transfer.
- China's state-owned refinery expansion:Technology transfer agreements with Sinopec and CNPC affiliates are concentrating demand for aromatics and derivative process licenses in the world's largest petrochemical capacity buildout.
Market Restraints
- Catalyst supply concentration:Proprietary reforming and polymerization catalyst formulations remain concentrated among a handful of specialized suppliers, creating input cost volatility and transfer-pricing leverage for licensors.
- Technical limitation in bio-based scale-up:Fermentation and enzymatic process licenses face yield and purity constraints at commercial volumes, limiting licensee confidence in performance guarantees for renewable chemical routes.
- Carbon border adjustment friction:The EU's CBAM is imposing documentation burdens on licensed process imports from carbon-intensive jurisdictions, complicating technology transfer timelines for Middle Eastern and Asian licensors.
Strategic Opportunities
- India's petrochemical deficit:Reliance Industries and Indian Oil are accelerating cracker and derivative investments, creating white space for licensors with modular construction expertise and fast-deployment ethylene technology bundles.
- Electrification of steam crackers:Convergence of renewable power procurement and e-furnace engineering is opening licensing scope for all-electric or hybrid cracking designs that eliminate scope-one emissions.
- Japan's METI hydrogen roadmap:Ammonia and methanol process licensors are positioning for technology transfer opportunities as Japanese chemical producers pilot hydrogen-integrated feedstock substitution under national decarbonization targets.
Industry Challenges
- Process safety engineer scarcity:Licensed technology deployment requires specialized hazard analysis expertise for high-pressure reactor systems, with talent gaps extending commissioning timelines for complex petrochemical units.
- IP fragmentation in modular designs:licensors and EPC contractors dispute ownership of standardized skid configurations, complicating royalty structures and enforcement across repeated deployments.
- Legacy system integration complexity:Digital twin and advanced process control packages from licensors must interface with existing DCS architectures, creating customization overhead and warranty boundary disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Licensing Market |
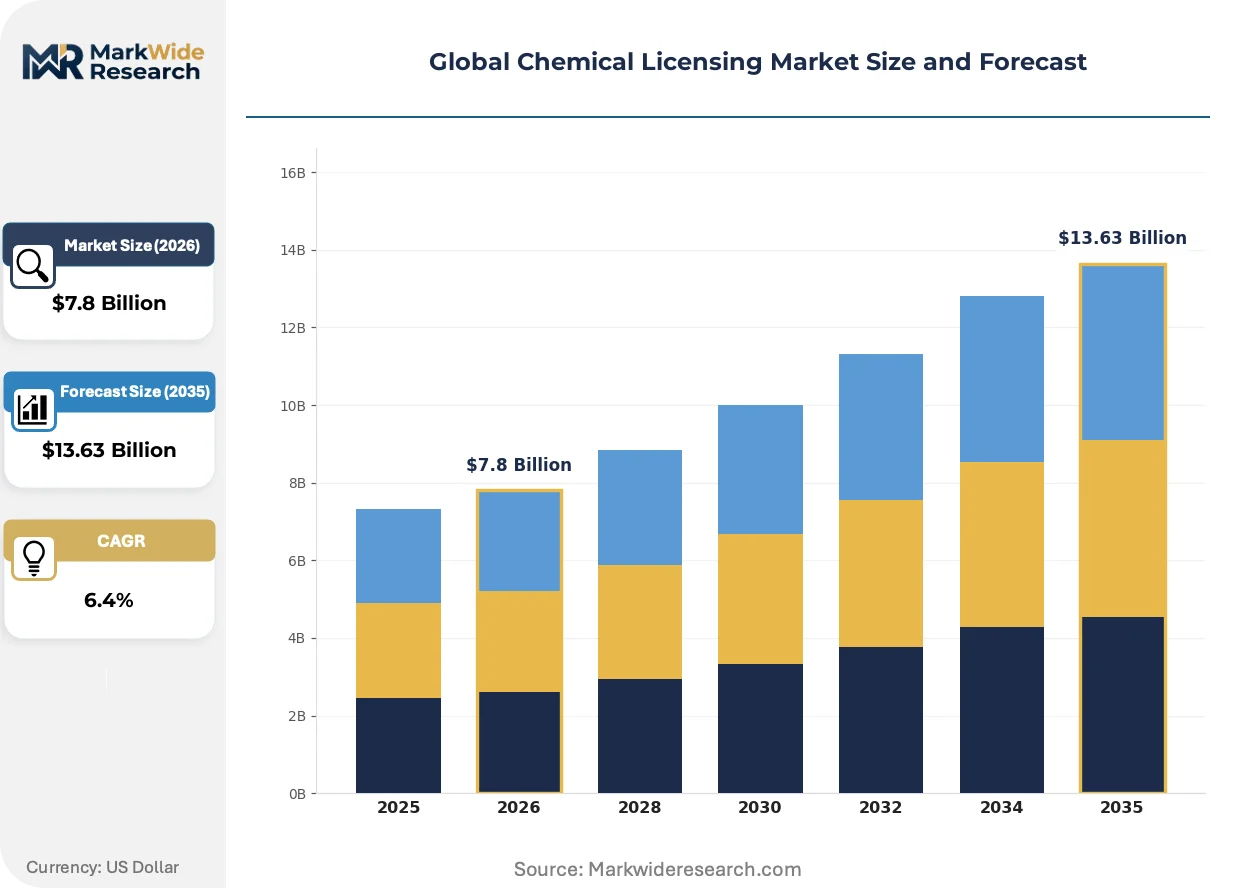
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | License Type: Exclusive, Non-exclusive, Sole License, Cross-License Industry Application: Pharmaceuticals, Agrochemicals, Specialty Chemicals, Fine Chemicals, Biochemicals License Duration: Short-term, Medium-term, Long-term, Perpetual Licensing Model: Royalty-based, Lump-sum, Equity-sharing, Revenue-sharing, Milestone-based |
| Companies Covered | UOP LLC, Lummus Technology LLC, Technip Energies N.V., KBR, Inc., Axens S.A.S., Johnson Matthey PLC, Clariant AG, Exxon Mobil Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Licensing Market Shifts & Advancements
Process intensification and digital integration are compressing the traditional engineering-procurement-construction cycle, while regulatory carbon accounting is embedding emissions verification directly into license performance guarantees.
Electrified cracking furnaces and plasma-assisted reforming are rendering obsolete conventional fired-heater designs in ethylene and aromatics production. European petrochemical operators are piloting these technologies at demonstration scale ahead of 2030 carbon neutrality commitments. The structural consequence is a bifurcation in licensor portfolios, with engineering firms lacking e-chemical expertise facing margin compression on new cracker awards.
REACH authorization requirements and the EU F-Gas Regulation are restricting fluorinated process chemicals and high-GWP refrigerants in licensed separation and purification systems. Licensors must now certify alternative solvent routes and document substitution plans before technology transfer completion. Specialty chemical segments serving agrochemical and pharmaceutical end-uses are most affected, with ECHA pre-registration timelines extending license negotiation cycles.
Licensee procurement committees are unbundling catalyst supply from process engineering, demanding competitive sourcing rights for reforming and polymerization formulations previously bundled as exclusive packages. This disintermediation is compressing licensor margins on recurring revenue streams. The shift is most visible in Middle Eastern integrated refinery-chemical complexes, where state-owned operators leverage scale to negotiate catalyst procurement autonomy.
Global Chemical Licensing Market Segmentation
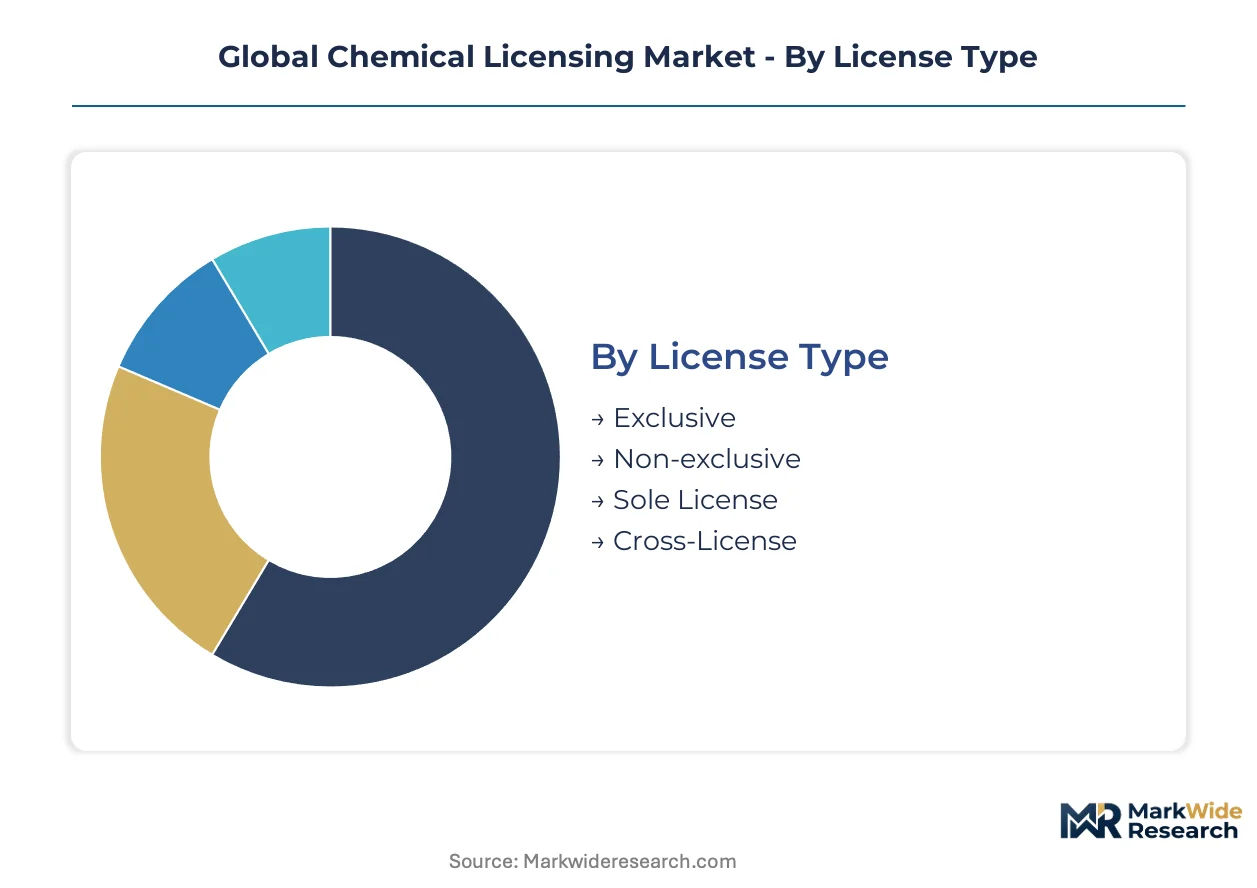
Segmentation in chemical licensing reveals how licensors structure value capture across technology maturity cycles and licensee risk appetites. License type and duration configurations directly shape capital recovery timelines for process developers while determining market access depth for manufacturing partners.
License Type:
Mature commodity chemistries favor non-exclusive arrangements that maximize licensor revenue through multiple deployments, while emerging bio-based and hydrogen-integrated processes command exclusive premiums for pioneering risk absorption.
- Exclusive:Grants sole manufacturing rights within defined territories or fields of use, typically reserved for breakthrough catalytic systems or pharmaceutical intermediates facing patent cliffs. European agrochemical producers pay substantial upfront fees for exclusivity on novel active ingredient synthesis routes under REACH pressure.
- Non-exclusive:Permits multiple licensees to operate identical process technologies simultaneously, dominating petrochemical derivatives where scale economics outweigh competitive differentiation. Chinese state-owned refiners prefer this structure for aromatics and ethylene crackers to accelerate capacity buildouts.
- Sole License:Restricts licensor from granting further rights while allowing licensee exclusivity, common in joint venture structures where capital partners demand protected market positions.
- Cross-License:Exchanges complementary process portfolios between technology holders, prevalent among catalyst suppliers seeking access to integrated reactor designs.
Non-exclusive arrangements retain volume leadership across installed base; exclusive licenses hold the steepest expansion curve as bio-based chemistry portfolios mature.
Industry Application:
Application segmentation tracks how regulatory stringency and margin profiles reshape licensing economics across chemical value chains.
- Pharmaceuticals:Patent cliff timing drives urgent manufacturing access negotiations, with EMA and FDA submission deadlines compressing license execution cycles for generic API producers.
- Agrochemicals:ECHA authorization requirements and residue tolerance protocols elevate process documentation burdens, favoring licensors with established regulatory submission track records.
- Specialty Chemicals:Polymer manufacturers seeking pyrolysis and chemical recycling technologies command expanded engineering scope as circular economy mandates tighten across EU member states.
- Fine Chemicals:High-purity specifications for electronics and coatings applications require licensors to certify impurity profiles and batch consistency protocols before technology transfer.
- Biochemicals:Fermentation and enzymatic routes face yield constraints at commercial scale, limiting licensee confidence in performance guarantees despite METI hydrogen roadmap incentives in Japan.
Specialty chemicals generate the densest licensing activity by project count; biochemicals are climbing fastest as carbon accounting embeds into corporate procurement criteria.
License Duration:
Duration structures align licensor revenue recognition with technology obsolescence risk and licensee capital recovery horizons.
- Short-term:One to three-year agreements suit pilot-scale demonstrations and process validation campaigns, common for plasma-assisted reforming technologies still maturing toward commercial reliability.
- Medium-term:Five to ten-year terms balance licensor annuity value against licensee flexibility, dominating specialty chemical formulations where feedstock substitution pressures accelerate process refresh cycles.
- Long-term:Fifteen to twenty-five year arrangements secure capital-intensive petrochemical units, with Saudi and Qatari integrated complexes favoring extended terms to match debt financing structures.
- Perpetual:Indefinite rights with ongoing royalty obligations, typically negotiated for foundational catalytic processes where patent expiration eliminates exclusivity leverage.
Medium-term structures dominate new awards by value; short-term agreements are expanding most quickly as modular and electrified process technologies require validation before scale commitment.
Licensing Model:
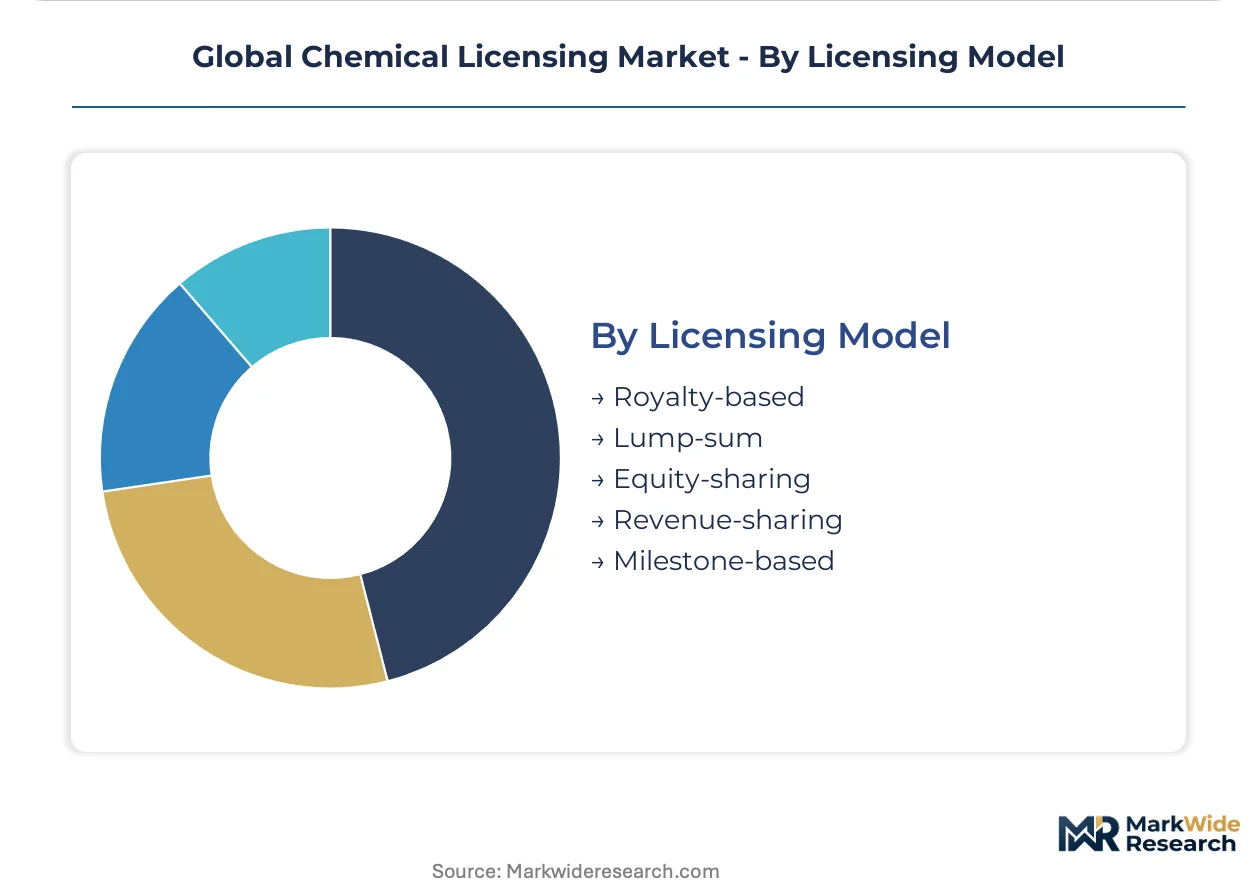
Revenue architecture determines how licensors participate in licensee operating performance versus extracting fixed returns.
- Royalty-based:Ties licensor compensation to production volume or sales value, dominating specialty chemicals where high-margin formulations justify ongoing participation without licensor capital deployment.
- Lump-sum:Single upfront payment for permanent technology access, preferred by Middle Eastern state operators seeking to eliminate future foreign exchange exposure and transfer pricing scrutiny.
- Equity-sharing:Licensors take direct ownership stakes in licensee entities, emerging for hydrogen-integrated ammonia and methanol projects where technology risk and commodity exposure intertwine.
- Revenue-sharing:Splits downstream product sales value, applied in pharmaceutical co-development where EMA approval uncertainty justifies risk distribution.
- Milestone-based:Triggers payments upon technical or commercial achievements, structuring bio-based process licenses where fermentation yield thresholds determine economic viability.
Royalty-based models retain the largest share of recurring licensor income; milestone structures are gaining share fastest as performance guarantees face heightened skepticism in renewable chemical routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel and its associated pipeline networks anchor North American chemical licensing activity, moving feedstock from Gulf Coast refineries to derivative manufacturers. Rotterdam's Europoort terminal serves as the primary entry point for licensed process technologies entering European markets. Singapore's Jurong Island petrochemical complex functions as the licensing hub for Southeast Asian capacity expansion.
United States
Shale gas economics drive demand for ethane-cracking process licenses along the Gulf Coast. EPA emissions standards tighten catalyst specifications for fluid catalytic cracking units. The Houston Ship Channel corridor concentrates licensing negotiations for polyethylene and polypropylene derivative technologies.
Germany
Chemical producers seek hydrogen-integrated process licenses to replace naphtha feedstocks in steam crackers. ECHA REACH authorization requirements extend documentation timelines for novel catalytic systems. The BASF Ludwigshafen Verbund site pilots electrified cracking furnaces under EU Green Deal carbon benchmarks.
China
State-owned refiners expand aromatics capacity through technology transfer agreements with international licensors. MEE-administered GB standards mandate emissions disclosure for licensed catalytic reforming processes. The Ningbo-Zhoushan petrochemical zone concentrates demand for integrated refinery-chemical complex designs.
Saudi Arabia
Integrated refinery-chemical complexes commission licensed technologies for derivative production from crude oil-to-chemicals configurations. SFDA chemical registration requirements align with broader Gulf regulatory harmonization efforts. The SATORP Jubail complex anchors regional demand for proprietary catalytic reforming portfolios.
India
Reliance Industries and Indian Oil accelerate cracker investments to address domestic petrochemical deficits. BIS certification requirements create compliance layers for imported process technologies. The Jamnagar refining complex drives licensing scope for aromatics and polymerization unit expansions.
Global Chemical Licensing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in catalyst and separations technology. The market structures around consolidated engineering-procurement-construction bundlers and fragmented catalyst formulation suppliers. Two archetypes dominate: integrated technology licensors offering full process-design-catalyst packages, and modular construction specialists compressing deployment timelines. Competitive moves center on portfolio diversification into bio-based and hydrogen-integrated process alternatives, plus geographic expansion through joint venture structures in Middle Eastern and Asian markets.
Within the integrated technology tier, UOP LLC and Lummus Technology LLC exemplify licensors with proprietary catalytic portfolios spanning reforming and cracking applications. Technip Energies N.V. occupies a distinct position through modular construction expertise, positioning bundled offerings for accelerated project execution timelines.
| Leading Market Players |
|---|
| UOP LLC |
| Lummus Technology LLC |
| Technip Energies N.V. |
| KBR, Inc. |
| Axens S.A.S. |
| Johnson Matthey PLC |
| Clariant AG |
| Exxon Mobil Corporation |
| BASF SE |
| Others |
Supply & Pricing Matrix
The Houston Ship Channel corridor concentrates proprietary catalytic reforming capacity, and this geographic clustering grants licensors downstream pricing leverage over ethylene cracker designs and aromatics unit configurations. Buyers in Middle Eastern integrated complexes face limited alternative sourcing for performance-guaranteed process bundles, compressing their negotiation position on lump-sum technology transfers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates technology licensing, with differentiation driven by catalyst life warranties and ECHA REACH pre-registration status. Cost compression in standard-tier steam-cracking licenses is intensifying because electrified furnace alternatives are displacing conventional fired-heater designs. State-owned refiners in China exhibit highest price sensitivity due to procurement autonomy mandates, while European agrochemical producers under patent cliff pressure show least sensitivity for exclusive synthesis routes.
Supply Chain Analysis
Extended payment terms from catalyst suppliers to licensors are stabilizing working capital across technology transfer cycles, though this financing layer concentrates counterparty exposure. Manufacturing of proprietary reforming and polymerization formulations centers on the United States, Germany, and Japan, with specialty zeolite and noble metal inputs drawing from South African and Russian mining operations. Single-source vulnerability in high-purity catalyst precursors threatens input cost volatility. Distribution runs through engineering-procurement-construction bundlers who integrate process design with modular construction deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical licensing is approaching a platform-economics inflection as digital twin packages and advanced process control systems create interoperability standards that favor licensors with integrated software-hardware-catalyst portfolios over component specialists.
For Market Incumbents: Entrench proprietary catalytic portfolios through backward integration into specialty zeolite manufacturing, neutralizing catalyst supply concentration risks that emerging modular construction specialists exploit. Lock in long-term technology transfer agreements with Saudi and Qatari integrated complexes before electrified cracking designs mature to commercial reliability, defending margin position against hydrogen-integrated process entrants.
For New Entrants and Emerging Players: Establish a beachhead in India's petrochemical deficit by offering fast-deployment ethylene technology bundles with modular construction expertise that Reliance Industries and Indian Oil demand for accelerated cracker commissioning. Target biochemical process licenses where fermentation yield performance guarantees remain unproven, capturing milestone-based revenue structures that incumbents avoid due to commercial scale-up skepticism.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors licensors with electrified furnace and plasma-assisted reforming pilot data, as these capabilities will determine competitive viability under EU Green Deal carbon benchmarks. The acquisition target archetype is modular construction specialists with hydrogen-integrated ammonia and methanol project experience. Watch Japan's METI hydrogen roadmap implementation pace as the signal for technology transfer demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Manufacturing | Captive supply of proprietary zeolite formulations neutralizes input cost volatility from concentrated suppliers. |
| Electrified Cracking Furnace Development | E-furnace engineering eliminates scope-one emissions, positioning licensors for EU carbon border adjustment compliance. |
| Joint Venture Structures in Middle East | Local partnerships with SATORP Jubail and SABIC affiliates accelerate technology transfer timelines and royalty capture. |
| Digital Twin Platform Integration | Advanced process control packages interfacing with existing DCS architectures create recurring software revenue streams. |
| Pyrolysis and Chemical Recycling Licensing | Circular economy mandates from EU member states expand engineering scope for polyethylene and polypropylene producers. |
Research Methodology
Desk research of SEC 10-K filings, customs and trade data from ACC and Cefic reports, and technology transfer agreement disclosures preceded structured interviews with plant managers at integrated refinery-chemical complexes, procurement leads at downstream polymer manufacturers, EPC contractors executing modular deployments, and technical R&D directors at catalyst formulation suppliers. Bottom-up project pipeline analysis triangulated against top-down capacity expansion announcements across the analysis window.
Assumptions held fixed include EU Green Deal carbon benchmark implementation trajectories and China's GB standards enforcement intensity, while feedstock substitution rates and hydrogen infrastructure buildout pace were varied across scenarios. Segmentation modeling incorporated license type, industry application, duration structure, and licensing model dimensions alongside regional production hub clustering. CAGRs were derived from installed base growth rates and average revenue per license configurations, with inputs from electrification technology readiness levels and REACH authorization timeline probabilities.
Stress conditions across crude oil-to-chemicals configuration economics, fermentation yield thresholds, and carbon border adjustment documentation burdens were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology commercialization timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Forchlorfenuron Market